
 Portable Infrared Digital Thermometer Market | 2026-2036
Portable Infrared Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Infrared Digital Thermometer Market Insights
Hospital procurement is consolidating across integrated delivery networks in the United States, concentrating buying power among fewer procurement officers who demand validated accuracy documentation. Fluke leverages its industrial metrology heritage to compete for clinical contracts requiring traceable calibration chains. Braun GmbH anchors European home-care channels with pediatric-focused forehead designs that emphasize ease-of-use over clinical feature depth. Omega Engineering specializes in high-temperature surface variants that serve industrial maintenance crews alongside medical applications.
A portable infrared digital thermometer measures thermal radiation emitted from a target surface or cavity, converting detected infrared energy into temperature readings via thermopile sensors and digital signal processing algorithms with typical response times under one second. Its primary purpose spans fever screening in clinical settings, process monitoring in manufacturing, and food safety verification in commercial kitchens. Forehead thermometers dominate home-care and public-screening volumes due to non-invasive operation, while handheld thermometers capture the deepest margin pools in industrial maintenance contracts where calibration certificates command pricing premiums. Smart thermometers integrating Bluetooth connectivity and app-based health tracking represent the fastest-growing technology segment as consumers and telehealth platforms seek continuous data streams.
FDA 510(k) premarket notification requirements enforce clinical accuracy standards within the United States, while the EU Medical Device Regulation mandates notified-body conformity assessments for infrared thermometers sold in Europe. China's NMPA oversees domestic registration through GB standard compliance testing that increasingly favors local manufacturers. Stakeholders must monitor evolving cybersecurity requirements for connected thermometer platforms as health-data regulations expand beyond traditional device-safety frameworks.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor margins while elevating clinical validation requirements. Buyers now demand traceable calibration chains and documented accuracy performance that only metrology-grade suppliers can satisfy.
Growth Catalysts
- FDA 510(k) pathway tightening:Stricter clinical accuracy thresholds for non-contact devices are filtering out low-precision competitors and rewarding manufacturers with established metrology capabilities.
- Telehealth platform integration:Bluetooth-enabled smart thermometers are creating continuous data streams that remote monitoring services require for chronic condition management.
- China's tier-one hospital chains:Domestic NMPA-certified manufacturers are displacing imports through localized supply chains and faster regulatory turnaround.
Market Restraints
- Thermopile sensor supply concentration:German and Japanese component specialists control high-precision infrared detector output, exposing assemblers to allocation risk during demand spikes.
- Contact thermometer substitution:Tympanic and oral probe devices retain preference in pediatric acute care where absolute precision outweighs speed.
- EU MDR conformity costs:Notified-body assessments for infrared thermometers now require extended clinical validation timelines that delay European market entry by 12-18 months.
Strategic Opportunities
- Industrial-food safety crossover:Handheld surface thermometers with dual medical-commercial certification are capturing maintenance contracts in pharmaceutical manufacturing facilities.
- Home-care channel digitization:App-connected forehead units with fever-history tracking are penetrating direct-to-consumer subscription models previously dominated by fitness wearables.
- GB standard harmonization:China's alignment of domestic infrared thermometer testing with IEC thermal-radiation protocols is simplifying export certification for compliant manufacturers.
Industry Challenges
- Calibration technician scarcity:Blackbody reference source operation and emissivity correction protocols require specialized training that clinical engineering departments struggle to staff.
- Legacy health-record integration:Bluetooth thermometer APIs face interoperability friction with hospital EHR systems that prioritize wired device protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Infrared Digital Thermometer Market |
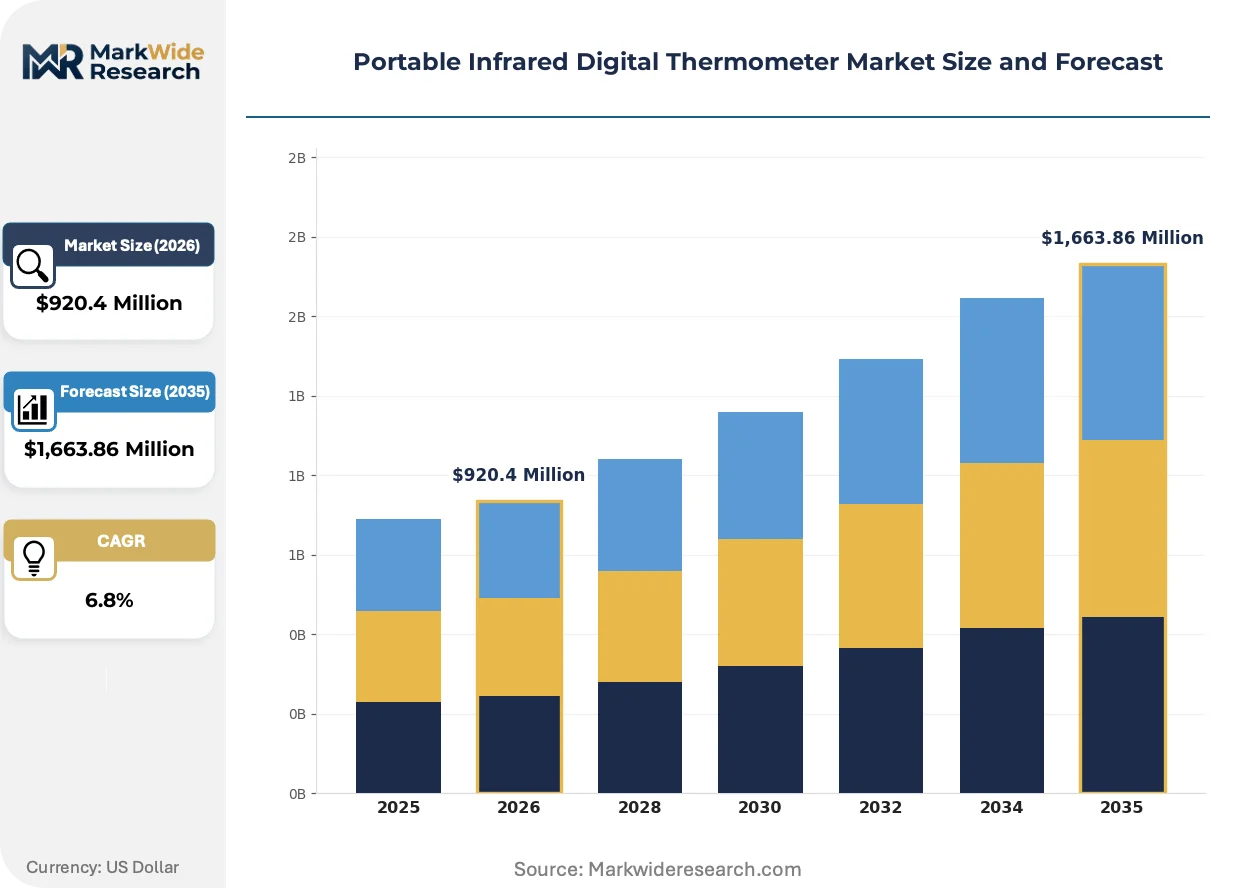
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,663.86 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forehead Thermometers, Ear Thermometers, Handheld Thermometers, Surface Thermometers Application: Home Care, Hospitals, Clinics, Laboratories End User: Consumers, Healthcare Professionals, First Responders, Industrial Workers Technology: Non-Contact, Contact, Smart Thermometers, Analog Thermometers |
| Companies Covered | Omron, Exergen, Fluke, Omega Engineering, Braun GmbH, FLIR, Microlife, ThermoWorks, Testo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Infrared Digital Thermometer Market Trends and Innovations
Sensor miniaturization and edge-computing integration are redefining performance benchmarks across clinical and consumer segments. Manufacturers are racing to embed artificial intelligence for emissivity compensation while regulatory bodies scramble to certify algorithm-driven accuracy claims.
Multi-wavelength infrared arrays are overtaking single-detector thermopile designs in premium clinical units. These sensors sample multiple spectral bands to compensate for skin moisture, ambient temperature drift, and measurement angle variation. Emergency departments in Singapore and Seoul are deploying these units for mass fever screening where throughput speed competes with diagnostic precision. The technology is overtaking conventional forehead thermometers in settings where false-negative rates carry public-health consequences.
EU Medical Device Regulation cybersecurity annexes are mandating encrypted data transmission for connected thermometers. Manufacturers must now submit technical documentation covering threat modeling and software lifecycle processes alongside traditional safety dossiers. Pediatric home-care brands selling into Germany and France are restructuring firmware architectures to satisfy these requirements ahead of notified-body audits.
Integrated health networks are consolidating thermometer procurement through centralized category managers who negotiate enterprise-wide calibration service contracts. This model displaces the previous pattern of individual department purchases from distributor catalogs. The shift is most visible across United States hospital systems where value-analysis committees now mandate five-year total-cost-of-ownership comparisons including traceable recertification schedules.
Portable Infrared Digital Thermometer Market Segmentation
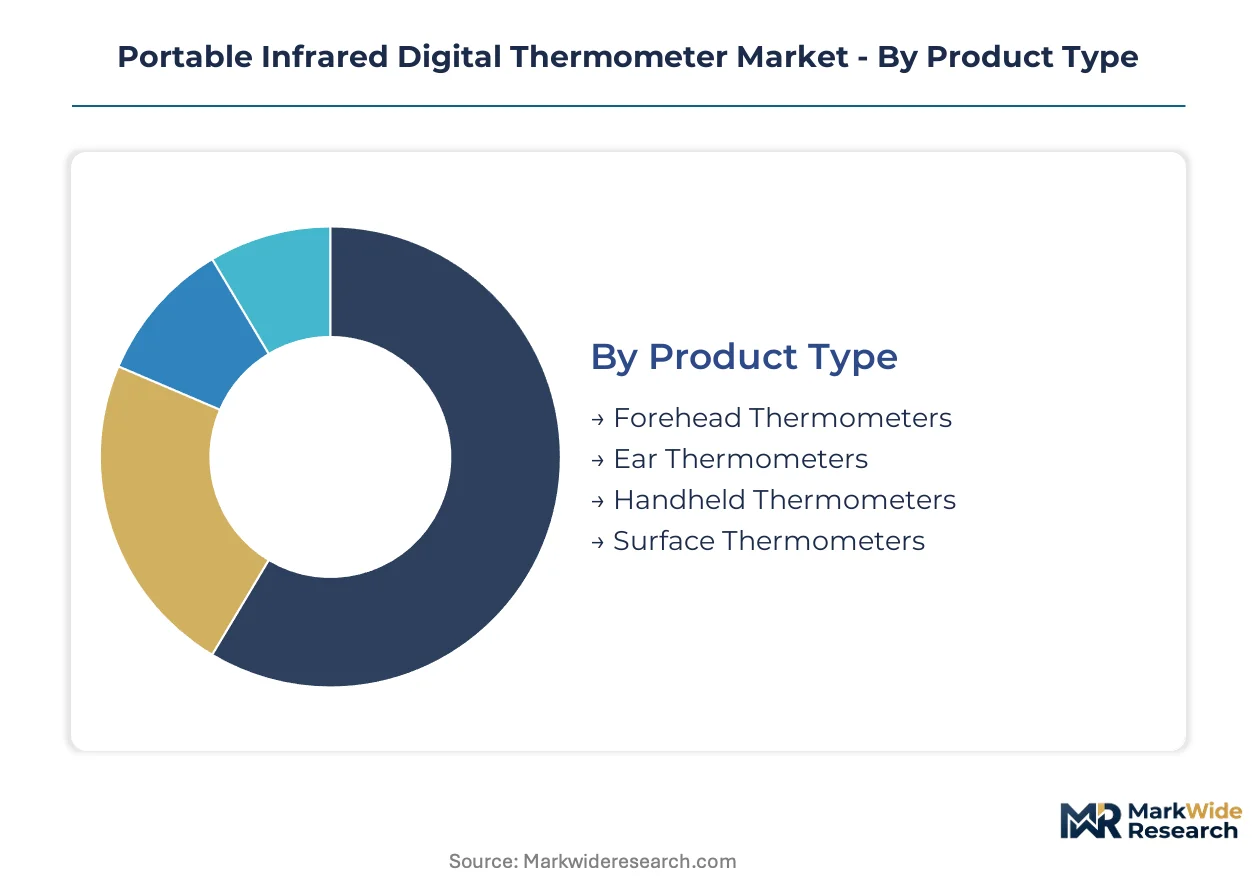
Portable infrared digital thermometer purchasing decisions split across clinical precision requirements, consumer convenience preferences, and industrial durability standards. Buyers prioritize response speed, calibration traceability, or connectivity features depending on end-use environment. Understanding these segment boundaries reveals where margin pools concentrate and which technology investments yield competitive separation.
Product Type:
Hospital procurement officers and home-care retailers evaluate response speed, ergonomic design, and calibration documentation when selecting form factors.
- Forehead Thermometers:Non-invasive temporal artery scanning dominates pediatric and public-screening volumes where speed outweighs absolute precision. Demand concentrates in China's tier-one hospital chains and North American school districts deploying mass fever-screening protocols.
- Handheld Thermometers:Pistol-grip industrial variants with adjustable emissivity settings capture pharmaceutical manufacturing maintenance contracts. FDA 510(k) clearance and ISO 17025 calibration certificates command pricing premiums in clinical engineering departments.
- Ear Thermometers:Tympanic infrared units with disposable probe covers retain preference in acute pediatric settings where core body temperature accuracy is mandatory.
- Surface Thermometers:Fixed-focus industrial variants serve food safety inspectors and HVAC technicians requiring distant target measurement without surface contact.
Forehead Thermometers lead on scale; Handheld Thermometers lead on momentum.
Application:
Regulatory intensity and reimbursement pathways determine where manufacturers concentrate clinical validation investments.
- Hospitals:Integrated delivery networks consolidate purchasing through value-analysis committees demanding five-year total-cost-of-ownership documentation. EU MDR conformity assessments and FDA 510(k) clearances filter supplier pools to metrology-grade manufacturers.
- Home Care:Direct-to-consumer channels prioritize one-button operation, fever-history memory, and pediatric comfort features. Bluetooth-enabled smart units with app connectivity are expanding most quickly in subscription-based telehealth platforms.
- Clinics:Outpatient facilities balance clinical accuracy requirements against capital budget constraints, often selecting mid-tier forehead units with basic calibration certificates.
- Laboratories:Research and quality-control applications demand blackbody-referenced accuracy traceable to national metrology institutes.
Hospitals anchor revenue concentration; Home Care exhibits the steepest expansion trajectory.
End User:
Training requirements and data integration needs separate professional-grade from consumer-grade purchasing criteria.
- Healthcare Professionals:Physicians and nurses require devices with documented accuracy performance, infection-control protocols, and EHR interoperability. Procurement runs through hospital supply chain departments with mandated calibration service contracts.
- Consumers:Parents and caregivers prioritize intuitive interfaces, silent operation, and fever-alert thresholds. Smart thermometer adoption is climbing fastest among households with chronic condition management needs.
- First Responders:Emergency medical technicians demand ruggedized units with rapid response times for field triage in variable ambient conditions.
- Industrial Workers:Maintenance crews in pharmaceutical and food processing facilities require dual medical-commercial certification for crossover applications.
Healthcare Professionals dominate contract value; Consumers drive volume expansion.
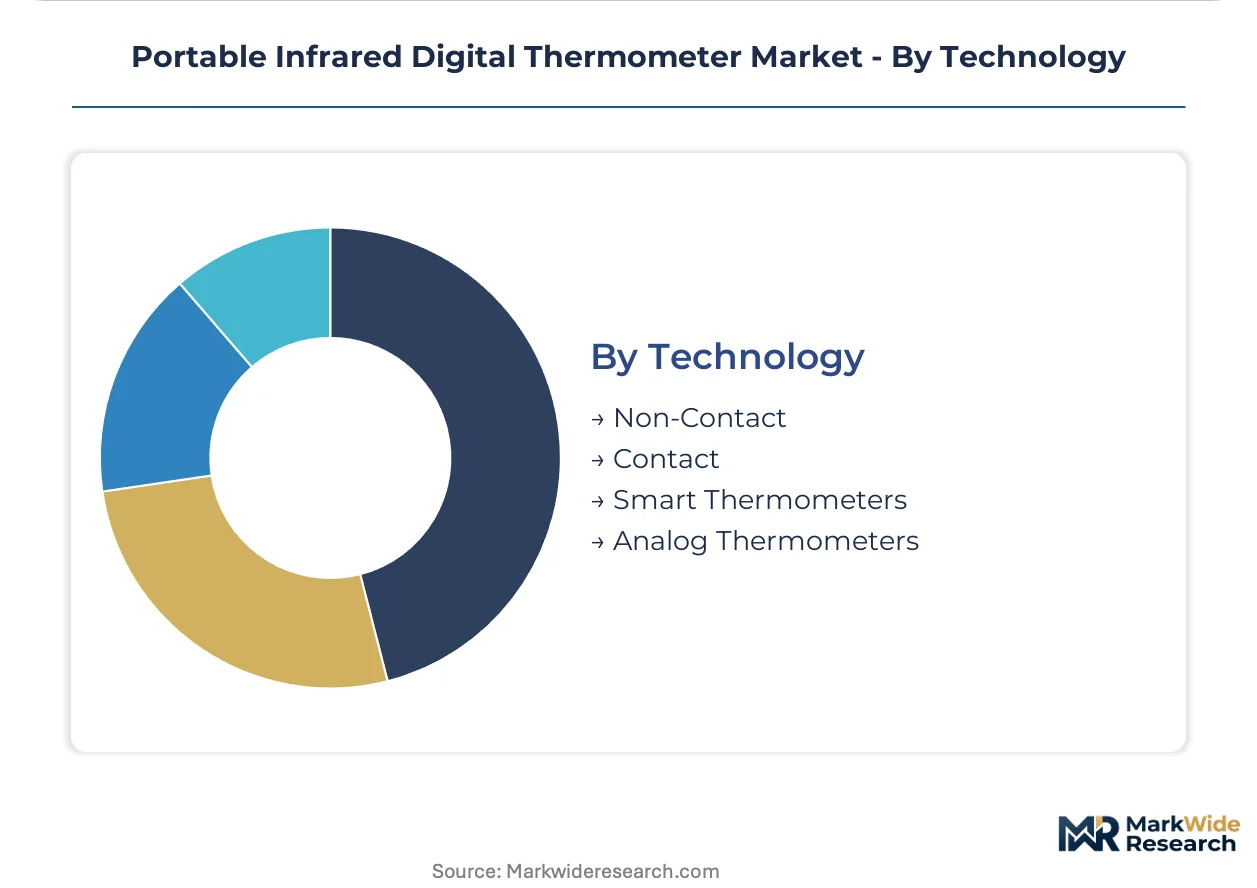
Technology:
Sensor architecture and connectivity capabilities define performance tiers and regulatory classification pathways.
- Smart Thermometers:Bluetooth-enabled units with edge-computing algorithms for emissivity compensation are gaining share fastest in telehealth and remote patient monitoring. EU MDR cybersecurity annexes now mandate encrypted transmission protocols.
- Non-Contact:Thermopile-based infrared detection with digital signal processing underpins forehead and surface variants. German and Japanese component specialists control high-precision detector supply.
- Contact:Tympanic and oral probe designs retain installed base in pediatric acute care where regulatory bodies accept established accuracy protocols.
- Analog Thermometers:Mercury-free liquid-crystal and bimetallic designs persist in cost-sensitive markets and backup clinical scenarios.
Non-Contact commands installed base; Smart Thermometers lead technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one hospital chains source infrared thermometers from domestic NMPA-certified manufacturers at faster regulatory turnaround than German hospital systems navigating EU MDR notified-body queues. Procurement velocity and certification friction now separate regional growth trajectories more than raw demand scale.
United States
Integrated delivery networks concentrate thermometer purchasing through value-analysis committees demanding five-year total-cost-of-ownership documentation. FDA 510(k) clearance requirements enforce clinical accuracy thresholds that filter supplier pools to metrology-grade manufacturers. Greater Boston's medical device cluster houses calibration laboratories serving hospital chains across the Northeast Corridor.
Germany
Industrial metrology heritage positions German manufacturers for crossover contracts spanning medical and pharmaceutical manufacturing applications. EU MDR conformity assessments now require extended clinical validation timelines that delay market entry by 12-18 months. Baden-Württemberg's precision engineering corridor supplies blackbody reference sources to calibration service providers.
China
Domestic NMPA-certified manufacturers displace imports through localized supply chains and faster regulatory turnaround in tier-one hospital chains. GB standard harmonization with IEC thermal-radiation protocols simplifies export certification for compliant manufacturers. Yangtze River Delta production clusters feed both domestic hospital procurement and Southeast Asian export channels.
Japan
High-precision thermopile sensor production concentrates among component specialists serving global thermometer assemblers. METI oversight of medical device quality management systems maintains stringent manufacturing standards. Kansai industrial corridors host infrared detector fabrication facilities supplying German and US device manufacturers.
Singapore
Multi-wavelength infrared arrays deploy in emergency departments for mass fever screening where throughput speed competes with diagnostic precision. Health Authority Singapore regulates clinical thermometer performance through post-market surveillance programs. Biomedical manufacturing hubs in Tuas integrate sensor assembly with regional distribution to Southeast Asian hospital networks.
Portable Infrared Digital Thermometer Market Competitive Landscape
German and Japanese component specialists anchor one tier; US and Chinese device assemblers hold another. The vendor base splits between metrology-grade suppliers serving hospital procurement and consumer-focused brands penetrating home-care channels. Three archetypes dominate: industrial-metrology crossover players, pediatric home-care specialists, and high-volume domestic manufacturers. Competitive moves concentrate on calibration service bundling and telehealth platform partnerships.
Within the industrial-metrology tier, Fluke and Omega Engineering exemplify crossover positioning between clinical engineering departments and pharmaceutical manufacturing maintenance contracts. Braun GmbH occupies a distinct niche in European home-care channels. Chinese manufacturers represented by Omron's regional supply chain presence anchor the high-volume domestic procurement segment serving tier-one hospital chains.
| Leading Market Players |
|---|
| Omron |
| Exergen |
| Fluke |
| Omega Engineering |
| Braun GmbH |
| FLIR |
| Microlife |
| ThermoWorks |
| Testo |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up metrology specialists now control calibration service networks across United States hospital systems, tightening pricing discipline through bundled recertification contracts while squeezing component assemblers on volume commitments. This ownership concentration feeds directly into procurement leverage that tier-one health networks exploit to compress margins on non-contact thermometer suppliers lacking traceable accuracy documentation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta production clusters are reshaping price floors for NMPA-certified forehead units, forcing legacy importers to reposition toward ISO 17025-calibrated handheld variants. Three-tier pricing structure across clinical-grade, commercial-certified, and consumer-basic levels separates FDA 510(k)-cleared hospital contracts from school-district bulk orders. Pricing pressure stems from procurement consolidation across integrated delivery networks demanding five-year total-cost-of-ownership guarantees. Home-care retailers exhibit highest price sensitivity; pharmaceutical manufacturing maintenance crews accept premiums for dual medical-commercial certification.
Supply Chain Analysis
Freight cost volatility from German and Japanese thermopile sensor specialists to device assemblers in China and the United States is amplifying working capital requirements for inventory buffers. Component supply concentrates in Japan's Kansai corridor for high-precision infrared detectors, Germany's Baden-Württemberg region for blackbody reference sources, and China's Yangtze Delta for final assembly. Thermopile sensor allocation risk during demand spikes rests on two dominant component houses. Tariff exposure on precision optics shipped from Japan to US device manufacturers threatens margin stability. Distribution runs through hospital GPO contracts, industrial maintenance distributors, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as hospital value-analysis committees mandate documented accuracy performance over lowest-unit-cost sourcing. This late-cycle quality story rewards manufacturers with established metrology capabilities and traceable calibration infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into thermopile sensor supply relationships, securing allocation priority during demand spikes. Deepen hospital system partnerships by bundling five-year recertification service contracts that lock out competitors lacking ISO 17025 laboratory networks. Contact thermometer substitution in pediatric acute care and EU MDR conformity cost escalation represent persistent threats requiring certification investment in notified-body relationships. For New Entrants and Emerging Players: Telehealth platform partnerships offer the most penetrable channel for Bluetooth-enabled smart thermometers, bypassing entrenched hospital supply chain relationships entirely. Target direct-to-consumer subscription models for chronic condition management households, where app-connected fever tracking displaces fitness wearables. Pursue white-label manufacturing for domestic Chinese hospital chains seeking faster NMPA turnaround than import competitors can deliver. For Investors and Strategic Acquirers: Industrial-metrology crossover specialists are the most active acquirer in this space, seeking clinical engineering capabilities to complement pharmaceutical manufacturing maintenance contracts. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale alone. Watch for GB standard harmonization completion as signal that Chinese manufacturers will accelerate export certification into Southeast Asian hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Investment | Clearance timelines filter supplier pools to metrology-grade manufacturers with traceable calibration chains. |
| CE Marking Under EU MDR | Notified-body assessments now require cybersecurity documentation that extends validation timelines for connected devices. |
| Hospital System Partnership | Integrated delivery networks consolidate procurement through value-analysis committees demanding total-cost-of-ownership guarantees. |
| Software Companion Development | Bluetooth-enabled fever-history tracking penetrates telehealth platforms requiring continuous data streams for remote monitoring. |
| Reimbursement Strategy | Home-care channel digitization depends on alignment with payer remote patient monitoring coverage policies. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Singapore, with primary inputs from each regional cluster combining interviews with hospital procurement officers, biomedical engineering directors, GPO contracts managers, and telehealth platform operators alongside secondary validation. FDA 510(k) filings, EU MDR notified-body databases, NMPA registration records, and hospital procurement contract repositories provided regulatory and commercial context. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across product type, application, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating regulatory approval timelines, procurement cycle durations, and technology substitution patterns. Thermopile sensor supply constraints and EU MDR conformity assessment bottlenecks represented key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory reciprocity agreements and EU cybersecurity annex enforcement intensity. Model outputs reflect assumptions regarding hospital procurement consolidation velocity and telehealth reimbursement policy stability. A model refresh is warranted upon material change in FDA 510(k) clinical accuracy threshold revisions or thermopile sensor supply allocation disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Electron Microscope Sample Preparation Market