
 Digital Multichannel Analyzer Market | 2026-2036
Digital Multichannel Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Multichannel Analyzer Market Insights
The gap between premium multi-channel systems and entry-level portable units is realigning competitive priorities across the supply base. ORTEC (AMETEK Inc.) leverages its nuclear instrumentation heritage to dominate high-resolution spectroscopy installations at government and academic research sites. CAEN SpA competes through dense channel integration and modular firmware architectures that appeal to physics laboratories running multi-detector arrays. Mirion Technologies anchors the radiation monitoring segment with ruggedized field-deployable analyzers serving environmental and defense end users.
A digital multichannel analyzer digitizes, processes, and stores pulse-height spectra from radiation detectors such as HPGe or scintillation crystals, typically achieving 16-bit amplitude resolution with throughput exceeding 100,000 counts per second per channel. Its core purpose is to discriminate gamma-ray or particle energies for quantitative radionuclide identification across nuclear medicine, environmental surveillance, and materials science workflows. Multi-channel configurations command the largest installed base in pharmaceutical quality control and nuclear research, while portable units represent the fastest-expanding category as point-of-need environmental screening protocols proliferate. Chemiluminescence and fluorescence detection modalities concentrate margin pools in clinical diagnostics, where contract laboratories and hospital systems prioritize throughput and regulatory compliance over capital cost minimization.
FDA 21 CFR Part 11, EU MDR CE marking requirements, and ISO 13485 quality management standards collectively elevate validation documentation and software traceability burdens for manufacturers serving regulated clinical and pharmaceutical end users. EPA radiological monitoring protocols and NRC license conditions further shape product specifications for environmental and nuclear power sector deployments. Stakeholders must weigh channel scalability against total cost of ownership as laboratory informatics integration and remote diagnostic capabilities become decisive procurement criteria.
Market Dynamics
FDA 21 CFR Part 11 electronic records mandates and EU MDR device classification rules are compressing validation timelines for analytical instrument vendors, forcing simultaneous software traceability upgrades and hardware recertification cycles across nuclear medicine and pharmaceutical quality control deployments.
Growth Catalysts
- German Research Cluster Density:Pharmaceutical quality control laboratories in Baden-Württemberg and Bavaria maintain dense procurement pipelines for high-channel-count systems, anchoring European demand concentration.
- NRC License Condition Expansion:Environmental surveillance protocols mandated by US Nuclear Regulatory Commission operating licenses are proliferating point-of-need field screening requirements.
- HPGe Detector Throughput Advances:16-bit amplitude resolution architectures now sustain count rates exceeding 100,000 per second, enabling real-time gamma spectroscopy in clinical radionuclide identification workflows.
Market Restraints
- High-Purity Germanium Supply Concentration:Cryogenic detector manufacturing depends on a limited supplier base for ultra-pure germanium crystal growth, creating single-source vulnerability.
- ISO 13485 Documentation Burden:Quality management system certification for clinical deployments demands 18-24 month validation cycles that extend product launch timelines.
- Scintillation Crystal Cost Volatility:Thallium-doped sodium iodide and lutetium-based crystal feedstock prices fluctuate with rare earth element mining output, compressing margin predictability.
Strategic Opportunities
- India Nuclear Medicine Expansion:CDSCO regulatory pathway streamlining and hospital system capital investment in gamma camera infrastructure are opening procurement channels for mid-channel systems.
- AI-Assisted Spectrum Analysis:Machine learning algorithms for automated radionuclide identification are converging with embedded firmware to reduce operator training requirements.
- EU Green Deal Radiological Monitoring:Environmental baseline survey mandates for decommissioned industrial sites are creating demand for portable battery-operated analyzers with wireless data transmission.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Liquid nitrogen cooling system design and maintenance expertise resides in a shrinking cohort of nuclear instrumentation specialists.
- Legacy MCA Interface Integration:Hospital information systems and laboratory information management systems require custom middleware development for multi-vendor data harmonization.
- CE Marking Technical Documentation:EU MDR Annex I general safety and performance requirements demand expanded clinical evidence portfolios that strain smaller manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Multichannel Analyzer Market |
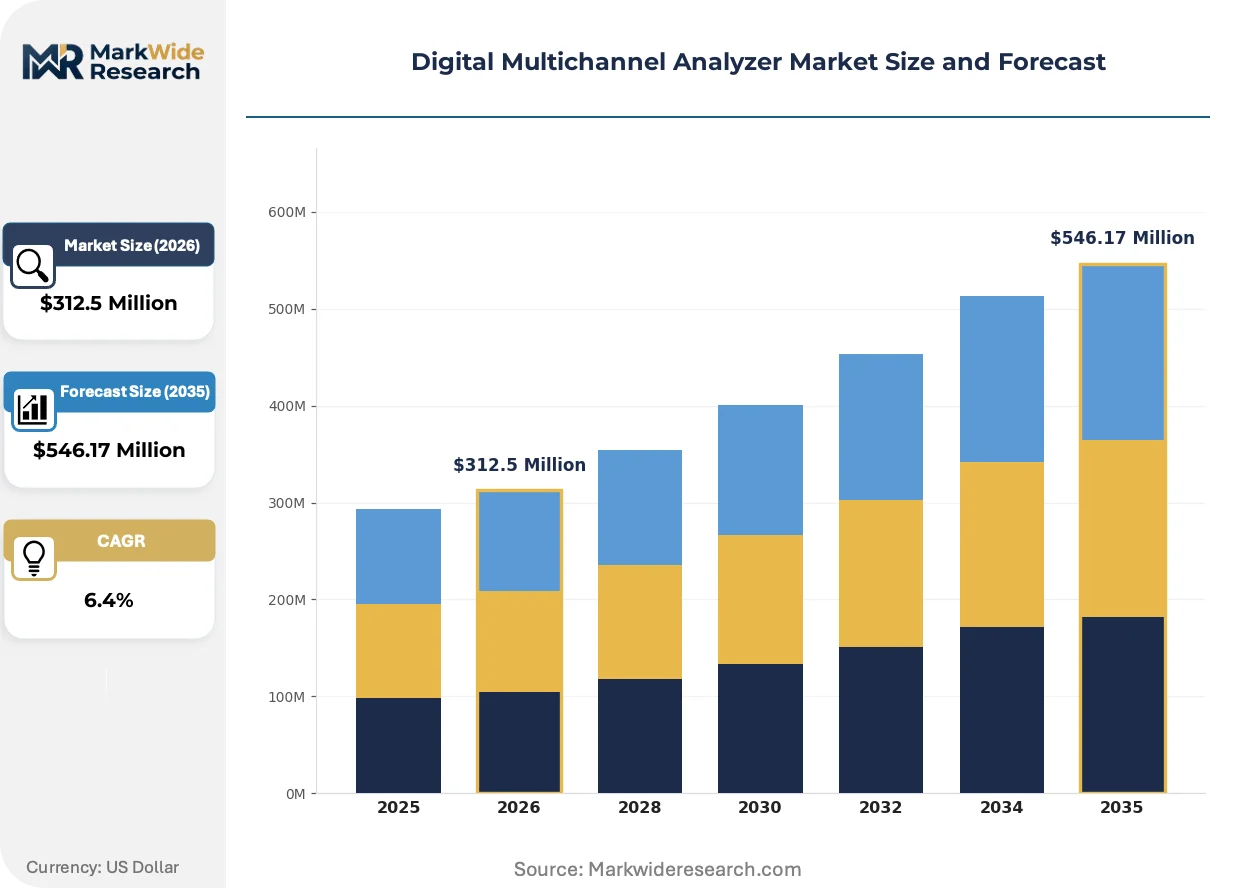
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Channel, Dual Channel, Multi-Channel, Portable Technology: Chemiluminescence, Fluorescence, Immunofluorescence, Spectrophotometry Application: Clinical Diagnostics, Environmental Monitoring, Food Testing, Research Laboratories End User: Hospitals, Academics, Pharmaceutical Companies, Contract Laboratories |
| Companies Covered | ORTEC (AMETEK Inc.), CAEN SpA, Mirion Technologies, Hitachi High-Tech Corporation, FAST ComTec, Berkeley Nucleonics Corporation, Berthold Technologies, LabLogic Systems, BrightSpec NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Multichannel Analyzer Market Trends and Innovations
Digital signal processing architectures are displacing analog pulse-height analysis, while regulatory digitization mandates and buyer consolidation are compressing vendor differentiation strategies across the supply base.
Field-programmable gate array-based digital pulse processing is converging with cloud-connected firmware update architectures. Government research laboratories in the United States and Germany are piloting these systems for remote diagnostic access. This convergence is collapsing the traditional boundary between hardware-defined and software-defined spectroscopy platforms, enabling post-installation feature expansion without physical retrofit.
EU MDR CE marking requirements and FDA 21 CFR Part 11 validation protocols are tightening in parallel, creating overlapping compliance burdens for multinational instrument vendors. Manufacturers serving both jurisdictions must maintain dual electronic records systems and audit trail architectures. Pharmaceutical quality control operations in Switzerland and the Netherlands are prioritizing vendors with pre-validated software packages to compress procurement cycles.
Hospital systems and contract research organizations are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party calibration and maintenance providers. Original equipment manufacturers face margin compression as independent service organizations capture recurring revenue streams. This disintermediation is most advanced in the United Kingdom and France, where national health service procurement frameworks explicitly separate service provision from device acquisition.
Digital Multichannel Analyzer Market Segmentation
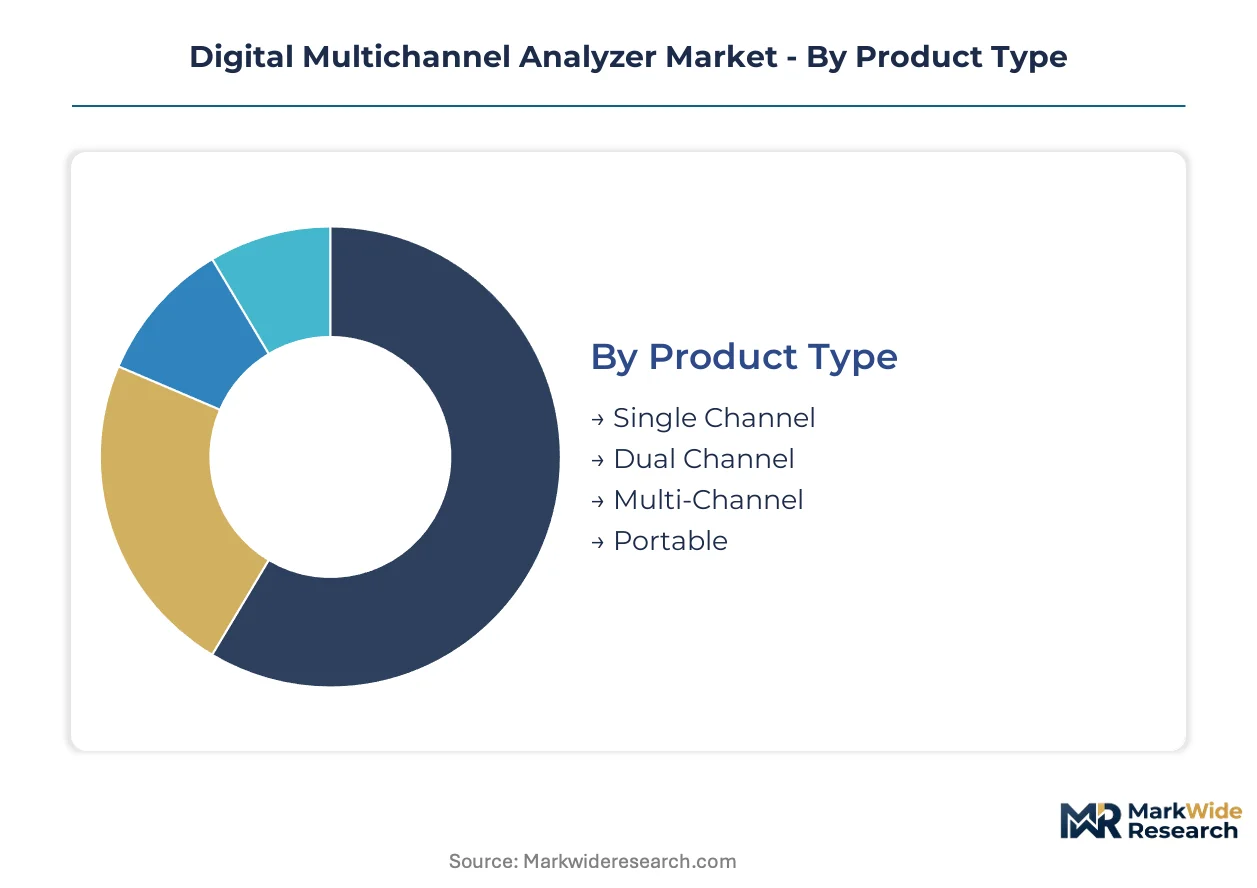
Digital multichannel analyzer procurement diverges sharply across deployment contexts, with channel count and portability requirements driving fundamentally different hardware specifications. Segmentation clarity enables vendors to align firmware architectures with precise validation burdens and throughput demands.
Product Type:
Supply concentration in detector manufacturing tilts procurement economics toward modular architectures that accommodate future channel expansion without full system replacement.
- Multi-Channel:Configurations with 16 to 4096 channels dominate pharmaceutical quality control and nuclear research installations. German laboratories in Baden-Württemberg sustain dense demand for high-channel-count systems with 16-bit amplitude resolution exceeding 100,000 counts per second.
- Portable:Battery-operated units with wireless data transmission are gaining share fastest in environmental surveillance protocols mandated by US Nuclear Regulatory Commission license conditions. Field-deployable designs sacrifice peak throughput for operational mobility.
- Single Channel:Entry-level systems serve teaching laboratories and routine screening with minimal capital outlay.
- Dual Channel:Intermediate configurations balance cost constraints against modest throughput requirements in contract testing operations.
Today's leader: Multi-Channel. Tomorrow's challenger: Portable.
Technology:
Cost tier stratification separates premium detection modalities from commodity analytical methods, with margin pools concentrating where regulatory validation requirements are most stringent.
- Chemiluminescence:High-sensitivity detection chemistry commands premium positioning in clinical diagnostics where FDA 21 CFR Part 11 electronic records compliance is mandatory. Hospital systems prioritize throughput and traceability over capital minimization.
- Fluorescence:Versatile excitation-emission architectures span research and quality control applications with moderate sensitivity requirements.
- Immunofluorescence:Antibody-based specificity serves targeted biomarker quantification in pharmaceutical development workflows.
- Spectrophotometry:Established absorbance measurement retains cost-sensitive applications where regulatory burden remains lighter.
Chemiluminescence holds the margin crown. Spectrophotometry faces steady displacement by digital pulse processing advances.
Application:
Volume concentration in radionuclide identification workflows creates procurement patterns that favor vendors with pre-validated software packages and established service networks.
- Clinical Diagnostics:Gamma spectroscopy for radiopharmaceutical purity verification drives demand in nuclear medicine departments. EU MDR device classification rules and FDA validation protocols compress vendor selection to established suppliers with quality management system certification.
- Environmental Monitoring:EPA radiological protocols and decommissioning site surveys proliferate point-of-need screening requirements. EU Green Deal baseline survey mandates for industrial sites create portable analyzer demand.
- Research Laboratories:Multi-detector arrays in physics facilities require modular firmware architectures with dense channel integration.
- Food Testing:Contamination screening applications prioritize cost efficiency over spectral resolution.
Clinical Diagnostics anchors current revenue. Environmental Monitoring represents the steepest expansion trajectory.
End User:
Customer type determines service contract structures, with hospital systems and contract research organizations increasingly unbundling maintenance from capital acquisition.
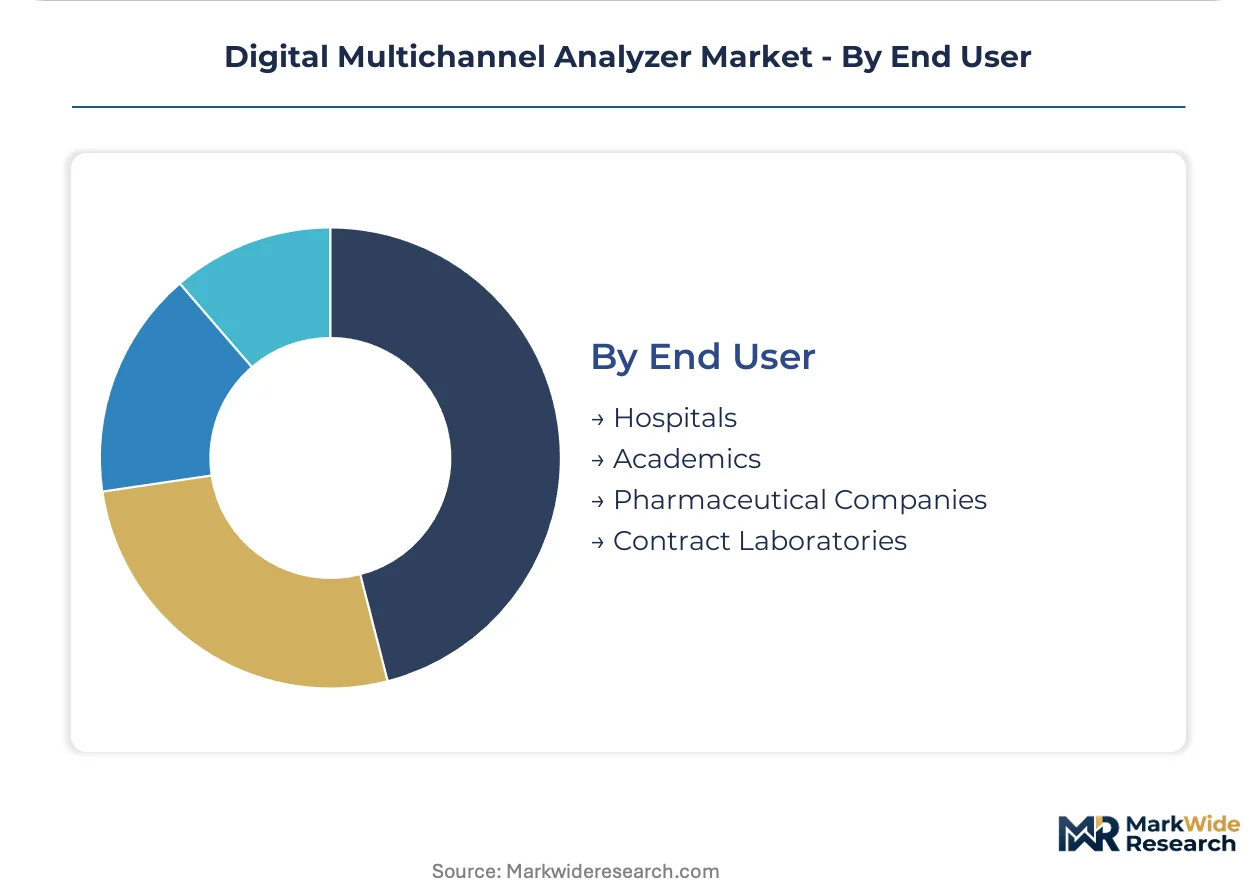
- Hospitals:Nuclear medicine departments in expanding health systems drive gamma camera infrastructure procurement. ISO 13485 documentation requirements extend validation cycles to 18-24 months.
- Pharmaceutical Companies:Quality control operations in Switzerland and the Netherlands prioritize vendors with pre-validated software to compress procurement timelines.
- Contract Laboratories:Third-party calibration and maintenance providers capture recurring revenue as independent service organizations disintermediate original equipment manufacturers.
- Academics:Government research laboratories in the United States and Germany pilot cloud-connected firmware architectures for remote diagnostic access.
Hospitals dominate installed base value. Contract Laboratories are restructuring vendor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic engineering specialists cluster around legacy nuclear research centers, anchoring regional demand for precision radiation instrumentation. Germany's Baden-Württemberg and Bavaria host dense concentrations of pharmaceutical quality control laboratories. The United States maintains leadership in government-funded research installations requiring high-channel-count spectroscopy systems.
United States
NRC license conditions for nuclear power operators and EPA radiological monitoring protocols drive environmental surveillance procurement. FDA 21 CFR Part 11 electronic records mandates compress validation timelines for clinical deployments. National laboratories in Tennessee and New Mexico pilot cloud-connected firmware architectures for remote diagnostic access.
Germany
Pharmaceutical quality control operations in Baden-Württemberg sustain dense demand for multi-channel systems with 16-bit amplitude resolution. EU MDR CE marking requirements and Annex I technical documentation standards elevate compliance burdens for analytical instrument vendors. Research facilities in Bavaria anchor European demand for modular firmware architectures serving multi-detector arrays.
India
Hospital system capital investment in gamma camera infrastructure and CDSCO regulatory pathway streamlining open procurement channels for mid-channel systems. The country's national pharmaceutical regulator advances device classification harmonization with international standards. Nuclear medicine departments in Maharashtra and Karnataka expand radionuclide identification capabilities.
Japan
PMDA quality management system requirements and METI industrial technology roadmaps shape domestic procurement specifications. The country's national standards body maintains stringent certification protocols for analytical instruments deployed in clinical environments. Research consortia in the Kanto region drive demand for high-throughput spectroscopy platforms.
Switzerland
Swissmedic device registration requirements and pharmaceutical quality control operations prioritize vendors with pre-validated software packages. The country's precision manufacturing heritage supports specialized cryogenic detector component fabrication. Basel and Zurich anchor demand concentration for regulatory-compliant analytical instrumentation.
Digital Multichannel Analyzer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the supply base, with cryogenic detector manufacturing concentrating among specialized foundries while firmware development fragments across modular architecture specialists. The market structure tilts toward consolidated high-resolution spectroscopy installations at government and academic sites, with portable environmental screening segments attracting diversified entrants. Three archetypes dominate: nuclear instrumentation heritage players, modular firmware specialists, and ruggedized field-deployment engineers. Competitive moves center on simultaneous software traceability upgrades for regulatory recertification and cloud-connected remote diagnostic capability expansion.
Within the nuclear instrumentation heritage tier, ORTEC (AMETEK Inc.) and CAEN SpA occupy positions reflecting distinct geographic and architectural specializations. ORTEC exemplifies the capital-intensive precision spectroscopy anchor serving government research installations with cryogenic engineering depth. CAEN SpA represents the modular firmware architecture approach that appeals to physics laboratories requiring dense channel integration and scalable detector arrays. Mirion Technologies sits within the ruggedized field-deployment archetype, anchoring radiation monitoring segments where environmental and defense end users prioritize operational mobility over laboratory-grade resolution.
| Leading Market Players |
|---|
| ORTEC (AMETEK Inc.) |
| CAEN SpA |
| Mirion Technologies |
| Hitachi High-Tech Corporation |
| FAST ComTec |
| Berkeley Nucleonics Corporation |
| Berthold Technologies |
| LabLogic Systems |
| BrightSpec NV/SA |
| Others |
Pricing and Supply Chain Analysis
Backward integration into cryogenic detector manufacturing anchors pricing power for heritage nuclear instrumentation vendors while compressing margin pools for modular firmware specialists dependent on outsourced HPGe crystal supply. This structural divergence separates premium multi-channel system pricing from portable unit commoditization pressure.
Pricing Analysis
The bundled-vs-unbundled service split separates hospital procurement frameworks from pharmaceutical quality control operations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales integration depth. Cost compression in portable environmental screening tiers intensifies because independent service organizations disintermediate original equipment manufacturers. Contract laboratories exhibit highest price sensitivity; government research installations show least.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for precision radiation instrumentation. Ultra-pure germanium crystal growth draws from limited foundry capacity in Belgium and the United States; thallium-doped sodium iodide feedstock sources from rare earth element mining concentrated in China. Single-source vulnerability in cryogenic detector manufacturing creates structural risk. Distribution runs through specialized scientific equipment distributors serving regulated laboratory environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Multichannel Analyzer Market reads as a late-cycle quality story where hospital systems and pharmaceutical quality control operations prioritize FDA 21 CFR Part 11 pre-validated software packages over capital cost minimization.
For Market Incumbents: Anchor market position through captive supply of cryogenic detector components and accelerated cloud-connected firmware certification for dual FDA-EU MDR compliance. Modular firmware specialists threaten heritage vendors through dense channel integration; vertical integration into HPGe crystal manufacturing defends margin structure against this encroachment. For New Entrants and Emerging Players: Capture white-space in India's CDSCO-streamlined procurement channels and EU Green Deal environmental baseline survey mandates for decommissioned industrial sites. Portable battery-operated analyzers with wireless data transmission represent the most penetrable product tier; partner with third-party calibration providers to bypass incumbent service network advantages. For Investors and Strategic Acquirers: Roll-up economics work for modular firmware architecture specialists because hospital system consolidation is compressing vendor counts and prioritizing scalable multi-detector array suppliers. Five-to-ten year viability favors vendors with pre-validated quality management systems; acquisition target archetype encompasses mid-channel system designers with ISO 13485 certification. Watch AI-assisted spectrum analysis algorithm deployment as inflection indicator for operator training requirement reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EU MDR Software Validation | Pre-validated electronic records packages compress pharmaceutical procurement cycles in Switzerland and the Netherlands. |
| Cloud-Connected Firmware Architecture | Remote diagnostic access pilots at national laboratories in Tennessee and New Mexico collapse hardware-software boundaries. |
| Backward Integration into HPGe Manufacturing | Captive cryogenic detector supply insulates premium spectroscopy vendors from germanium crystal price volatility. |
| Portable Analyzer Wireless Data Transmission | Battery-operated field-deployable units align with NRC license condition expansion for point-of-need environmental screening. |
| AI-Assisted Spectrum Analysis Development | Machine learning radionuclide identification algorithms reduce operator training burdens in contract laboratory environments. |
Research Methodology
Bottom-up nuclear medicine department modeling reconciled against top-down HPGe detector supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads combine with secondary validation against FDA 510(k) filings, EPA radiological monitoring protocols, NRC license condition databases, and ISO 13485 certification registries.
Historical trendline analysis of multi-channel system installations and portable unit deployments across the projection horizon informs growth trajectory calibration. Segmentation dimensions span product type, detection technology, application workflow, and end-user procurement structure. CAGRs derive from unit economics modeling of pharmaceutical quality control capital cycles and environmental surveillance protocol expansion rates.
Germanium crystal supply disruption, EU MDR technical documentation requirement expansion, and AI-assisted spectrum analysis regulatory classification are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Metallurgical Microscope Market