
 Russia Paper Packaging Market | 2026-2036
Russia Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Paper Packaging Market Analytics
Modular folding-carton configurations is hardening as the dominant format for pharmaceutical and personal care brands seeking shelf differentiation and supply chain flexibility. Ilim Group leverages its integrated pulp-to-board infrastructure across Siberian and northwestern mills to secure fiber supply. Mondi Group differentiates through coated specialty grades that serve electronics exporters requiring moisture-resistant barriers. Segezha Group anchors its position in corrugated and boxboard segments through extensive forest lease holdings and sawmill co-location.
Russia paper packaging comprises paper-based containment and protection systems manufactured from kraft pulp, recycled fibers, or coated substrates, typically ranging from 200 to 400 gsm for folding cartons and up to triple-wall flute profiles for heavy-duty shipping. These materials undergo calendering, lamination, or extrusion coating to achieve grease resistance, printability, or structural rigidity for industrial and consumer goods distribution. Boxboard and folding cartons lead value generation due to their penetration across food retail and pharmaceutical blister packs, while paper bags register accelerated momentum as quick-service restaurants and grocery chains phase out polyethylene alternatives. Recycled material grade volumes expand fastest among municipal waste sorting investments, though coated grades retain margin concentration in premium cosmetics and export-oriented electronics packaging.
Russia's technical regulation on packaging safety, administered by Rosstandart, together with the Ministry of Natural Resources' extended producer responsibility decrees, shapes substrate choices and recycling infrastructure deployment. The EAEU's harmonized labeling requirements for food contact materials further constrain import sourcing and elevate domestic certification costs for converters. Stakeholders must monitor enforcement intensity around recycled-content quotas and the Central Bank's ruble volatility management, as these jointly determine whether domestic fiber integration or imported equipment modernization delivers superior returns.
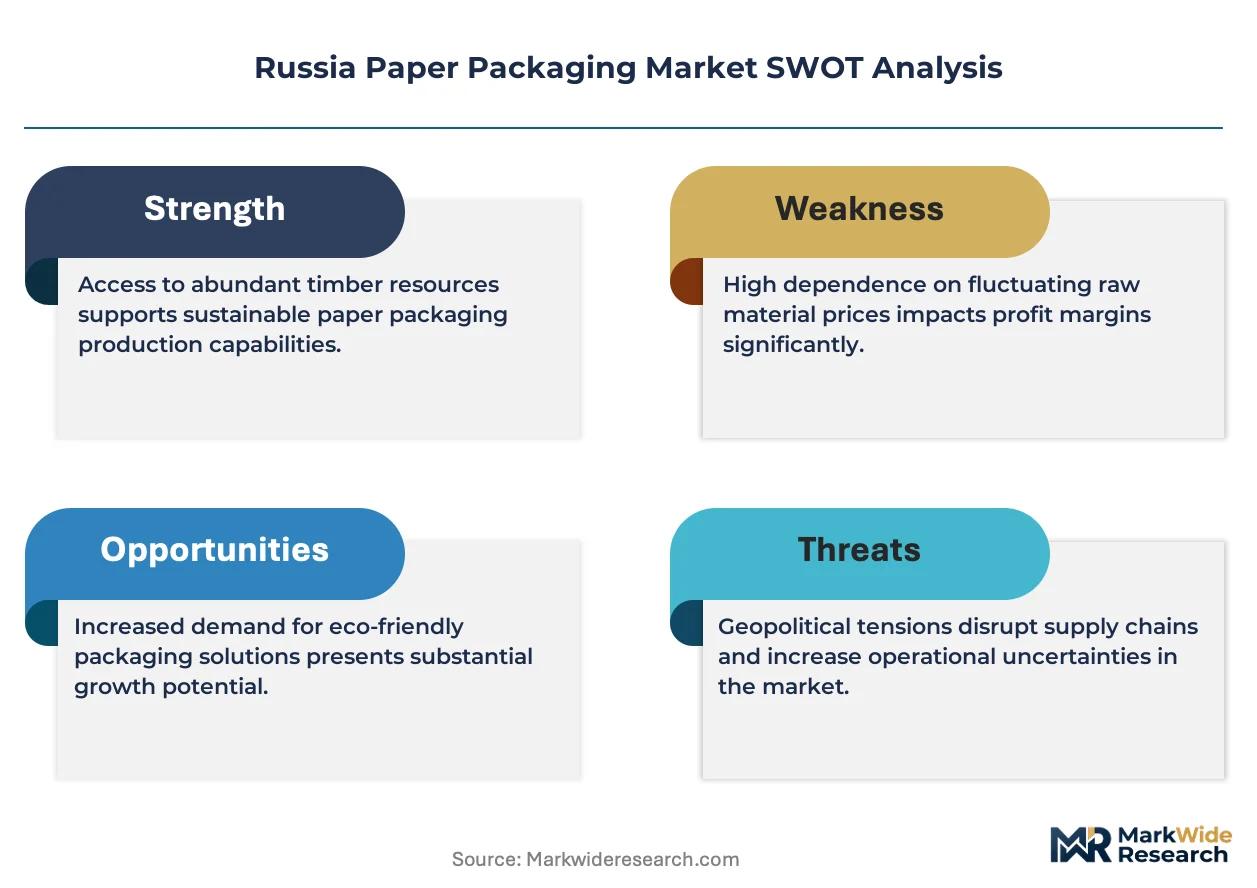
Market Dynamics
Rosstandart's extended producer responsibility decrees are forcing converters to reconfigure fiber sourcing and recycling infrastructure ahead of tightened recycled-content quotas. The Central Federal District's dominance as a demand cluster creates geographic asymmetry between Moscow-based fulfillment networks and Siberian pulp supply.
Growth Catalysts
- Import substitution mandates:Food and beverage processors are switching to domestic paper-based primary packaging as foreign substrate supplies face EAEU certification barriers. This accelerates demand for locally certified folding cartons.
- E-commerce fulfillment expansion:Moscow-based retail chains and quick-service restaurants are scaling corrugated box consumption to serve same-day delivery networks. Triple-wall flute profiles see particular traction for heavy-goods shipping.
- Extended producer responsibility framework:The Ministry of Natural Resources' recycled-content thresholds are compelling municipal waste sorting investments. Recycled material grade volumes expand fastest in the Central Federal District.
Market Restraints
- Pulp cost volatility:Softwood kraft pulp prices fluctuate with ruble exchange rate movements managed by the Central Bank. Converters without captive fiber face margin compression during currency instability.
- Siberian supply concentration:Ilim Group's integrated pulp-to-board infrastructure controls critical fiber access across northwestern and Siberian mill networks. Independent converters face upstream dependency risks.
- Polyethylene substitution threat:Flexible plastic packaging retains cost advantages for moisture-sensitive electronics exports despite coated specialty grade advances. Some brands delay paper transitions.
Strategic Opportunities
- Volga Federal District underpenetration:Secondary cities between Moscow and Kazan lack dedicated folding carton converters. Regional distributors could establish localized finishing capacity for pharmaceutical blister packs.
- Quick-service restaurant channel innovation:Paper bags for food delivery are displacing polyethylene alternatives as chains phase out single-use plastics. Grease-resistant substrates command premium positioning.
- EAEU harmonization tailwind:Unified labeling requirements for food contact materials create scale advantages for domestic converters achieving cross-border certification. Export-oriented electronics packaging benefits.
Industry Challenges
- Extrusion coating technician scarcity:Specialized operators for moisture barrier application are concentrated in legacy Soviet-era mill towns. Training pipelines lag converter expansion plans.
- Legacy equipment modernization capex:Calendering and lamination lines require ruble-denominated debt financing amid Central Bank rate volatility. Smaller converters delay automation investments.
- Rosstandart certification timelines:Food contact safety approvals stretch 14-18 months for novel coated substrates. Product launch cycles compress against regulatory windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Paper Packaging Market |
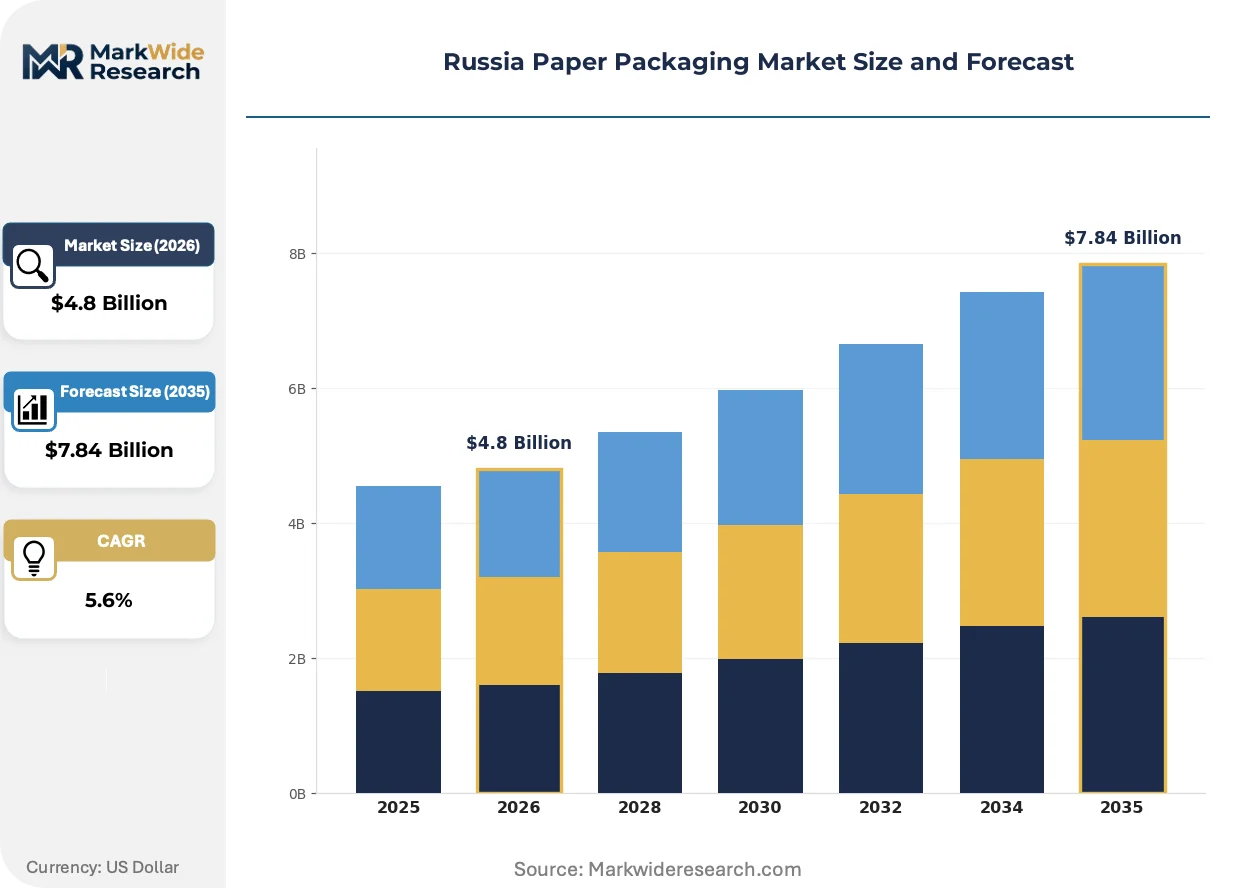
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxboard, Paper Bags, Folding Cartons, Wrapping Paper End User: Food & Beverage, Personal Care, Electronics, Pharmaceuticals Application: Packing, Shipping, Retail, Storage Material Grade: Recycled, Coated, Uncoated, Specialty |
| Companies Covered | Arkhangelsk PPM, International Paper (DS Smith), Ilim Group, Tetra Pak Russia, Smurfit WestRock, Segezha Group, Gotek Group, Kama PPM, Mondi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Paper Packaging Market Evolving Landscape
Substrate engineering and regulatory compliance automation are converging to reshape competitive positioning across Russian paper packaging. Converters are racing to integrate barrier technologies ahead of EAEU enforcement milestones.
Water-based barrier coatings are integrating into folding carton production lines to replace polyethylene laminates for food contact applications. Pharmaceutical and personal care brands in Moscow are adopting these substrates at accelerated pace to meet Rosstandart's 2025 safety thresholds. The technology is integrating moisture resistance with fiber recyclability, compressing the trade-off between performance and circularity that previously favored plastic.
Rosstandart's technical regulation on packaging safety now mandates batch-level traceability for food contact materials entering the EAEU. Converters must deploy serialization systems or face market exclusion. Folding carton segments serving dairy and ready-meal brands are responding fastest, with Moscow-based plants leading compliance investments.
Centralized procurement by retail chains is consolidating supplier relationships around converters with integrated design-to-delivery capabilities. Quick-service restaurant networks are replacing fragmented regional purchasing with national framework agreements. This concentration is most visible in the Central Federal District, where e-commerce fulfillment centers demand just-in-time boxboard supply with 48-hour turnaround guarantees.
Russia Paper Packaging Market Segmentation
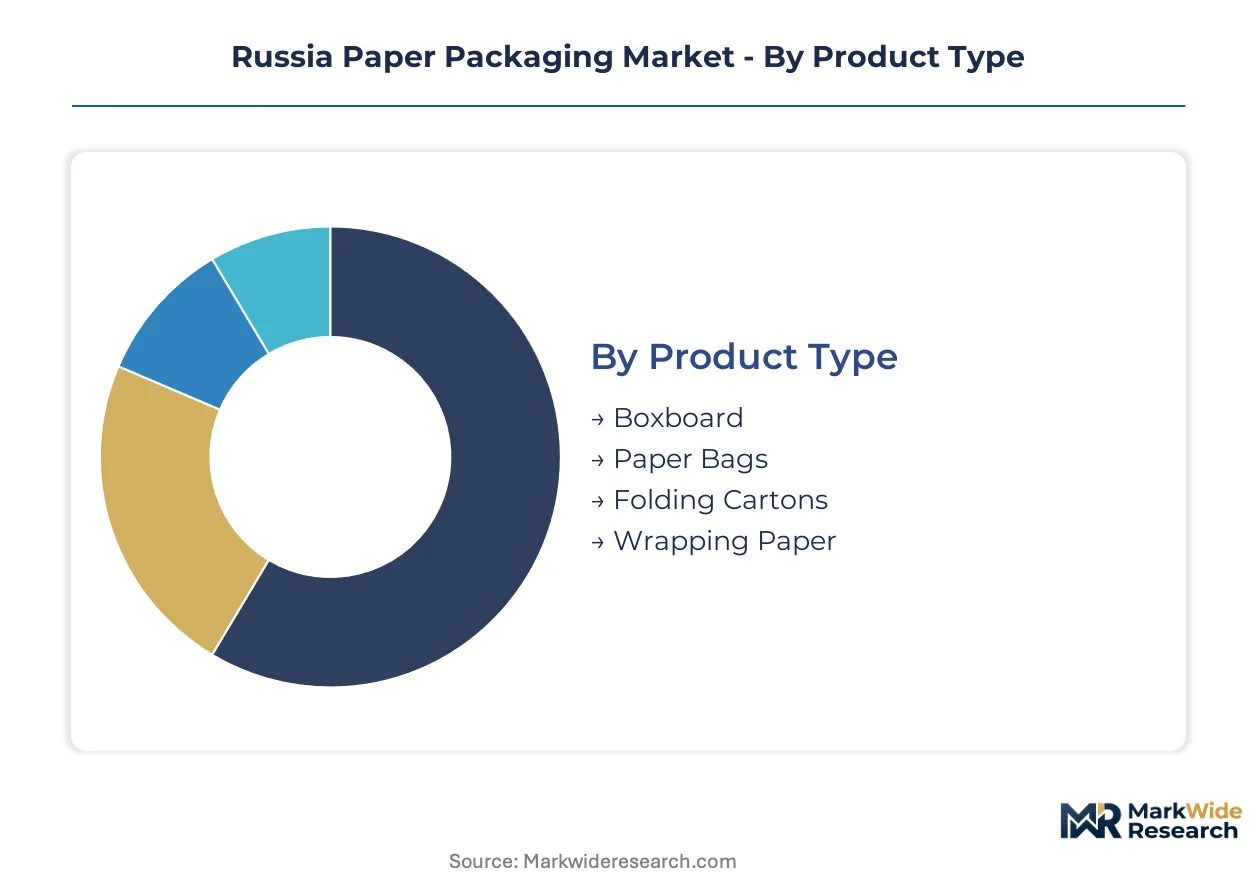
Segmentation in Russia's paper packaging market reveals how regulatory pressure and supply chain geography reshape procurement patterns. Each dimension exposes different fault lines between import substitution mandates, fiber access constraints, and end-use performance requirements.
Product Type:
Standalone formats dominate primary packaging applications, while embedded configurations serve protective functions within broader logistics systems.
- Folding Cartons:These 200-400 gsm structures undergo calendering and die-cutting to create rigid primary packaging for pharmaceuticals and cosmetics. Moscow-based converters supply retail chains with just-in-time delivery guarantees as import substitution accelerates demand for EAEU-certified substrates.
- Boxboard:Multi-ply constructions ranging from white-lined chipboard to solid bleached sulfate provide structural rigidity for electronics and premium food items. Central Federal District fulfillment networks consume the highest volumes for e-commerce shipping consolidation.
- Paper Bags:Kraft and grease-resistant substrates displace polyethylene in quick-service restaurant channels. Rosstandart's extended producer responsibility framework elevates their circularity credentials against plastic alternatives.
- Wrapping Paper:Lightweight uncoated grades protect industrial components and consumer durables during transit. Siberian pulp mills supply fiber for this cost-sensitive segment.
Volume placements concentrate in boxboard; the faster expansion belongs to paper bags.
End User:
Customer concentration varies sharply between regulated sectors demanding certified substrates and price-sensitive channels accepting standard grades.
- Food & Beverage:Dairy, ready-meal, and beverage processors drive folding carton consumption under Rosstandart's food contact safety mandates. Batch-level traceability requirements now govern substrate selection for this largest demand pool.
- Electronics:Export-oriented manufacturers require moisture-resistant coated grades with EAEU harmonized labeling. Mondi Group's specialty barriers serve this quality-sensitive segment.
- Pharmaceuticals:Blister pack backers and informational inserts demand pharmaceutical-grade certification. Personal care brands in Moscow adopt water-based barrier coatings ahead of regulatory deadlines.
- Personal Care:Cosmetics and hygiene products favor premium coated substrates for shelf differentiation. Modular carton configurations enable rapid format changes for promotional cycles.
Food and beverage commands the largest volume footprint; pharmaceuticals exhibits the steepest expansion trajectory as safety regulations tighten.
Application:
Functional role determines whether packaging remains with the end consumer or re-enters recycling streams through industrial channels.
- Packing:Primary containment functions for retail sale. Folding cartons and boxboard dominate, with grease-resistant substrates gaining share in food service.
- Shipping:Protective logistics functions through distribution networks. Triple-wall corrugated profiles handle heavy-goods transport for Central Federal District e-commerce hubs.
- Retail:Point-of-sale presentation and shelf-ready formats. Quick-service restaurant chains consolidate procurement around national framework agreements.
- Storage:Intermediate warehousing and bulk handling. Lower-grade recycled materials serve this cost-minimized application.
Shipping applications absorb the highest tonnage; retail formats are climbing the fastest as brand owners prioritize shelf impact.
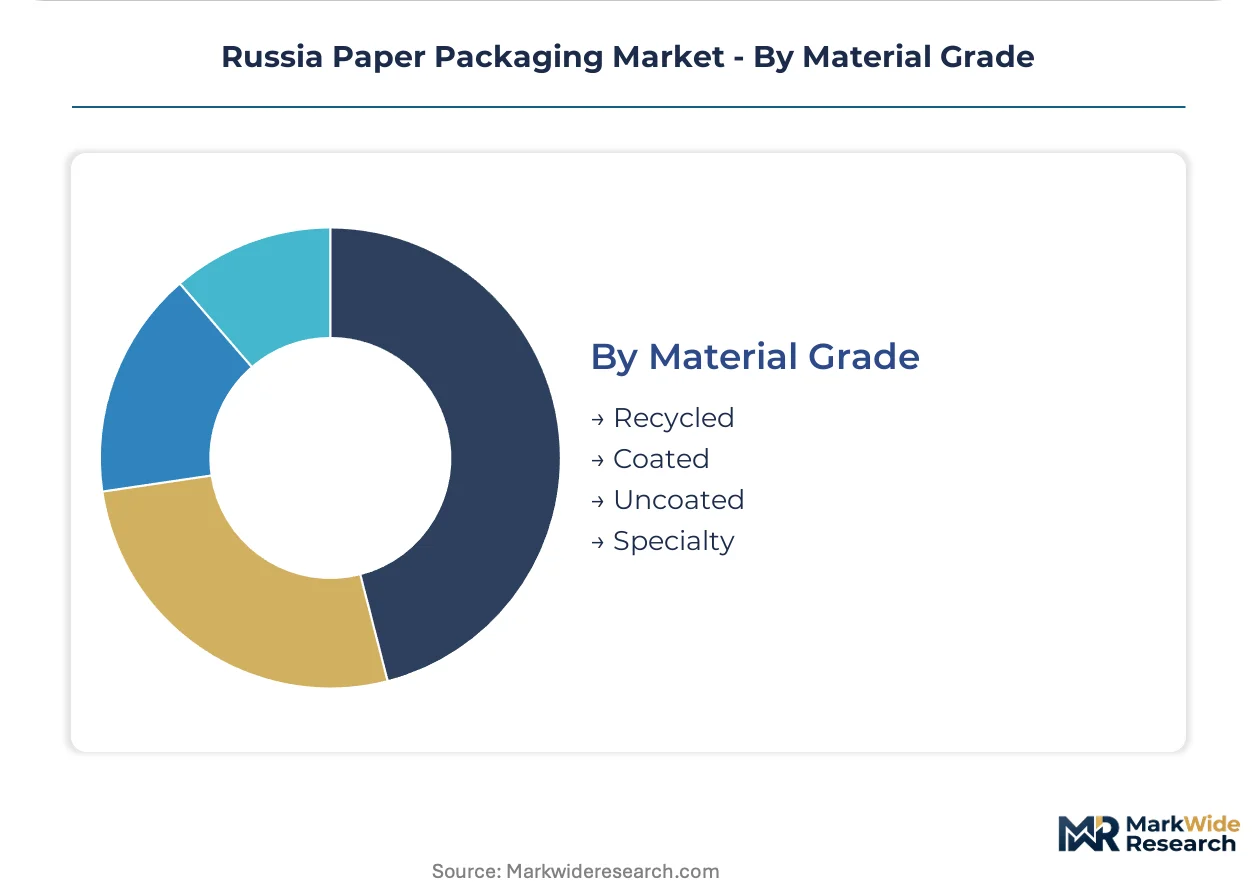
Material Grade:
Fiber origin and surface treatment create a hierarchy of performance, compliance cost, and circularity credentials across the value chain.
- Recycled:Post-consumer fiber grades expand fastest as municipal waste sorting investments mature. Ministry of Natural Resources thresholds mandate rising incorporation rates.
- Coated:Clay or polymer surface treatments enable high-resolution printing and moisture resistance. Electronics exporters and premium cosmetics rely on these margin-concentrated substrates.
- Uncoated:Natural kraft and testliner grades serve cost-sensitive industrial applications. Ilim Group's Siberian pulp integration supplies this volume segment.
- Specialty:Extrusion-coated or laminated barriers for demanding performance specifications. Technician scarcity constrains converter expansion in this high-value tier.
Uncoated grades maintain volume dominance; recycled material is gaining share fastest under extended producer responsibility enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's paper packaging production clusters in Siberia and the northwest, while consumption concentrates around Moscow and the Central Federal District. This geographic asymmetry shapes logistics costs and converter procurement strategies.
Central Federal District
Moscow-based e-commerce fulfillment centers and retail chains drive boxboard demand for same-day delivery networks. Rosstandart's extended producer responsibility decrees mandate recycled-content thresholds that accelerate municipal waste sorting investments. Converters in the Moscow region supply pharmaceutical blister packs and food contact cartons under tight 48-hour turnaround guarantees.
Northwestern Federal District
Arkhangelsk and Leningrad oblasts host integrated pulp-to-board mills serving export-oriented electronics packaging. The Ministry of Natural Resources' forest lease policies concentrate fiber access among vertically integrated operators. St. Petersburg converters specialize in coated specialty grades requiring EAEU harmonized labeling certification.
Siberian Federal District
Krasnoyarsk Krai and Irkutsk Oblast anchor softwood kraft pulp production for uncoated industrial grades. Ilim Group's mill networks control critical fiber supply for independent converters facing upstream dependency risks. Regional sawmill co-location generates wood residues for boxboard furnish.
Volga Federal District
Secondary cities between Moscow and Kazan present underpenetrated demand for pharmaceutical folding cartons and food service paper bags. The Central Bank's ruble volatility management complicates equipment modernization financing for prospective regional entrants. Local distributors could establish finishing capacity for blister pack backers.
Southern Federal District
Rostov-on-Don and Krasnodar Krai serve quick-service restaurant chains phasing out polyethylene alternatives. Grease-resistant substrate demand climbs as national framework agreements consolidate procurement. Black Sea port access supports coated grade exports to EAEU markets.
Russia Paper Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Russia's paper packaging value chain. The market structure tilts toward consolidation among integrated pulp-to-board operators controlling Siberian fiber access. Three archetypes dominate: vertically integrated forest-products majors, regional converters with design-to-delivery capabilities, and specialty barrier-coating technicians. Competitive moves center on backward integration into pulp supply and strategic partnerships with retail chains for national framework agreements.
Among integrated forest-products majors, Ilim Group, Segezha Group, and Mondi Group exemplify scale-driven positioning. Ilim Group anchors the pulp-to-board infrastructure tier through Siberian and northwestern mill networks. Segezha Group occupies a position within corrugated and boxboard segments tied to extensive forest lease holdings. Mondi Group sits within the specialty-coated grade tier serving moisture-sensitive export applications. These three represent the upstream concentration that shapes margin structures for independent converters lacking captive fiber.
| Leading Market Players |
|---|
| Arkhangelsk PPM |
| International Paper (DS Smith) |
| Ilim Group |
| Tetra Pak Russia |
| Smurfit WestRock |
| Segezha Group |
| Gotek Group |
| Kama PPM |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Captive pulp-to-board integration across Siberian and northwestern mill networks anchors both supply security and pricing power for Russian paper packaging converters. Ilim Group's fiber control creates asymmetric cost positions that independent competitors cannot replicate without ruble-denominated debt exposure.
Pricing Analysis
Margin tightening in uncoated industrial grades reflects Ilim Group's captive fiber advantage over independent converters. Three-tier pricing structure across premium coated, standard boxboard, and economy recycled levels separates electronics exporters from mass-market food retail. Price differentiation hinges on Rosstandart certification tier and volume scale under national framework agreements. Quick-service restaurant chains exhibit highest price sensitivity; pharmaceutical blister pack buyers prioritize compliance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Siberian softwood kraft pulp concentration across Krasnoyarsk Krai and Irkutsk Oblast mill networks. Raw material dependencies center on wood residues from sawmill co-location, imported coating chemicals, and recycled fiber from municipal sorting investments. Supply chain risk traces to Central Bank ruble volatility complicating equipment modernization financing. Distribution runs through Moscow-based fulfillment networks serving Central Federal District e-commerce hubs with 48-hour turnaround guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's paper packaging sector is consolidating around integrated pulp-to-board operators as Rosstandart's extended producer responsibility thresholds force sub-scale converters into exit or acquisition.
For Market Incumbents: Lock in fiber supply through long-term forest lease extensions or sawmill co-location partnerships before independent competitors secure ruble financing. Accelerate water-based barrier coating certification ahead of Rosstandart's food contact safety enforcement milestones. Defend against polyethylene substitution threats by demonstrating grease-resistant substrate performance at quick-service restaurant trials. For New Entrants and Emerging Players: Secondary cities in the Volga Federal District between Moscow and Kazan present underpenetrated demand for pharmaceutical folding cartons and food service paper bags. Regional distributors can establish localized finishing capacity for blister pack backers without competing against Ilim Group's pulp integration. Go-to-market positioning should emphasize 48-hour turnaround guarantees matching Central Federal District service levels. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty barrier-coating technicians with Rosstandart batch-traceability compliance already deployed. Five-to-ten year viability favors converters with captive fiber or design-to-delivery integration serving retail chain national frameworks. Watch extrusion coating technician training pipeline expansion as the inflection signal for specialty grade capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Ilim Group's Siberian mill networks demonstrate how captive fiber insulates margins from ruble volatility. |
| Water-Based Barrier Coating Certification | Rosstandart's food contact safety mandates create first-mover advantage for compliant converters. |
| Regional Finishing Capacity Expansion | Volga Federal District underpenetration offers white-space capture without competing against integrated majors. |
| National Framework Agreement Procurement | Quick-service restaurant chains consolidate purchasing around design-to-delivery capabilities. |
| Extrusion Coating Technician Training | Specialty grade expansion hinges on overcoming Soviet-era mill town talent concentration constraints. |
Research Methodology
Document review covered trade customs data, Rosstandart regulatory filings, and EAEU harmonization directives, complemented by interviews with mill operations directors, folding carton procurement managers at retail chains, and extrusion coating technicians. Primary fieldwork engaged Siberian pulp mill executives, Moscow-based converter plant managers, and pharmaceutical packaging specification leads. Secondary validation drew from Ministry of Natural Resources extended producer responsibility decrees, Central Bank ruble volatility reports, and forest lease holding disclosures. Bottom-up capacity modeling and top-down demand estimation were triangulated against regional production cluster data.
Output metrics spanning tonnage, value, and grade mix were generated across product type, end user, application, and material grade segmentation dimensions. CAGRs were derived from trend extrapolation moderated by regulatory enforcement intensity assumptions and import substitution pace. Forecast inputs incorporated municipal waste sorting investment timelines, quick-service restaurant polyethylene phase-out commitments, and EAEU cross-border certification adoption rates.
Revisions become necessary when Rosstandart accelerates recycled-content quota enforcement, Central Bank rate volatility exceeds modeled bands, or polyethylene substitution economics shift dramatically. Forecasts reflect documented assumptions about regulatory timelines and fiber supply concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Display Paper Box Market