
 Global Endoscopic Vessel Harvesting Systems Market | 2026-2036
Global Endoscopic Vessel Harvesting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopic Vessel Harvesting Systems Market Foresight
CE marking under EU MDR and FDA 510(k) clearance cycles is collapsing from historical norms, compressing the window for new entrants to establish clinical evidence. Getinge leverages its integrated perfusion and surgical workflows to sustain bundled contract positions across European hospital networks. Medtronic anchors North American distribution through deep cath lab relationships and proprietary vessel assessment protocols. Terumo Corporation differentiates via electromechanical harvesting platforms that navigate Japan's stringent reimbursement scrutiny.
Endoscopic vessel harvesting systems comprise minimally invasive surgical instruments designed for saphenous vein and radial artery extraction through small incisions, typically employing endoscopic visualization with carbon dioxide insufflation and thermal or mechanical dissection modalities to preserve conduit integrity for coronary revascularization. These systems integrate optical imaging channels with electromechanical cutting mechanisms to reduce leg wound complications and accelerate postoperative recovery compared to open harvesting techniques. Vein harvesting systems occupy the dominant revenue position given established clinical protocols for saphenous vein graft procurement in coronary artery bypass grafting, while robotic assisted systems represent the fastest-expanding technology segment as hospitals seek to standardize anastomotic precision and reduce operator-dependent variability. Optical imaging technologies lead technology adoption due to mature supply chains and surgeon familiarity, though fluorescence-guided systems are gaining procedural share through enhanced vessel delineation capabilities.
FDA premarket notification requirements, EU MDR technical documentation mandates, and Japan's PMDA shonin approval pathways collectively elevate barriers for novel harvesting technologies seeking multi-regional commercialization. These frameworks demand extensive biocompatibility testing, sterilization validation, and clinical outcome documentation that favor incumbents with established quality management systems and regulatory affairs infrastructure. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital health guidance intersections with robotic harvesting platforms to anticipate compliance cost trajectories and competitive access dynamics.
Market Dynamics
EU MDR recertification timelines and FDA 510(k) clearance compression are forcing vendors to front-load clinical evidence generation, privileging incumbents with established quality management infrastructure over emerging entrants seeking multi-regional commercialization.
Growth Catalysts
- Japan PMDA shonin pathways:Accelerated reimbursement scrutiny for electromechanical harvesting platforms creates competitive differentiation for compliant vendors.
- Coronary artery bypass grafting volumes:Elevated procedural demand in the United States, Germany, and Japan sustains replacement cycle momentum for harvesting systems.
- Fluorescence-guided vessel delineation:Enhanced optical imaging capabilities expand procedural indications beyond standard saphenous vein procurement protocols.
Market Restraints
- EU MDR notified body capacity constraints:Technical documentation mandates and biocompatibility testing requirements extend certification timelines for novel harvesting technologies.
- Carbon dioxide insufflation supply volatility:Input cost fluctuations for insufflation gases compress margin structures across disposable component portfolios.
- Conduit preservation limitations:Thermal dissection modalities risk endothelial damage compared to mechanical alternatives, constraining clinical protocol standardization.
Strategic Opportunities
- Robotic-assisted anastomotic standardization:Convergence of electromechanical harvesting with surgical robotics addresses operator-dependent variability in high-volume cardiac centers.
- India's expanding cardiac surgery infrastructure:Underpenetrated tertiary care networks present white space for minimally invasive harvesting platform deployment.
- Bundled perfusion workflow contracts:Integrated surgical system positioning across European hospital networks captures cath lab and OR capital allocation decisions.
Industry Challenges
- Surgeon training pathway compression:Minimally invasive technique certification requirements outpace fellowship program capacity expansion in established markets.
- Legacy vessel assessment protocol integration:Proprietary imaging formats create data interoperability friction with existing electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopic Vessel Harvesting Systems Market |
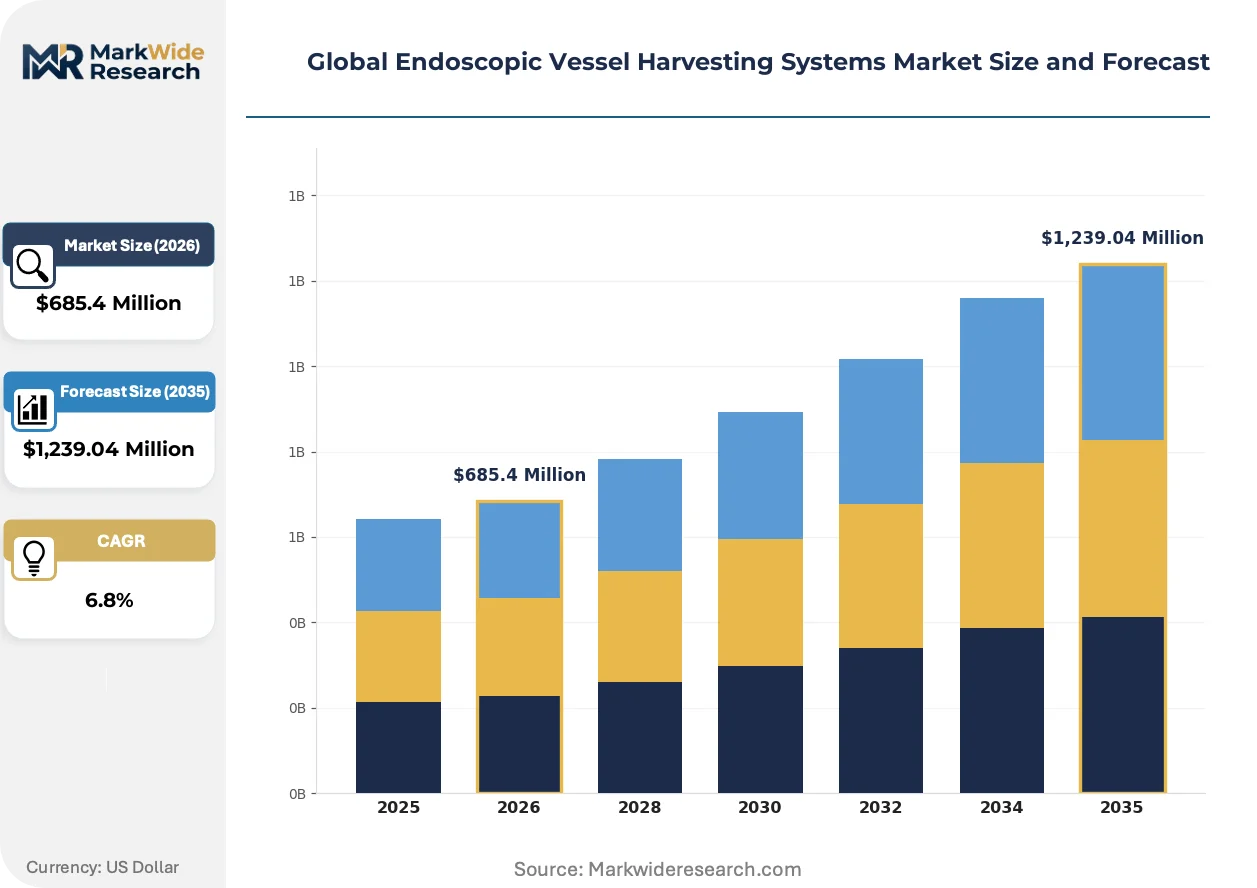
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vein Harvesting Systems, Artery Harvesting Devices, Hybrid Harvesters, Robotic Assisted Systems, Manual Tools Technology: Optical Imaging, Laser Assisted, Radiofrequency, Ultrasonic, Fluorescence, Electromechanical Application: Coronary Artery Bypass Grafting, Peripheral Artery Disease Treatment, Valve Repair, Lymphatic Vessel Reconstruction End User: Cardiothoracic Surgery Centers, Specialty Clinics, Research Laboratories, Academic Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Getinge, Terumo Corporation, Medtronic, LivaNova, Saphena Medical, KARL STORZ, Stryker, Maquet, Medical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopic Vessel Harvesting Systems Market Shifts & Advancements
Electromechanical harvesting platforms are actively fragmenting traditional optical imaging dominance through enhanced vessel assessment capabilities and reduced operator variability. Regulatory convergence across FDA, EU MDR, and PMDA frameworks is compressing innovation cycles toward standardized clinical evidence packages.
Robotic-assisted harvesting systems is decomposing conventional endoscopic platform architectures by integrating force-feedback instrumentation with autonomous vessel mapping algorithms. High-volume cardiothoracic surgery centers in Germany and Japan are piloting these configurations to reduce anastomotic revision rates. The technology is decomposing standalone harvesting device margins into comprehensive surgical workflow contracts that bundle capital equipment with per-procedure consumable commitments.
EU MDR technical documentation mandates are elevating sterilization validation and biocompatibility testing burdens for vessel harvesting system manufacturers seeking CE marking renewal. The regulation forces consolidation of supplier qualification programs and accelerates outsourcing of notified body interactions to specialized regulatory affairs consultancies. Electromechanical platform vendors with pre-existing ISO 13485 infrastructure capture disproportionate certification velocity compared to optical imaging incumbents navigating legacy quality system migrations.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, shifting toward performance-guaranteed maintenance agreements with penalty clauses for system downtime. This pattern disrupts traditional distributor-led service models across North American integrated delivery networks. The behavior is most pronounced in United States academic medical centers where value-analysis committees now mandate total cost-of-ownership documentation spanning five-year utilization horizons.
Global Endoscopic Vessel Harvesting Systems Market Segmentation
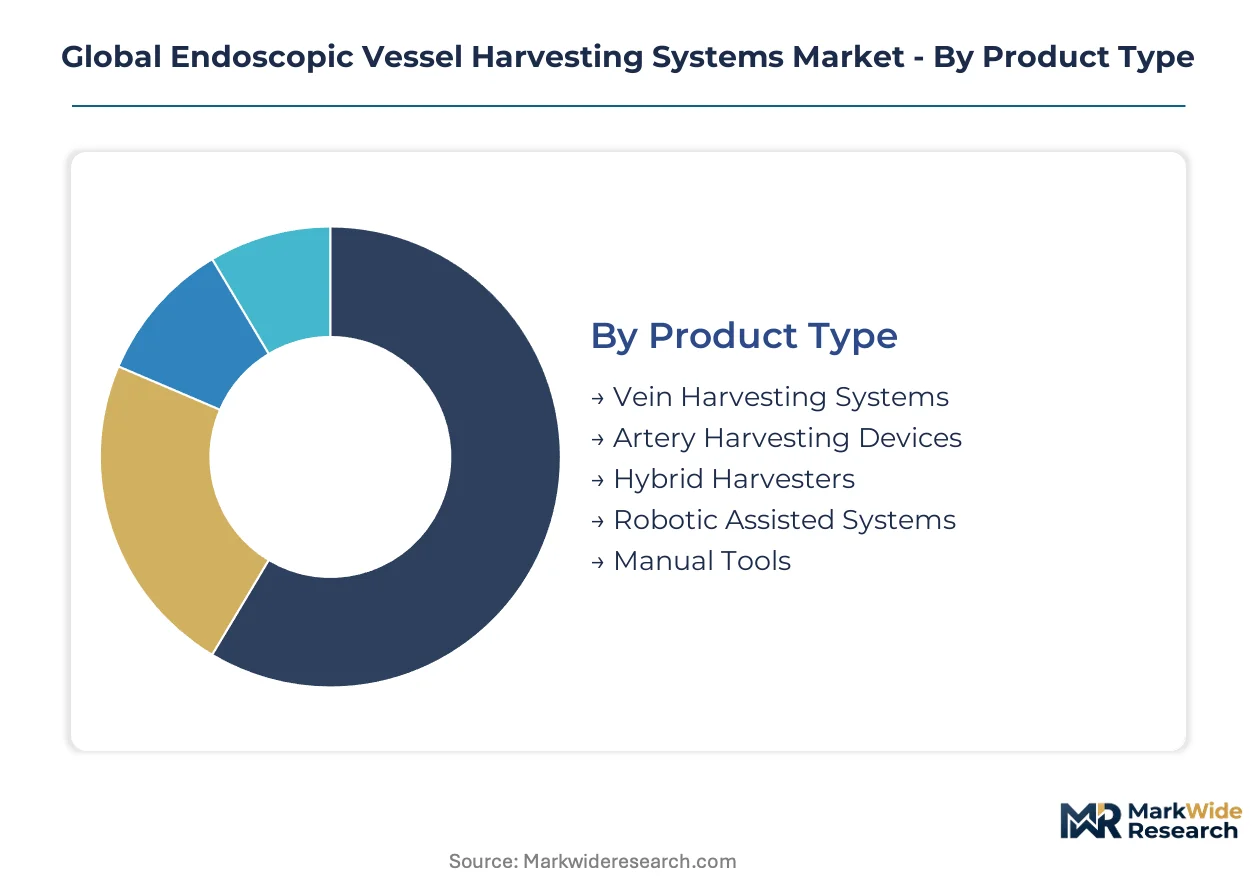
Endoscopic vessel harvesting systems fragment across product architectures, energy modalities, clinical indications, and care settings. Each dimension carries distinct regulatory pathways, reimbursement profiles, and capital intensity requirements that reshape vendor positioning.
Product Type:
Domestic demand concentrates in electromechanical and robotic platforms across Japan and Germany, while manual tools and hybrid harvesters serve price-sensitive procurement in India and Southeast Asian markets.
- Vein Harvesting Systems:These platforms integrate carbon dioxide insufflation with thermal or mechanical dissection for saphenous vein extraction. United States cardiothoracic surgery centers drive replacement cycles as coronary artery bypass grafting volumes sustain installed base refresh.
- Robotic Assisted Systems:Force-feedback instrumentation with autonomous vessel mapping algorithms reduces operator-dependent variability. German and Japanese high-volume cardiac centers pilot these configurations to standardize anastomotic precision.
- Artery Harvesting Devices:Specialized radial artery procurement instruments with smaller port profiles.
- Hybrid Harvesters:Dual-modality platforms combining optical and electromechanical dissection.
- Manual Tools:Basic endoscopic retractors and dissectors for resource-constrained settings.
Vein harvesting systems command the established base. The steepest expansion runs through robotic assisted systems.
Technology:
Cost tiers separate mature optical imaging from premium fluorescence and electromechanical platforms, with laser and radiofrequency occupying mid-market positioning.
- Optical Imaging:Mature visualization channels with carbon dioxide insufflation dominate installed bases. Surgeon familiarity and established supply chains sustain procurement across United States academic medical centers despite technical limitations.
- Fluorescence:Near-infrared vessel delineation capabilities expand procedural indications beyond standard saphenous vein protocols. Japan's PMDA reimbursement scrutiny favors vendors with robust clinical evidence packages.
- Laser Assisted:Precision cutting with reduced thermal spread for conduit preservation.
- Radiofrequency:Bipolar energy delivery for vessel sealing and transection.
- Ultrasonic:Harmonic scalpel technology for simultaneous cutting and coagulation.
- Electromechanical:Motorized dissection with integrated vessel assessment protocols.
Optical imaging anchors current revenue. Fluorescence platforms are gaining share fastest through enhanced visualization capabilities.
Application:
Volume concentration in coronary revascularization creates margin pressure, while peripheral and lymphatic applications offer expansion corridors for specialized platforms.
- Coronary Artery Bypass Grafting:Established protocols for saphenous vein and radial artery procurement sustain the core demand base. United States, Germany, and Japan maintain elevated procedural volumes that drive system utilization.
- Peripheral Artery Disease Treatment:Lower extremity revascularization with autologous conduit harvest. Specialty clinics in Germany explore minimally invasive platforms for femoropopliteal bypass procedures.
- Valve Repair:Concomitant vessel harvest during open cardiac procedures.
- Lymphatic Vessel Reconstruction:Emerging microsurgical applications for lymphedema management.
Coronary artery bypass grafting commands the established base. The steepest expansion runs through peripheral artery disease treatment.
End User:
Customer type stratifies across integrated delivery networks with bundled contracting power versus independent facilities with capital constraints.
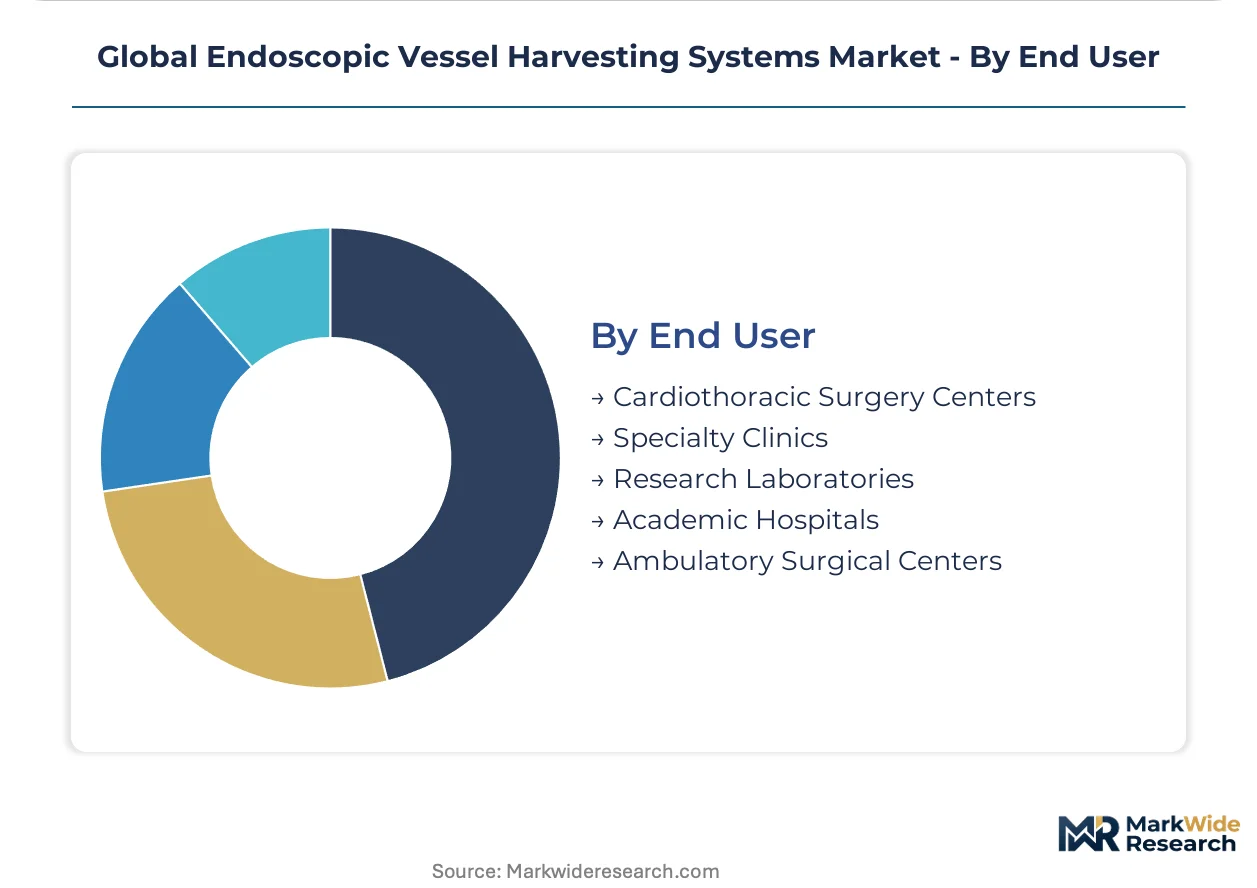
- Cardiothoracic Surgery Centers:High-volume cardiac programs with dedicated perfusion teams and standardized protocols. United States integrated delivery networks leverage scale for total cost-of-ownership negotiations.
- Academic Hospitals:Research-active institutions driving technology evaluation and fellowship training pathways. Value-analysis committees mandate five-year utilization documentation.
- Specialty Clinics:Focused vascular surgery practices with selective platform adoption.
- Research Laboratories:Preclinical and clinical trial sites for novel harvesting modalities.
- Ambulatory Surgical Centers:Limited applicability given procedure complexity and emergency backup requirements.
Cardiothoracic surgery centers command the established base. The steepest expansion runs through academic hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-volume cardiothoracic surgery centers concentrate procurement power across the United States, Germany, and Japan, where coronary artery bypass grafting volumes sustain replacement cycles for minimally invasive harvesting platforms.
United States
Academic medical centers and integrated delivery networks drive system utilization through value-analysis committees mandating five-year total cost-of-ownership documentation. FDA 510(k) clearance pathways compress vendor qualification timelines, privileging incumbents with established quality management infrastructure. The Cleveland Clinic and Mayo Clinic anchor clinical protocol standardization for electromechanical harvesting adoption.
Germany
Cardiothoracic surgery centers in Bavaria and North Rhine-Westphalia pilot robotic-assisted configurations to reduce anastomotic revision rates. EU MDR technical documentation mandates elevate sterilization validation burdens, forcing consolidation of supplier qualification programs. The Heidelberg and Berlin hospital networks bundle perfusion workflow contracts across European procurement alliances.
Japan
High-volume cardiac programs in Tokyo and Osaka navigate stringent PMDA shonin reimbursement scrutiny for electromechanical platforms. METI industrial policy supports domestic medical device manufacturing, creating procurement preferences for Japan-origin equipment. The Juntendo and Keio University hospital systems standardize fluorescence-guided vessel delineation protocols.
India
Underpenetrated tertiary care networks in Maharashtra and Karnataka present deployment corridors for cost-optimized harvesting platforms. CDSCO medical device registration requirements are harmonizing with IMDRF guidelines, streamlining import pathways for multinational vendors. The All India Institute of Medical Sciences in New Delhi and Narayana Health in Bangalore anchor training pathway expansion for minimally invasive techniques.
Global Endoscopic Vessel Harvesting Systems Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with integrated perfusion and surgical workflows. Three to five vendors capture disproportionate share through bundled contract positions across European and North American hospital networks. Strategic archetypes separate electromechanical platform specialists from optical imaging incumbents and robotic-assisted system integrators. Competitive moves concentrate on M&A for regulatory infrastructure assets and strategic partnerships for fluorescence-guided technology licensing.
Among diversified medical technology conglomerates, Getinge and Medtronic exemplify the integrated workflow archetype through bundled perfusion and surgical system positioning. Terumo Corporation anchors the electromechanical specialization tier within Japan-origin manufacturers navigating PMDA reimbursement frameworks. These three entities occupy positions that reflect divergent geographic anchoring and regulatory compliance infrastructure rather than interchangeable competitive positioning.
| Leading Market Players |
|---|
| Getinge |
| Terumo Corporation |
| Medtronic |
| LivaNova |
| Saphena Medical |
| KARL STORZ |
| Stryker |
| Maquet |
| Medical Instruments |
| Others |
Supply & Pricing Matrix
Ninety-day sterilization validation cycles for carbon dioxide insufflation components compress inventory buffers across disposable portfolios, tethering pricing power to German and Japanese electromechanical platform manufacturers with captive ISO 13485 infrastructure.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate European hospital procurement, separating premium electromechanical systems with bundled service commitments from standard optical imaging platforms and economy manual tools. Price differentiation hinges on FDA 510(k) tier certification and five-year total cost-of-ownership documentation demanded by United States academic medical centers. Pricing pressure stems from carbon dioxide insufflation supply volatility compressing margins in disposable component tiers. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with bundled perfusion contracts demonstrate lowest.
Supply Chain Analysis
Germany and Japan anchor precision electromechanical actuator manufacturing, while the United States concentrates optical imaging channel production and China supplies carbon dioxide insufflation hardware. Raw material dependencies span medical-grade polymers, near-infrared fluorescence dyes, and biocompatible sterilization packaging. Single-source vulnerability concentrates in electromechanical motor assemblies qualified under EU MDR technical documentation mandates. Distribution runs through specialized cardiac surgery distributors with cath lab and OR capital equipment relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) clearance compression and EU MDR recertification timelines erect switching-cost barriers that privilege incumbents with established quality management infrastructure.
For Market Incumbents: Shield bundled contract positions across European hospital networks by deepening backward integration into sterilization validation services, countering emerging electromechanical specialists threatening unbundled service arrangements. Accelerate ISO 13485 infrastructure deployment in Japan to capture PMDA shonin pathway velocity advantages over optical imaging incumbents navigating legacy quality system migrations.
For New Entrants and Emerging Players: Post-market surveillance data aggregation services represent an under-served layer where incumbents under-invest, creating white-space for specialized analytics vendors to penetrate United States academic medical centers with value-analysis committee relationships. Target India's underpenetrated tertiary care networks in Maharashtra and Karnataka with cost-optimized hybrid harvester platforms, leveraging CDSCO registration harmonization with IMDRF guidelines to streamline import pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic-assisted system development as force-feedback instrumentation and autonomous vessel mapping algorithms demand specialized electromechanical engineering talent pools. Long-term viability across the projection horizon favors acquisition targets with pre-existing regulatory affairs infrastructure and ISO 13485 certification velocity rather than pure technology plays. Monitor EU MDR notified body capacity constraints as the inflection signal for certification timeline compression and competitive access dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Accelerated notified body engagement compresses vendor qualification timelines for electromechanical platforms. |
| Hospital System Partnership | Bundled perfusion workflow contracts across German networks capture cath lab and OR capital allocation decisions. |
| Software Companion Development | Autonomous vessel mapping algorithms integrated with robotic platforms reduce operator-dependent variability in high-volume centers. |
| Reimbursement Strategy | PMDA shonin pathway navigation for fluorescence-guided systems secures Japan's stringent coverage determination advantages. |
| Backward Integration into Sterilization Services | Captive validation infrastructure insulates margin structures from EU MDR technical documentation cost inflation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, PMDA shonin approval records, and hospital procurement contract repositories. Bottom-up installed base modeling triangulated against top-down coronary artery bypass grafting volume projections.
Across the analysis window, the forecasting framework segmented by product architecture, energy modality, clinical indication, and care setting, with CAGRs derived from replacement cycle dynamics and procedural volume trajectories. Fluorescence-guided technology adoption curves and robotic-assisted system penetration rates served as industry-specific forecast inputs alongside carbon dioxide insufflation supply elasticity assumptions.
Material uncertainties — EU MDR notified body capacity constraints, carbon dioxide insufflation supply volatility, and PMDA reimbursement determination shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline compression and procedural volume stability. Recalibration cycles align with material shifts in MDR implementation velocity and Japan's electromechanical platform coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopy Device Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Colonic Stents Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Endoscope Washer Disinfector Market