
 Lavage Kits Market | 2026-2036
Lavage Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Lavage Kits Market Foresight
Single-use sterility assurance is reorganizing competitive dynamics in lavage kit supply. Stryker Corporation leverages integrated operating room workflows to sustain premium positioning across automated lavage systems. Smith & Nephew anchors its market presence through wound care specialization that extends into lavage kit co-procurement contracts.
Lavage kits are sterile fluid delivery and aspiration assemblies comprising irrigation tubing, collection canisters, and suction control mechanisms, typically manufactured from medical-grade PVC or silicone with particulate filtration thresholds calibrated to surgical field requirements; their primary purpose is to cleanse operative sites and remove debris during open or arthroscopic procedures. Automated systems command the dominant revenue share due to capital equipment attachment and recurring consumable pull-through, while single-use kits represent the fastest-expanding segment as hospitals phase out reprocessing-dependent inventory. Specialty kits targeting orthopedic lavage capture concentrated margin pools through procedure-specific customization and surgeon preference loyalty.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern lavage kit commercialization in the United States, with sterilization validation protocols under 21 CFR Part 820 directly influencing product design decisions and manufacturing location choices. The EPA's oversight of ethylene oxide sterilization facilities has tightened capacity for terminal sterilization services, accelerating manufacturer migration to gamma-irradiated or e-beam alternatives. Stakeholders must monitor evolving state-level surgical site infection reporting mandates that increasingly tie reimbursement to lavage protocol compliance.
Market Dynamics
Single-use sterility protocols are compressing reusable device economics across hospital supply chains, forcing capital equipment manufacturers to reconceptualize attachment strategies for consumable pull-through revenue.
Growth Catalysts
- FDA sterilization validation:Updated 21 CFR Part 820 requirements for reusable medical devices are accelerating hospital procurement of disposable lavage kits to eliminate reprocessing liability and compliance documentation burdens.
- Ambulatory surgical center expansion:United States outpatient procedure volumes are concentrating demand for compact, single-use lavage systems that minimize facility infrastructure investment and turnover time between cases.
- Orthopedic procedure specialization:Arthroscopic lavage protocols for joint irrigation are driving procedure-specific kit customization that commands premium positioning through surgeon preference loyalty and outcome-linked procurement.
Market Restraints
- Ethylene oxide sterilization capacity:EPA facility oversight has constrained terminal sterilization service availability, creating supply bottlenecks for manufacturers dependent on EtO terminal sterilization of porous polymer components.
- Medical-grade PVC resin concentration:Feedstock supply concentrates among Asian petrochemical producers, exposing kit manufacturers to input cost volatility and freight disruption risk across Pacific shipping lanes.
- Manual lavage system substitution:Low-cost gravity-fed irrigation alternatives continue displacing automated suction-control systems in price-sensitive emerging market hospital segments.
Strategic Opportunities
- India hospital infrastructure:Government medical device manufacturing incentives under the PLI scheme are attracting contract sterilization investment that enables localized kit production for South Asian distribution.
- Wound care convergence:Negative pressure wound therapy integration with lavage aspiration is creating combined modality systems that capture expanded reimbursement codes in post-acute care settings.
- E-beam sterilization adoption:Gamma irradiation alternatives are opening facility location flexibility for manufacturers seeking to decouple from ethylene oxide sterilization network constraints.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new polymer formulations extend product development cycles by 12-18 months before FDA 510(k) submission.
- Legacy suction pump interoperability:Automated lavage kit connectivity standards vary across installed capital equipment bases, forcing manufacturers to maintain multiple tubing connector configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lavage Kits Market |
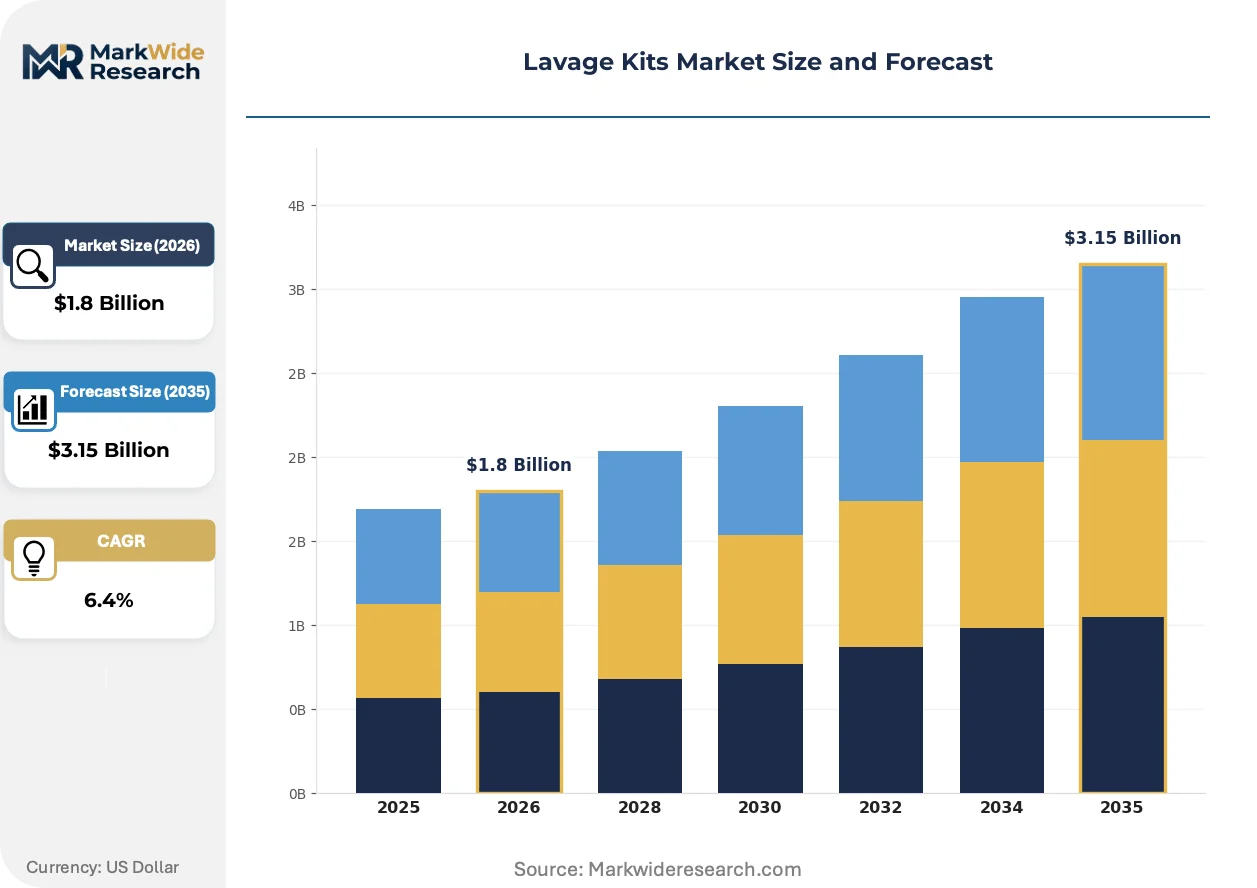
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Kits, Automated Systems, Specialty Kits, Single-Use Kits End User: Hospitals, Clinicians, Emergency Services, Outpatient Facilities Application: Wound Care, Surgical Procedures, Infection Control, Diagnostic Testing Packaging Type: Bulk Packaging, Individual Kits, Sterile Kits, Custom Packaging |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Smith & Nephew, Mölnlycke Health Care AB, Heraeus Holding GmbH, MicroAire Surgical Instruments, Judd Medical Limited, De Soutter Medical Limited, ConMed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lavage Kits Market Shifts & Advancements
Fluid management technology is bifurcating between closed-loop automated systems and simplified single-use assemblies, with regulatory sterilization mandates acting as the decisive selection mechanism across procurement categories.
Closed-circuit suction-irrigation systems with integrated particulate filtration are fragmenting traditional open-basin lavage protocols in orthopedic and spinal surgery suites. Tertiary hospitals in the United States are adopting these systems at accelerating replacement cycles to satisfy Joint Commission surgical site infection surveillance requirements. The technology is fragmenting capital equipment vendor relationships as hospitals demand cross-compatible consumable sourcing rather than locked proprietary attachments.
EPA enforcement actions against ethylene oxide sterilization facilities are compressing terminal sterilization capacity for porous medical devices across the United States. Manufacturers are responding with accelerated validation of gamma irradiation and electron beam alternatives for polymer-based lavage kit components. Single-use kit producers with established e-beam sterilization partnerships are capturing procurement preference from hospitals seeking supply security.
Surgeon preference cards are consolidating lavage kit specifications within integrated delivery networks to standardize operative workflows and reduce nursing inventory burden. Group purchasing organizations are displacing individual hospital contracting autonomy with formulary lock agreements that specify approved kit configurations. This concentration is most visible in United States multi-hospital systems where supply chain rationalization targets 15-20% consumable cost reduction across standardized procedure categories.
Lavage Kits Market Segmentation
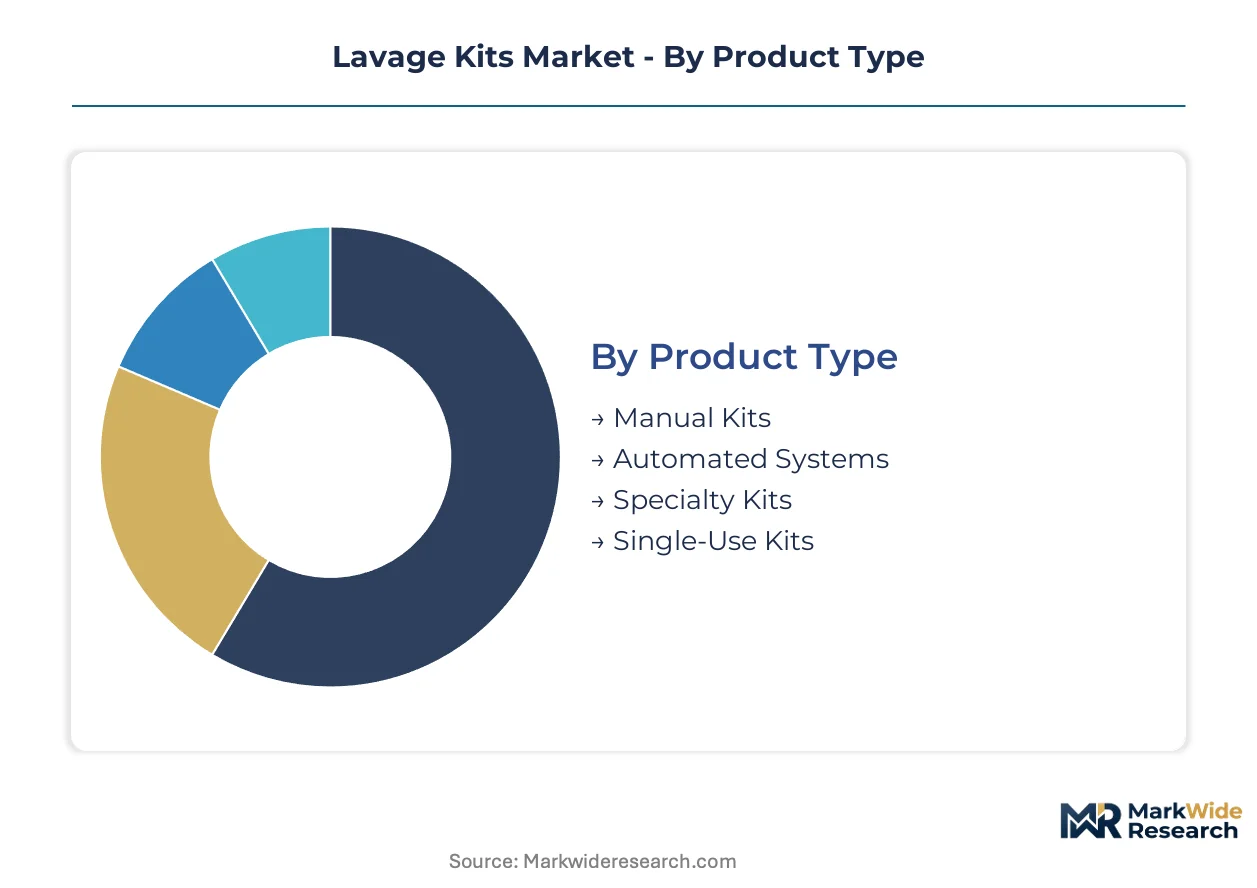
Lavage kit procurement channels diverge sharply by product complexity and sterility assurance requirements. Automated systems flow through capital equipment distributors with service contracts, while single-use kits penetrate group purchasing organization formularies. Understanding these channel dynamics reveals where margin pools concentrate and where volume expansion accelerates.
Product Type:
Channel strategy splits between capital-intensive automated platforms and consumable-driven disposable kits, with distribution partnerships determining market access speed.
- Automated Systems:Closed-loop suction-irrigation platforms integrate particulate filtration and pressure modulation for orthopedic and spinal suites. United States tertiary hospitals concentrate procurement here to satisfy Joint Commission surgical site infection surveillance mandates.
- Single-Use Kits:Pre-sterilized disposable assemblies eliminate reprocessing documentation burdens under FDA 21 CFR Part 820. Ambulatory surgical centers in the United States drive fastest adoption as outpatient arthroscopic volumes climb.
- Manual Kits:Gravity-fed irrigation assemblies with basic tubing and collection canisters serve price-sensitive procurement tiers.
- Specialty Kits:Procedure-specific configurations target orthopedic lavage with surgeon-customized component arrays.
By volume, Single-Use Kits leads. By growth pace, Automated Systems is ahead.
End User:
Customer concentration varies by reimbursement structure and capital availability, with facility scale dictating kit complexity preferences.
- Hospitals:Integrated delivery networks standardize lavage protocols across surgical service lines to reduce nursing inventory burden. United States multi-hospital systems capture procurement economies through formulary lock agreements.
- Outpatient Facilities:Ambulatory surgical centers prioritize compact single-use systems minimizing infrastructure investment and turnover time. United States outpatient procedure volume expansion concentrates demand here.
- Clinicians:Individual practice settings drive small-volume procurement of manual kits for office-based wound irrigation.
- Emergency Services:Pre-hospital and trauma bay applications require rapid-deployment sterile kits with minimal setup protocols.
By revenue concentration, Hospitals dominates. By expansion trajectory, Outpatient Facilities gains share fastest.
Application:
Clinical use case determines sterility grade requirements and filtration specifications, with orthopedic and wound protocols commanding premium positioning.
- Surgical Procedures:Arthroscopic joint irrigation and open operative site cleansing demand closed-circuit systems with calibrated particulate thresholds. United States orthopedic surgery volumes sustain premium kit procurement.
- Wound Care:Negative pressure wound therapy integration with lavage aspiration creates combined modality systems capturing expanded reimbursement codes in post-acute settings.
- Infection Control:Prophylactic irrigation protocols in contaminated trauma cases drive standardized kit deployment across emergency departments.
- Diagnostic Testing:Laboratory and pathology applications utilize lavage fluid collection for cytological analysis with specialized filtration requirements.
By procedure volume, Surgical Procedures leads. By reimbursement expansion, Wound Care climbs the fastest.
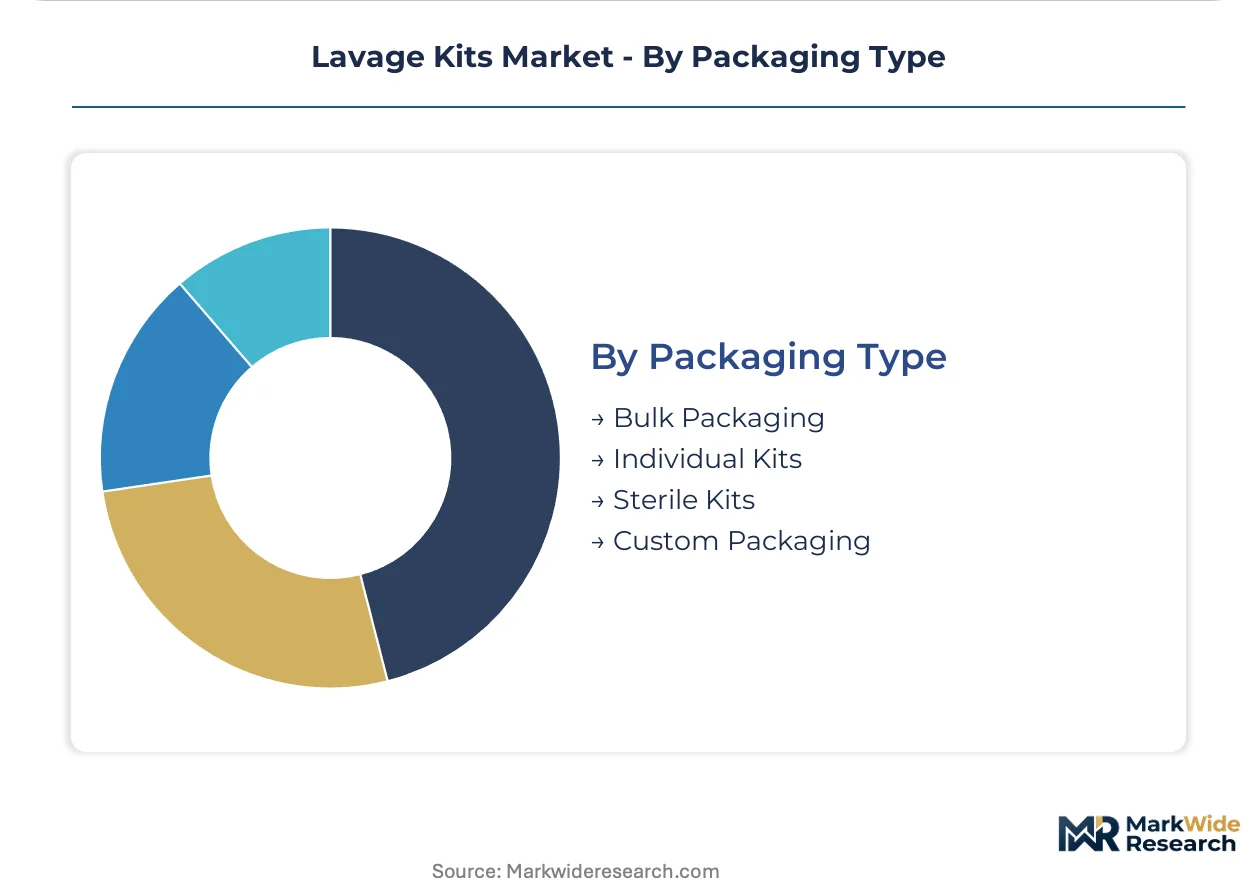
Packaging Type:
Packaging configuration aligns with inventory management strategy and sterility assurance level, with terminal sterilization method influencing material selection.
- Sterile Kits:Terminal sterilized assemblies using gamma irradiation or e-beam alternatives bypass ethylene oxide capacity constraints. Manufacturers with validated non-EtO partnerships capture procurement preference from supply-security-focused buyers.
- Individual Kits:Unit-of-use packaging reduces nursing preparation time and supports just-in-time inventory models in high-turnover surgical environments.
- Bulk Packaging:Multi-unit cases serve central sterile processing departments with established reprocessing infrastructure.
- Custom Packaging:Surgeon preference card-aligned configurations consolidate component specifications within integrated delivery networks.
By procurement standardization, Sterile Kits leads. By customization demand, Custom Packaging expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss lavage kit manufacturers export precision surgical assemblies to United States hospital systems, while Chinese contract sterilizers supply gamma-irradiated components to Southeast Asian distributors.
United States
Ambulatory surgical centers in Texas and Florida drive single-use kit procurement as outpatient arthroscopic volumes climb. FDA 21 CFR Part 820 sterilization validation requirements pressure hospitals to eliminate reusable device reprocessing. The Minneapolis-Saint Paul corridor hosts automated lavage system engineering clusters serving integrated delivery networks.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia standardize closed-circuit suction-irrigation protocols for orthopedic suites. EU MDR compliance timelines accelerate documentation burdens for reusable device manufacturers. The Stuttgart region concentrates precision tubing fabrication for export-oriented kit assemblers.
China
Domestic hospital procurement shifts toward single-use kits as provincial health commissions tighten surgical site infection reporting. NMPA medical device registration reforms compress approval timelines for gamma-sterilized polymer assemblies. The Yangtze River Delta hosts contract sterilization capacity serving both domestic and export markets.
India
Government hospital infrastructure expansion under the PLI scheme attracts lavage kit manufacturing investment for South Asian distribution. CDSCO medical device rules harmonize with ISO 13485 standards for import substitution. Tamil Nadu and Karnataka medical device parks incubate localized sterilization validation capabilities.
Japan
Aging demographics sustain orthopedic procedure volumes requiring specialized joint irrigation systems. PMDA quality management system inspections enforce rigorous biocompatibility documentation for polymer components. The Osaka-Kobe manufacturing belt concentrates precision medical tubing production for domestic and regional supply.
Lavage Kits Market Competitive Landscape
Listed leaders compete with private specialists across sterilization technology and distribution reach. The vendor base splits between capital equipment conglomerates with automated system portfolios and disposable-focused specialists with single-use kit expertise. Three archetypes dominate: integrated surgical workflow providers, wound care convergence specialists, and contract manufacturing aggregators. Competitive moves center on sterilization partnership restructuring and GPO formulary lock agreements.
Among United States-based diversified medical technology corporations, Stryker Corporation and ConMed Corporation exemplify the integrated surgical workflow archetype through capital equipment attachment strategies. Smith & Nephew represents the wound care convergence specialist model, leveraging negative pressure therapy integration. Zimmer Biomet Holdings occupies a position within the orthopedic procedure-specific customization tier. German industrial conglomerate Heraeus Holding GmbH anchors the precision component supply archetype. Mölnlycke Health Care AB exemplifies the single-use sterile kit specialist model with established e-beam sterilization partnerships.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Smith & Nephew |
| Mölnlycke Health Care AB |
| Heraeus Holding GmbH |
| MicroAire Surgical Instruments |
| Judd Medical Limited |
| De Soutter Medical Limited |
| ConMed Corporation |
| Others |
Supply & Pricing Matrix
Gamma irradiation substitution for ethylene oxide sterilization simultaneously shifts contract sterilization geography toward Southeast Asian hubs and compresses terminal processing cost premiums for single-use lavage kit manufacturers. This dual restructuring rewards early e-beam validators with procurement preference while penalizing EtO-dependent suppliers facing EPA-constrained capacity.
Pricing Analysis
Automated suction-irrigation platforms command three-to-five-fold premiums over gravity-fed manual kits, with next-generation closed-loop filtration systems targeting additional surgeon-preference premiums. Pricing stratifies across premium automated systems, standard single-use disposable kits, and economy manual assemblies, with differentiation anchored in FDA 510(k) clearance tier and Joint Commission compliance bundling. Cost compression in the manual kit tier is intensifying because Asian contract manufacturers are expanding gamma-sterilized output for price-sensitive emerging market procurement. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint and procedure volume volatility, while United States tertiary hospitals demonstrate lowest sensitivity given outcome-linked reimbursement structures.
Supply Chain Analysis
Pacific container availability fluctuations and Los Angeles-Long Beach port congestion cycles directly inflate inbound logistics costs for medical-grade PVC resin shipments from Chinese and South Korean petrochemical producers. Kit manufacturing concentrates in China, Malaysia, and Costa Rica, with final assembly drawing from Taiwanese precision tubing and German filtration membrane inputs. Supply chain risk centers on single-source vulnerability for gamma irradiation cobalt-60 sourcing from Canadian and Russian mining operations. Distribution runs through capital equipment distributors for automated platforms and group purchasing organization formularies for single-use consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lavage kit market sits in a post-regulatory-shock recovery phase, with FDA sterilization validation mandates driving cyclical replacement demand as hospitals phase out reusable device inventory.
For Market Incumbents: Compound sterilization partnership diversification by validating e-beam alternatives across multiple contract facilities in Southeast Asia and Eastern Europe. Deepen backward integration into medical-grade polymer compounding to offset PVC resin price volatility from Asian petrochemical suppliers. Lock group purchasing organization formulary positions through surgeon preference card standardization before emerging competitors establish credentialing relationships.
For New Entrants and Emerging Players: Anchor in the Indian hospital infrastructure expansion under PLI scheme incentives, where localized gamma sterilization capacity incubates import-substitution opportunities for domestic kit assembly. Target negative pressure wound therapy convergence applications in United States post-acute care settings, where reimbursement code expansion creates penetrable white space outside incumbent orthopedic strongholds. Pursue hospital system partnership models that bundle lavage kit supply with capital equipment service contracts.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors single-use sterile kit specialists with established non-EtO sterilization partnerships and GPO contract density. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone, privileging targets with validated ISO 13485 quality systems and FDA submission track records. Monitor EPA enforcement actions against ethylene oxide facilities as the critical inflection signal for supply-constraint-driven valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| E-beam Sterilization Validation | Decouples manufacturing from EPA-constrained ethylene oxide terminal sterilization capacity. |
| Surgeon Preference Card Standardization | Locks integrated delivery network formulary positions through nursing workflow consolidation. |
| Negative Pressure Wound Therapy Integration | Captures expanded reimbursement codes in post-acute care settings beyond surgical suites. |
| Indian PLI Scheme Manufacturing Localization | Establishes South Asian distribution hub with CDSCO-aligned regulatory infrastructure. |
| Group Purchasing Organization Formulary Lock | Displaces hospital-level contracting autonomy with multi-system procurement economies. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineering directors, ambulatory surgical center administrators, and group purchasing organization contracts managers anchored the qualitative base for this analysis. Primary interview insights were cross-validated against FDA 510(k) submission databases, hospital procurement expenditure records, EPA sterilization facility inspection reports, and ISO 13485 certification registries. Bottom-up demand modeling across end-user segments was triangulated with top-down market sizing from trade flow and customs data.
Sensitivity analysis tested volume and value projections across the modeling period against sterilization capacity constraints, resin price volatility scenarios, and regulatory enforcement intensity variations. Segmentation dimensions modeled include product complexity tier, end-user facility scale, application-specific sterility requirements, and regional regulatory cluster. CAGRs were derived from procedure volume trend extrapolation, replacement cycle analysis, and penetration rate assumptions for automated versus manual system substitution. Industry-specific forecast inputs incorporated orthopedic surgery volume trajectories and ambulatory surgical center construction pipelines.
Material uncertainties — EPA ethylene oxide facility enforcement escalations, medical-grade PVC supply disruptions, and Joint Commission protocol revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding sterilization technology migration timelines and hospital capital expenditure recovery patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Amniotic Products Market