
 Display Fingerprint Technology Market | 2026-2036
Display Fingerprint Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Display Fingerprint Technology Market Analysis
Automotive cockpit digitization is expanding as a demand vector for display-integrated fingerprint modules, with luxury OEMs embedding biometric ignition and personalization systems. Shenzhen Goodix Technology leverages its optical sensor portfolio to anchor supply relationships with Chinese EV brands. Qualcomm Technologies sustains ultrasonic R&D intensity through its 3D Sonic platform, while Synaptics Incorporated competes across capacitive and optical architectures for tier-one smartphone accounts.
Display fingerprint technology embeds biometric authentication sensors beneath or within electronic display panels, typically using optical imaging arrays at 400-800 ppi resolution or piezoelectric ultrasonic transducers to capture ridge-valley patterns through cover glass. The technology enables seamless user verification without dedicated physical buttons, serving consumer electronics, automotive HMI, and enterprise access control systems. Optical technology dominates unit shipments in smartphones due to mature supply chains and cost structures, while ultrasonic approaches capture premium-tier margin pools through superior spoof resistance and wet-finger performance. Automotive applications represent the fastest-growing demand category as dashboard consolidation eliminates discrete control surfaces.
FDA guidelines for biometric data in healthcare devices, China's MIIT cybersecurity standards for personal information protection, and the EU's GDPR data processing rules collectively shape product design and market access requirements across major economies. These frameworks mandate encryption, local processing, and user consent architectures that increase engineering overhead but create compliance-based differentiation. Stakeholders must monitor evolving automotive safety regulations and cross-border data flow restrictions as deployment scales beyond consumer electronics into connected vehicle and medical device ecosystems.
Market Dynamics
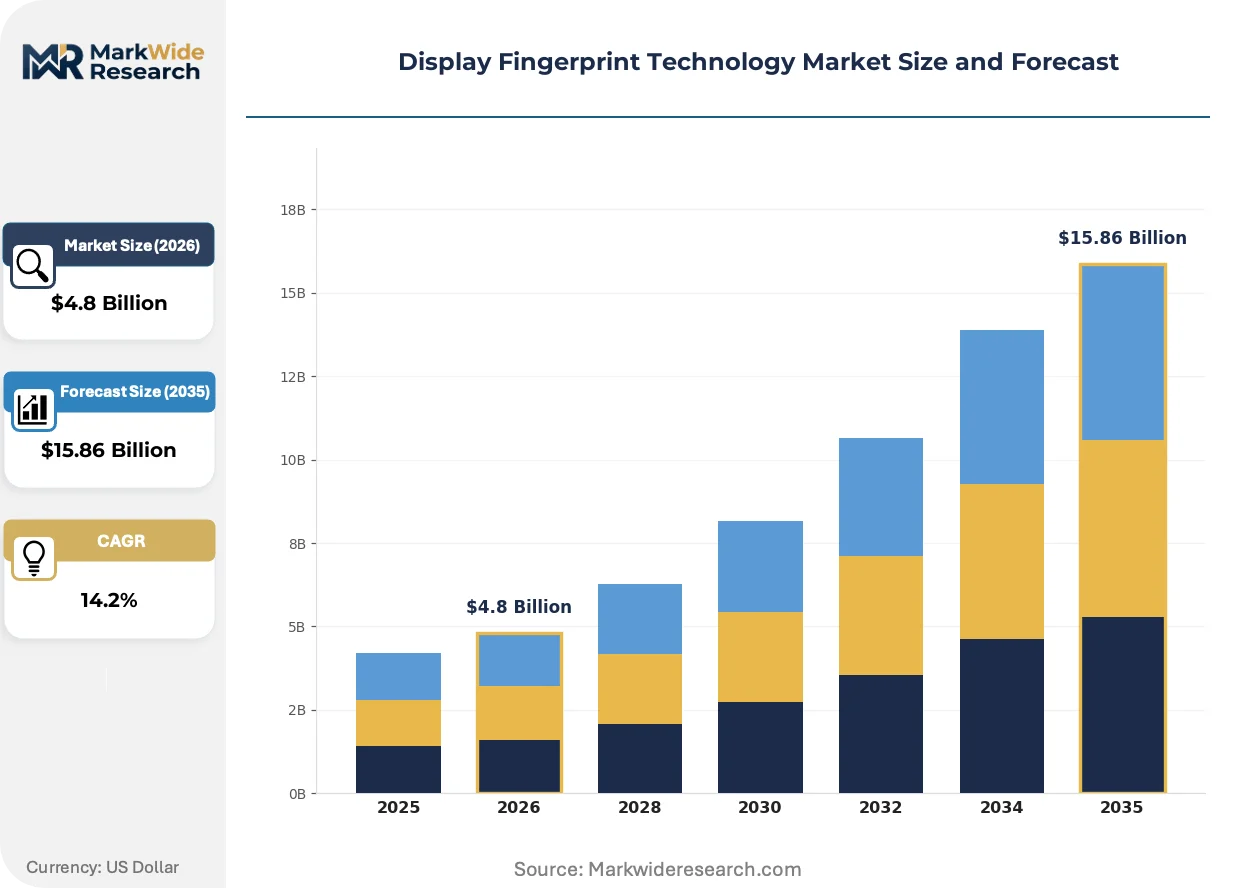
Smartphone OEMs in Asia-Pacific are accelerating the retirement of capacitive home buttons, forcing sensor suppliers to reconfigure fabrication lines around under-display optical and ultrasonic architectures while automotive cockpit consolidation creates parallel demand for dashboard-integrated biometric modules.
Growth Catalysts
- China MIIT Cybersecurity Standards:Mandatory encryption and local processing requirements for biometric data protection are compelling smartphone manufacturers to upgrade authentication hardware, creating replacement demand across installed bases.
- Automotive HMI Consolidation:Luxury EV brands are embedding fingerprint-enabled ignition and driver personalization systems as physical keys and buttons disappear from vehicle interiors.
- Optical Sensor Maturation:Shenzhen-based fabs have achieved 400-800 ppi resolution at mass-production yields, compressing cost structures for mid-tier smartphone adoption.
Market Restraints
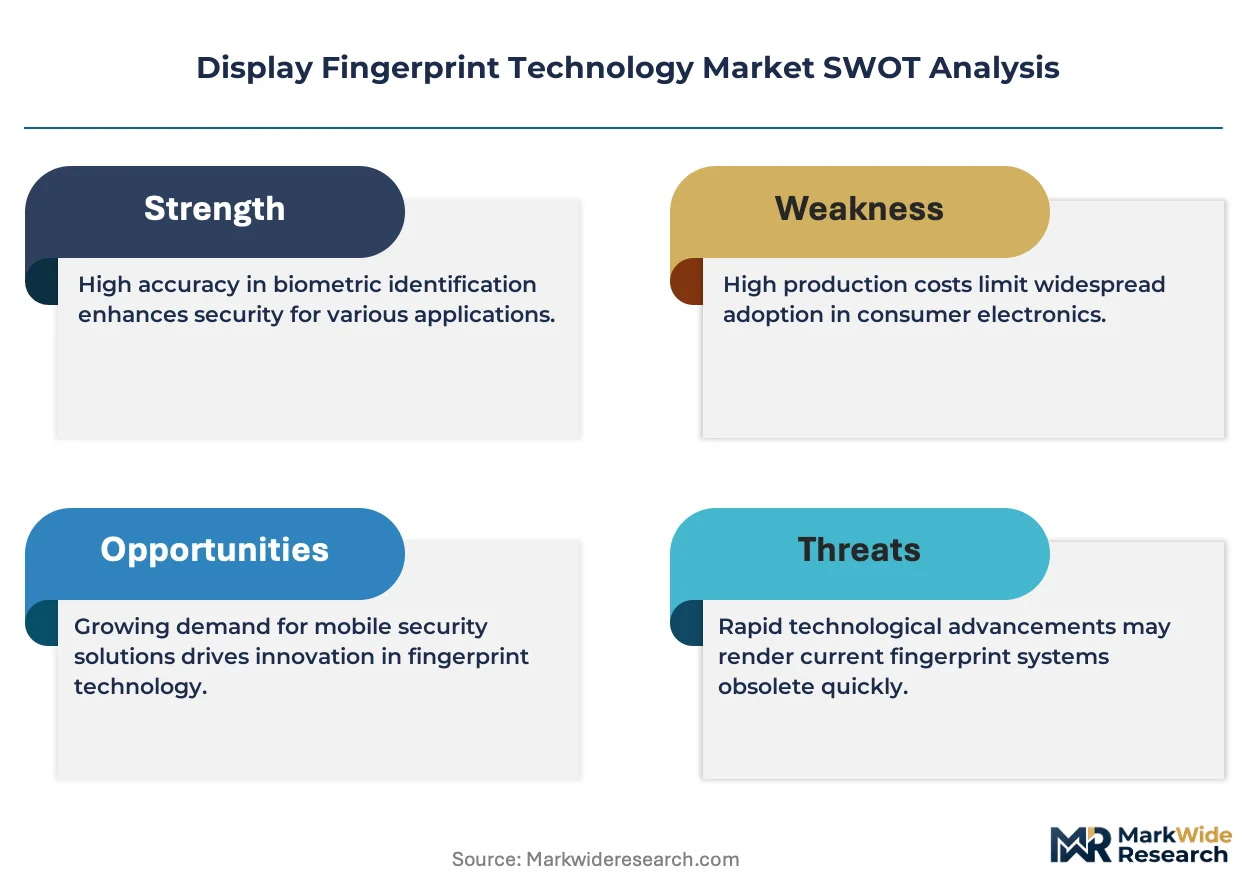
- Ultrasonic Transducer Cost Volatility:Piezoelectric materials and precision MEMS fabrication remain 3-4x more expensive than optical alternatives, constraining deployment to premium price tiers.
- Guangdong Supply Concentration:Over 70% of optical sensor module assembly clusters in Shenzhen and Dongguan, exposing buyers to single-province disruption risks from power rationing or logistics constraints.
- Wet-Finger Performance Limitations:Optical arrays suffer recognition failures with moisture or contamination, forcing ultrasonic retention in applications requiring environmental resilience.
Strategic Opportunities
- India PLI Scheme Incentives:Production-linked incentives for electronics manufacturing are attracting sensor module integrators to establish captive capacity outside China.
- Healthcare Device Integration:FDA guidelines for biometric data in clinical settings are opening design-in opportunities for patient identification and medication dispensing systems.
- Ultrasonic-Optical Convergence:Hybrid architectures combining optical speed with ultrasonic spoof resistance are emerging for enterprise access control applications requiring both throughput and security.
Industry Challenges
- Biometric Algorithm Engineering Talent Scarcity:Shortage of specialists in ridge-pattern recognition and liveness detection is extending R&D timelines for tier-two suppliers.
- Cross-Border Certification Complexity:Divergent encryption standards between China's MIIT, EU GDPR, and US FDA frameworks force redundant testing cycles for multi-region product launches.
- Automotive Safety Validation Burden:Functional safety requirements for dashboard-integrated sensors under ISO 26262 are imposing 18-24 month qualification periods unfamiliar to consumer electronics suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Fingerprint Technology Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Capacitive, Optical, Ultrasonic, Thermal Application: Smartphones, Laptops, Wearables, Automotive End User: Consumers, Enterprises, Government, Healthcare Integration Level: Built-in, Add-on, Embedded, Custom Solutions |
| Companies Covered | Synaptics Incorporated, Shenzhen Goodix Technology, Qualcomm Technologies, Fingerprint Cards, Egis Technology, NEC Corporation, Apple, Samsung Electronics, IDEX Biometrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Fingerprint Technology Market Emerging Trajectories
Sensor architectures are bifurcating between cost-optimized optical dominance in smartphones and performance-driven ultrasonic expansion into automotive and healthcare verticals, while regulatory fragmentation forces modular compliance designs.
Ultrasonic 3D sensing is electrifying authentication reliability by capturing sub-surface ridge patterns through cover glass using piezoelectric transducer arrays. Automotive OEMs are adopting this technology for biometric ignition systems at triple-digit annual rates. The shift is electrifying premium-tier margin pools while compressing optical sensor pricing power in adjacent segments.
GDPR data processing rules and China's MIIT personal information protection standards are mandating on-device encryption and consent architectures. Component suppliers must integrate secure enclaves and local processing capabilities into sensor modules. Smartphone manufacturers targeting EU and China markets are responding with dual-certification hardware platforms to avoid market exclusion.
Fleet procurement of biometric access systems is displacing individual unit sales in enterprise and shared-mobility segments. Corporate IT and automotive fleet managers are consolidating vendor relationships around multi-year service agreements with integrated hardware-software support. This pattern is most visible in Germany and Japan where workplace security standardization and corporate car leasing penetration are highest.
Display Fingerprint Technology Market Segmentation
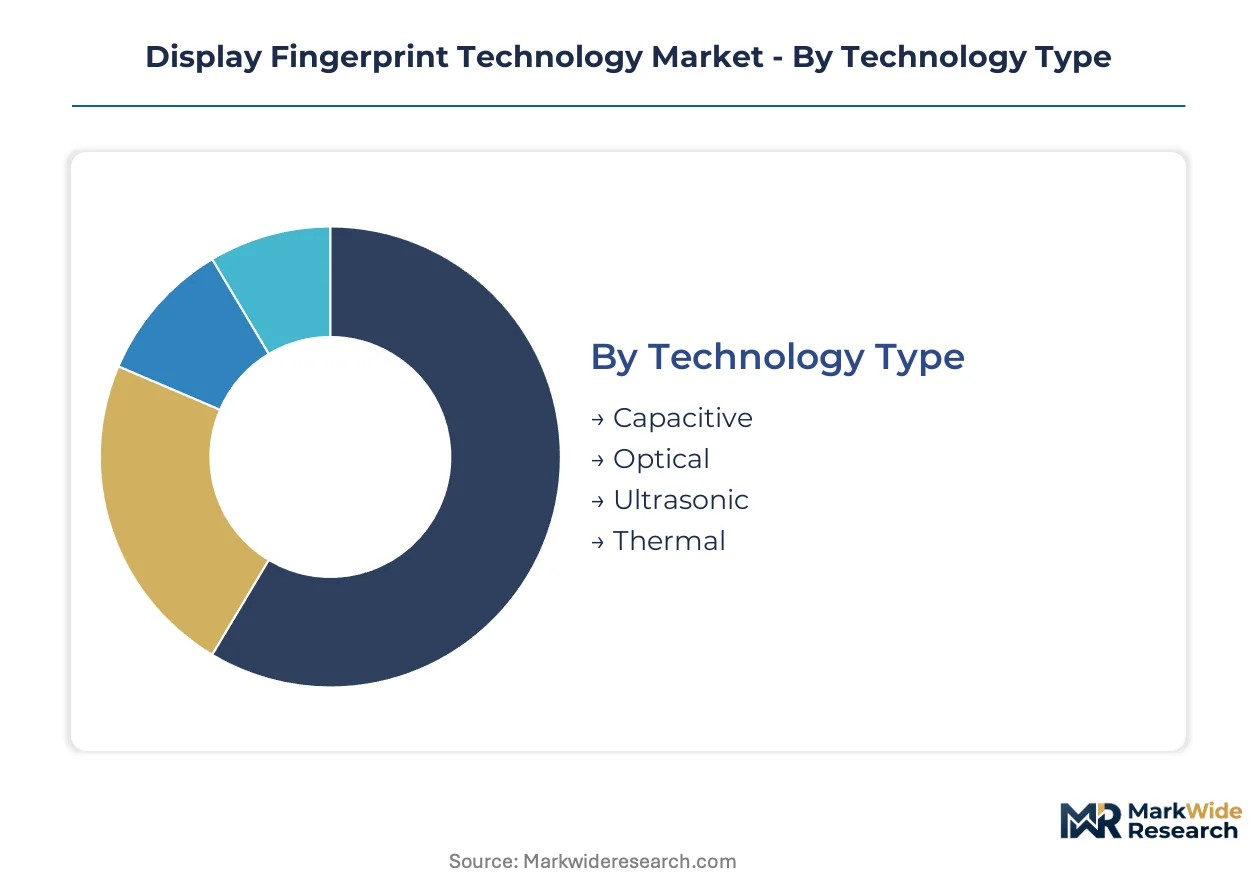
Display fingerprint technology segments along four critical dimensions that determine engineering requirements, certification burdens, and margin structures. Each segmentation axis reveals distinct upgrade cycles and competitive dynamics shaping supplier strategy across consumer electronics, automotive, and enterprise verticals.
Technology Type:
Upgrade cycles in smartphone authentication hardware are forcing sensor suppliers to reconfigure fabrication lines around under-display architectures while legacy capacitive capacity retools or exits.
- Optical:CMOS imaging arrays at 400-800 ppi resolution capture ridge patterns through OLED cover glass using reflected light. Mass-production yields at Shenzhen fabs have compressed unit costs, anchoring supply relationships with mid-tier smartphone OEMs across China and India. Optical dominates unit shipments but faces margin compression from commoditization.
- Ultrasonic:Piezoelectric transducer arrays emit acoustic pulses to map sub-surface fingerprint topography through glass, metal, or plastic substrates. Qualcomm's 3D Sonic platform sustains R&D intensity here. Demand concentrates in premium-tier smartphones and automotive biometric ignition systems where wet-finger reliability and spoof resistance command price premiums.
- Capacitive:Electrode arrays measuring ridge-valley capacitance differentials dominated pre-under-display smartphone designs. Retreating to low-cost feature phones, industrial handhelds, and legacy device replacement markets as OEMs retire home-button form factors.
- Thermal:Pyroelectric sensors detecting heat differential between ridges and air gaps occupies niche applications in cold-climate industrial access control and specialized medical device authentication where optical interference from sterilants occurs.
Volume placements concentrate in Optical; the faster expansion belongs to Ultrasonic.
Application:
Cost tier stratification separates premium automotive and enterprise deployments from mass-market consumer electronics where sensor ASPs face relentless downward pressure.
- Smartphones:Under-display integration in OLED and AMOLED panels represents the volume anchor for optical and ultrasonic suppliers. China's MIIT cybersecurity standards and EU GDPR mandates are compelling hardware upgrades across installed bases, creating replacement demand even in saturated markets.
- Automotive:Dashboard-integrated biometric modules enable keyless ignition and driver profile personalization as physical controls disappear from luxury EV interiors. ISO 26262 functional safety requirements impose 18-24 month qualification periods unfamiliar to consumer electronics suppliers, filtering participant pools.
- Laptops:Power-button integration and trackpad-embedded sensors serve enterprise security policies requiring multi-factor authentication. Microsoft's Windows Hello certification programs shape hardware specifications for PC OEMs targeting corporate procurement channels.
- Wearables:Miniaturized optical sensors in smartwatches and fitness bands support payment authentication and health data access control. Battery constraints and form-factor limitations favor low-power optical architectures over ultrasonic alternatives.
Smartphone volumes dwarf adjacent categories; Automotive climbs the fastest as cockpit digitization accelerates.
End User:
Customer type determines encryption requirements, procurement patterns, and support infrastructure intensity across deployment scenarios.
- Consumers:Individual purchasers through retail channels drive smartphone and wearable adoption. Price sensitivity favors optical sensors; brand cachet sustains ultrasonic penetration in flagship devices.
- Enterprises:Corporate IT departments consolidate fleet procurement around multi-year service agreements with integrated hardware-software support. Workplace security standardization in Germany and Japan concentrates demand for enterprise-grade biometric access systems.
- Government:National ID programs, border control systems, and secure facility access impose stringent liveness detection and anti-spoofing requirements. Certification timelines extend 12-18 months beyond commercial deployments.
- Healthcare:FDA guidelines for biometric data in clinical settings are opening design-in opportunities for patient identification and medication dispensing systems. Local processing mandates under HIPAA shape sensor architecture specifications.
Consumer placements anchor aggregate volumes; Healthcare gains share fastest as clinical digitization expands.
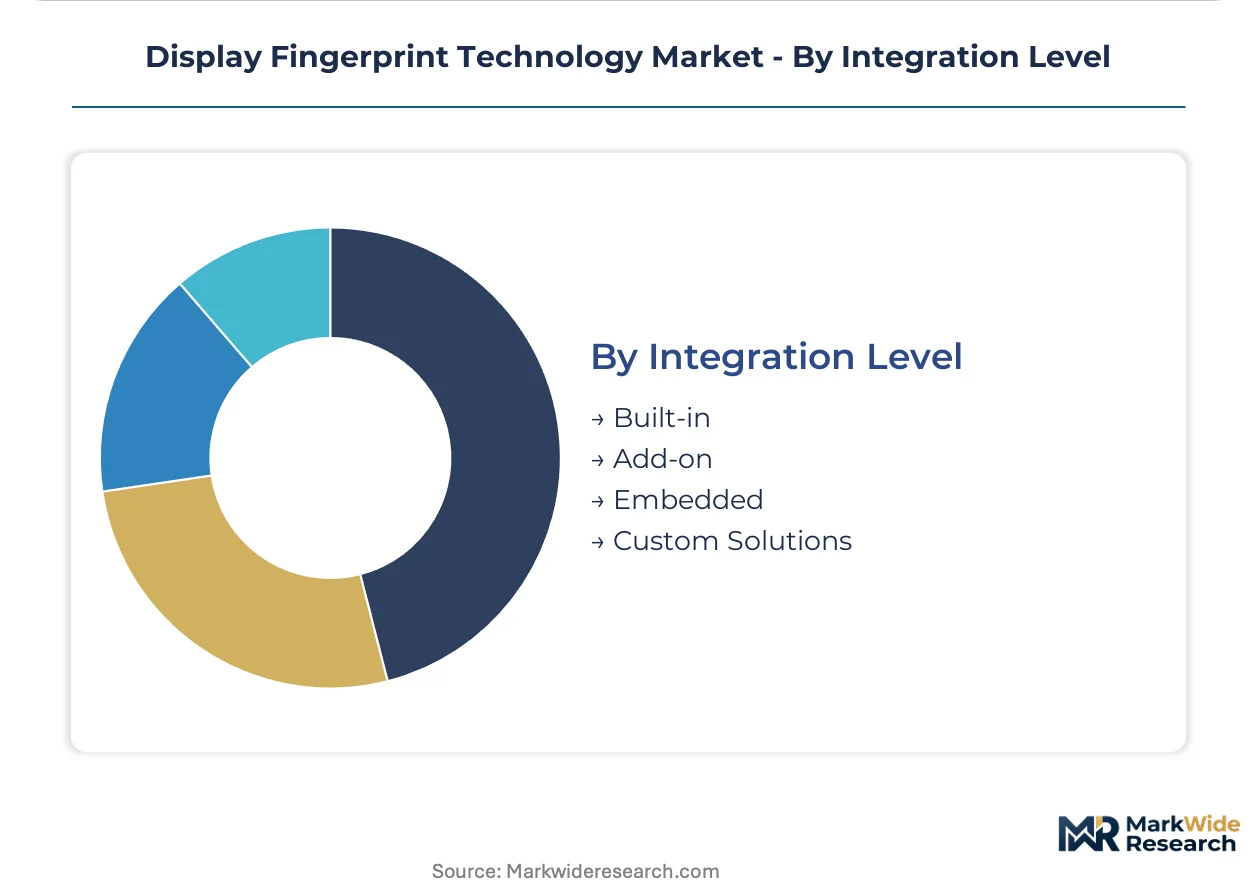
Integration Level:
Supply concentration in Guangdong module integrators shapes availability and lead time differentials across integration tiers.
- Embedded:Sensors fabricated directly into display driver ICs or cover glass during panel manufacturing enable thinnest device profiles. Shenzhen Goodix Technology anchors supply relationships with Chinese display fabs for this tier.
- Built-in:Pre-integrated sensor-display modules ship from panel manufacturers to device assemblers, reducing final assembly complexity. Dominates smartphone supply chains for tier-one OEMs.
- Add-on:External fingerprint readers connect via USB or Bluetooth for retrofit authentication on legacy devices. Serves enterprise IT refresh cycles and shared-workstation environments.
- Custom Solutions:Bespoke sensor architectures for specialized industrial, medical, or automotive applications requiring non-standard form factors, environmental sealing, or extended temperature ranges.
Built-in placements concentrate manufacturing volumes; Custom Solutions expands most quickly as automotive and healthcare verticals diverge from consumer electronics specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's Qianhai and Nansha special economic zones concentrate optical sensor module assembly, drawing Shenzhen-based fabs and Dongguan integrators through tax incentives and bonded logistics facilities.
China
Smartphone OEMs in Beijing and Shanghai are retiring capacitive home buttons at scale, compelling authentication hardware upgrades. MIIT cybersecurity standards mandate local processing and encryption for biometric data protection. Shenzhen hosts Goodix Technology and downstream module integrators serving domestic EV brands with dashboard-embedded sensors.
South Korea
Display panel manufacturers in Gyeonggi-do are integrating fingerprint sensors directly into OLED driver ICs for flagship smartphone lines. The country's personal information protection framework shapes encryption requirements for export-bound devices. Seoul-based electronics conglomerates anchor R&D partnerships with ultrasonic technology developers.
United States
Automotive OEMs in Michigan and California are embedding biometric ignition systems as cockpit digitization accelerates. FDA guidelines for biometric data in healthcare devices open design-in opportunities for patient identification systems. Austin and San Diego host fabless semiconductor developers focused on 3D sensing architectures.
Germany
Corporate fleet managers in Bavaria and Baden-Württemberg are consolidating biometric access procurement around multi-year service agreements. GDPR data processing rules mandate on-device encryption and user consent architectures. Stuttgart's automotive engineering cluster drives ISO 26262 functional safety validation for dashboard-integrated sensors.
India
Electronics manufacturing in Karnataka and Tamil Nadu is expanding through PLI scheme incentives attracting sensor module integrators. BIS certification requirements and data localization policies shape product specifications for domestic market entry. Noida and Chennai host assembly operations for mid-tier smartphone OEMs adopting optical under-display solutions.
Display Fingerprint Technology Market Vendor Landscape
Top-tier vendors anchor premium-tier smartphone and automotive deployments, while mid-tier specialists compete on cost-optimized optical architectures for mass-market handsets. The vendor base stratifies across three strategic archetypes: fabless semiconductor designers with ultrasonic IP, integrated module suppliers controlling Shenzhen fabrication, and diversified electronics conglomerates with captive display integration. Competitive moves concentrate on backward integration into MEMS fabrication and strategic partnerships with automotive Tier-1s for cockpit digitization programs.
Among Asia-Pacific-based module suppliers, Shenzhen Goodix Technology occupies a position within the integrated fabrication archetype, while Qualcomm Technologies exemplifies the fabless semiconductor model with its 3D Sonic platform. Synaptics Incorporated represents the diversified supplier category spanning multiple sensor architectures. These three anchors illustrate the competitive tension between cost-optimized optical dominance and performance-driven ultrasonic expansion into automotive verticals.
| Leading Market Players |
|---|
| Synaptics Incorporated |
| Shenzhen Goodix Technology |
| Qualcomm Technologies |
| Fingerprint Cards |
| Egis Technology |
| NEC Corporation |
| Apple |
| Samsung Electronics |
| IDEX Biometrics |
| Others |
Supply Flow & Price Mechanics
Captive integration into Shenzhen-based MEMS fabs anchors both supply security and margin retention for optical sensor suppliers serving mid-tier smartphone OEMs, while ultrasonic specialists without wafer-level packaging control face persistent cost disadvantages against vertically integrated rivals.
Pricing Analysis
Short lead-time premiums of 15-25% apply to rush orders from automotive Tier-1s facing ISO 26262 qualification deadlines, while spot inventory discounts emerge during Chinese New Year production lulls. Three-tier pricing structure across premium ultrasonic, standard optical, and economy capacitive tiers reflects certification grade and wet-finger performance differentials. Price erosion runs through optical mid-tier modules as Dongguan integrators add capacity. Enterprise fleet buyers show lowest price sensitivity due to multi-year service bundling; Indian PLI beneficiaries exhibit highest sensitivity as they absorb BIS certification costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Samsung Electronics and Apple, while distributor networks serve tier-two smartphone brands and industrial access control integrators. Geographic concentration centers on China, South Korea, and Taiwan for CMOS image sensors, piezoelectric materials, and OLED driver ICs respectively. Raw material dependencies include silicon wafers, lead zirconate titanate ceramics, and indium tin oxide coatings. Single-source vulnerability from Guangdong power rationing exposes 70% of optical module assembly. Distribution runs through Shenzhen bonded logistics zones to Noida and Chennai assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from MIIT cybersecurity compliance costs will force sub-scale module integrators to exit or sell, creating acquisition opportunities for survivors with captive encryption IP and local processing architectures.
For Market Incumbents: Anchor defensive positioning through backward integration into 400-800 ppi CMOS wafer production at Shenzhen fabs, eliminating margin leakage to merchant foundries. Secure automotive qualification pipelines early to lock out consumer electronics suppliers unfamiliar with ISO 26262 validation burdens. Threat of Qualcomm's 3D Sonic ultrasonic expansion into mid-tier smartphones demands preemptive optical performance roadmaps.
For New Entrants and Emerging Players: Begin with healthcare device integration as FDA guidelines for biometric patient identification create design-in openings outside saturated smartphone channels. Target India's PLI-subsidized assembly ecosystem for cost-competitive optical module production serving domestic smartphone brands. Go-to-market leverage rests on HIPAA-compliant local processing architectures absent from incumbent consumer electronics portfolios.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified semiconductor conglomerates seeking biometric authentication capabilities. Long-term viability favors suppliers with automotive safety certification infrastructure and healthcare regulatory relationships beyond cyclical smartphone replacement demand. Watch ultrasonic cost convergence with optical as the inflection signal for premium-tier share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Safety Certification | ISO 26262 validation opens dashboard-integrated sensor supply to luxury EV brands in Germany and China. |
| MEMS Fabrication Scale-Up | Captive piezoelectric transducer production at Shenzhen fabs reduces ultrasonic sensor cost disadvantage against optical alternatives. |
| Healthcare Regulatory Partnership | FDA 510(k) pathway alignment for patient identification systems creates clinical digitization revenue streams outside consumer electronics. |
| India PLI Manufacturing Footprint | BIS-certified module assembly in Tamil Nadu hedges Guangdong supply concentration risks for mid-tier smartphone OEMs. |
| Ultrasonic-Optical Hybrid Architecture | Enterprise access control adoption combines Qualcomm's spoof resistance with optical throughput for high-throughput security environments. |
Methodological Framework
Multi-period observation of sensor shipment volumes, fab utilization rates, and automotive qualification timelines anchored the trend analysis, supplemented by interviews with smartphone platform engineers, automotive Tier-1 procurement directors, biometric algorithm specialists, and healthcare device regulatory leads. Secondary validation drew from MIIT cybersecurity filings, FDA 510(k) submission databases, SEC semiconductor segment disclosures, and India PLI scheme beneficiary registries. Bottom-up module shipment aggregation triangulated against top-down display panel production estimates.
The input-output matrix framed demand as smartphone replacement cycles, automotive cockpit digitization rates, and healthcare clinical system upgrade waves against supply-side fab capacity, MEMS fabrication yields, and regional certification throughput. Segmentation dimensions modeled include technology type, application vertical, end-user category, and integration level. CAGRs derived from logistic diffusion curves fitted to adoption saturation points across consumer, enterprise, and government deployment scenarios. Industry-specific inputs incorporated OLED panel penetration rates and ultrasonic wet-finger performance benchmarks.
Underlying measurement precision varies by segment; smartphone volume estimates carry tighter precision than nascent automotive and healthcare deployment forecasts. Projections reflect assumptions regarding MIIT enforcement consistency, automotive safety validation timelines, and cross-border data flow regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
E-Paper Display Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Volumetric Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Electronic Display Market