
 Display Optical Film Market | 2026-2036
Display Optical Film Market Size, Share, and Industry Trends Forecast 2026-2036
Display Optical Film Market Analysis
The gap between premium and commodity optical film tiers is shifting from thickness tolerance to luminance efficiency and haze control specifications. Toray Industries leverages its polyester film vertical integration to sustain margin pools in high-end polarizer substrates. Nitto Denko dominates adhesive-layer technologies that bond polarizer films to display panels, while 3M competes through proprietary micro-replication optics for brightness enhancement films in premium notebooks and tablets.
Display optical film comprises thin polymer substrates engineered with precise refractive-index layering to manage light transmission, polarization, and diffusion across liquid-crystal and organic light-emitting diode screens, typically manufactured through multi-layer extrusion or solvent casting with thickness tolerances below two micrometers. Polarizer film anchors the largest value pool due to its irreplaceable role in LCD stacks, while anti-reflective coatings for automotive and medical displays represent the fastest-expanding application segment driven by readability requirements in high-ambient-light environments. Diffuser film maintains steady volume in television backlight units though margin compression intensifies as Chinese suppliers expand casting capacity.
The US EPA regulates perfluorinated compounds in optical coating chemistries, while REACH in Europe restricts phthalate plasticizers common in legacy adhesive formulations, forcing reformulation investments across Korean and Japanese suppliers. China's SAMR enforces GB standards for display energy efficiency that indirectly specify minimum transmittance thresholds for optical films used in domestic television and monitor production. Stakeholders must monitor how evolving dual carbon goals in China and extended producer responsibility frameworks in Europe reshape material selection and recycling infrastructure requirements for multi-layer film constructions.
Market Dynamics
Automotive OEMs are reshaping procurement specifications for curved dashboard displays, forcing polarizer and anti-reflective film suppliers to recalibrate thickness tolerances and haze metrics for non-planar substrate bonding.
Growth Catalysts
- Automotive display proliferation:Tier-1 suppliers are scaling anti-reflective film orders for curved instrument clusters and center-stack screens. Dashboard integration demands films with sub-2% haze and controlled birefringence.
- EU RoHS substance restrictions:Phased cadmium and lead limitations in coating chemistries are accelerating reformulation toward halogen-free adhesive layers. Korean and Japanese suppliers are retooling solvent casting lines to maintain EU market access.
- OLED panel expansion:Circular polarizer film stacks are penetrating premium television and tablet segments. Display makers in Gyeonggi-do are expanding multi-layer extrusion capacity for thin-film encapsulation compatibility.
Market Restraints
- Petrochemical input volatility:Polyester substrate costs fluctuate with purified terephthalic acid spot markets. Film converters lack pricing power to pass through resin index movements.
- South Korean supply concentration:Polarizer substrate and adhesive-layer production clusters heavily in Gyeonggi-do. Geopolitical friction or logistics disruption would cascade through LCD and OLED supply chains.
- Technical thickness floor:Mechanical handling limits prevent polarizer films below 50 micrometers from maintaining optical performance during panel lamination. Roll-to-roll processing yields degrade sharply at thinner gauges.
Strategic Opportunities
- Medical display certification:Diagnostic monitor manufacturers are sourcing anti-reflective films with EN 60601-1-8 compliance for surgical suite readability. European OEMs specify minimum 98% transmittance and anti-microbial surface treatments.
- China dual carbon alignment:SAMR energy-efficiency mandates for domestic television production indirectly specify optical film transmittance thresholds. Suppliers with verified carbon footprint data gain preferential procurement status.
- Micro-LED convergence:Chip-on-board display architectures eliminate backlight units but require new diffuser and brightness enhancement film configurations. Early qualification relationships with Taiwan and China panel makers offer positioning advantages.
Industry Challenges
- Multi-layer lamination precision:Aligning refractive-index gradients across polarizer, compensation, and adhesive films demands sub-micron thickness control. Defect rates spike when humidity fluctuates in cleanroom environments.
- REACH compliance documentation:Full substance disclosure for phthalate-free adhesive reformulations extends certification timelines. Korean suppliers report 14-18 month validation cycles for new European customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Optical Film Market |
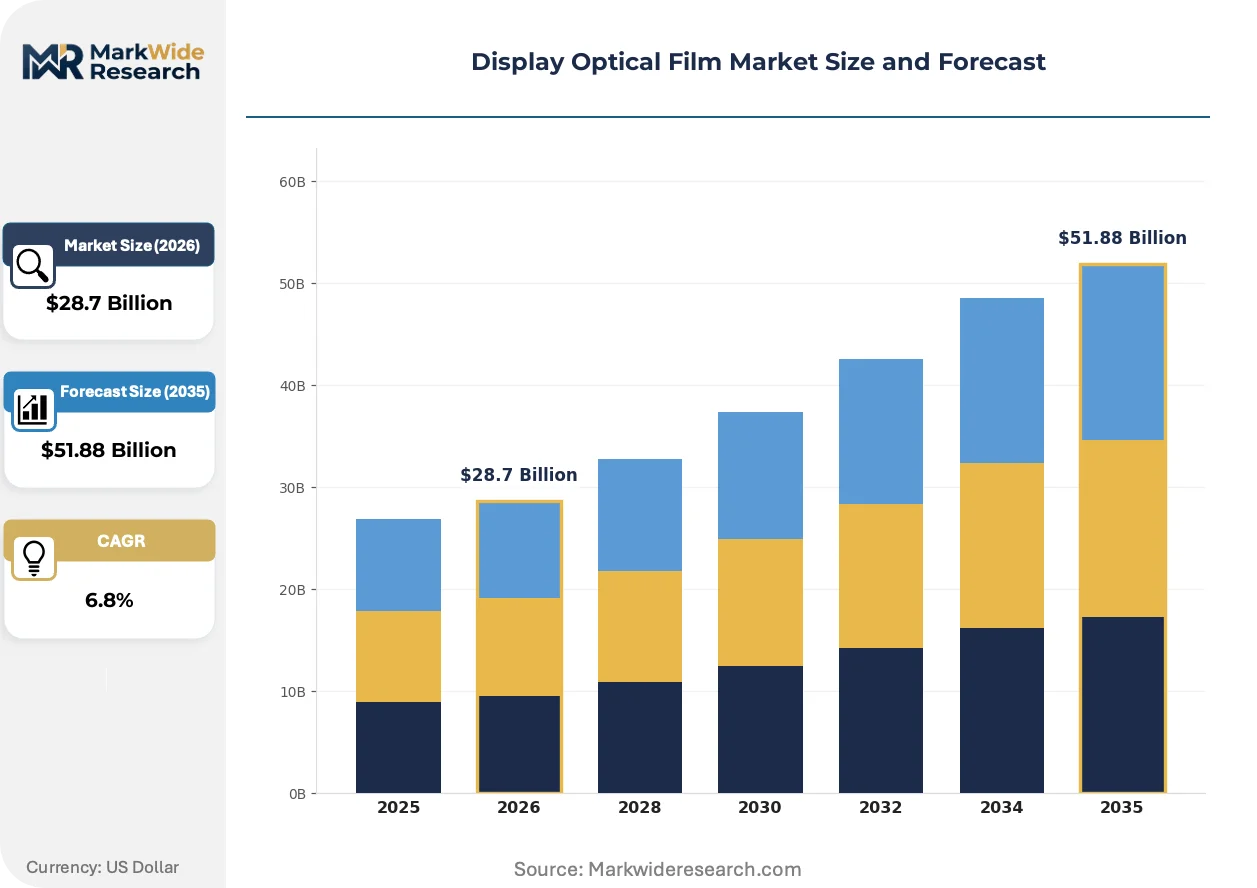
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Reflective Film, Diffuser Film, Polarizer Film, Reflective Film Technology: Optical Coating, Laminating, Printing, Adhesive Technologies End User: Consumer Electronics, Automotive Displays, Medical Devices, Industrial Displays Size: Small Formats, Medium Formats, Large Formats, Custom Sizes |
| Companies Covered | Toray Industries, Inc., Nitto Denko Corporation, 3M, LG Chem, Sumitomo Chemical Co., Ltd., Samsung SDI Co., Ltd., Teijin Limited, Toyobo Co., Ltd., Kolon Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Optical Film Market Emerging Trajectories
Film functionalization is migrating from mechanical thickness control to optical performance engineering, with refractive-index layering and surface microstructure dominating competitive differentiation.
Nanoimprint lithography is converging with roll-to-roll processing to manufacture micro-lens arrays for brightness enhancement films. Automotive display suppliers are adopting these structures for sunlight readability in curved dashboard configurations. The technology is converging with polarizer substrate production to consolidate film stack thickness and reduce lamination steps.
China's MIIT display standards are tightening energy-efficiency thresholds that cascade into minimum transmittance specifications for optical films in domestic television production. SAMR enforcement of GB standards is compressing margin tolerance for commodity-grade diffuser suppliers. Korean and Japanese substrate makers are responding with premium-grade product differentiation to maintain price positioning.
Buyers are consolidating supplier relationships around integrated film stack providers rather than discrete component sourcing. Panel makers in South Korea and China are qualifying fewer vendors capable of delivering polarizer-adhesive-diffuser combinations. This concentration is most visible in Gyeonggi-do, where Samsung SDI and LG Chem anchor captive supply networks for OLED production lines.
Display Optical Film Market Segmentation
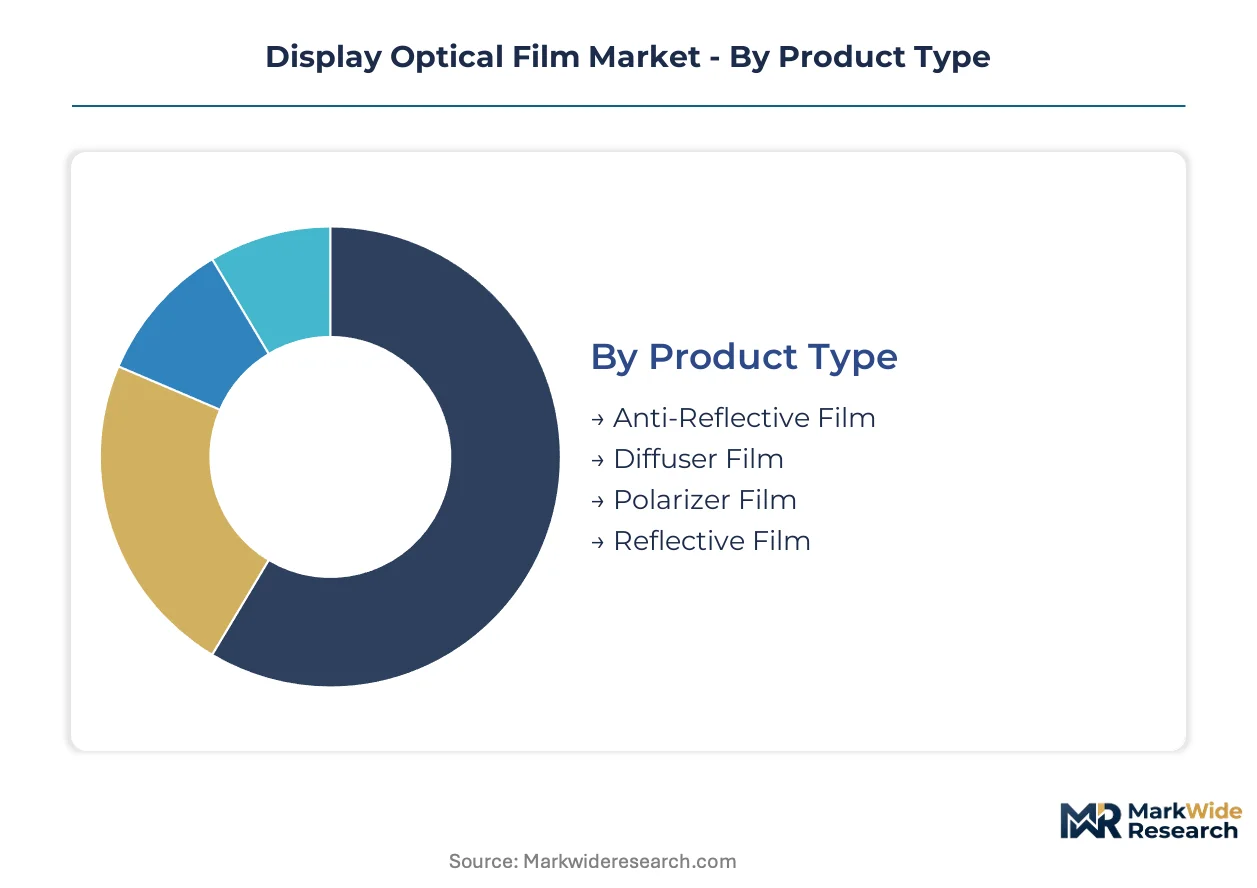
Display optical film segmentation reveals how capital deployment, technical specifications, and end-use requirements fragment procurement patterns across the value chain. Manufacturers prioritize segments where thickness tolerances and optical performance metrics align with panel maker qualification timelines.
Product Type:
Polarizer film demands the heaviest capital commitment, requiring multi-layer extrusion lines and cleanroom infrastructure that can exceed $200 million per production facility.
- Polarizer Film:Multi-layer polymer substrates with precisely aligned iodine-doped PVA cores control light polarization across LCD and OLED stacks. Samsung SDI and LG Chem in Gyeonggi-do anchor global supply for television and mobile panel production, where circular polarizer configurations are penetrating premium segments. Sub-micron thickness tolerances and birefringence control separate qualified suppliers from commodity converters.
- Anti-Reflective Film:Nano-structured surface coatings or vapor-deposited interference layers suppress surface reflections for readability in high-ambient-light conditions. Automotive OEMs in Germany and Japan are scaling procurement for curved dashboard displays, specifying sub-2% haze metrics and controlled refractive-index gradients for non-planar bonding.
- Diffuser Film:Microparticle-embedded polymer substrates scatter backlight illumination across LCD television panels.
- Reflective Film:Metallized or multilayer dielectric constructions redirect light toward display apertures in edge-lit configurations.
Polarizer film absorbs the bulk of installed capacity; anti-reflective film is expanding most quickly.
Technology:
Process selection determines which suppliers can meet automotive and medical certification requirements versus competing on television backlight unit volume.
- Optical Coating:Vacuum deposition and sol-gel processes apply anti-reflective, hard-coat, and conductive layers with nanometer precision. Sputtering and chemical vapor deposition systems command premium pricing but enable the transmittance thresholds that China's SAMR enforces through GB standards for domestic television efficiency.
- Laminating:Roll-to-roll bonding of polarizer substrates, compensation films, and adhesive layers requires tension control systems that maintain optical axis alignment. Korean suppliers dominate this segment for OLED panel qualification, where defect rates spike with humidity fluctuations in cleanroom environments.
- Printing:Gravure and inkjet deposition apply functional patterns for light extraction and diffusion.
- Adhesive Technologies:Pressure-sensitive and UV-cure formulations bond film stacks to display panels.
Laminating commands the highest equipment utilization rates; optical coating delivers the steepest margin expansion.
End User:
Customer mix shifts toward applications where optical performance specifications justify premium pricing over commodity television backlight procurement.
- Automotive Displays:Curved instrument clusters and center-stack screens demand films with mechanical flexibility, thermal stability, and anti-reflective surface treatments. European OEMs specify EN 60601-1-8 compliance thresholds for surgical suite readability, while Tier-1 suppliers in Stuttgart and Toyota City scale orders for sub-2% haze configurations.
- Consumer Electronics:Smartphones, tablets, laptops, and televisions consume the largest film volumes, with premium notebooks requiring brightness enhancement films from 3M's micro-replication optics and standard televisions accepting Chinese-sourced diffuser films under severe margin compression.
- Medical Devices:Diagnostic monitors require anti-microbial surface treatments and minimum 98% transmittance.
- Industrial Displays:HMI panels and outdoor signage prioritize durability and wide-temperature operation.
Consumer electronics absorbs the bulk of installed capacity; automotive displays are climbing the fastest.
Size:
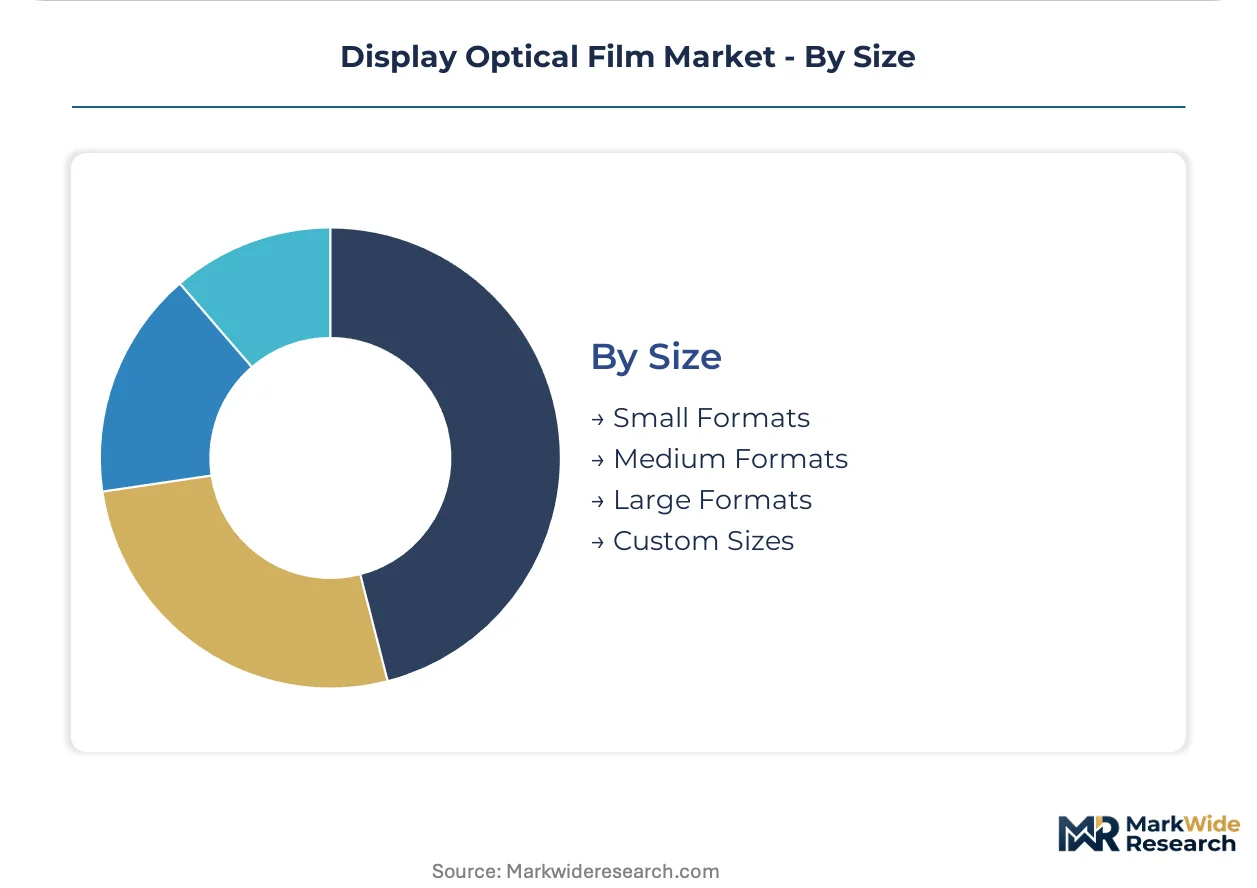
Format selection constrains which production assets qualify for specific panel maker supply agreements, with large formats requiring specialized handling infrastructure.
- Large Formats:Gen 8.5 and Gen 10.5 panel substrates for television production demand film widths exceeding 2,200 millimeters. Chinese panel makers in Hefei and Guangzhou drive volume, while Korean suppliers maintain qualification advantages for premium OLED television stacks where thickness uniformity across wide webs determines yield.
- Medium Formats:Monitor and laptop panel dimensions balance volume scale with handling flexibility.
- Small Formats:Smartphone and wearable displays require ultra-thin polarizer films approaching the 50-micrometer mechanical handling floor.
- Custom Sizes:Medical and automotive applications specify non-standard dimensions with tight lot-size requirements.
Large formats absorb the bulk of installed capacity; custom sizes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi-do province anchors global polarizer film production, hosting Samsung SDI and LG Chem facilities that supply OLED and LCD panel makers across East Asia. Regional procurement patterns diverge sharply between automotive display specifications in Germany and Japan, energy-efficiency mandates in China, and medical certification requirements in Switzerland.
South Korea
Automotive OEMs in Seoul and Busan are scaling curved dashboard display procurement with sub-2% haze specifications. The Ministry of Trade, Industry and Energy enforces K-REACH substance disclosure for adhesive-layer chemistries. Samsung SDI and LG Chem in Gyeonggi-do are expanding multi-layer extrusion capacity for circular polarizer stacks targeting premium television segments.
China
Panel makers in Hefei and Guangzhou are driving large-format film volume for Gen 10.5 television substrates. SAMR enforces GB standards for display energy efficiency that specify minimum transmittance thresholds for optical films. Yangtze River Delta suppliers are retooling casting lines to meet dual carbon goals while maintaining cost positioning against Korean imports.
Japan
Medical display manufacturers in Osaka and Nagoya are sourcing anti-reflective films with 98% transmittance and anti-microbial surface treatments. METI regulates fluorinated compound usage in optical coating chemistries through amended Chemical Substances Control Law provisions. Toray Industries leverages captive polyester substrate production in Chubu to sustain margin pools in high-end polarizer materials.
Germany
Tier-1 automotive suppliers in Stuttgart are qualifying films for curved instrument clusters with controlled birefringence for non-planar bonding. ECHA REACH restrictions on phthalate plasticizers are forcing 14-18 month validation cycles for Korean adhesive suppliers seeking EU market access. Bavaria-based diagnostic monitor OEMs specify EN 60601-1-8 compliance for surgical suite readability applications.
United States
Premium notebook and tablet brands are procuring brightness enhancement films with proprietary micro-replication optics. The EPA regulates perfluorinated compounds in coating chemistries under TSCA Section 5 premanufacture notification requirements. Michigan and Texas automotive clusters are integrating anti-reflective films into center-stack screens for sunlight readability in electric vehicle platforms.
Display Optical Film Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thickness tolerance and optical performance specifications. The market structures around three tiers: integrated substrate-adhesive-diffuse stack providers, specialized coating technology licensors, and volume-focused casting converters. Strategic archetypes include captive chemical conglomerates with polyester film backward integration, precision laminators with cleanroom qualification advantages, and automotive-certified surface treatment specialists. Dominant competitive moves involve multi-layer stack consolidation to reduce panel maker vendor counts and geographic capacity expansion to qualify for China SAMR preferential procurement status.
Among Japanese chemical conglomerates, Toray Industries, Inc., Nitto Denko Corporation, and Teijin Limited exemplify distinct positioning archetypes. Toray Industries represents the vertically integrated substrate producer with captive polymer supply chains. Nitto Denko occupies the adhesive-layer specialist position where roll-to-roll bonding precision determines OLED panel qualification. Teijin Limited sits within the diversified materials tier where medical and automotive certification pathways create margin differentiation from commodity television applications.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Nitto Denko Corporation |
| 3M |
| LG Chem |
| Sumitomo Chemical Co., Ltd. |
| Samsung SDI Co., Ltd. |
| Teijin Limited |
| Toyobo Co., Ltd. |
| Kolon Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into polyester substrate production anchors supply positioning and pricing power for Japanese and Korean chemical conglomerates, while Chinese casting converters without captive resin supply face margin compression from purified terephthalic acid spot volatility. Toray Industries and LG Chem leverage in-house polymer production to defend premium positioning against commodity-grade diffuser suppliers in the Yangtze River Delta.
Pricing Analysis
Yield-based pricing anchors polarizer film contracts, with panel makers paying premiums for sub-micron thickness tolerances and birefringence control that reduce downstream lamination defect rates. Three-tier pricing structure across premium, standard, and economy levels separates qualified OLED stack suppliers from television backlight commodity converters. Cost compression in diffuser films is intensifying because Chinese casting capacity expansion outpaces Gen 10.5 panel demand growth. Automotive OEMs exhibit lowest price sensitivity, prioritizing sub-2% haze specifications and EN 60601-1-8 compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Gyeonggi-do province, where Samsung SDI and LG Chem anchor global polarizer substrate and adhesive-layer production for OLED and LCD panel makers. South Korea, Japan, and China dominate film manufacturing, drawing from purified terephthalic acid, iodine-doped PVA cores, and halogen-free adhesive chemistries as critical inputs. Tariff exposure on Korean exports to the EU compounds REACH compliance timelines for phthalate-free reformulations. Distribution runs through qualified vendor programs at Samsung Display, LG Display, and Chinese panel makers in Hefei and Guangzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated film stack providers as panel makers reduce vendor counts, with REACH and K-REACH substance disclosure requirements forcing 14-18 month validation cycles that weaker players cannot absorb.
For Market Incumbents: Anticipate qualification consolidation by securing circular polarizer stack approvals for premium television segments before adhesive-layer reformulation deadlines. Defend margin pools through captive polyester substrate production and cleanroom laminating capacity expansion in Gyeonggi-do. Threats from micro-LED chip-on-board architectures that eliminate backlight units demand early diffuser reconfiguration partnerships with Taiwan panel makers. For New Entrants and Emerging Players: Enter via medical display certification pathways, where EN 60601-1-8 compliance and anti-microbial surface treatments create defensible positioning against commodity television suppliers. White-space targets include diagnostic monitor OEMs in Osaka and Nagoya requiring 98% transmittance specifications, and European Tier-1 automotive suppliers in Stuttgart qualifying curved dashboard films. Go-to-market angle should emphasize carbon footprint verification for China SAMR preferential procurement status. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by chemical conglomerates seeking OLED qualification capabilities and automotive certification portfolios. Long-term viability favors suppliers with multi-layer extrusion infrastructure and verified halogen-free adhesive formulations. Acquisition target archetype: mid-cap laminators with Gyeonggi-do cleanroom assets and existing Samsung SDI or LG Chem supply relationships. Signal to watch: panel maker consolidation of qualified vendor lists from six to three suppliers per film stack category.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Substrate Production | Toray Industries leverages captive resin supply to sustain margin pools in high-end polarizer materials. |
| Multi-Layer Stack Consolidation | Integrated polarizer-adhesive-diffuser offerings reduce panel maker vendor counts and qualification overhead. |
| Automotive Certification Investment | Sub-2% haze specifications for curved dashboards open premium procurement channels with Stuttgart and Toyota City Tier-1s. |
| Halogen-Free Adhesive Reformulation | Korean suppliers retool solvent casting lines to maintain EU market access under phased cadmium and lead limitations. |
| Carbon Footprint Verification Program | Suppliers with verified data gain preferential status under China SAMR dual carbon alignment mandates. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with polarizer film plant managers, display panel procurement leads, automotive Tier-1 supplier quality directors, optical coating R&D directors, and medical device regulatory affairs specialists. SEC 10-K disclosures from Toray Industries and Nitto Denko, Korean Ministry of Trade customs export statistics, ECHA REACH substance registration databases, and China MIIT display standard enforcement records provided validation. Bottom-up capacity modeling triangulated against top-down panel production forecasts.
Granularity-level modeling deployed product type, technology process, end-use application, and format size as core segmentation dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating OLED panel expansion rates, automotive display content per vehicle trajectories, and television backlight unit replacement cycles. Industry-specific inputs included Gen 8.5 and Gen 10.5 panel substrate width requirements, circular polarizer film stack thickness specifications, and micro-LED chip-on-board diffusion layer reconfiguration timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to Gyeonggi-do supply clusters or accelerated micro-LED adoption eliminating backlight unit demand. Forecasts reflect assumptions about SAMR enforcement consistency, REACH substance restriction phase-in schedules, and polyester resin price volatility bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transmitter Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Global Adaptive Optics Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Laser Module Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Optical Interconnect Market
Optical Components
Digital Cinema Lens Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Machine Vision Light Source Market
Optical Components
Fluorophore Market
Optical Components
Raman Amplifier Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Bio-Optics Market