
 Next Generation 3D Display Market | 2026-2036
Next Generation 3D Display Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation 3D Display Market Outlook
EU F-Gas Regulation is expanding compliance burdens for thermal management in high-luminance 3D panel production, elevating capital requirements for new entrants. Samsung Electronics leverages in-house semiconductor fabrication to sustain cost advantages in MicroLED backlighting architectures. NVIDIA Corp. anchors software-layer differentiation through proprietary rendering pipelines for light-field displays. Toshiba Corporation competes in medical-grade volumetric imaging segments where certification timelines favor incumbents.
Next Generation 3D Display denotes emissive and transmissive visualization systems capable of rendering depth-perceptible imagery without dedicated eyewear, typically achieving spatial resolution above 100 million rays per steradian in holographic configurations and operating across visible spectra from 380 to 740 nanometers for commercial and industrial visualization. The technology dimension spans light-field, volumetric, holographic, and autostereoscopic approaches, with holographic systems commanding premium positioning in surgical planning and volumetric capture studios while autostereoscopic panels penetrate advertising networks at scale. OLED product types retain margin concentration in near-eye VR applications where pixel density exceeds 2,000 pixels per inch, whereas MicroLED product types are displacing incumbent LCD architectures in outdoor digital signage due to luminance thresholds above 5,000 nits.
The US FDA governs diagnostic display luminance calibration for radiological volumetric viewers, while the EU MDR tightens clinical evidence requirements for surgical holography systems and Japan's METI funds domestic light-field patent pools through national technology roadmaps. China's MIIT mandates GB standard compliance for 3D display electromagnetic emissions, creating non-tariff barriers for import-dependent healthcare integrators. Stakeholders must monitor divergence between FDA premarket notification pathways and EU MDR conformity assessment timelines when allocating R&D across transatlantic product portfolios.
Market Dynamics
MicroLED backlighting architectures are compressing manufacturing costs for high-brightness autostereoscopic panels, while EU F-Gas Regulation compliance is redistributing capital toward solid-state thermal management systems in display fabrication facilities.
Growth Catalysts
- Autostereoscopic arcade procurement:Gaming studios in Japan and South Korea are accelerating panel orders for immersive entertainment installations, creating dedicated demand corridors for high-refresh-rate volumetric displays.
- METI patent pool funding:Japan's national technology roadmaps are financing domestic light-field intellectual property aggregation, lowering licensing friction for indigenous display developers.
- VR headset assembler concentration:Shenzhen's display cluster in Guangdong province feeds downstream virtual reality manufacturers with specialized OLED and MicroLED subassemblies.
Market Restraints
- Rare earth phosphor supply concentration:High-purity europium and terbium sourcing for quantum-dot color conversion remains concentrated in limited extraction jurisdictions, creating input cost volatility.
- F-Gas compliance capital intensity:The EU F-Gas Regulation mandates refrigerant phase-out timelines that force fabs toward unproven solid-state cooling architectures, elevating new entrant barriers.
- Holographic resolution physics:Current spatial light modulator pixel densities impose hard limits on viewable angle expansion without unacceptable brightness trade-offs in medical visualization systems.
Strategic Opportunities
- Surgical holography certification pathways:The EU MDR's tightened clinical evidence requirements create incumbent-favored segments where established volumetric imaging vendors can defend positioning through regulatory relationships.
- Light-field and AI rendering convergence:Neural radiance field compression algorithms are enabling real-time holographic streaming over standard bandwidth, opening broadcast and telepresence applications previously blocked by data throughput constraints.
- GB standard compliance services:China's MIIT electromagnetic emission mandates for 3D displays create non-tariff barriers that favor domestic healthcare integrators with established testing relationships.
Industry Challenges
- Cross-regulatory portfolio allocation:R&D teams must reconcile divergent FDA premarket notification timelines against EU MDR conformity assessment durations when designing transatlantic surgical visualization products.
- Multi-physics simulation talent scarcity:The intersection of wave optics, thermal management, and semiconductor process engineering requires specialized expertise that outpaces current graduate program output in display-relevant disciplines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation 3D Display Market |
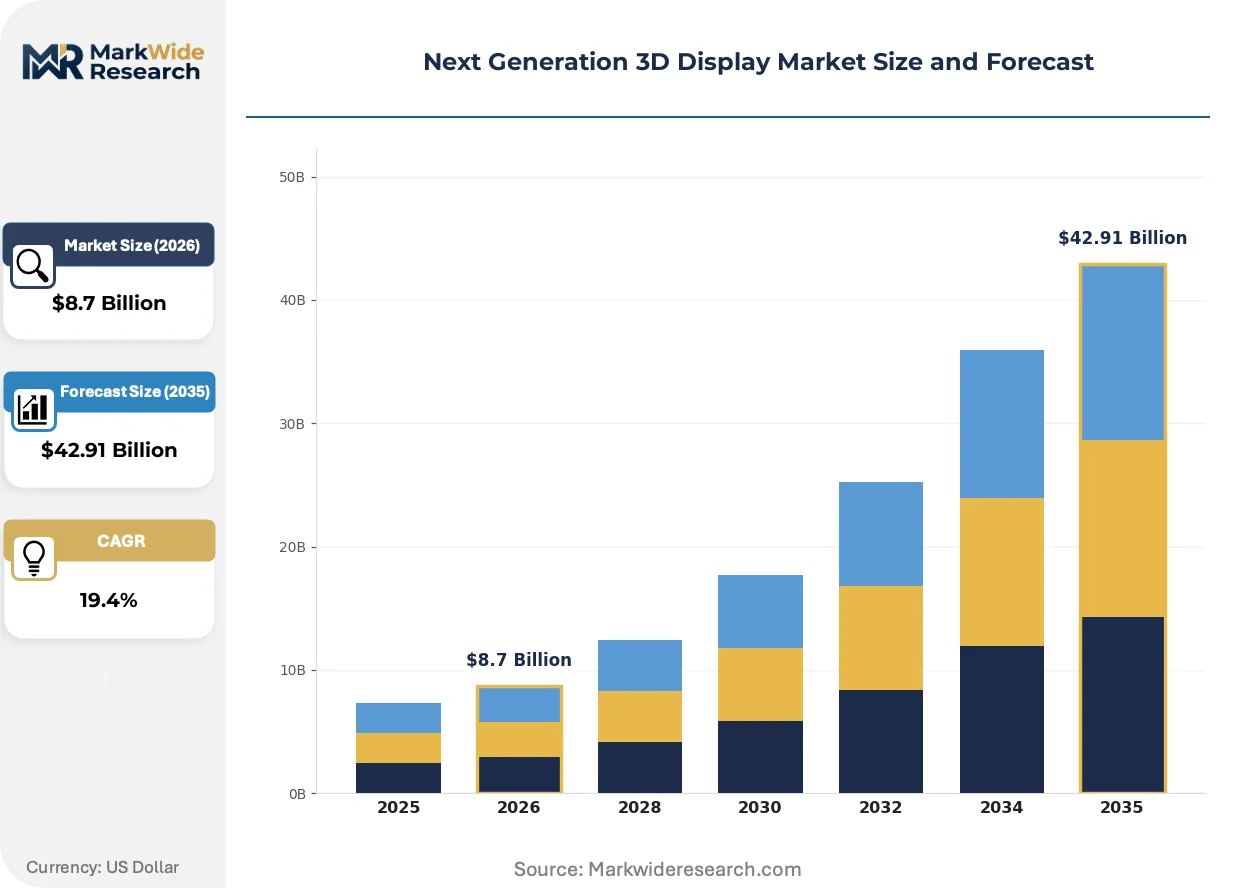
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, DLP, MicroLED Technology: Light Field, Volumetric, Holographic, Autostereoscopic End User: Gaming, Healthcare, Education, Entertainment Application: Virtual Reality, Augmented Reality, Simulation, Advertising |
| Companies Covered | AU Optronics, Toshiba Corporation, Samsung Electronics, NVIDIA Corp., Continental AG, LG Electronics, Sharp Corporation, Avalon Holographics Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation 3D Display Market Strategic Shifts
Computational display architectures are merging previously separate hardware and software layers, collapsing traditional component boundaries while regulatory jurisdictions compete to establish certification precedents for immersive medical visualization.
Light-field display systems are unifying ray sampling and directional backlight control into single optical stacks. Automotive HUD developers in Germany are piloting these architectures for augmented windscreen projection. This convergence is unifying previously separate illumination and modulation subsystems, compressing module thickness while expanding effective depth range.
The EU F-Gas Regulation is accelerating refrigerant substitution timelines across high-luminance panel manufacturing. Solid-state thermoelectric and vapor chamber alternatives are displacing conventional compressor-based cooling in fabs serving outdoor digital signage segments. German and Dutch equipment suppliers are capturing retrofit contracts as existing lines face compliance deadlines.
Buyer concentration among VR headset assemblers is compressing component negotiation cycles for display module vendors. Shenzhen-based integrators now demand quarterly price renegotiation clauses previously reserved for commodity memory contracts. This pattern is most visible in Guangdong province, where panel procurement has shifted from annual framework agreements to spot-market-indexed purchasing.
Next Generation 3D Display Market Segmentation
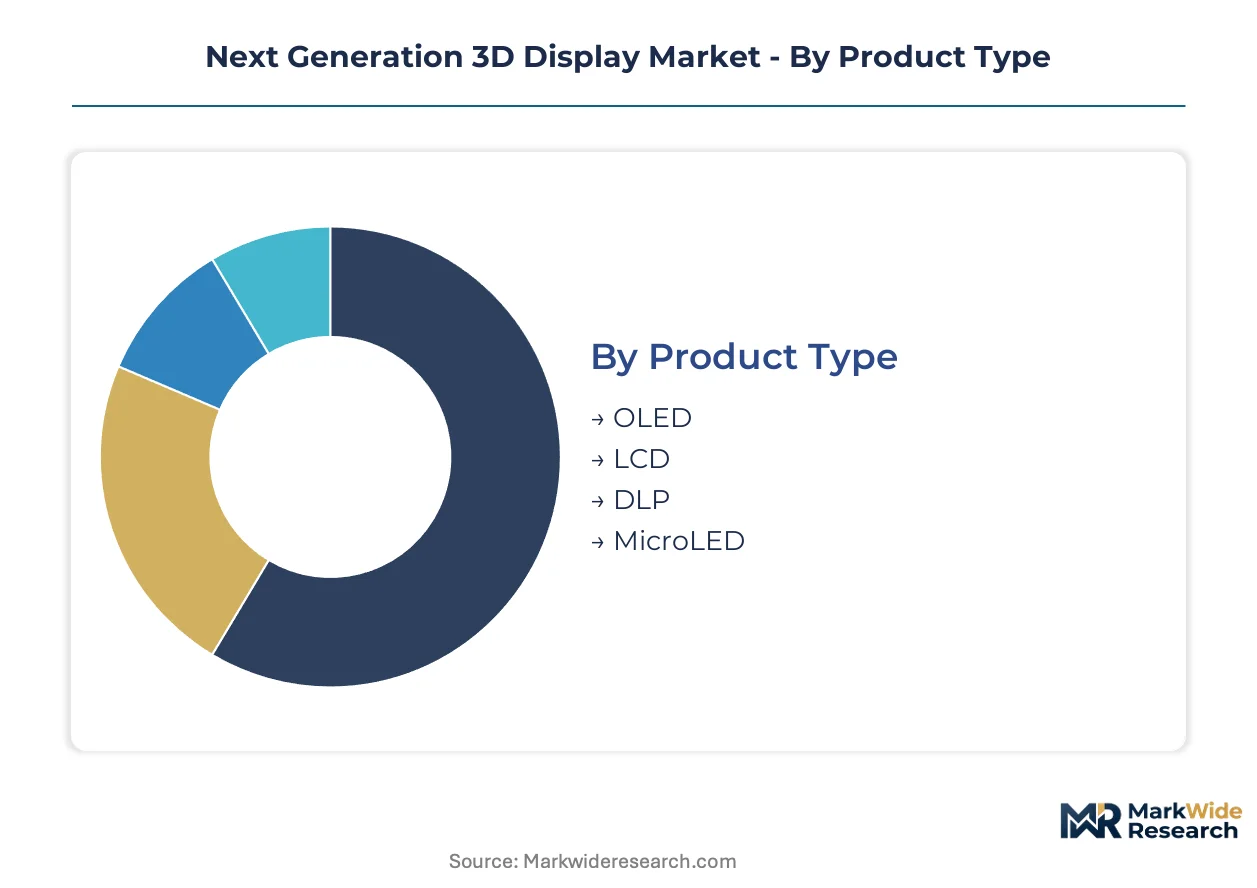
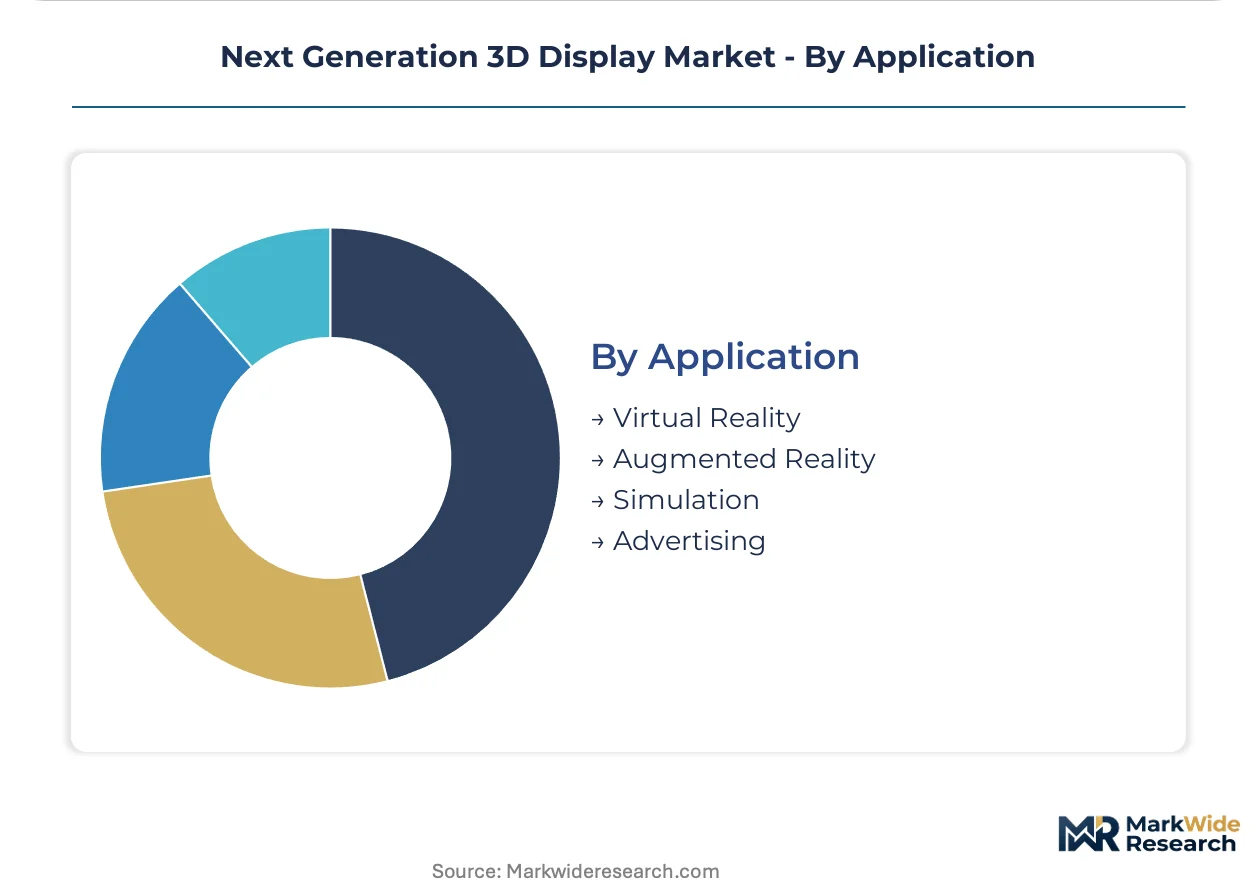
Segmentation reveals where capital requirements concentrate and which technology pathways justify premium positioning. The report examines four critical dimensions shaping procurement patterns and vendor profitability across the Next Generation 3D Display Market.
Product Type:
Capital intensity varies sharply across emissive and transmissive architectures, with semiconductor fabrication requirements determining entry barriers.
- OLED:Organic compound deposition through precision shadow masking achieves pixel densities exceeding 2,000 pixels per inch for near-eye VR applications. Demand concentrates in Shenzhen's headset assembly cluster where Guangdong province integrators specify sub-millimeter form factors for weight-constrained wearables.
- MicroLED:Chiplet transfer bonding and mass repair equipment demands upfront fab investment an order of magnitude above OLED equivalents. Outdoor digital signage in Japan and South Korea drives procurement where luminance thresholds above 5,000 nits displace incumbent LCD backlights.
- LCD:Mature thin-film transistor supply chains limit differentiation opportunities in cost-sensitive autostereoscopic panels.
- DLP:Digital micromirror device architectures serve volumetric projection systems where rapid refresh rates support medical imaging workflows.
MicroLED absorbs the bulk of installed capacity expansion capex; OLED is expanding most quickly in unit shipment terms.
Technology:
Intellectual property density and regulatory certification timelines segment competitive positioning across depth-rendering approaches.
- Holographic:Spatial light modulator pixel densities above 100 million rays per steradian enable surgical planning applications. EU MDR tightened clinical evidence requirements favor incumbent volumetric imaging vendors with established regulatory relationships in Germany and France.
- Autostereoscopic:Lenticular lens arrays and parallax barrier architectures eliminate eyewear requirements for arcade and advertising deployments. Gaming studios in Japan and South Korea accelerate procurement for immersive entertainment installations.
- Light Field:Ray sampling convergence with directional backlight control compresses module thickness for automotive HUD pilot programs in Germany.
- Volumetric:Swept-volume and static-volume approaches serve medical-grade visualization where FDA diagnostic display luminance calibration governs radiological viewer certification in the United States.
Holographic commands the steepest expansion trajectory in revenue per unit; autostereoscopic captures the largest installed base in volume terms.
End User:
Procurement sophistication and specification rigor determine margin capture across buyer categories.
- Gaming:High-refresh-rate volumetric display requirements from Japanese and South Korean arcade operators create dedicated demand corridors with quarterly price renegotiation clauses.
- Healthcare:Surgical holography and diagnostic imaging segments impose dual regulatory burdens from FDA premarket notification pathways and EU MDR conformity assessment timelines.
- Entertainment:Broadcast and telepresence applications emerge as neural radiance field compression enables real-time holographic streaming over standard bandwidth.
- Education:Institutional procurement cycles favor established display vendors with service infrastructure across distributed campus networks.
Healthcare absorbs premium pricing for certified systems; gaming drives volume procurement acceleration.
Application:
Use-case performance thresholds and environmental operating conditions shape technology selection and thermal management requirements.
- Virtual Reality:Near-eye pixel density and motion-to-photon latency specifications concentrate demand in Guangdong province assembly operations feeding global headset distribution.
- Augmented Reality:Optical see-through waveguide architectures require precision manufacturing partnerships with German and Dutch equipment suppliers.
- Simulation:Military and aviation training systems demand ruggedized volumetric displays with extended temperature operating ranges.
- Advertising:Network-scale autostereoscopic deployment in retail environments prioritizes luminance consistency and remote content management capabilities.
Virtual Reality commands the dominant share of component procurement value; Augmented Reality gains share fastest in patent filing activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three distinct manufacturing corridors where display fabs, gaming studios, and healthcare integrators cluster. Shenzhen's assembly ecosystem, Tokyo-Osaka's arcade entertainment belt, and Stuttgart-Munich's automotive HUD development zones absorb the majority of procurement volume.
China
Guangdong province hosts Shenzhen's display cluster feeding VR headset assemblers with specialized OLED and MicroLED subassemblies. MIIT mandates GB standard compliance for 3D display electromagnetic emissions, creating non-tariff barriers for import-dependent healthcare integrators. Dongguan and Huizhou satellite cities expand precision molding capacity for autostereoscopic lens arrays.
Japan
Gaming studios in Tokyo and Osaka accelerate procurement of autostereoscopic panels for immersive arcade installations. METI funds domestic light-field patent pools through national technology roadmaps, lowering licensing friction for indigenous display developers. Kyoto-based precision optics suppliers serve holographic surgical planning equipment manufacturers.
South Korea
Seoul Capital Area gaming conglomerates drive high-refresh-rate volumetric display orders for entertainment venues. MFDS maintains diagnostic display luminance calibration standards for radiological equipment parallel to FDA frameworks. Suwon and Yongin fabrication complexes expand MicroLED chiplet transfer bonding capacity.
Germany
Automotive HUD developers in Stuttgart and Munich pilot light-field architectures for augmented windscreen projection. EU F-Gas Regulation compliance deadlines force fabs toward solid-state thermoelectric cooling retrofits. Dresden equipment suppliers capture display manufacturing retrofit contracts as existing lines face refrigerant phase-out mandates.
United States
Healthcare integrators concentrate in Greater Boston and San Diego metropolitan zones for FDA premarket notification pathway access. FDA governs diagnostic display luminance calibration for radiological volumetric viewers with timelines diverging from EU MDR conformity assessments. Austin and Phoenix emerging as secondary clusters for simulation and defense training display procurement.
Next Generation 3D Display Market Competitive Environment
South Korean and Japanese producers anchor one tier; German automotive specialists and Taiwan-based panel fabricators hold adjacent positions. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive semiconductor fabrication, pure-play display module specialists, and holographic imaging technology developers. Competitive moves center on backward integration into LED epitaxy and strategic patent pool participation rather than horizontal consolidation.
Within the diversified electronics tier, Samsung Electronics exemplifies vertical control through in-house semiconductor fabrication, while LG Electronics occupies a parallel position in adjacent display architectures. NVIDIA Corp. sits within the software-layer differentiation archetype, anchoring proprietary rendering pipeline development. Toshiba Corporation represents the medical-grade specialization vector where regulatory certification timelines favor established volumetric imaging vendors.
| Leading Market Players |
|---|
| AU Optronics |
| Toshiba Corporation |
| Samsung Electronics |
| NVIDIA Corp. |
| Continental AG |
| LG Electronics |
| Sharp Corporation |
| Avalon Holographics Inc. |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Shenzhen-based VR headset assemblers concentrate procurement leverage, compressing display module negotiations into quarterly price renegotiation cycles indexed to spot-market memory benchmarks. This buyer archetype dominance forces panel vendors toward contract structures that sacrifice margin predictability for volume commitments.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to autostereoscopic panel orders for Japanese and South Korean arcade studios facing immersive installation deadlines. The dominant model rests on tiered pricing stratifying across premium holographic surgical systems, standard autostereoscopic advertising panels, and economy LCD-based volumetric projectors. Price differentiation hinges on FDA and EU MDR certification tiers alongside pixel density specifications. Cost compression in MicroLED chiplet transfer bonding is intensifying because equipment utilization rates remain below breakeven thresholds. Healthcare integrators exhibit least price sensitivity due to regulatory lock-in, while advertising network operators drive hardest bargain.
Supply Chain Analysis
Regional distribution centers in Dongguan and Huizhou satellite cities feed precision-molded lenticular lens arrays to Guangdong province panel integrators. Manufacturing gravity centers on China, South Korea, and Japan, with Dresden equipment suppliers capturing solid-state cooling retrofit contracts. Rare earth phosphor sourcing for quantum-dot color conversion draws from concentrated europium and terbium extraction jurisdictions. Single-source vulnerability in high-purity phosphor supply creates input cost volatility exposure. Distribution runs through hub-and-spoke patterns anchored by Shenzhen's display cluster with secondary nodes in Tokyo-Osaka and Suwon-Yongin corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MicroLED chiplet transfer bonding capacity scarcity props pricing across high-brightness autostereoscopic segments, constraining supply expansion regardless of downstream demand signals.
For Market Incumbents: To counter quarterly price renegotiation clauses demanded by Shenzhen headset assemblers, Samsung Electronics and LG Electronics should deepen backward integration into LED epitaxy wafer production while securing multi-year patent pool participation through METI-funded light-field aggregations. Captive semiconductor fabrication preserves cost advantages against pure-play module specialists. For New Entrants and Emerging Players: German automotive HUD developers present the most penetrable channel partner type for light-field architecture pilots, particularly Stuttgart and Munich engineering centers piloting augmented windscreen projection. White-space targets include EU MDR-certified surgical holography components and GB standard compliance services for China healthcare integrators. Go-to-market positioning should emphasize solid-state thermal management retrofits for EU F-Gas Regulation compliance deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play holographic imaging developers in Germany and France where EU MDR conformity assessment timelines have stranded pre-revenue ventures with completed clinical evidence packages. Long-term viability over the next decade hinges on regulatory relationship moats rather than raw technology differentiation. Watch for FDA premarket notification pathway divergence from EU MDR timelines as inflection signal for transatlantic portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Epitaxy | Samsung Electronics secures cost advantages in MicroLED backlighting architectures against pure-play competitors. |
| Patent Pool Participation | METI-funded light-field intellectual property aggregation lowers licensing friction for indigenous Japanese developers. |
| EU F-Gas Compliance Retrofit | Dresden equipment suppliers capture display manufacturing retrofit contracts as refrigerant phase-out mandates tighten. |
| Neural Radiance Field Integration | NVIDIA Corp. anchors software-layer differentiation through proprietary rendering pipelines for real-time holographic streaming. |
| GB Standard Compliance Services | Domestic Chinese healthcare integrators leverage established MIIT testing relationships against import-dependent competitors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with display fab process engineers, arcade procurement directors, healthcare GPO contracts managers, and automotive HUD platform engineers. FDA 510(k) premarket notification databases, EU MDR conformity assessment documentation, METI technology roadmap publications, and MIIT GB standard compliance registries provided validation triangulation. Bottom-up module shipment aggregation and top-down semiconductor equipment capex analysis were cross-referenced.
Granularity-level modeling distinguished emissive versus transmissive architectures, depth-rendering technology approaches, end-user procurement sophistication tiers, and application-specific performance thresholds across the projection horizon. CAGRs were derived from equipment utilization rate trajectories, patent filing velocity, and regulatory approval timeline differentials. Forecast inputs incorporated rare earth phosphor spot price volatility and EU F-Gas Regulation compliance cost curves.
Caveats apply where spatial light modulator pixel density breakthroughs or solid-state cooling architecture failures could materially shift the outlook. Forecasts reflect documented assumptions regarding gaming studio procurement acceleration and healthcare regulatory pathway divergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Graphic LCD Modules Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Backlit Displays Market
Display Technologies
OLED Laptops Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Display Mask Market
Display Technologies
Flexible OLED Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Global UHD Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Electronic Display Signs Market