
 Dispensing Pharmacy Packaging Machine Market | 2026-2036
Dispensing Pharmacy Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Pharmacy Packaging Machine Market Analysis
Unit-dose specification compliance is collapsing the installed base of legacy manual equipment into replacement cycles. Omnicell, Inc. leverages cloud-connected inventory software to anchor hospital automation contracts. Becton, Dickinson and Company sustains dominant positions in high-throughput blister systems through backward integration into medication tracking software. Yuyama Manufacturing Co., Ltd. specializes in compact robotic dispensers that occupy dense urban pharmacy footprints.
Dispensing pharmacy packaging machines mechanically sort, count, label, and seal oral solid and liquid medications into patient-specific or unit-dose formats with throughput rates exceeding 300 prescriptions per hour for top-tier automatic systems. These systems serve primary commercial purposes of eliminating dispensing errors, enabling traceability, and reducing labor costs in high-volume medication distribution environments. Blister packaging machines lead product type segments due to institutional preference for tamper-evident unit-dose formats, while robotic technology represents the fastest-expanding category as labor shortages intensify across retail and hospital pharmacies. End-user concentration tilts toward hospitals and drug manufacturers where regulatory compliance requirements create durable margin pools for validated equipment.
FDA serialization mandates under the Drug Supply Chain Security Act compel track-and-trace hardware integration, while EU MDR and F-Gas Regulation shape refrigerant-based packaging for temperature-sensitive biologics in European installations. The country's national pharmaceutical regulator in Japan enforces PIC/S GMP Annex 1 compliance that filters equipment procurement toward isolator-integrated filling lines. Stakeholders must monitor evolving USP <797> and <800> sterile compounding revisions that will redefine cleanroom packaging machine specifications without grandfathering existing installations.
Market Dynamics
Hospital pharmacy consolidation is compressing vendor selection cycles toward enterprise-wide automation contracts, forcing equipment manufacturers to bundle hardware with cloud-native inventory platforms or lose multi-site tenders.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates compel track-and-trace hardware retrofits across US hospital and retail pharmacies, accelerating replacement of non-compliant legacy blister lines.
- Robotic dispensing systems:Labor shortages in high-cost pharmacy markets are pulling capital toward compact robotic dispensers that reduce technician headcount in 24-hour operations.
- Japan:The country's national pharmaceutical regulator enforces PIC/S GMP Annex 1 compliance that filters procurement toward isolator-integrated filling lines for sterile compounding.
Market Restraints
- Stainless steel and electronic component costs:Input price volatility compresses margins on mid-tier equipment, particularly for European manufacturers exposed to energy-intensive metal processing.
- Validation timelines:FDA 21 CFR Part 11 software validation requirements extend commissioning cycles by 4-6 months, delaying revenue recognition for complex integrated systems.
- Manual pouch packaging:Low-cost semi-automatic alternatives retain share in cash-constrained independent pharmacies, capping premium automation penetration.
Strategic Opportunities
- India:CDSCO's phased GMP upgrades for domestic pharmaceutical manufacturing create first-mover advantage for isolator-integrated packaging lines in contract packaging facilities.
- Cold-chain biologics packaging:EU F-Gas Regulation restrictions on refrigerant-based systems are opening demand for solid-state cooling integration in temperature-sensitive medication dispensers.
- Cloud-connected predictive maintenance:Convergence of IoT sensors and machine learning algorithms enables outcome-based service contracts that lock in multi-year recurring revenue streams.
Industry Challenges
- Pharmacy automation technicians:Scarce talent pools for servicing electromechanical systems with both pharmaceutical and robotics expertise inflate field service costs and extend mean-time-to-repair.
- Legacy HIS/PIS integration:Proprietary communication protocols in existing hospital information systems force costly middleware development for seamless workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Pharmacy Packaging Machine Market |
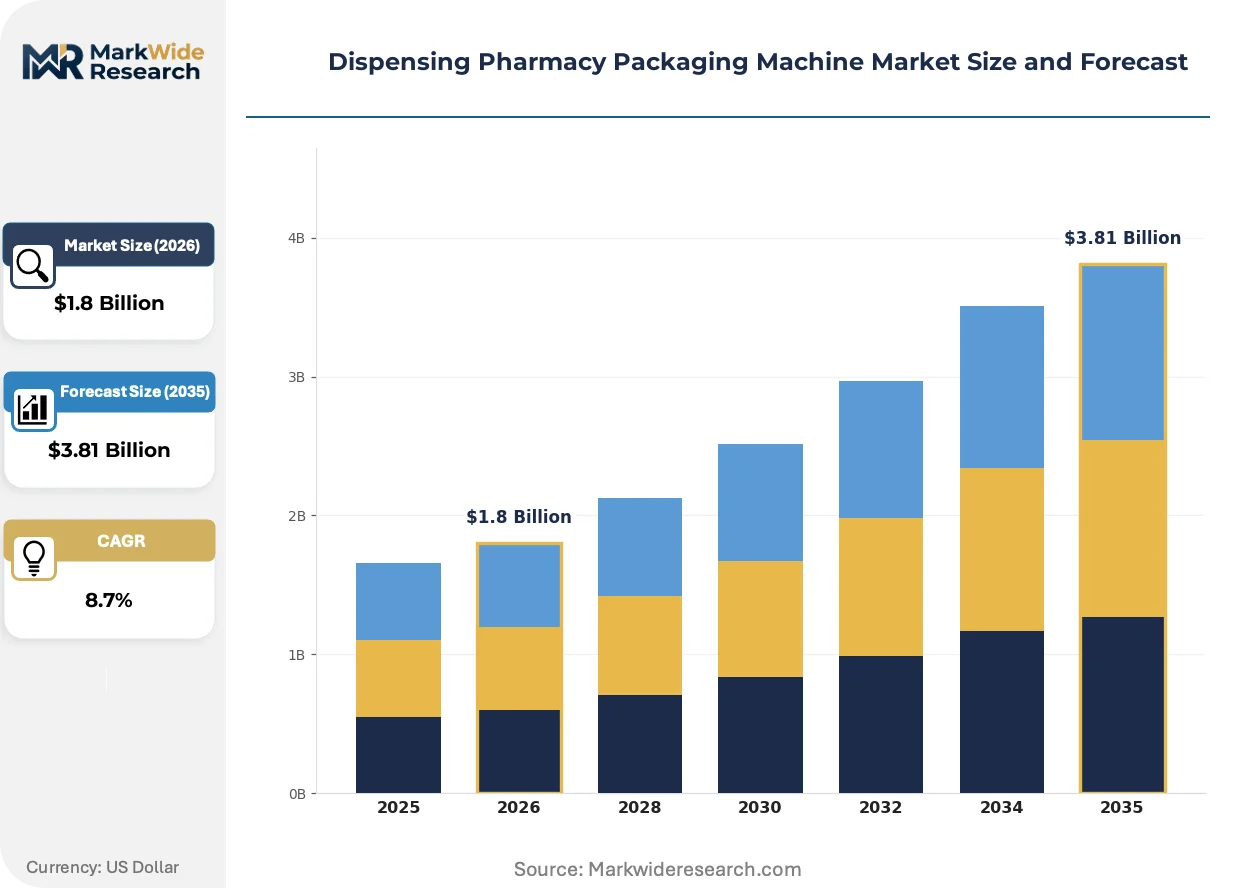
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packaging Machines, Sachet Filling Machines, Bottle Filling Machines, Carton Packaging Machines End User: Pharmacies, Hospitals, Drug Manufacturers, Contract Packaging Organizations Technology: Automatic, Semi-Automatic, Manual, Robotic Application: Pharmaceuticals, Nutraceuticals, Veterinary, Herbal Products |
| Companies Covered | Yuyama Manufacturing Co., Ltd., TOSHO Inc., Omnicell, Inc., Becton, Dickinson and Company, Takazono Corporation, Swisslog Holding AG, Parata Systems, JVM Co., Ltd., Marchesini Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Pharmacy Packaging Machine Market Emerging Trajectories
Cloud-native inventory platforms are rewriting competitive boundaries by embedding dispensing machines within broader medication management ecosystems rather than treating them as standalone capital equipment.
Robotic dispensing cells with integrated vision systems are supplanting conventional counting-and-pouching workflows in high-throughput hospital pharmacies. Systems exceeding 300 prescriptions per hour now anchor enterprise automation tenders. This compression of labor-dependent processes is eroding the installed base of mechanical counting devices.
EU MDR traceability requirements for medical devices are forcing packaging equipment manufacturers to embed unique device identification serialization modules as standard rather than optional configurations. European hospital procurement committees now disqualify non-UDI-ready blister lines from capital budgets. German and French health systems are accelerating this transition through centralized purchasing consortiums.
Consolidated health systems are unbundling after-sales service from initial equipment purchases, negotiating separate multi-year performance contracts with third-party technical service organizations. This disintermediation of manufacturer service revenue is most visible in United States hospital networks with 10+ pharmacy sites, where procurement teams prioritize vendor-agnostic maintenance coverage over OEM service lock-in.
Dispensing Pharmacy Packaging Machine Market Segmentation
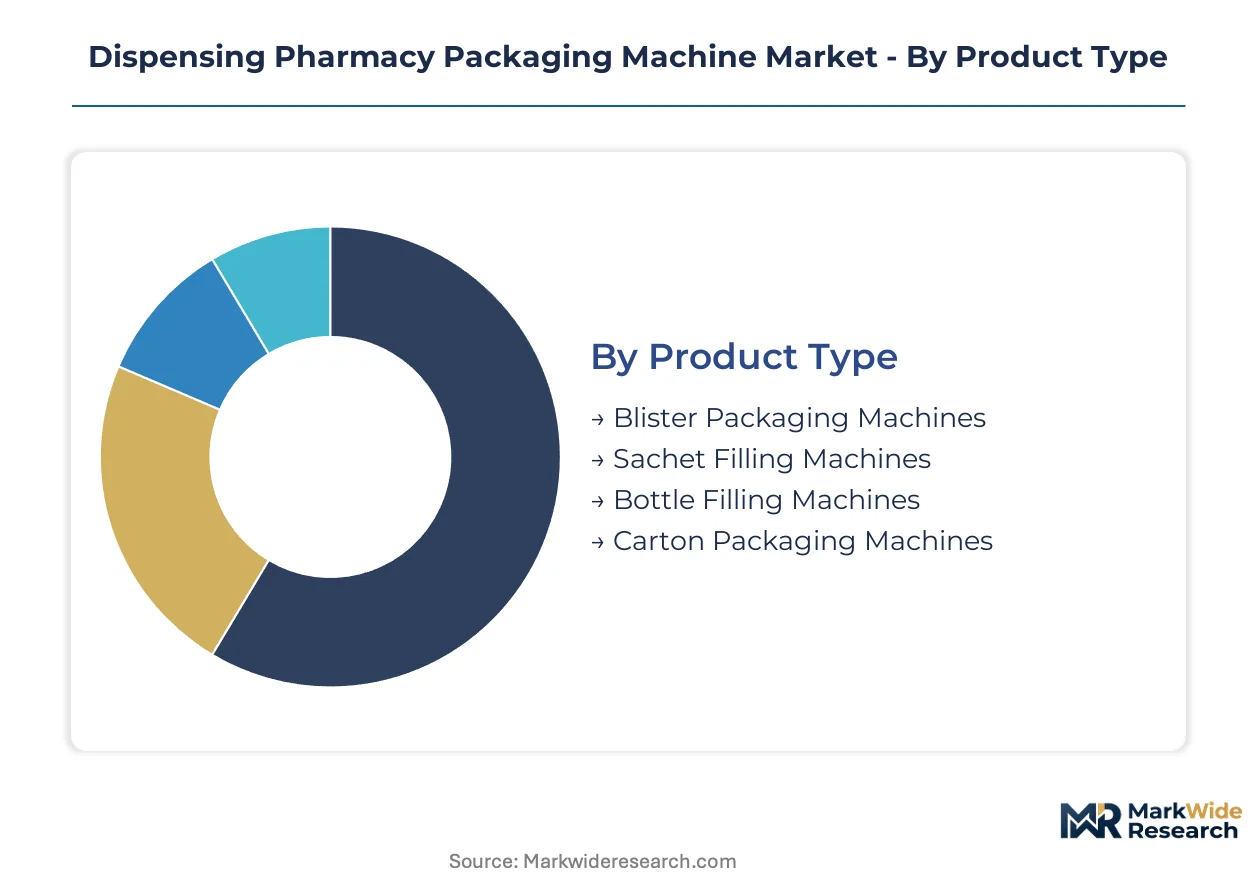
Packaging machine segmentation reveals divergent margin structures across equipment categories. Product type and technology tiers create distinct profitability pools based on regulatory validation burdens and throughput specifications.
Product Type:
Margin pools concentrate in validated blister systems where tamper-evident unit-dose formats command premium pricing from institutional buyers.
- Blister Packaging Machines:These systems form, fill, and seal thermoformed or cold-formed cavities with aluminum-foil lidding for unit-dose oral solids. Demand clusters in United States hospital networks where FDA DSCSA serialization mandates require track-and-trace integration at the point of dispensing.
- Sachet Filling Machines:Vertical form-fill-seal equipment packages powders and granules into laminated film pouches. Japanese retail pharmacies favor compact sachet lines for dense urban footprints where space constraints dominate procurement criteria.
- Bottle Filling Machines:Rotary and inline systems count tablets or capsules into HDPE or PET containers with desiccant insertion and child-resistant capping.
- Carton Packaging Machines:End-of-line equipment erects, loads, and seals secondary packaging around primary containers for palletization and distribution.
Blister packaging machines hold installed capacity. Sachet filling machines are rotating up the share rankings.
End User:
Customer type determines contract structure, with consolidated health systems extracting multi-site pricing leverage unavailable to fragmented independents.
- Pharmacies:Retail and outpatient dispensaries deploy countertop automation for prescription fulfillment. Labor shortages in high-wage markets pull capital toward robotic dispensing cells that reduce technician headcount.
- Hospitals:Inpatient pharmacies anchor enterprise automation tenders exceeding 300 prescriptions per hour. United States health system consolidation compresses vendor selection cycles toward bundled hardware-software contracts.
- Drug Manufacturers:Primary packaging operations at pharmaceutical production facilities require isolator-integrated lines for sterile compounding compliance.
- Contract Packaging Organizations:Third-party packagers serving multiple clients demand rapid changeover capabilities and modular equipment configurations.
Hospital procurement dominates capital deployment. Contract packaging organizations are climbing the fastest as outsourcing accelerates.
Technology:
Automation tier shapes total cost of ownership calculations, with semi-automatic equipment retaining relevance in cost-constrained segments.
- Automatic:Fully integrated systems with PLC-controlled sorting, counting, labeling, and sealing achieve throughput rates exceeding 300 prescriptions per hour. FDA 21 CFR Part 11 software validation requirements extend commissioning cycles by 4-6 months.
- Robotic:Articulated arm and delta robot configurations with integrated vision systems handle variable pouch sizes and medication formats. Labor shortages intensify across retail and hospital pharmacies, accelerating capital allocation to robotic dispensers.
- Semi-Automatic:Operator-assisted equipment balances throughput with capital expenditure constraints.
- Manual:Benchtop devices for low-volume or specialty compounding operations.
Automatic systems anchor the installed base. Robotic technology is gaining share fastest as workforce constraints tighten.
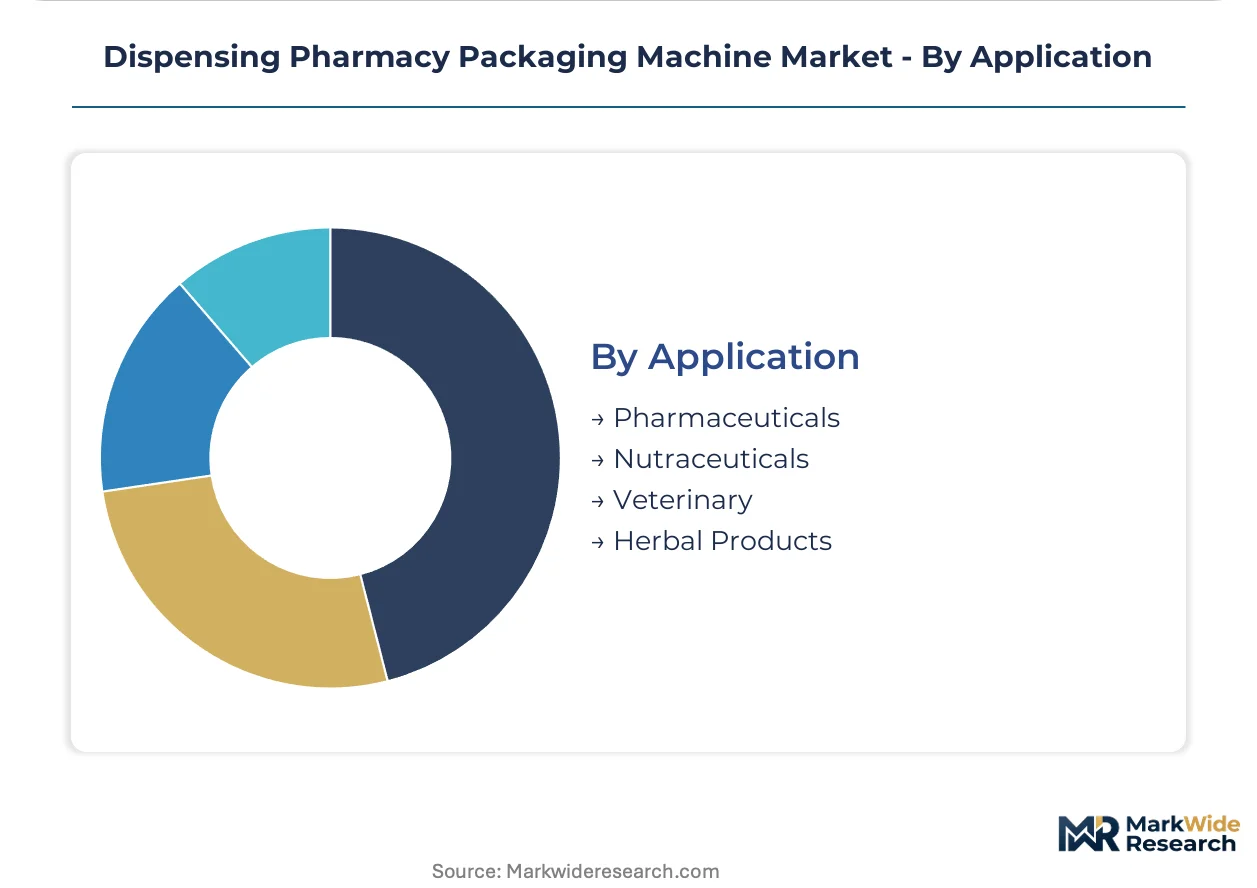
Application:
Regulatory pathway complexity creates margin stratification, with human pharmaceuticals commanding validation premiums over adjacent categories.
- Pharmaceuticals:Prescription and over-the-counter medications drive equipment specifications for cGMP compliance, serialization, and sterility assurance. EU MDR traceability requirements force UDI-ready configurations as standard.
- Nutraceuticals:Dietary supplements and functional foods utilize packaging equipment with reduced validation burdens but similar throughput requirements.
- Veterinary:Animal health products require dedicated lines or validated cleaning protocols to prevent cross-contamination.
- Herbal Products:Traditional medicine formats in Asian markets utilize adapted pouch and bottle filling systems.
Pharmaceutical applications concentrate revenue. Nutraceuticals are rotating up the share rankings as wellness markets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial import surplus in dispensing pharmacy packaging machinery, sourcing precision blister systems from Germany and compact robotic dispensers from Japan while exporting validation-heavy hospital automation to Canada and Mexico. European manufacturers dominate the premium tier, while Asian fabricators capture volume demand across emerging markets.
United States
Hospital network consolidation concentrates procurement power among ten major health systems operating 300+ pharmacy sites each. FDA Drug Supply Chain Security Act serialization deadlines force 2025-2027 replacement cycles for non-compliant blister lines. Minneapolis and Nashville anchor the densest clusters of pharmacy automation deployment, with regional purchasing consortia extracting multi-site pricing leverage from vendors.
Germany
Precision engineering capabilities sustain dominance in high-throughput isolator-integrated systems for sterile compounding. EU MDR traceability requirements and F-Gas Regulation refrigerant restrictions shape equipment specifications for temperature-sensitive biologics. The Baden-Württemberg corridor around Stuttgart hosts the densest concentration of packaging machinery engineering talent and supplier ecosystems.
Japan
Urban pharmacy density drives demand for compact robotic dispensers occupying minimal floor space in Tokyo and Osaka metro areas. The country's national pharmaceutical regulator enforces PIC/S GMP Annex 1 compliance that filters procurement toward isolator-integrated filling lines. Nagoya and Kyoto anchor specialized clusters of pharmaceutical equipment manufacturing with deep backward integration into precision motion control components.
India
Contract packaging organization expansion creates first-mover opportunities for isolator-integrated lines as CDSCO phases in domestic GMP upgrades. Price-sensitive procurement favors semi-automatic equipment in independent retail pharmacies, while hospital chains invest in automatic systems. Ahmedabad and Hyderabad concentrate the fastest-growing contract packaging facility construction, with multinational manufacturers establishing captive packaging operations for export markets.
China
Hospital pharmacy automation adoption accelerates in tier-one cities facing technician labor shortages and 24-hour operation requirements. NMPA serialization mandates for pharmaceutical track-and-trace drive equipment upgrades across provincial hospital networks. Shanghai and Suzhou host the primary clusters of domestic packaging machinery manufacturing, with state-backed pharmaceutical industrial parks subsidizing automation investments in Chengdu and Xi'an.
Dispensing Pharmacy Packaging Machine Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized pharmacy automation pure-plays rather than general packaging machinery fabricators. The vendor base stratifies across three tiers: multinational hospital automation platforms with software-anchored ecosystems, regional specialists in compact robotic dispensing, and European precision machinery houses with isolator expertise. Dominant competitive moves include backward integration into medication tracking software and cloud-native inventory platform bundling to lock in multi-year service contracts.
Within the diversified medical technology tier, Becton, Dickinson and Company and Omnicell, Inc. exemplify platform strategies that embed hardware within broader medication management ecosystems. Japanese specialists Yuyama Manufacturing Co., Ltd. and TOSHO Inc. occupy positions in compact robotic dispensers optimized for dense urban pharmacy footprints. Swisslog Holding AG represents the European automation engineering archetype with intralogistics heritage applied to pharmacy workflow integration. These named entities anchor competitive dynamics without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Yuyama Manufacturing Co., Ltd. |
| TOSHO Inc. |
| Omnicell, Inc. |
| Becton, Dickinson and Company |
| Takazono Corporation |
| Swisslog Holding AG |
| Parata Systems |
| JVM Co., Ltd. |
| Marchesini Group S.p.A. |
| Others |
Supply Flow & Price Mechanics
Four-to-six-month validation timelines for FDA 21 CFR Part 11 software compliance compress pricing power for integrated system vendors while amplifying cost pass-through leverage for precision component suppliers in Germany and Japan. This lead-time band concentrates procurement decisions among consolidated United States hospital networks that extract multi-site pricing leverage through bundled hardware-software contracts.
Pricing Analysis
Hospital pharmacy buyers anchor a three-tier pricing structure across premium isolator-integrated lines, standard automatic blister systems, and economy semi-automatic equipment. Price differentiation separates FDA-validated configurations with track-and-trace serialization from non-compliant legacy alternatives and from CE-marked European isolator systems. Cost compression in mid-tier equipment intensifies because stainless steel and electronic component input volatility erodes fabricator margins. Independent retail pharmacies exhibit highest price sensitivity, while consolidated health systems with enterprise automation tenders command volume discounts.
Supply Chain Analysis
Strait of Malacca transit routes underpin component logistics for precision motion control systems sourced from Nagoya and Kyoto engineering clusters. Supply concentrates in Germany for high-throughput isolator-integrated sterile compounding lines, Japan for compact robotic dispensers, and the United States for cloud-native inventory platform integration. Raw material dependencies include medical-grade stainless steel, PLC controllers, and vision system sensors. Single-source vulnerability in precision linear actuator production creates chokepoint exposure. Distribution runs through regional equipment distributors with validation expertise and direct OEM contracts for enterprise hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as pharmacy automation demand splinters across hospital consolidation, retail labor shortages, and contract packaging outsourcing—creating distinct vendor specialization niches that resist platform dominance.
For Market Incumbents: Fortify software-anchored ecosystem lock-in by bundling cloud-native inventory platforms with hardware contracts to counter third-party technical service organization disintermediation. Deepen backward integration into medication tracking software to defend margin pools against regional robotic dispenser specialists. Prioritize isolator-integrated line certification investments as USP <797> and <800> sterile compounding revisions approach. For New Entrants and Emerging Players: FDA 21 CFR Part 11 validation fast-tracks open white-space entry into contract packaging organization segments where rapid changeover capabilities and modular configurations outrank brand heritage. Target Indian CDSCO GMP upgrade timelines for isolator-integrated line first-mover positioning. Pursue outcome-based service contracts with IoT-enabled predictive maintenance as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core pharmacy automation divisions. Long-term viability centers on vendors with installed base density in 24-hour hospital pharmacy operations and recurring software revenue attachment. Monitor FDA DSCSA enforcement intensity as the signal to watch for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Inventory Platform Integration | Embeds dispensing machines within broader medication management ecosystems rather than standalone capital equipment sales. |
| Isolator-Integrated Line Certification | Positions vendors for USP <797> and <800> sterile compounding revisions without grandfathering existing installations. |
| Outcome-Based Service Contract Expansion | Converts IoT sensor data into multi-year recurring revenue streams that lock in customer retention. |
| Robotic Dispenser Compact Form Factor Development | Captures dense urban pharmacy footprints in Tokyo, Osaka, and tier-one Chinese cities facing space constraints. |
| Third-Party Technical Service Partnership | Addresses consolidated health system procurement preferences for vendor-agnostic maintenance coverage over OEM lock-in. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmacy directors, hospital procurement managers, biomedical engineers, GPO contracts managers, and equipment aftermarket service heads. Secondary validation drew from FDA 510(k) filings, EMA technical documentation, hospital procurement databases, GPO contract repositories, and SEC 10-K equipment segment disclosures. Bottom-up installed base estimates and top-down health system capital expenditure allocations were triangulated to reconcile volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions including automation tier, end-user concentration, product format specifications, and regional regulatory compliance clusters. CAGRs were derived from replacement cycle timing, health system consolidation trajectories, and labor shortage intensity indices. Forecast inputs incorporated FDA DSCSA enforcement schedules, EU MDR traceability phase-ins, and CDSCO domestic GMP upgrade timelines.
Underlying assumptions cover stable stainless steel input pricing and sustained hospital network consolidation velocity, with deviation risk concentrated in validation timeline extensions and robotics technician talent scarcity. Practitioners should keep alternative scenarios live as USP sterile compounding revision finalization and EU F-Gas Regulation enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market