
 Pharmaceutical HDPE Bottle Market | 2026-2036
Pharmaceutical HDPE Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical HDPE Bottle Market Insights
Buyer concentration among large drug manufacturers is decoupling from the long-tail of specialty pharmaceutical startups, fragmenting procurement patterns across two distinct volume tiers. Berry Global Inc. leverages its multi-site blow molding footprint to anchor supply contracts with top-tier generics producers. Amcor plc sustains R&D intensity in barrier-enhanced HDPE formulations for moisture-sensitive compounds. Graham Packaging Company competes through regional manufacturing scale that reduces freight costs for mid-size drug manufacturers.
Pharmaceutical HDPE bottles are high-density polyethylene containers engineered with specific wall thicknesses, dimensional stability, and chemical resistance profiles to protect oral solid and liquid dosage forms from moisture, oxygen, and light degradation; blow molding and injection-stretch blow molding dominate production, with resin grades selected against USP Class VI and EP 3.1.3 extraction limits. Child-resistant bottles lead the product type category due to Poison Prevention Packaging Act compliance requirements in North American supply chains. The 100ml capacity segment captures significant margin pools from chronic medication packaging where patient adherence programs drive consistent reorder volumes. Screw caps dominate closure type demand in institutional channels, though pump dispensers are gaining traction in ophthalmic and pediatric liquid formulations.
FDA enforces current Good Manufacturing Practice standards that mandate container closure integrity validation and extractables-leachables documentation for all primary packaging materials. The European Medicines Agency applies CE marking and MDR traceability rules that push HDPE bottle suppliers toward integrated serialization capabilities. India's Central Drugs Standard Control Organization requires BIS-certified resin sourcing for export-oriented pharmaceutical packaging operations. Stakeholders must monitor how tightening pharmacopeial harmonization between USP, EP, and ICH Q3D guidelines reshapes material qualification timelines and supplier audit burdens.
Market Dynamics
Generic drug manufacturers in India and contract packaging operations across emerging manufacturing clusters are consolidating procurement volumes, forcing HDPE bottle suppliers to reconfigure production footprints around pharmacopeial harmonization timelines rather than regional cost arbitrage alone.
Growth Catalysts
- CDSCO export certification mandates:India's regulator now requires BIS-certified resin documentation for pharmaceutical packaging bound for regulated markets, accelerating formal channel adoption among contract manufacturers serving EU and US buyers.
- Barrier-enhanced resin formulations:Moisture-sensitive biologics and fixed-dose combination tablets are driving specification upgrades to multilayer HDPE structures with EVOH or nylon interlayers.
- Chronic medication adherence programs:Patient support initiatives from diabetes and cardiovascular drug marketers are generating consistent reorder volumes for 100ml and 200ml child-resistant bottles.
Market Restraints
- Polyethylene resin price volatility:Naphtha-linked feedstock costs and regional cracker maintenance cycles create margin compression for converters locked into annual supply contracts with drug manufacturers.
- Pharmacopeial extraction limit divergence:Misalignment between USP Class VI and EP 3.1.3 testing protocols forces redundant qualification batches, extending material approval timelines.
- Glass and COP vial substitution:Parenteral and high-value oral liquid formulations are migrating to cyclic olefin polymer containers with superior oxygen barrier properties.
Strategic Opportunities
- Serialization-integrated bottle production:EU MDR traceability rules are creating first-mover advantage for blow molders with in-house laser marking and aggregation station capabilities.
- Pediatric liquid dosing formats:Ophthalmic and antihistamine syrups are shifting from standard screw caps to metered pump dispensers with dose-counting features.
- Domestic Indian contract packaging:CDSCO's tightened oversight of export-oriented facilities is displacing informal suppliers, consolidating volume among qualified regional converters.
Industry Challenges
- Extractables-leachables documentation gaps:Smaller converters lack analytical chemistry capabilities to generate ICH Q3D elemental impurity profiles required by FDA stability testing protocols.
- Blow molding technician scarcity:Process optimization for thin-wall pharmaceutical containers with dimensional stability tolerances requires specialized extrusion expertise concentrated among aging workforces in traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical HDPE Bottle Market |
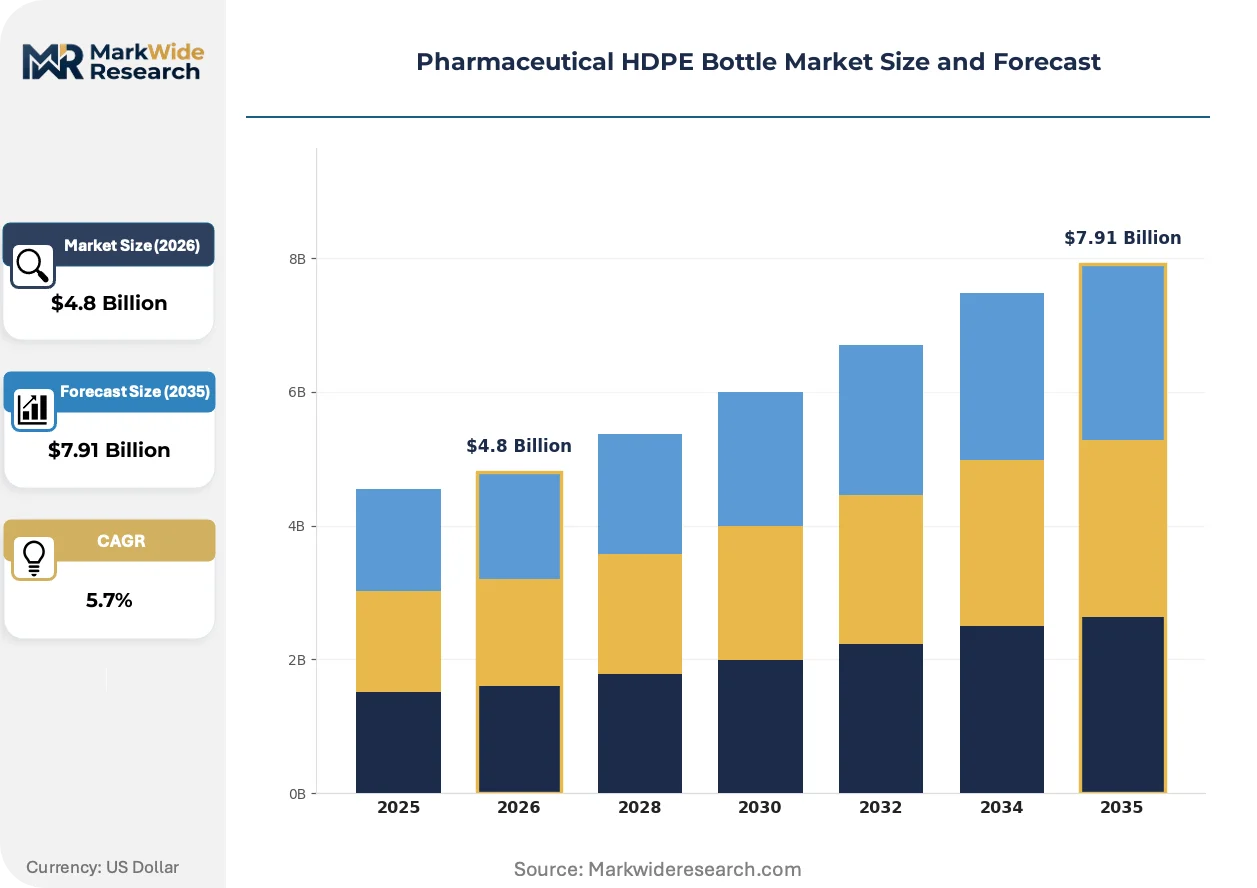
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bottles, Child-Resistant Bottles, Squeeze Bottles, Dropper Bottles Capacity: 30ml, 60ml, 100ml, 250ml Closure Type: Screw Caps, Snap Caps, Pump Dispensers, Spout Caps End User: Pharmacies, Hospitals, Clinics, Drug Manufacturers |
| Companies Covered | Berry Global Inc., Amcor plc, Graham Packaging Company, ALPLA Werke Alwin Lehner GmbH & Co KG, Plastipak Holdings, Inc, Gerresheimer AG, Drug Plastics Group, Alpack Plastics, Dahl-Tech, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical HDPE Bottle Market Trends and Innovations
Active pharmaceutical ingredient stability requirements and patient safety mandates are converging to reshape material specifications, manufacturing processes, and supplier qualification protocols across oral solid and liquid dosage packaging.
Multilayer coextrusion blow molding is expanding into moisture-sensitive chronic medication segments previously dominated by desiccant-capped single-layer bottles. Generic manufacturers in India and Southeast Asia are adopting these structures for fixed-dose combination tablets vulnerable to hydrolytic degradation. The technology is expanding into mid-tier contract packaging operations that previously avoided capital-intensive barrier solutions.
EMA's Medical Device Regulation traceability mandates now require Unique Device Identification on primary pharmaceutical containers, compelling HDPE bottle suppliers to integrate serialization hardware directly into production lines. European generics marketers are consolidating supplier bases around converters with verified aggregation capabilities. The regulatory pressure is compressing qualification timelines for blow molders lacking established track-and-trace infrastructure.
Hospital and long-term care procurement committees are consolidating purchasing authority previously dispersed across pharmacy, materials management, and infection control departments. This concentration is displacing fragmented spot-buying patterns with multi-year framework agreements specifying child-resistant certification and supplier audit documentation. The shift is most visible in US institutional channels where group purchasing organizations now mandate Poison Prevention Packaging Act compliance certificates at contract inception.
Pharmaceutical HDPE Bottle Market Segmentation
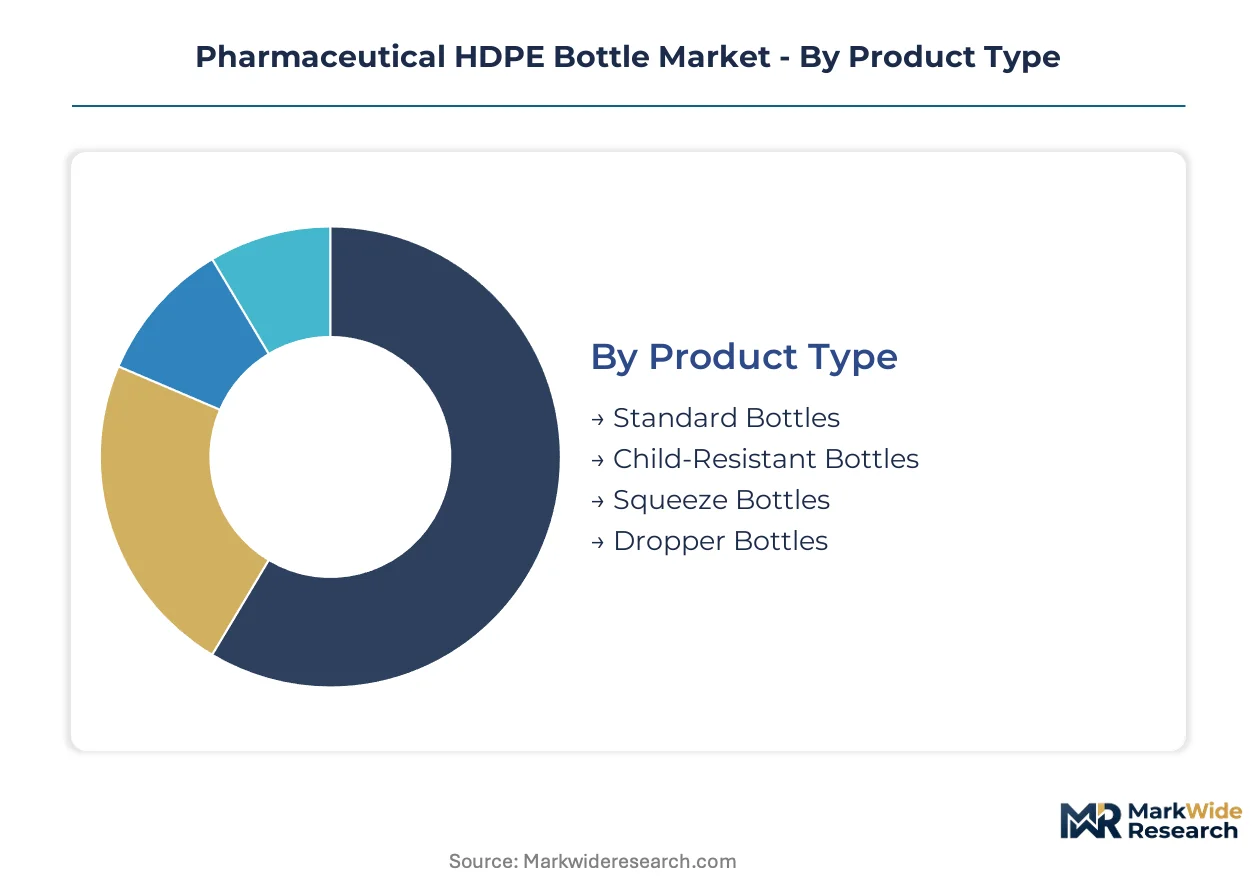
Pharmaceutical HDPE bottle segmentation reflects divergent compliance burdens and volume economics across packaging formats. Procurement patterns split between high-volume oral solid dosage programs and specialized liquid delivery systems with stringent barrier requirements.
Product Type:
Volume tiers separate commodity oral solid containers from premium child-resistant and precision-dosing formats with regulatory certification overhead.
- Child-Resistant Bottles:Engineered with dual-action closure mechanisms meeting Poison Prevention Packaging Act torque specifications. Demand concentrates among US generic manufacturers supplying chronic cardiovascular and diabetes medications where patient safety litigation exposure drives specification rigidity. FDA compliance documentation requirements extend supplier qualification timelines.
- Standard Bottles:Single-layer HDPE construction optimized for cost-efficient oral solid dosage packaging with basic moisture protection. Indian contract manufacturers serving EU export markets favor these formats for high-volume antibiotic and analgesic portfolios where margin compression limits barrier technology adoption. CDSCO BIS certification mandates nonetheless tighten resin traceability requirements.
- Squeeze Bottles:Flexible wall construction with controlled deformation characteristics for viscous liquid formulations.
- Dropper Bottles:Precision-orifice designs with integrated pipette assemblies for ophthalmic and pediatric applications.
Today's leader: Child-Resistant Bottles. Tomorrow's challenger: Squeeze Bottles.
Capacity:
Prescription duration and patient adherence program structures determine volume selection across acute versus chronic therapy packaging.
- 100ml:Mid-range capacity capturing 30-day supply protocols for hypertension and cholesterol management regimens. German hospital pharmacies and US mail-order distributors specify this format for automated dispensing compatibility. Patient support program reorder cycles generate predictable demand streams.
- 30ml:Compact format engineered for acute antibiotic courses and travel-size pharmaceutical kits. Southeast Asian contract manufacturers favor this capacity for export-oriented tropical disease medications where portability and cost minimization converge. Limited headspace reduces oxidative degradation risk for sensitive APIs.
- 60ml:Intermediate volume serving pediatric liquid formulations and short-duration specialty therapies.
- 250ml:Extended-supply format for institutional chronic disease management and veterinary pharmaceutical applications.
Adherence economics favor 100ml. Emerging market cost sensitivity elevates 30ml.
Closure Type:
Dosing precision requirements and user demographics separate institutional screw-cap standards from consumer-facing pump and spout innovations.
- Screw Caps:Threaded closure systems with tamper-evident ring configurations dominating hospital and pharmacy institutional procurement. US group purchasing organizations mandate child-resistant certification at contract inception, consolidating supplier bases around validated torque-testing documentation. Long-term care facilities specify these closures for automated dispensing machine compatibility.
- Pump Dispensers:Metered-dose mechanisms with dose-counting features gaining traction in ophthalmic antihistamine and pediatric cough syrup segments. European generics marketers specify these for over-the-counter differentiation where patient convenience commands shelf price premiums. EMA MDR traceability rules push integration of serialization-ready closure platforms.
- Snap Caps:Hinged single-action closures for elderly-accessible packaging and institutional efficiency.
- Spout Caps:Directional flow designs for viscous suspensions and topical pharmaceutical preparations.
Institutional procurement anchors screw-cap dominance. Pediatric and ophthalmic segments accelerate pump adoption.
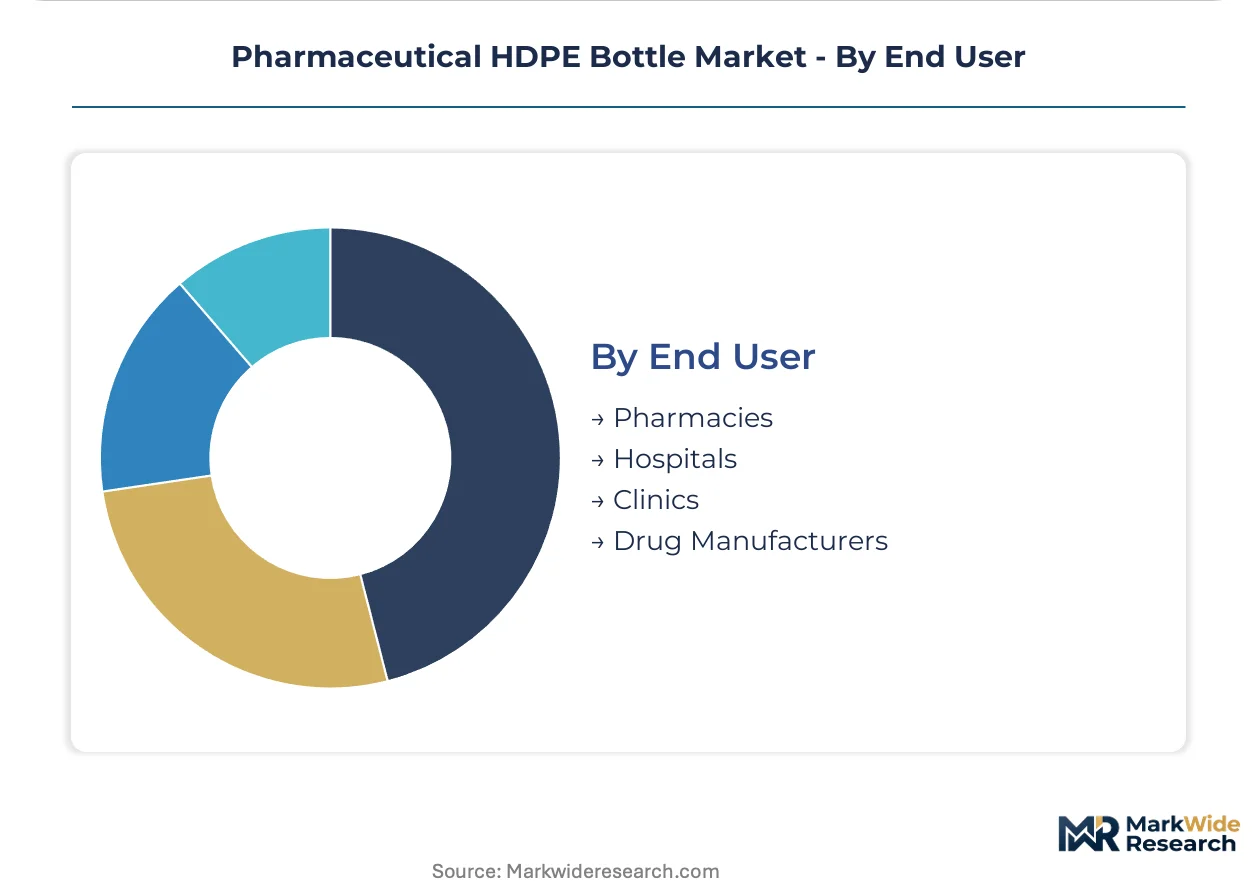
End User:
Regulatory audit intensity and volume concentration differentiate drug manufacturer direct procurement from fragmented institutional channel purchasing.
- Drug Manufacturers:Primary packaging buyers with integrated quality systems demanding extractables-leachables documentation and USP Class VI resin certification. Indian export-oriented generic houses consolidate procurement volumes among qualified regional converters with CDSCO-compliant BIS traceability. Multi-year framework agreements displace spot-buying patterns.
- Hospitals:Consolidated purchasing authority through pharmacy and materials management committees specifying child-resistant certification and supplier audit documentation. German university hospitals and US integrated delivery networks drive standardization around 100ml and 250ml formats for automated dispensing.
- Pharmacies:Dispensing channel with mixed independent and chain configurations driving regional packaging preferences.
- Clinics:Outpatient settings with limited storage capacity favoring compact 30ml and 60ml formats for immediate dispensing.
Manufacturer direct procurement commands premium compliance standards. Hospital consolidation reshapes institutional specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blow molding technicians with USP Class VI certification cluster around Mumbai, New Jersey, and Düsseldorf, anchoring regional production quality for export-oriented pharmaceutical packaging.
United States
Generic drug manufacturers in New Jersey and Pennsylvania drive child-resistant bottle demand for chronic cardiovascular therapies. FDA enforces current Good Manufacturing Practice standards mandating container closure integrity validation. Philadelphia-area contract packaging facilities are expanding blow molding capacity to serve mail-order pharmacy distributors.
Germany
Hospital pharmacy automation in Bavaria and North Rhine-Westphalia standardizes procurement around 100ml and 250ml formats. EMA applies MDR traceability rules pushing HDPE suppliers toward integrated serialization capabilities. The Düsseldorf-Ruhr industrial corridor concentrates barrier-enhanced resin formulation R&D for moisture-sensitive biologics.
India
CDSCO-compliant contract manufacturers in Maharashtra and Gujarat scale export-oriented production for EU and US buyers. India's regulator now requires BIS-certified resin documentation for pharmaceutical packaging bound for regulated markets. The Baddi-Barotiwala-Nalagarh pharmaceutical hub is consolidating procurement volumes among qualified regional converters.
China
Domestic generic houses in Jiangsu and Zhejiang provinces drive standard bottle demand for antibiotic portfolios. NMPA stability testing guidelines align with ICH Q3D elemental impurity protocols. The Yangtze River Delta pharmaceutical cluster is absorbing multilayer coextrusion technology from European equipment suppliers.
Switzerland
Specialty pharmaceutical packaging for high-value oral liquids concentrates around Basel and Zurich logistics corridors. Swissmedic enforces pharmacopeial harmonization between USP and EP extraction limits. The Basel biotech cluster is sourcing barrier-enhanced HDPE structures for fixed-dose combination tablets vulnerable to hydrolytic degradation.
Pharmaceutical HDPE Bottle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Large multi-site converters anchor supply contracts through geographic proximity to generic manufacturing clusters, while regional specialists capture mid-tier volumes through flexible qualification timelines. Strategic archetypes separate barrier-technology leaders, serialization-integrated producers, and cost-optimized commodity suppliers. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves reshaping supplier positioning.
Among North American diversified packaging conglomerates, Berry Global Inc. and Graham Packaging Company exemplify the multi-site blow molding archetype serving top-tier generics producers. Amcor plc occupies a position within the barrier-enhanced formulation tier, sustaining R&D intensity for moisture-sensitive compound applications. ALPLA Werke Alwin Lehner GmbH & Co KG represents European specialist engineering with regional manufacturing scale reducing freight costs for mid-size drug manufacturers.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Graham Packaging Company |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Plastipak Holdings, Inc |
| Gerresheimer AG |
| Drug Plastics Group |
| Alpack Plastics |
| Dahl-Tech, Inc |
| Others |
Pricing and Supply Chain Analysis
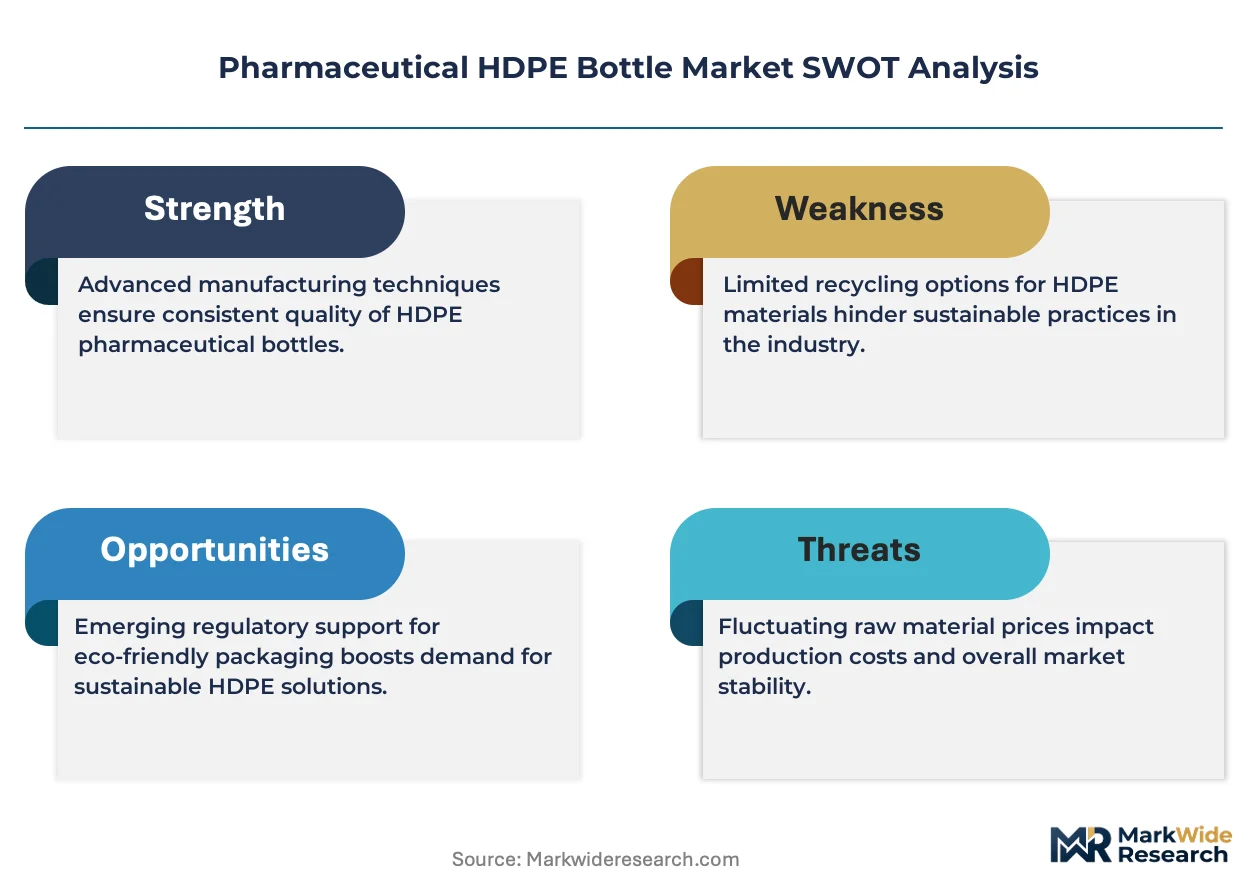
Backward integration into resin compounding anchors supply position for large converters while compressing pricing power for mid-tier competitors dependent on spot naphtha-linked feedstock purchases. CDSCO certification mandates in India and FDA stability testing protocols in the United States fragment procurement tiers, with qualified suppliers commanding premium positioning against uncertified regional converters.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard oral solid dosage bottles serving export-oriented generic manufacturers. Three-tier pricing structure across barrier-enhanced, child-resistant certified, and commodity standard levels reflects USP Class VI documentation burdens and BIS traceability requirements. Cost compression in the commodity tier intensifies because naphtha-linked polyethylene resin volatility transfers directly to converters locked into annual drug manufacturer contracts. Hospital group purchasing organizations exhibit lowest price sensitivity due to mandated compliance documentation, while Indian contract manufacturers serving EU export markets face acute margin pressure.
Supply Chain Analysis
Blow molding technician scarcity in the Düsseldorf-Ruhr corridor and Mumbai pharmaceutical clusters constrains qualified production expansion for thin-wall pharmaceutical containers with dimensional stability tolerances. Manufacturing concentrates in India, Germany, and the United States, with each geography feeding distinct regulatory compliance tiers. Raw material sourcing draws from Saudi and US Gulf Coast polyethylene resin suppliers, with EVOH and nylon interlayer additives sourced from European specialty chemical producers. Single-source vulnerability runs through BIS-certified resin documentation required by CDSCO for export-oriented operations. Distribution runs through drug manufacturer direct procurement channels, hospital group purchasing organizations, and regional contract packaging intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical HDPE bottle demand functions as a stable compounder anchored by chronic medication adherence programs that generate predictable reorder cycles for cardiovascular and diabetes packaging formats.
For Market Incumbents: Anticipate glass and COP vial substitution in high-value oral liquid segments by accelerating multilayer coextrusion R&D for moisture-sensitive biologics. Defensive consolidation through captive resin compounding capacity in India and Germany insulates margin structures against naphtha price volatility. Serialization-integrated production lines with laser marking capabilities capture EU MDR traceability mandates that displace unqualified regional competitors. For New Entrants and Emerging Players: Launch via CDSCO-compliant contract packaging partnerships serving Maharashtra and Gujarat export corridors where informal supplier displacement creates volume consolidation opportunities. Target pediatric liquid dosing formats with metered pump dispensers for ophthalmic and antihistamine segments where patient convenience commands shelf price premiums. White-space exists in 30ml compact formats for Southeast Asian tropical disease medications where portability and cost minimization converge. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialists with verified USP Class VI certification because pharmacopeial harmonization between FDA and EMA protocols extends supplier qualification timelines beyond smaller converter capabilities. Long-term viability rests on barrier-enhanced formulation expertise and integrated serialization infrastructure rather than commodity scale alone. Watch for ICH Q3D elemental impurity profile documentation gaps as a signal for distressed acquisition opportunities among analytical chemistry-deficient regional players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates margin structures against naphtha-linked feedstock volatility for large converters. |
| Serialization-Integrated Production Lines | Laser marking and aggregation capabilities satisfy EU MDR traceability mandates that displace unqualified blow molders. |
| Multilayer Coextrusion Capacity Expansion | EVOH and nylon interlayer technology addresses moisture-sensitive biologics previously served by desiccant-capped single-layer bottles. |
| CDSCO Certification Investment | BIS-certified resin documentation unlocks export-oriented contract packaging volumes from Maharashtra and Gujarat clusters. |
| Pediatric Dosing Format Development | Metered pump dispensers with dose-counting features capture ophthalmic and antihistamine segment shelf price premiums. |
Research Methodology
Multiple input streams — primary interviews with blow molding operations managers, regulatory affairs leads at generic drug manufacturers, and hospital pharmacy procurement directors; secondary validation through FDA 483 observations, EMA MDR guidance documents, and CDSCO export certification records; customs and trade data from Indian pharmaceutical packaging corridors — were reconciled through bottom-up and top-down triangulation to establish volume and value baselines.
Historical capacity utilization patterns across Düsseldorf, Mumbai, and New Jersey manufacturing clusters were cross-referenced against panel input from resin procurement specialists and blow molding equipment suppliers. Segmentation dimensions modeled include product type, capacity tier, closure mechanism, and regional regulatory cluster. CAGRs were derived from regression analysis of oral solid dosage packaging volumes against generic drug approval pipelines and chronic medication adherence program expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyethylene resin price volatility and pharmacopeial extraction limit divergence scenarios. Forecasts reflect documented assumptions regarding CDSCO enforcement intensity and EU MDR traceability implementation timelines. Material deviation in USP-EP harmonization progress or sudden feedstock cost spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Pharma Packaging Films Market