
 Wax Paper Medicine Pots Market | 2026-2036
Wax Paper Medicine Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Paper Medicine Pots Market Analytics
Multi-source procurement among European pharmacy wholesalers is consolidating around contract manufacturers with dedicated pharmaceutical packaging lines. JFA Medical leverages its NHS supply agreements to anchor distribution across England's primary care networks. Caretex competes through specialized wax-coating formulations that meet British Pharmacopoeia moisture-barrier specifications. Origin Pharma sustains its position by controlling dispensing-box packaging workflows that integrate directly with automated pharmacy fulfillment systems.
Wax paper medicine pots are cylindrical containers fabricated from kraft paper substrates laminated with food-grade paraffin or vegetable-based wax barriers, engineered to contain solid oral doses while resisting moisture penetration during typical seven-day dispensing cycles. Standard Pots still generate the bulk of volume, though Biodegradable Pots are capturing margin pools as NHS trusts and German hospital groups embed sustainability criteria into tender evaluations. Specialty Containers command premium positioning in research labs and clinical trial settings where tamper-evident features and custom sizing reduce dispensing errors.
The EU Green Deal and REACH frameworks restrict certain paraffin wax chemistries, while the F-Gas Regulation indirectly pressures converters toward bio-based coating alternatives. Germany's national packaging regulator and the UK's Medicines and Healthcare products Regulatory Agency both enforce child-resistant and labeling standards that shape pot geometry and print-area specifications. Stakeholders must monitor how pending revisions to the EU Packaging and Packaging Waste Regulation redefine compostability certification requirements for single-dose dispensers.
Market Dynamics
EU Green Deal packaging waste directives are forcing pharmaceutical supply chains to abandon petroleum-based paraffin coatings in favor of certified compostable alternatives, compressing converter margins while rewiring raw material sourcing patterns across Northern European manufacturing clusters.
Growth Catalysts
- REACH chemical restrictions:The European Chemicals Agency's tightening controls on mineral oil saturated hydrocarbons in food-contact materials are accelerating vegetable-based wax formulation adoption among coating specialists serving NHS and German hospital networks.
- Community pharmacy consolidation:England's primary care networks are centralizing dispensing procurement through regional pharmacy hubs, creating volume anchors that justify dedicated pharmaceutical-grade production lines at contract manufacturers.
- Automated fulfillment integration:Robotic dispensing systems in German hospital pharmacies now require dimensionally standardized pots with machine-readable labeling, pulling demand toward precision-molded formats with tight tolerance specifications.
Market Restraints
- Vegetable wax feedstock volatility:Carnauba and candelilla wax prices fluctuate with Brazilian and Mexican harvest cycles, exposing converters to margin compression when pharmaceutical customers resist price pass-through clauses.
- Coating equipment concentration:Specialist wax-lamination machinery for pharmaceutical-grade moisture barriers is manufactured by a narrow base of German and Italian equipment suppliers, creating bottleneck risk for capacity expansion.
- Compostable certification lag:Industrial compostability validation under EN 13432 requires six-to-nine-month testing cycles at accredited laboratories, delaying product launches for converters switching from conventional paraffin formulations.
Strategic Opportunities
- Clinical trial logistics:Contract research organizations managing multi-site pharmaceutical studies require tamper-evident, batch-coded pots with custom sizing for investigational drug dispensing, commanding price premiums above standard NHS contract rates.
- Extended Producer Responsibility schemes:Germany's national packaging regulator is tightening fee modulation rules that reward compostable formats with lower compliance contributions, incentivizing converters to accelerate bio-based coating transitions.
- Homecare dispensing channels:Direct-to-patient medication management services in England are sourcing patient-friendly packaging with simplified opening mechanisms for elderly users, opening design differentiation beyond hospital procurement specifications.
Industry Challenges
- Pharmaceutical validation timelines:New coating chemistries require stability testing under ICH guidelines to demonstrate no extractables migration into solid oral doses, extending qualification periods before commercial supply approval.
- Print-area compliance complexity:The UK's Medicines and Healthcare products Regulatory Agency enforces specific font sizes and symbol placements for dosage instructions that conflict with automated labeling equipment formats designed for continental European specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Paper Medicine Pots Market |
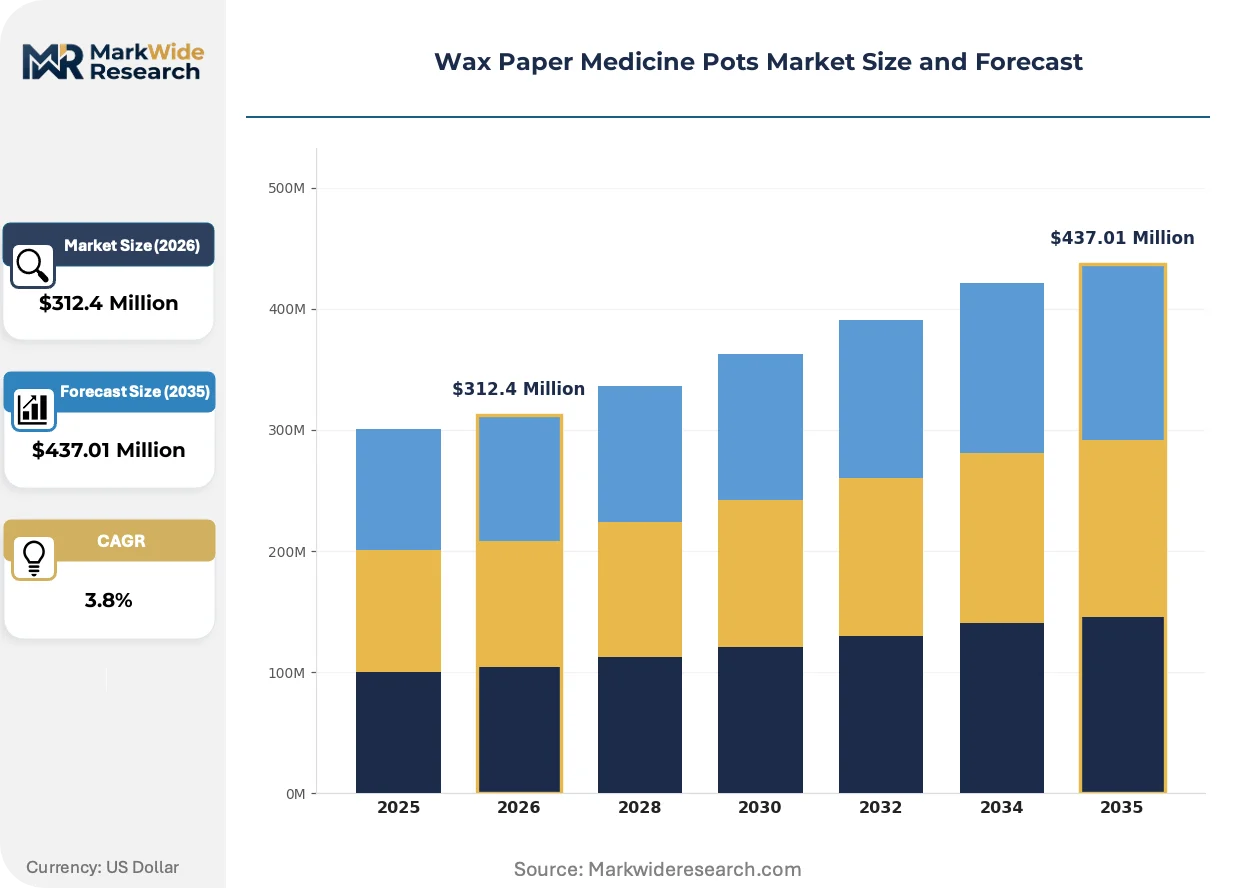
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pots, Biodegradable Pots, Specialty Containers, Bulk Packs End User: Pharmacies, Hospitals, Home Care, Research Labs Material: Recyclable Paper, Coated Paper, Waxed Paper, Compostable Materials Packaging Type: Dispensing Boxes, Shrink Wrapping, Individual Packs, Printed Sleeves |
| Companies Covered | JFA Medical, Caretex, Genware, BIOZOYG, Origin Pharma, Solo Cups, Riverside Paper Co., Inc., Acorn Paper Products, AMTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Paper Medicine Pots Market Evolving Landscape
Coating technology convergence with pharmaceutical automation requirements is compressing product development cycles while regulatory chemistry restrictions are fragmenting the supplier base into bio-specialists and legacy paraffin operators.
Precision wax-lamination systems with real-time thickness monitoring are automating quality control for moisture-barrier consistency that automated pharmacy robots demand. German hospital procurement consortia now specify maximum variance thresholds of 0.05 millimeters in wall thickness to prevent jamming in high-speed dispensing lines. This automation is compressing the viable supplier base to converters with capital-intensive coating equipment capable of pharmaceutical-grade repeatability.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing coating reformulations across European pharmaceutical packaging supply chains. The regulation's 2025 enforcement timeline is accelerating laboratory testing budgets at converters still reliant on paraffin wax blends. Specialty container segments serving clinical trial markets are absorbing the highest compliance costs due to smaller batch sizes and documentation intensity.
Hospital pharmacy buying groups are consolidating annual pot contracts into multi-year framework agreements with sustainability-linked pricing mechanisms. England's NHS Supply Chain now embeds carbon footprint scoring into tender evaluations, weighting compostable certification equally with unit cost. German hospital procurement has moved fastest, with several university medical centers mandating bio-based coatings for all new dispensing contracts regardless of price premium.
Wax Paper Medicine Pots Market Segmentation
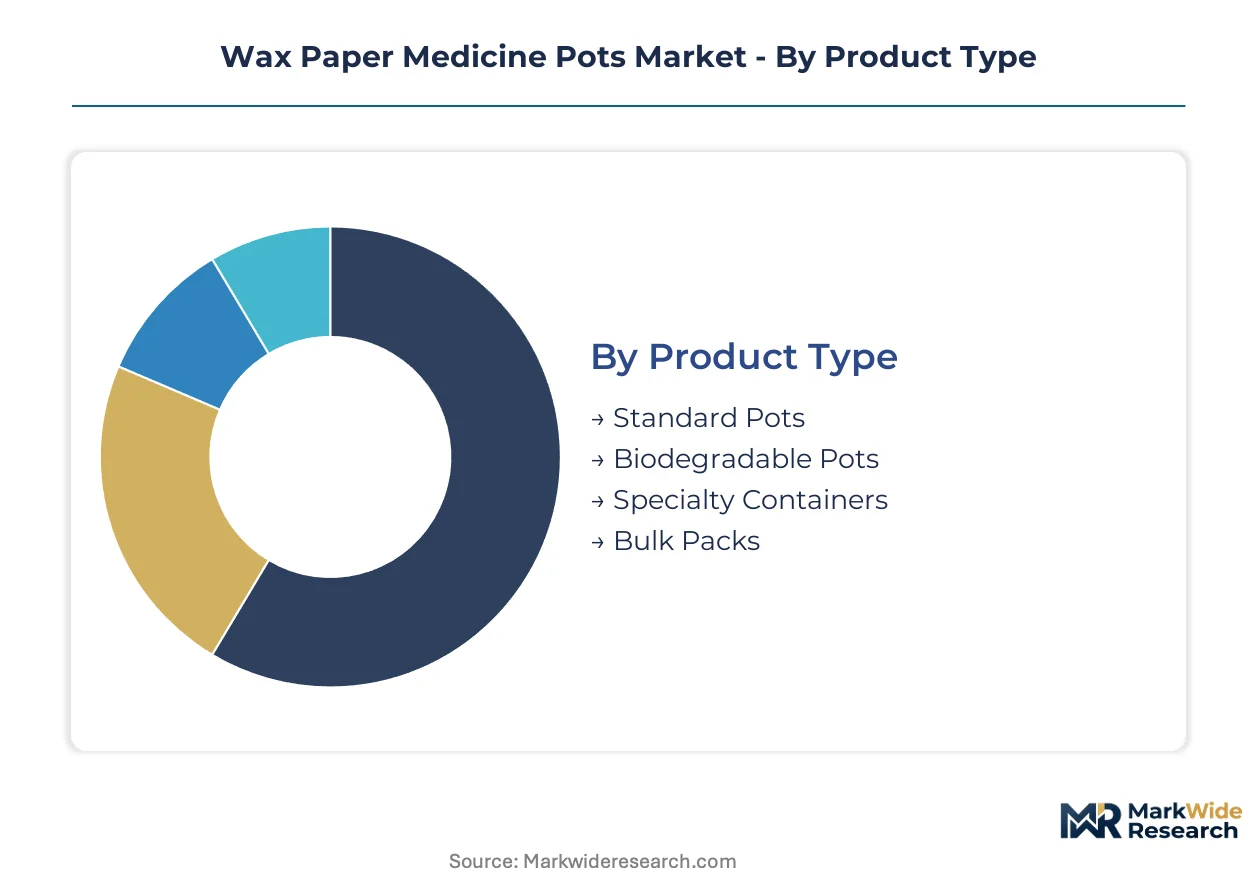
Wax paper medicine pots serve distinct operational requirements across pharmaceutical supply chains. Procurement specifications diverge sharply between high-volume hospital automation and precision clinical trial workflows. Understanding these segment boundaries clarifies where coating technology investments and regulatory compliance burdens concentrate.
Product Type:
Buyers differentiate primarily by sustainability mandates and automation compatibility rather than unit cost alone.
- Standard Pots:These cylindrical containers use kraft paper substrates laminated with paraffin wax barriers to resist moisture penetration during seven-day dispensing cycles. England's NHS Supply Chain and German hospital procurement consortia anchor volume demand, though REACH chemical restrictions on mineral oil saturated hydrocarbons are forcing coating reformulations.
- Biodegradable Pots:Vegetable-based wax formulations replace petroleum-derived coatings to meet EU Green Deal packaging waste directives. NHS trusts now embed compostable certification equally with unit cost in tender evaluations, compressing converter margins while rewiring raw material sourcing patterns across Northern European manufacturing clusters.
- Specialty Containers:Tamper-evident features and custom sizing serve research labs and clinical trial settings where batch coding reduces dispensing errors.
- Bulk Packs:High-count configurations target regional pharmacy hubs consolidating procurement through England's primary care networks.
Volume sits with Standard Pots; growth tilts toward Biodegradable Pots.
End User:
Automation intensity and regulatory scrutiny create divergent purchasing power across buyer categories.
- Pharmacies:Community pharmacy consolidation in England and Germany is centralizing dispensing procurement through regional hubs. Robotic dispensing systems now require dimensionally standardized pots with machine-readable labeling, pulling demand toward precision-molded formats.
- Hospitals:German university medical centers mandate bio-based coatings for all new dispensing contracts regardless of price premium. Procurement consortia specify maximum variance thresholds of 0.05 millimeters in wall thickness to prevent jamming in high-speed lines.
- Home Care:Direct-to-patient medication management services source patient-friendly packaging with simplified opening mechanisms for elderly users.
- Research Labs:Contract research organizations require custom sizing for investigational drug dispensing, commanding price premiums above standard NHS contract rates.
Procurement concentration favors Hospitals; Home Care channels are expanding most quickly.
Material:
Feedstock certification status increasingly determines supplier qualification for pharmaceutical contracts.
- Recyclable Paper:Kraft substrates meet baseline structural requirements but lack moisture barriers without supplemental coating layers.
- Coated Paper:Polymer barriers provide pharmaceutical-grade protection though face scrutiny under Extended Producer Responsibility fee modulation rules.
- Waxed Paper:Paraffin and vegetable-based wax laminations dominate current production, with ECHA restrictions accelerating transitions toward bio-based alternatives.
- Compostable Materials:EN 13432 certification requires six-to-nine-month validation cycles at accredited laboratories, delaying product launches for converters switching from conventional formulations.
Waxed Paper maintains installed base dominance; Compostable Materials face steepest expansion trajectory pending certification backlog resolution.
Packaging Type:
Integration with automated fulfillment systems dictates format selection more than protection requirements.
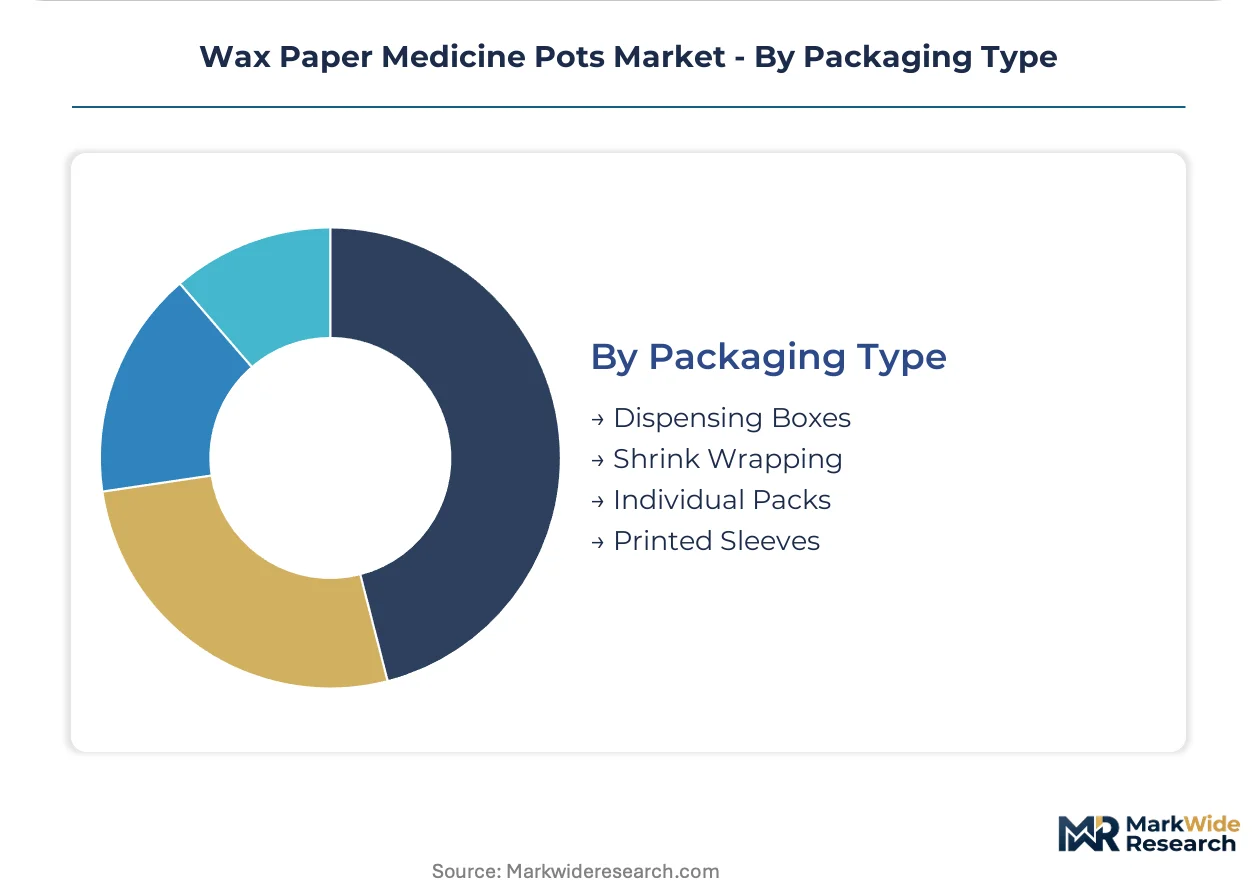
- Dispensing Boxes:Integrated packaging workflows connect directly with automated pharmacy fulfillment systems, requiring tight tolerance specifications for robotic handling.
- Shrink Wrapping:Unitization for bulk distribution serves hospital procurement consortia managing centralized warehouse operations.
- Individual Packs:Single-dose configurations align with homecare dispensing channels and patient-specific medication management protocols.
- Printed Sleeves:Variable data printing accommodates batch coding for clinical trial logistics where documentation intensity absorbs highest compliance costs.
Dispensing Boxes capture automation-driven volume; Individual Packs gain share fastest in direct-to-patient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kraft paper feedstock from Scandinavian forestry operations anchors Northern European supply chains for wax-laminated pharmaceutical packaging. Germany and the United Kingdom concentrate procurement volume through hospital consortia and national health service networks. Regulatory chemistry restrictions and automation requirements are fragmenting converter bases across manufacturing clusters.
Germany
University medical centers in Munich and Hamburg mandate bio-based wax coatings for all new dispensing contracts regardless of price premium. The national packaging regulator enforces Extended Producer Responsibility fee modulation rules that reward compostable formats with lower compliance contributions. Precision coating equipment manufacturers in Bavaria supply lamination machinery with real-time thickness monitoring to pharmaceutical-grade converters.
United Kingdom
England's National Health Service Supply Chain embeds carbon footprint scoring equally with unit cost in tender evaluations for primary care network procurement. The Medicines and Healthcare products Regulatory Agency enforces specific font sizes and symbol placements for dosage instructions that shape pot geometry specifications. Manufacturing clusters in the Midlands and Yorkshire host contract converters with dedicated pharmaceutical packaging lines.
France
Hospital pharmacy buying groups in Paris and Lyon are consolidating annual pot contracts into multi-year framework agreements with sustainability-linked pricing mechanisms. ANSM enforces child-resistant and labeling standards that influence print-area specifications for automated dispensing systems. The Île-de-France region hosts converters transitioning from paraffin to vegetable-based wax formulations under REACH Annex XVII timelines.
Italy
Specialist wax-lamination machinery manufacturers in Milan and Bologna supply pharmaceutical-grade coating equipment to converters across Northern Europe. The national pharmaceutical regulator aligns with EMA guidance on extractables testing for new coating chemistries under ICH stability protocols. Emilia-Romagna hosts precision molding operations serving clinical trial logistics with tamper-evident container formats.
Netherlands
Distribution hubs in Rotterdam and Amsterdam serve as consolidation points for Benelux hospital procurement consortia sourcing standardized dispensing formats. The national packaging authority implements EU Green Deal waste directives through accelerated compostable certification pathways for single-dose dispensers. Randstad manufacturing clusters specialize in high-volume production for regional pharmacy wholesaler networks.
Wax Paper Medicine Pots Market Competitive Landscape
Strategic partnerships with automated pharmacy equipment vendors dominate the current competitive landscape for wax paper medicine pot supply. The vendor base separates into three tiers: national health service contract holders with dedicated pharmaceutical lines, specialty coating formulators with bio-based wax capabilities, and regional paper converters serving generic dispensing demand. Two strategic archetypes have emerged: sustainability-focused bio-coating specialists and automation-integrated precision molders. Competitive intensity centers on qualification speed for compostable certifications and tolerance specifications for robotic handling systems.
Among UK-based pharmaceutical packaging specialists, JFA Medical and Origin Pharma occupy positions within the NHS contract holder archetype, while Caretex exemplifies the coating formulation specialist tier. German and Italian equipment-integrated converters anchor the precision molding segment serving hospital automation requirements. These named entities represent the competitive structure without implying specific strategic actions, financial positions, or technology deployments beyond their visible market positioning.
| Leading Market Players |
|---|
| JFA Medical |
| Caretex |
| Genware |
| BIOZOYG |
| Origin Pharma |
| Solo Cups |
| Riverside Paper Co., Inc. |
| Acorn Paper Products |
| AMTEC |
| Others |
Value Network & Pricing Analysis
Vegetable wax feedstock costs from Brazilian carnauba and Mexican candelilla harvests cascade through coating formulation tiers into NHS contract pricing, where pharmaceutical buyers resist pass-through clauses and compress converter margins across Northern European manufacturing clusters.
Pricing Analysis
Compostable certification bundling separates quoted pot prices from legacy paraffin alternatives, with EN 13432 validation costs embedded in premium tiers for German hospital procurement. Price differentiation hinges on moisture-barrier grade and automation tolerance specifications, with robotic-compatible formats commanding sustained premiums. Cost compression in standard paraffin tiers is intensifying because REACH Annex XVII compliance is forcing reformulation investments. Community pharmacy hubs in England's primary care networks exhibit highest price sensitivity, while clinical trial logistics buyers absorb premiums for custom batch-coding and tamper-evident features.
Supply Chain Analysis
Dual-sourcing requirements from NHS Supply Chain and German hospital consortia mandate qualified backup converters across England's Midlands, Yorkshire, and Bavarian manufacturing clusters. Raw material dependencies center on Scandinavian kraft paper substrates, Brazilian carnauba wax, and German-Italian precision lamination equipment. Single-source vulnerability concentrates in specialist wax-coating machinery from Milan and Bologna suppliers. Distribution runs through regional pharmacy wholesaler networks and hospital procurement consortia with centralized warehouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
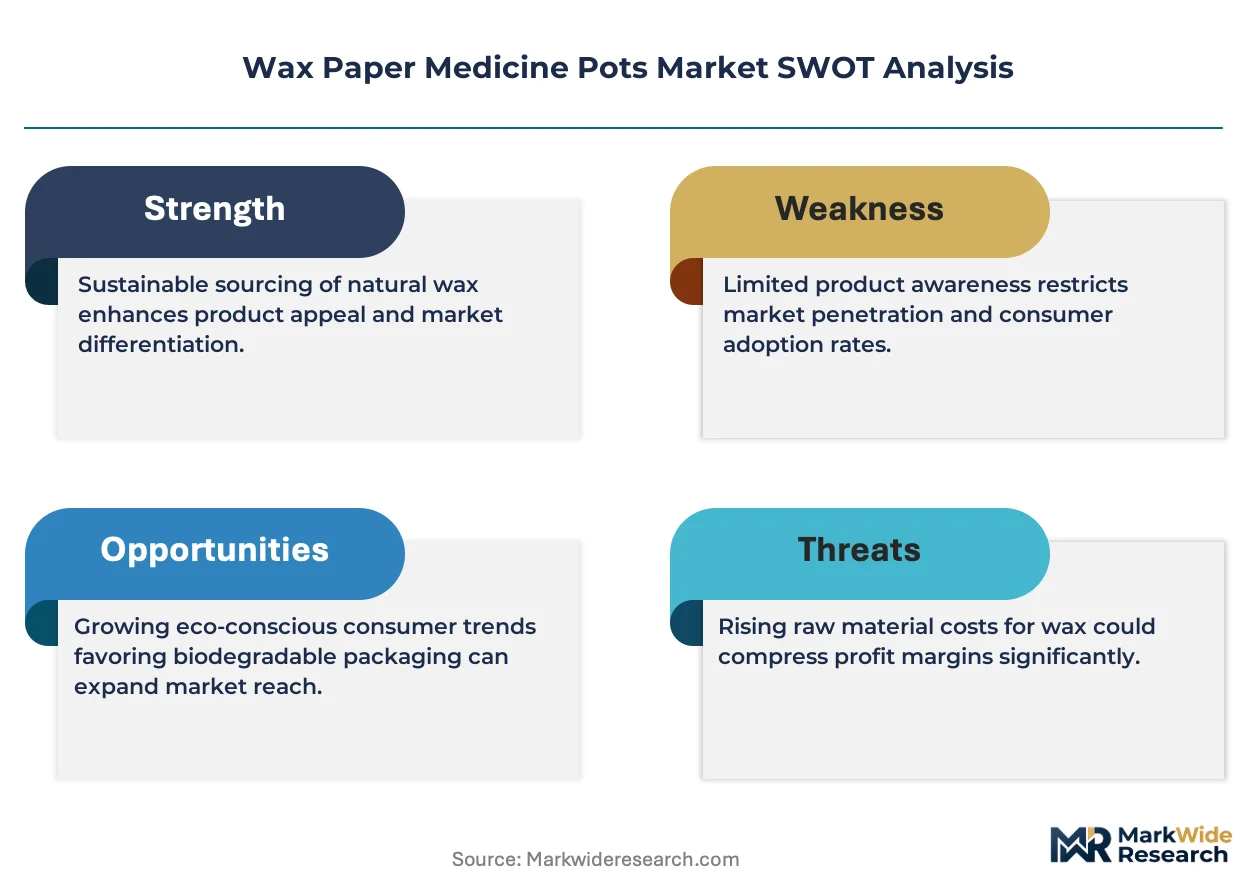
This market functions as a cost-of-compliance story where REACH chemical restrictions on mineral oil saturated hydrocarbons erect barrier-to-entry moats favoring converters with validated bio-based coating capabilities and accredited laboratory relationships.
For Market Incumbents: Acquire compostable certification capacity at accredited EN 13432 laboratories to preempt qualification bottlenecks. Consolidate coating equipment relationships with Bavarian and Italian machinery suppliers before capacity constraints harden. Defensive positioning requires backward integration into vegetable wax supply agreements with Brazilian and Mexican harvest cooperatives, insulating against feedstock volatility that emerging bio-specialists cannot match.
For New Entrants and Emerging Players: Precision wax-lamination automation technology offers entry wedge into German hospital pharmacy consortia demanding 0.05 millimeter wall thickness tolerances. Target England's homecare dispensing channel where patient-friendly packaging with simplified opening mechanisms remains underpenetrated by incumbent automation-focused suppliers. Go-to-market execution should anchor on direct relationships with NHS primary care network procurement hubs rather than fragmented community pharmacy accounts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with paraffin legacy revenues and partially completed bio-coating transitions in Northern England manufacturing clusters. Long-term viability across the analysis window rests on qualification speed for compostable certifications and installed base relationships with automated pharmacy equipment vendors. Watch for inflection when NHS Supply Chain tenders embed mandatory bio-based coating requirements regardless of price premium acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Certification Investment | EN 13432 validation accelerates qualification for NHS and German hospital procurement tenders. |
| Precision Coating Equipment Acquisition | German-Italian machinery with real-time thickness monitoring meets robotic dispensing tolerance specifications. |
| Vegetable Wax Supply Agreement | Long-term contracts with Brazilian and Mexican harvest cooperatives stabilize feedstock cost exposure. |
| Homecare Channel Product Development | Patient-friendly formats with simplified opening mechanisms capture England's direct-to-patient expansion. |
| Clinical Trial Logistics Specialization | Custom sizing and batch-coding capabilities command price premiums above standard NHS contract rates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating equipment manufacturers, pharmaceutical packaging procurement managers, NHS supply chain directors, and German hospital pharmacy consortia leads. ECHA restriction timelines, British Pharmacopoeia specifications, and EU Green Deal implementation documents provided regulatory validation. Bottom-up volume modeling across pot format categories reconciled with top-down pharmaceutical dispensing expenditure patterns.
Data-stream reconciliation connected coating equipment shipment records from Bavarian and Italian machinery suppliers with NHS tender award notifications and German hospital procurement consortium contract registers. Segmentation dimensions spanned product type, end-user automation intensity, material certification status, and packaging integration format. CAGRs derived from volume trajectory analysis weighted by sustainability-linked pricing mechanisms in multi-year framework agreements. Forecast inputs incorporated REACH Annex XVII enforcement timelines and robotic dispensing system deployment curves in German university medical centers.
Several conditions sit outside the modeled scope, including pending revisions to EU Packaging and Packaging Waste Regulation compostability definitions and potential substitution by polymer-based alternatives in non-EU markets. Forecasts reflect assumptions regarding certification backlog resolution and coating chemistry stability validation under ICH guidelines. Deviation in NHS mandatory bio-based coating procurement mandates or German Extended Producer Responsibility fee modulation rules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market