
 Pharmaceutical Packaging Equipment Market | 2026-2036
Pharmaceutical Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Packaging Equipment Market Intelligence
The split between validated aseptic lines and standard oral-solid equipment is restructuring procurement budgets across the industry. Körber AG leverages its integrated pharma systems portfolio to anchor high-containment applications. Syntegon Technology differentiates through digital twin-enabled line optimization. Romaco Group competes via modular platform architectures that reduce changeover times.
Pharmaceutical packaging equipment encompasses machinery engineered to fill, seal, label, and inspect drug containers at speeds exceeding 600 units per minute with contamination control protocols. Blister packaging lines dominate current installed bases due to oral-solid volume scale, while automated technology segments capture expanding margin pools as labor costs rise and batch integrity standards tighten. Vial and ampoule equipment sustains premium positioning through isolator integration and robotics, though manual systems persist in emerging biologics pilot facilities.
The US FDA enforces Current Good Manufacturing Practice requirements that mandate electronic batch records and environmental monitoring on all commercial packaging lines. The EU EMA coordinates with national competent authorities to apply Annex 1 sterile manufacturing revisions that drive isolator-based barrier technology adoption. Japan's PMDA aligns with ICH Q9 quality risk management frameworks, creating harmonized compliance burdens for multinational equipment suppliers. Stakeholders must weigh total cost of ownership against regulatory trajectory when selecting between retrofit paths and greenfield automation investments.
Market Dynamics
Serialization mandates under the US Drug Supply Chain Security Act and the EU Falsified Medicines Directive are forcing contract packagers to accelerate automation investments across blister and vial lines. This regulatory compression is restructuring procurement budgets toward validated aseptic systems and away from standard oral-solid equipment.
Growth Catalysts
- Annex 1 sterile manufacturing revisions:The EU EMA's updated guidelines drive isolator-based barrier technology adoption across European fill-finish operations. German machinery clusters around Stuttgart and Frankfurt capture export demand from compliance-driven upgrades.
- Biologics pipeline expansion:Cell and gene therapy manufacturing requires high-containment packaging lines with robotics integration. Isolator-equipped vial and ampoule equipment sustains premium positioning through contamination control protocols.
- Labor cost escalation:Automated technology segments capture expanding margin pools as pharmaceutical manufacturers replace manual systems to maintain batch integrity at speeds exceeding 600 units per minute.
Market Restraints
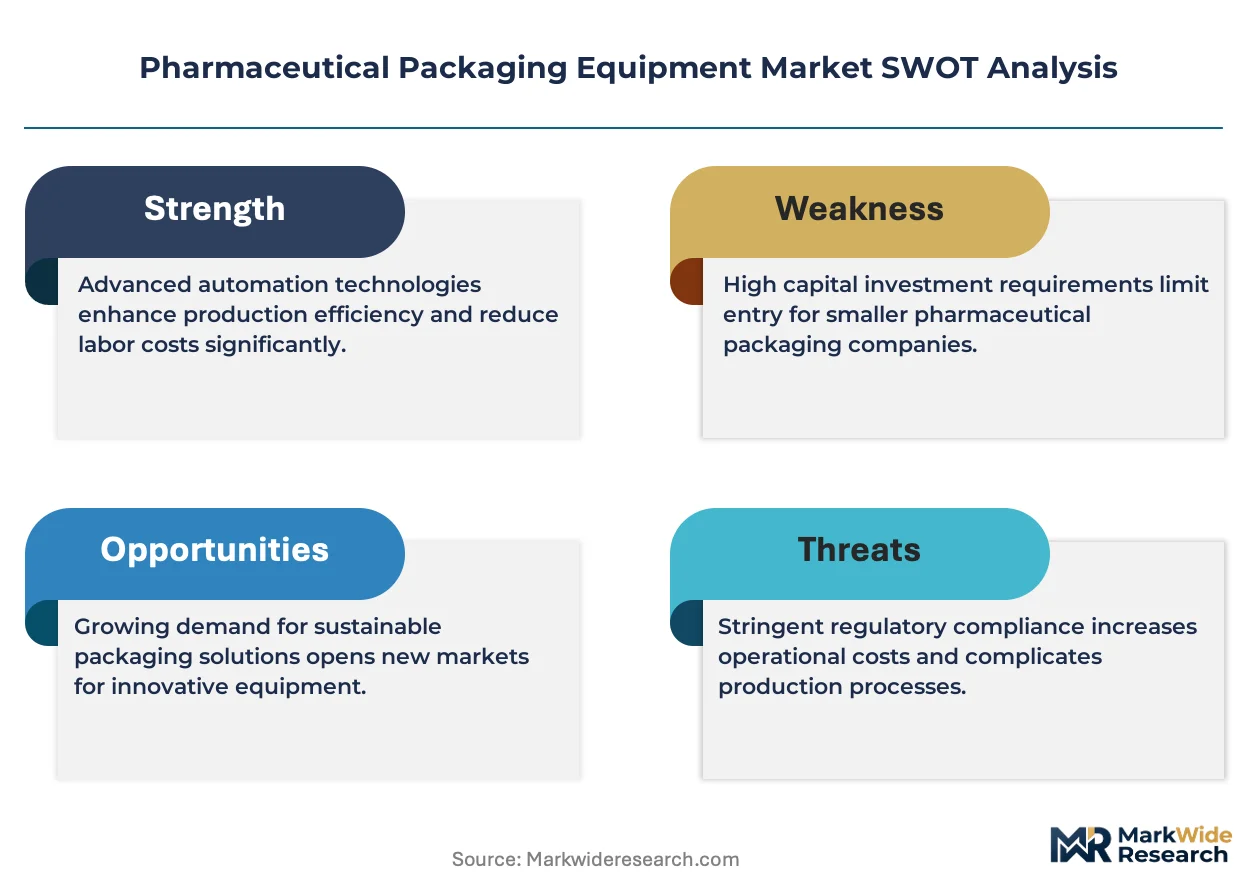
- Stainless steel and electronic component volatility:Input cost fluctuations for precision-machined parts and servo drives compress margins for mid-tier equipment suppliers dependent on spot-market purchasing.
- German supply concentration:Machinery clusters around Stuttgart and Frankfurt create geographic vulnerability for export-dependent packagers seeking alternative qualified suppliers.
- Legacy system interoperability gaps:Electronic batch record mandates under FDA Current Good Manufacturing Practice create friction for facilities running pre-digital control architectures.
Strategic Opportunities
- India CDMO expansion:The country's national pharmaceutical regulator is aligning with ICH Q9 quality risk management frameworks, creating harmonized compliance entry points for isolator-integrated line suppliers.
- Digital twin convergence:Virtual commissioning combined with predictive maintenance analytics enables remote line optimization without production downtime.
- Serialization-as-a-service channels:Equipment vendors are unbundling compliance hardware from software subscriptions, capturing recurring revenue from mid-sized contract packagers.
Industry Challenges
- Qualified validation engineering scarcity:FDA-mandated electronic batch records and environmental monitoring protocols require specialized personnel that outpace vocational training pipeline output.
- Greenfield versus retrofit capex decisions:Total cost of ownership calculations must weigh isolator integration complexity against brownfield structural constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Packaging Equipment Market |
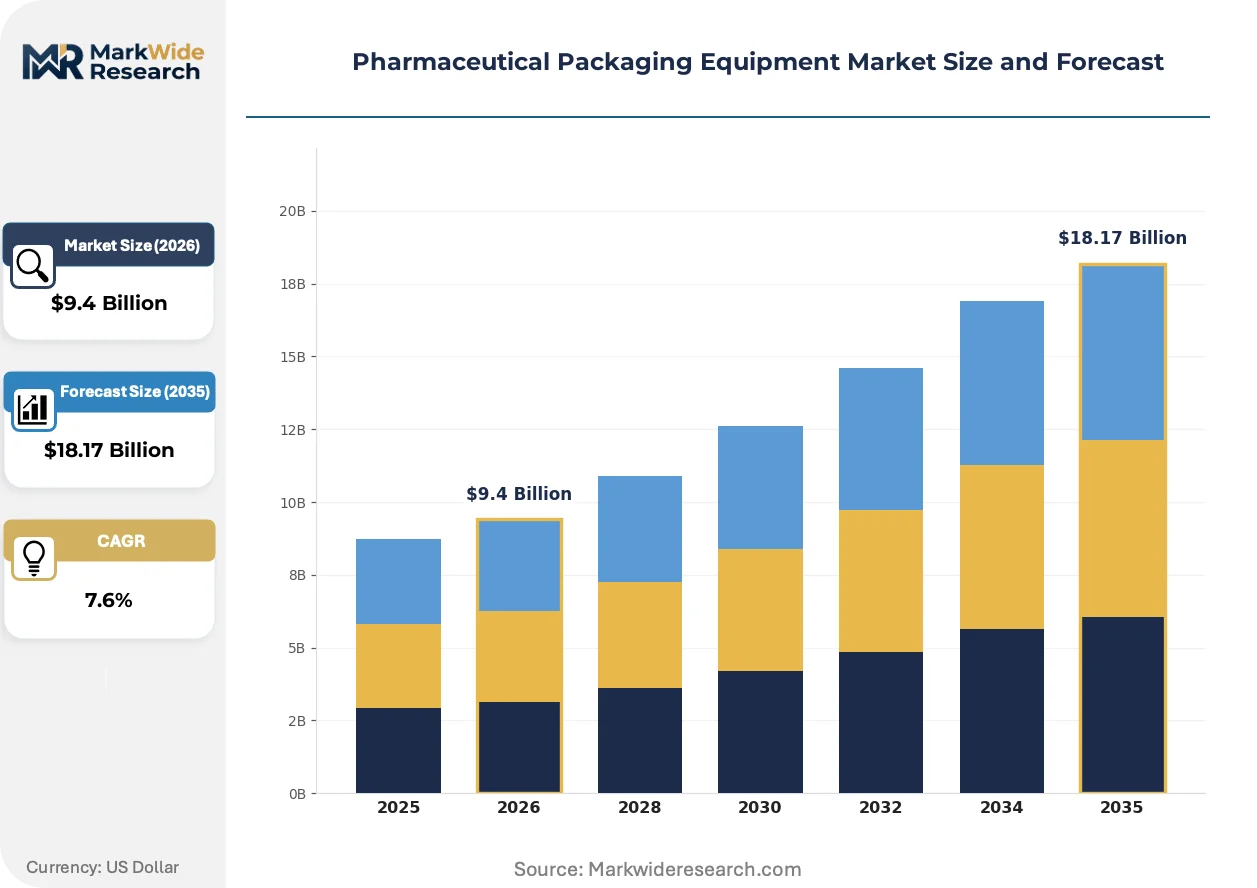
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.17 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blisters, Vials, Bottles, Ampoules Technology: Automated, Semi-Automated, Manual, Digital End User: Pharmaceutical Companies, Contract Packagers, Biotechnology Firms, Research Institutions Packaging Material: Glass, Plastic, Aluminum, Paper |
| Companies Covered | Romaco Group, Körber AG, Syntegon Technology, Bausch + Ströbel, Industria Macchine Automatiche, Marchesini Group, IMA Group, SaintyCo, Uhlmann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Packaging Equipment Market Strategic Shifts & Innovations
Equipment architectures are fragmenting between monolithic high-speed lines and reconfigurable cell-based systems. This divergence reflects competing pressures from batch-size flexibility demands and regulatory validation burdens.
Modular platform architectures are modularizing pharmaceutical packaging lines into standardized skids with plug-and-play isolator, filling, and inspection cells. Biologics pilot facilities and emerging CDMOs adopt these systems to compress changeover times between small-batch products. The approach is modularizing competitive differentiation around configuration speed rather than raw throughput specifications.
The EU Falsified Medicines Directive mandates end-to-end traceability through unique identifier aggregation at bundle, case, and pallet levels. Pharmaceutical manufacturers must retrofit existing blister and bottle lines with vision systems and aggregation software or face market withdrawal. High-volume oral-solid facilities in Germany and the United States are responding through phased capital programs that prioritize serialization-ready equipment in greenfield investments.
Service contract unbundling is disrupting traditional equipment procurement. Pharmaceutical manufacturers now separate hardware acquisition from validation support, spare parts logistics, and remote monitoring subscriptions. CDMOs in India and contract packagers in the United States lead this shift, preferring operational expenditure models that align vendor incentives with uptime performance rather than capital recovery schedules.
Pharmaceutical Packaging Equipment Market Segmentation
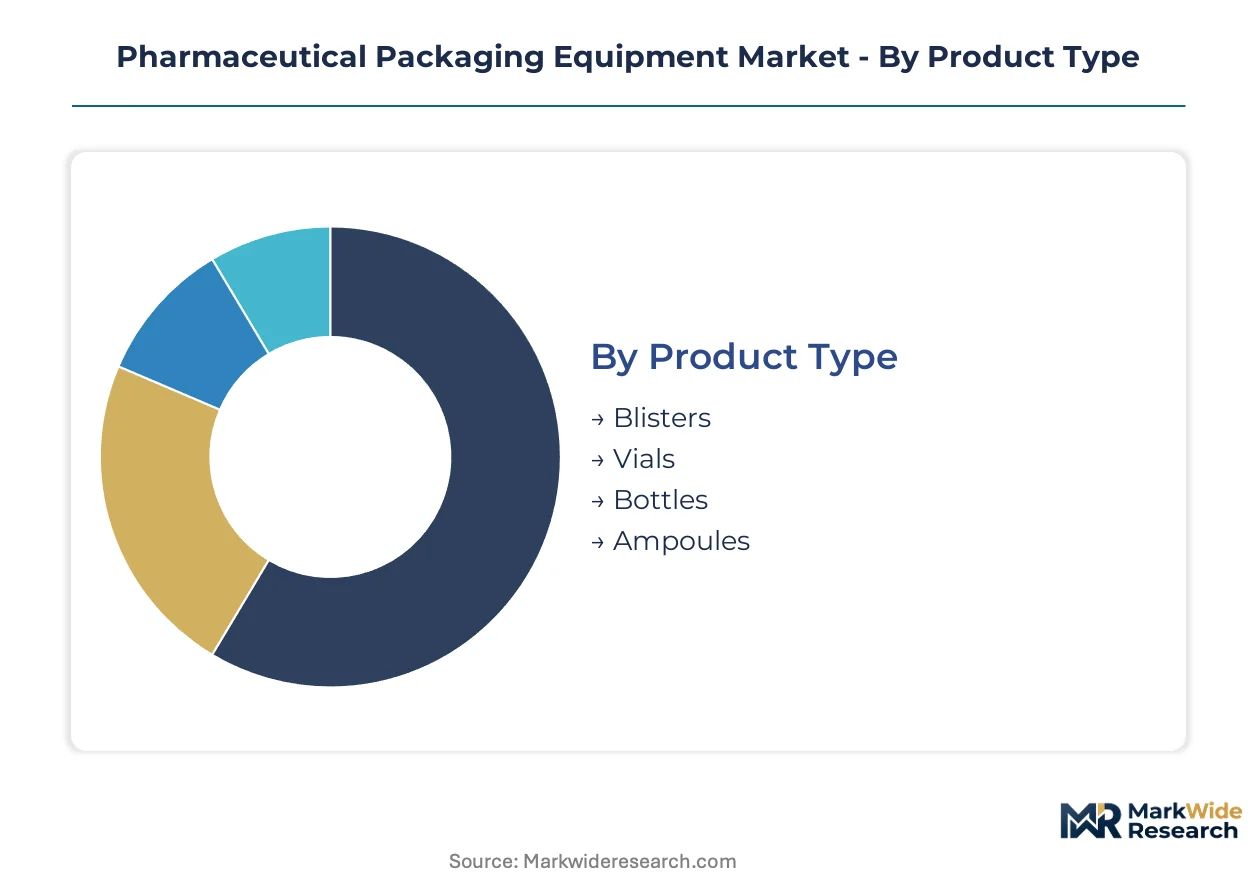
Equipment segmentation in pharmaceutical packaging reflects divergent compliance burdens across dosage forms and production scales. Procurement decisions hinge on matching validation requirements to product risk classifications and batch volume profiles.
Product Type:
EMA Annex 1 sterile manufacturing revisions and FDA Current Good Manufacturing Practice mandates impose tiered certification requirements across dosage form equipment, with isolator-integrated systems demanding extensive documentation.
- Blisters:Thermoforming and cold-forming lines process oral-solid doses at speeds exceeding 600 units per minute with aluminum-PVC laminate sealing. German machinery clusters around Stuttgart supply validated lines to contract packagers facing EU Falsified Medicines Directive serialization deadlines.
- Vials:Glass and polymer vial systems integrate isolator barriers and robotics for parenteral fill-finish operations. Biologics manufacturers in the United States and Switzerland specify these lines for cell therapy contamination control protocols.
- Bottles:HDPE and PET container handling equipment serves high-volume oral liquid and solid dispensing with desiccant insertion and child-resistant closure torque testing.
- Ampoules:Small-volume glass ampoule lines retain niche positioning in emerging market injectable facilities where isolator capital exceeds budget constraints.
Blister equipment sits at the top of the volume ranking, with vial systems climbing the fastest on biologics pipeline expansion.
Technology:
Automation intensity correlates directly with labor cost arbitrage and batch integrity enforcement across production geographies.
- Automated:Servo-driven lines with machine vision inspection and electronic batch recording command premium positioning in high-wage manufacturing regions. Japanese and German pharmaceutical manufacturers specify these systems to meet PMDA and EMA data integrity requirements.
- Semi-Automated:Operator-intermediate systems balance throughput with flexibility for mid-volume CDMO operations in India and Eastern Europe.
- Manual:Bench-scale equipment persists in biologics pilot facilities and research institutions where batch sizes fall below automated line economic thresholds.
- Digital:Digital twin-enabled platforms with predictive maintenance analytics represent the steepest expansion trajectory as vendors unbundle software subscriptions from hardware procurement.
Automated technology captures the dominant revenue share, while digital platforms are gaining share fastest through remote commissioning capabilities.
End User:
Customer type determines equipment specification complexity and service contract structuring across the procurement lifecycle.
- Pharmaceutical Companies:Multinational manufacturers with captive packaging operations specify integrated lines with centralized environmental monitoring and serialization aggregation software.
- Contract Packagers:Third-party service providers prioritize modular platforms with rapid changeover protocols to accommodate diverse client product portfolios and compliance profiles.
- Biotechnology Firms:Cell and gene therapy developers require high-containment isolator systems with single-use component pathways and robotics integration.
- Research Institutions:Academic and clinical trial material facilities specify bench-scale equipment with flexible batch size accommodation and simplified validation documentation.
Pharmaceutical companies anchor equipment demand by volume, with contract packagers expanding most quickly on outsourcing trend acceleration.
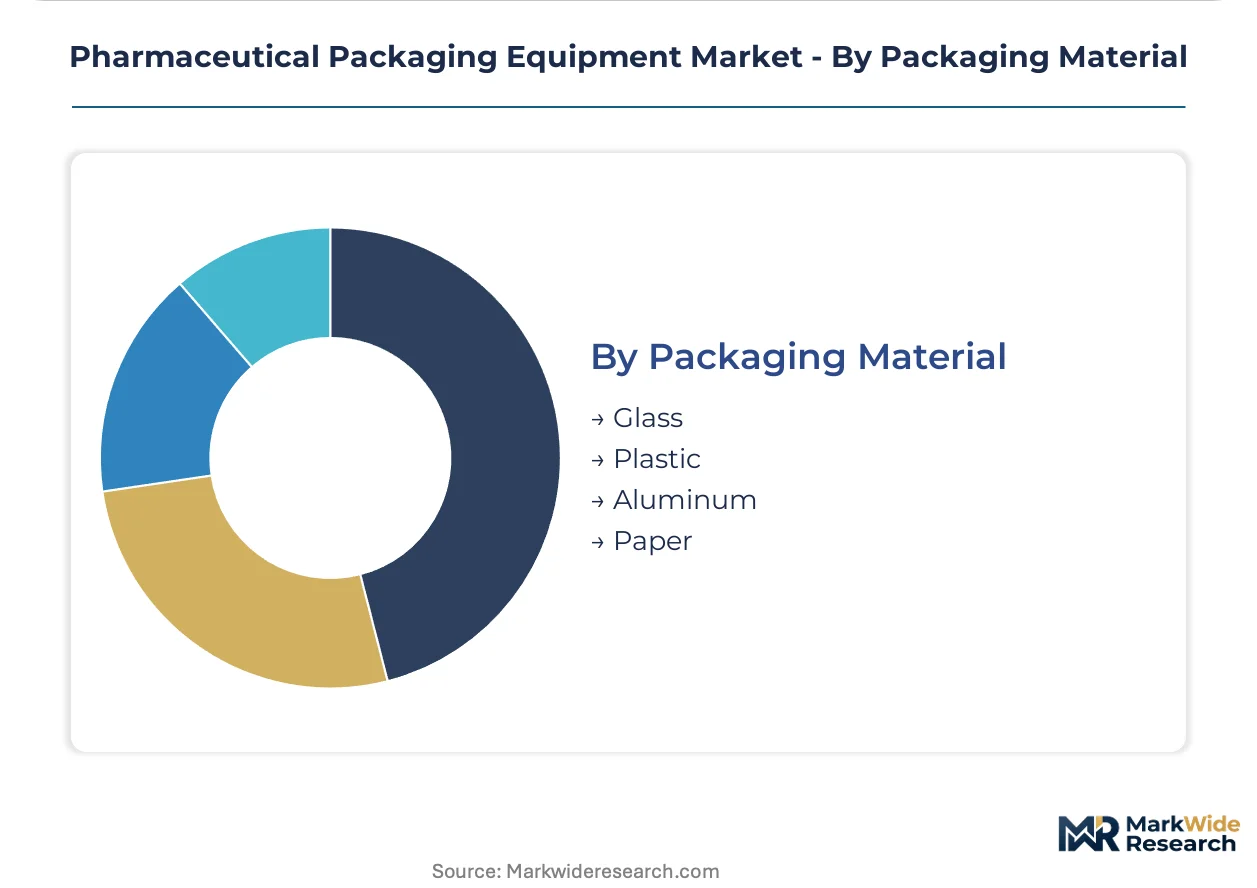
Packaging Material:
Material selection drives machinery design specifications for barrier properties, chemical compatibility, and serialization surface requirements.
- Glass:Borosilicate and molded glass handling systems dominate parenteral applications with siliconization, depyrogenation, and visual inspection integration.
- Plastic:Polymer container systems serve oral solid and liquid doses with moisture barrier multilayer structures and child-resistant closure compatibility.
- Aluminum:Cold-form foil and lidding material processing equipment provides oxygen and light barrier protection for moisture-sensitive formulations.
- Paper:Secondary packaging and labeling systems with print verification accommodate patient information leaflet insertion and aggregation coding.
Glass retains the highest value per unit processed, with plastic systems climbing fastest on oral solid volume scale and polymer vial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the machinery export base for pharmaceutical packaging equipment, while the United States drives compliance-driven retrofit demand through serialization mandates. India and China are expanding domestic manufacturing capacity to serve contract packaging growth. Switzerland and Japan maintain premium positioning through isolator-integrated biologics systems.
United States
Contract packagers in New Jersey and Pennsylvania are accelerating automation investments to meet FDA Drug Supply Chain Security Act deadlines for end-to-end traceability. The FDA enforces Current Good Manufacturing Practice requirements mandating electronic batch records on all commercial packaging lines. Greater Boston biotechnology clusters specify high-containment isolator systems for cell therapy manufacturing.
Germany
Stuttgart and Frankfurt machinery clusters supply validated blister and vial lines to export markets facing EU Falsified Medicines Directive compliance deadlines. The EMA coordinates Annex 1 sterile manufacturing revisions that drive isolator-based barrier technology adoption across European fill-finish operations. Baden-Württemberg engineering networks specialize in servo-driven lines exceeding 600 units per minute with contamination control protocols.
India
CDMOs in Maharashtra and Gujarat are scaling automated packaging capacity as the national pharmaceutical regulator aligns with ICH Q9 quality risk management frameworks. The CDSCO harmonizes compliance standards with international benchmarks, creating entry points for isolator-integrated line suppliers. Ahmedabad pharmaceutical manufacturing corridors concentrate contract packaging demand for oral-solid dose serialization upgrades.
Switzerland
Biologics manufacturers in Basel specify premium vial and ampoule equipment with robotics integration for parenteral contamination control. Swissmedic maintains stringent sterile manufacturing standards that sustain premium positioning for isolator-equipped barrier systems. The Basel-Land industrial region anchors high-containment packaging demand from cell and gene therapy pipeline expansion.
Japan
Pharmaceutical manufacturers specify automated lines with machine vision inspection to meet PMDA data integrity requirements for electronic batch recording. The PMDA aligns with ICH Q9 frameworks, creating harmonized compliance burdens for multinational equipment suppliers. Kanto region production facilities concentrate demand for servo-driven systems with environmental monitoring integration.
Pharmaceutical Packaging Equipment Market Key Industry Players
Top-tier vendors anchor premium isolator-integrated systems, while mid-tier specialists compete on modular platform flexibility and changeover speed. The vendor base stratifies across three archetypes: integrated pharma systems providers, digital twin-enabled optimization specialists, and modular skid fabricators. Dominant competitive moves include portfolio diversification into serialization software subscriptions and strategic partnerships with CDMOs for validation support services.
Among Germany-based integrated systems providers, Körber AG and Bausch + Ströbel occupy positions anchoring high-containment applications through comprehensive machinery portfolios. Syntegon Technology represents the digital optimization archetype, exemplifying virtual commissioning capabilities that enable remote line optimization. Romaco Group sits within the modular platform tier, offering reconfigurable cell-based systems that compress changeover times for contract packagers managing diverse product portfolios.
| Leading Market Players |
|---|
| Romaco Group |
| Körber AG |
| Syntegon Technology |
| Bausch + Ströbel |
| Industria Macchine Automatiche |
| Marchesini Group |
| IMA Group |
| SaintyCo |
| Uhlmann Group |
| Others |
Cost & Logistics Intelligence
Isolator-integrated line architectures simultaneously inflate capital expenditure thresholds and concentrate procurement authority among German machinery clusters, compressing mid-tier vendor margins while elevating premium-tier pricing power. This technology-driven cost bifurcation reshapes supplier-buyer dynamics across contract packaging networks facing EU Falsified Medicines Directive compliance deadlines.
Pricing Analysis
Bundled hardware-validation-service packages are fragmenting into unbundled subscription models as vendors capture recurring revenue from software-enabled remote monitoring. Three-tier pricing structure across premium isolator-integrated, standard automated, and economy manual levels reflects certification grade and after-sales service intensity. Cost compression in mid-tier equipment is intensifying because stainless steel and electronic component spot-market volatility erodes fixed-price contract viability. CDMOs in India exhibit highest price sensitivity due to capital constraint structures, while Swiss biologics manufacturers demonstrate lowest sensitivity given contamination control protocol non-negotiability.
Supply Chain Analysis
Freight cost escalation for precision-machined servo drives and isolator-grade stainless steel components amplifies geographic supply concentration effects across Germany, Switzerland, and Japan. Component sourcing draws from Baden-Württemberg engineering networks for high-speed filling systems, Basel-Land robotics integrators, and Kanto region machine vision suppliers. Single-source vulnerability concentrates in German servo motor and controller manufacturing clusters serving export markets. Distribution runs through OEM direct sales for multinational pharmaceutical manufacturers and specialized dealer networks for emerging market CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pharmaceutical Packaging Equipment Market functions as a stable compounder anchored by irreversible regulatory compliance mandates that perpetuate replacement cycles regardless of macroeconomic cyclicality.
For Market Incumbents: Hedge against modular platform disruption by acquiring digital twin software capabilities and expanding validation engineering services into India CDMO corridors. Isolator-integrated line commoditization threatens premium positioning; backward integration into servo drive manufacturing secures margin control against input cost volatility. For New Entrants and Emerging Players: Capture white-space opportunity in serialization-as-a-service software subscriptions for mid-sized US contract packagers facing FDA Drug Supply Chain Security Act deadlines. India's pharmaceutical manufacturing corridors present the most penetrable geography given CDSCO regulatory harmonization with ICH Q9 frameworks. Lead with operational expenditure pricing models that align vendor incentives with line uptime performance. For Investors and Strategic Acquirers: Valuations sit cheapest among semi-automated equipment specialists with underdeveloped digital service portfolios. Five-to-ten year viability favors vendors with installed base scale enabling recurring software revenue conversion. Monitor FDA electronic batch record enforcement intensity as inflection indicator for automation upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual commissioning reduces validation timelines for EU Annex 1 compliance upgrades. |
| Serialization Software Unbundling | Subscription revenue captures mid-tier packagers seeking opex-aligned procurement structures. |
| Isolator Barrier Technology Licensing | Technology transfer agreements accelerate emerging market biologics manufacturing capability. |
| Validation Support Service Expansion | Qualified engineering scarcity creates captive service revenue from CDMO outsourcing. |
| Modular Skid Standardization | Plug-and-play cell architectures compress changeover times for diverse product portfolios. |
Research Approach
Coverage spans Germany, the United States, India, Switzerland, and Japan, with primary inputs from each territory combined with secondary validation. Equipment procurement directors at multinational pharmaceutical manufacturers, validation engineering leads at contract packagers, and regulatory affairs specialists at CDMOs contributed interview data. Secondary sources include FDA 483 observation databases, EMA GMP inspection reports, CDSCO guidance documents, and SEC filings from publicly traded machinery vendors. Bottom-up equipment shipment tracking and top-down pharmaceutical manufacturing capacity estimates were triangulated.
Rate-of-change decomposition across the projection horizon isolates volume effects from mix-shift and pricing components. Segmentation dimensions modeled include dosage form, automation intensity, end-user archetype, and packaging material. CAGRs were derived from installed base replacement cycles, greenfield capacity announcements, and regulatory deadline clustering. Forecast inputs incorporate EU Falsified Medicines Directive implementation phasing and US Drug Supply Chain Security Act compliance milestones.
Underlying measurement precision varies by segment; automated technology and digital platform categories carry tighter precision than manual equipment due to vendor disclosure consistency. Forecasts reflect assumptions regarding regulatory enforcement continuity and input cost stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market