
 Europe Pharmaceutical Blister Packaging Market | 2026-2036
Europe Pharmaceutical Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Blister Packaging Market Insights
High-barrier coextrusion and sustainable film lamination is reconfiguring how European blister packs achieve moisture and oxygen protection without multi-material complexity. Amcor Plc leverages integrated film-to-packaging workflows across its European manufacturing network. Constantia Flexibles GmbH anchors its position through specialized aluminum-PVC composite lidding solutions. Klockner Pentaplast Group dominates rigid PET and recycled-content blister film supply to major pharmaceutical contract packagers.
Europe pharmaceutical blister packaging consists of thermoformed or cold-formed cavity structures sealed with lidding foil, typically achieving water vapor transmission rates below 0.5 g/m²/day for moisture-sensitive solid oral doses. These configurations protect tablet and capsule integrity through shelf life while enabling patient adherence via individual unit-dose accessibility. Cold formed blisters command premium positioning due to complete light and moisture barrier properties for hygroscopic and photosensitive APIs. Push-through blisters sustain volume leadership across retail pharmacy and hospital discharge segments where child-resistant features are not mandated. Lidding films concentrate margin pools as converter differentiation hinges on peel-force consistency, printability, and compatibility with high-speed form-fill-seal lines.
EMA's quality guidelines, the EU Packaging and Packaging Waste Regulation, and national medicines agencies across Germany, France, and Italy shape material selection, recyclability targets, and child-resistant certification requirements. REACH restrictions on phthalate plasticizers and the F-Gas Regulation's phase-down of fluorinated barrier films are accelerating migration toward polypropylene and recycled PET substrates. Stakeholders must monitor evolving EMA guidance on extractables and leachables testing as novel barrier coatings replace conventional aluminum-PVC structures.
Market Dynamics
EMA's extractables and leachables testing mandates are compressing formulation-to-package development timelines, forcing pharmaceutical manufacturers to front-load compatibility studies before commercial scale-up. REACH restrictions on phthalate plasticizers and the F-Gas Regulation's barrier-film phase-down are simultaneously reshaping material qualification protocols across European contract packaging networks.
Growth Catalysts
- Unit-dose compliance packaging:Germany's national medicines agency and hospital pharmacy networks mandate individual cavity formats for medication adherence programs in chronic disease management.
- REACH phthalate restrictions:The regulation accelerates substitution of conventional PVC with polypropylene and recycled PET substrates in thermoformed blister bases.
- Cold-form aluminum demand:Hygroscopic and photosensitive APIs from Italian specialty pharmaceutical manufacturers require complete moisture and light barrier properties.
Market Restraints
- Aluminum foil supply concentration:European rolling mill capacity for pharmaceutical-grade lidding concentrates in Germany and France, creating input cost volatility during energy price spikes.
- Recycled-content technical limits:EFSA food-contact migration thresholds constrain post-consumer PET incorporation in direct-contact blister films below 30% by mass.
- F-Gas fluorinated barrier phase-down:The regulation eliminates high-performance PVDC and EVOH coextrusions before polyolefin alternatives achieve equivalent oxygen transmission rates.
Strategic Opportunities
- Central and Eastern European contract packaging:Poland and Czech Republic host underpenetrated pharmaceutical manufacturing clusters seeking EU-accessible packaging capacity.
- Child-resistant senior-friendly (CRSF) formats:France's ANSM certification pathway for push-turn and slide blister mechanisms opens premium positioning in retail pharmacy.
- Digital watermarking integration:Convergence of printed electronics with thermoforming enables unit-level traceability for anti-counterfeiting compliance with the EU Falsified Medicines Directive.
Industry Challenges
- Extractables testing talent scarcity:Analytical chemists capable of designing forced extraction protocols per EMA quality guidelines command premium compensation in Germany's Rhine-Main cluster.
- Legacy form-fill-seel line retrofit costs:High-speed equipment originally configured for PVC-PVDC structures requires substantial capital outlay to process recycled PET and PP alternatives.
- Multi-material recyclability certification delays:Extended producer responsibility schemes under the EU Packaging and Packaging Waste Regulation await harmonized sorting infrastructure for aluminum-PP laminate structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Blister Packaging Market |
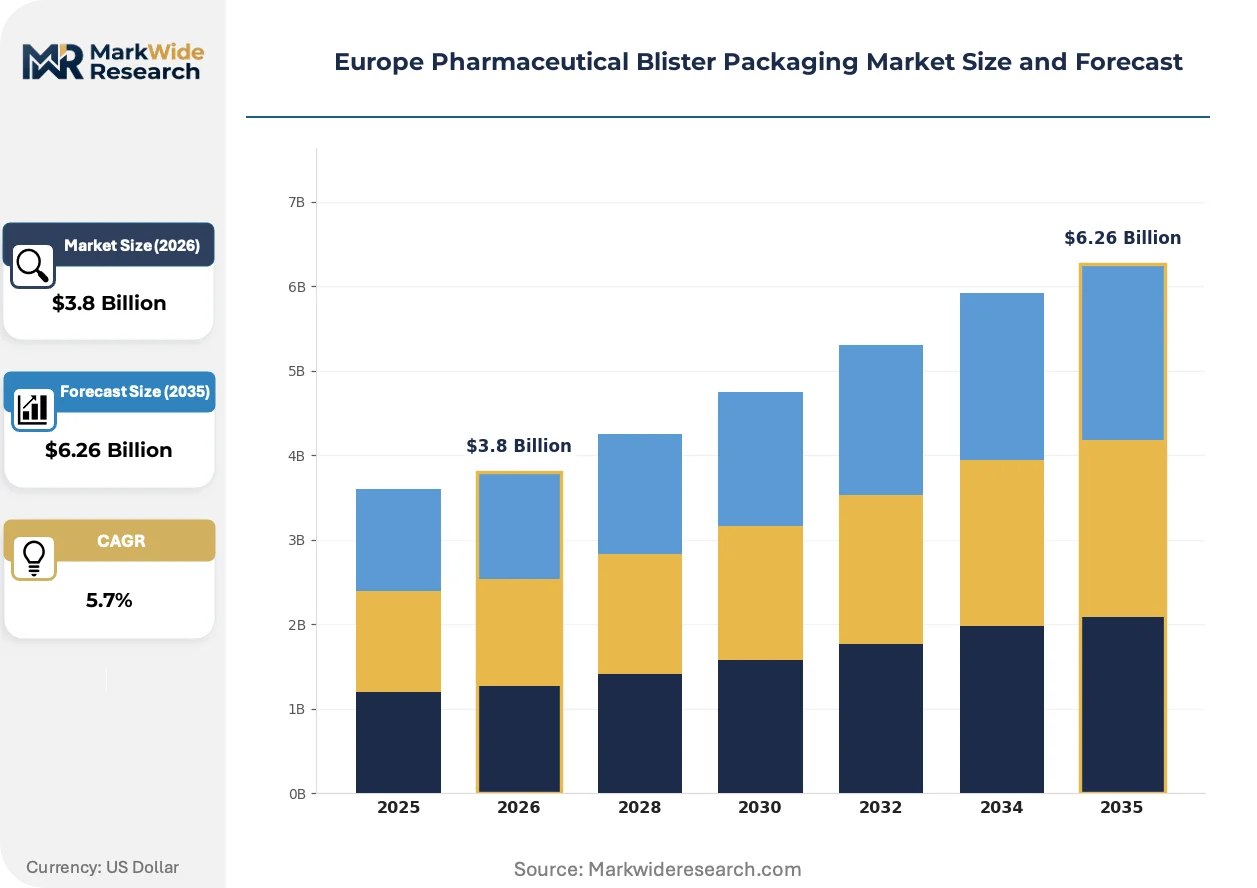
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Formed Blister, Rigid Blister, Push-Through Blister, Clamshell Blister Material: Polyvinyl Chloride, Polypropylene, Aluminum, PET End User: Pharmaceutical Manufacturers, Contract Packagers, Drug Distributors, Retail Pharmacies Packaging Type: Thermoformed Blisters, Lidding Films, Modified Atmosphere Packaging, Child-Resistant Packaging |
| Companies Covered | Amcor Plc, Constantia Flexibles GmbH, Sonoco Products Company, Klockner Pentaplast Group, Bilcare Limited, WestRock Company, Ecobliss Pharmaceutical Packaging, Wonderpack Group, Tekni-Plex Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Blister Packaging Market Trends and Innovations
Barrier coating technologies and substrate innovations are collapsing the performance gap between conventional multi-material blisters and recyclable mono-polymer alternatives. European converters are reconfiguring lamination workflows to accommodate pharmaceutical-grade sustainability mandates without sacrificing moisture protection.
High-barrier silicon oxide and aluminum oxide vapor-deposited coatings on oriented polypropylene films are hybridizing moisture and oxygen protection into single-substrate structures. Mid-sized pharmaceutical contract packagers in France and Italy are qualifying these coated OPP films for moisture-sensitive solid oral doses at accelerated timelines. The technology is hybridizing what previously required aluminum-PVC-PVDC triplex laminates into peelable mono-material formats compatible with existing thermoforming equipment.
The EU Packaging and Packaging Waste Regulation's 2030 recyclability targets are forcing redesign of lidding-to-base material pairings across all member states. Pharmaceutical packaging specifications now exclude non-separable aluminum-thermoplastic composites from new product registrations. German generic drug manufacturers are responding fastest, converting volume to peelable aluminum-polypropylene structures that maintain child-resistance certification while enabling aluminum recovery.
Hospital pharmacy procurement consortia in France, Germany, and the Netherlands are consolidating supplier panels around packaging converters with integrated sustainability certification. Three-year framework agreements now specify recycled-content minimums and carbon footprint disclosure as mandatory award criteria. This concentration is most visible in oncology and cardiovascular therapeutic categories where tender volumes exceed 50 million annual units.
Europe Pharmaceutical Blister Packaging Market Segmentation
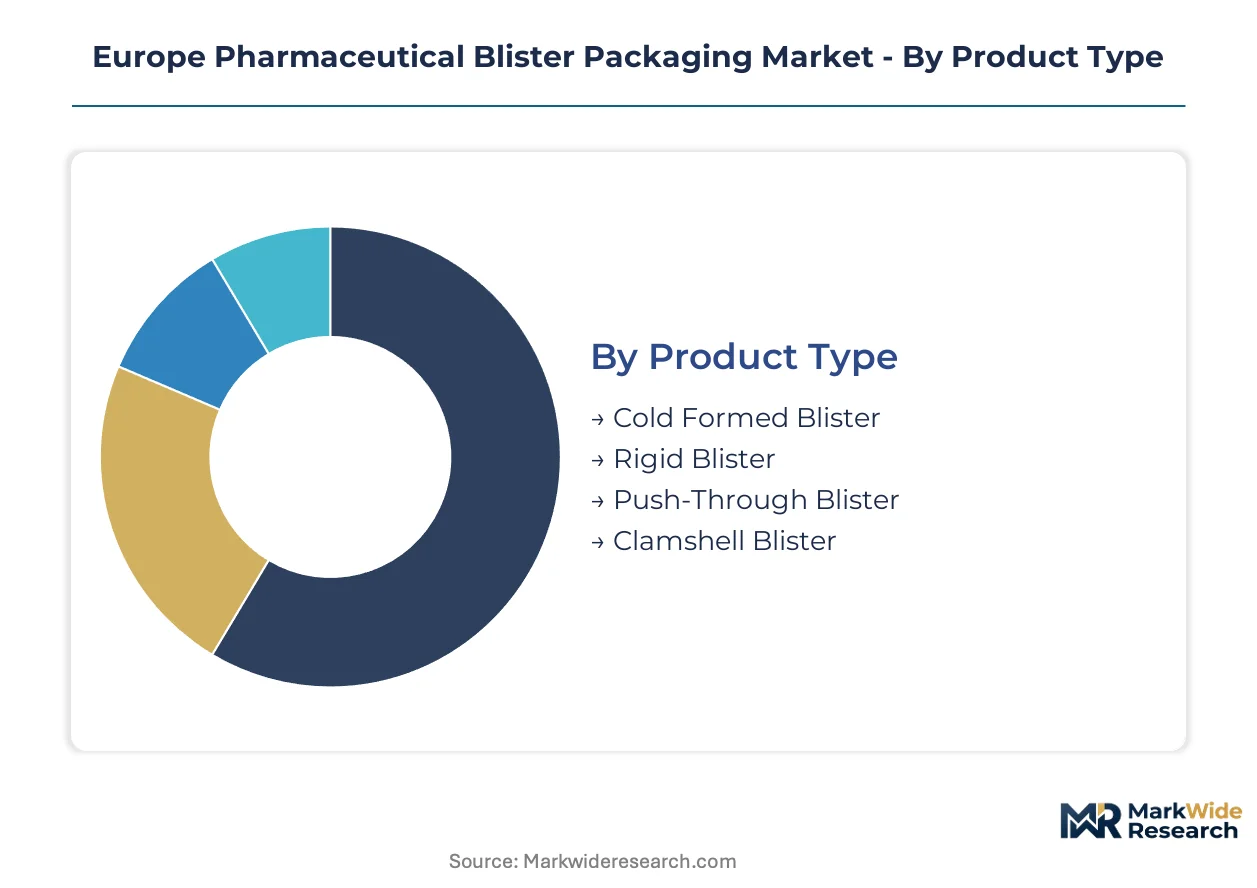
European pharmaceutical blister packaging segments reflect divergent barrier requirements across solid oral dose formats, with material choices increasingly constrained by EMA extractables protocols and EU Packaging and Packaging Waste Regulation recyclability mandates. Understanding these divisions reveals where converter investment and pharmaceutical qualification timelines concentrate.
Product Type:
Mature formats dominate hospital and retail pharmacy procurement, while emerging configurations address specialty pharmaceutical moisture sensitivity.
- Cold Formed Blister:Aluminum-PVC-aluminum triplex laminates deliver complete moisture, oxygen, and light barrier protection for hygroscopic and photosensitive APIs. Italian specialty pharmaceutical manufacturers in Lombardy and Piedmont drive qualification volumes for oncology and cardiovascular compounds requiring sub-0.1 g/m²/day water vapor transmission rates.
- Push-Through Blister:Standard PVC or PET-based cavities with aluminum lidding enable individual unit-dose access for chronic disease adherence programs. Germany's hospital pharmacy networks and retail chains specify this format for non-controlled substances where child-resistance is not mandated.
- Rigid Blister:Thick-gauge PET or PP structures provide dimensional stability for heavy tablet counts and diagnostic kit integration.
- Clamshell Blister:Hinged thermoformed designs serve medical device and combination product presentations requiring reusable access.
Push-Through Blister handles the majority of throughput; Cold Formed Blister is expanding most quickly on share.
Material:
Cost tiers stratify around regulatory compliance burden and barrier performance, with premium substrates commanding extended qualification timelines.
- Polyvinyl Chloride:Conventional blister base material faces accelerating substitution under REACH phthalate plasticizer restrictions. German generic manufacturers maintain volume commitment during transition periods due to established form-fill-seal line configurations.
- Aluminum:Pharmaceutical-grade lidding foil and cold-form structures concentrate margin pools. Rolling mill capacity in Germany's Rhine-Ruhr cluster and France's Isère region creates supply concentration risk during energy price volatility.
- Polypropylene:Emerging mono-material substrate enables recyclability certification under extended producer responsibility schemes. French and Dutch hospital procurement consortia specify minimum recycled-content thresholds favoring PP adoption.
- PET:Recycled-content films from post-consumer feedstock face EFSA migration threshold constraints capping incorporation below direct-contact limits.
Polyvinyl Chloride retains volume leadership; Polypropylene is gaining share fastest.
End User:
Customer type determines specification complexity, with integrated manufacturers driving barrier innovation and contract packagers managing format flexibility.
- Pharmaceutical Manufacturers:Originators of solid oral dose formulations specify packaging during early-phase development to satisfy EMA extractables and leachables testing timelines. German and Swiss headquarters operations anchor regional demand for high-barrier cold-form structures.
- Contract Packagers:Multi-client service providers in Poland and Czech Republic manage format conversion across PVC, PP, and PET substrates for EU-accessible production capacity.
- Drug Distributors:Wholesale and logistics operators specify secondary packaging compatibility with automated dispensing systems.
- Retail Pharmacies:Chain procurement in France, Germany, and Netherlands consolidates supplier panels around sustainability certification and carbon disclosure.
Pharmaceutical Manufacturers command specification authority; Contract Packagers are climbing the fastest on capacity expansion.
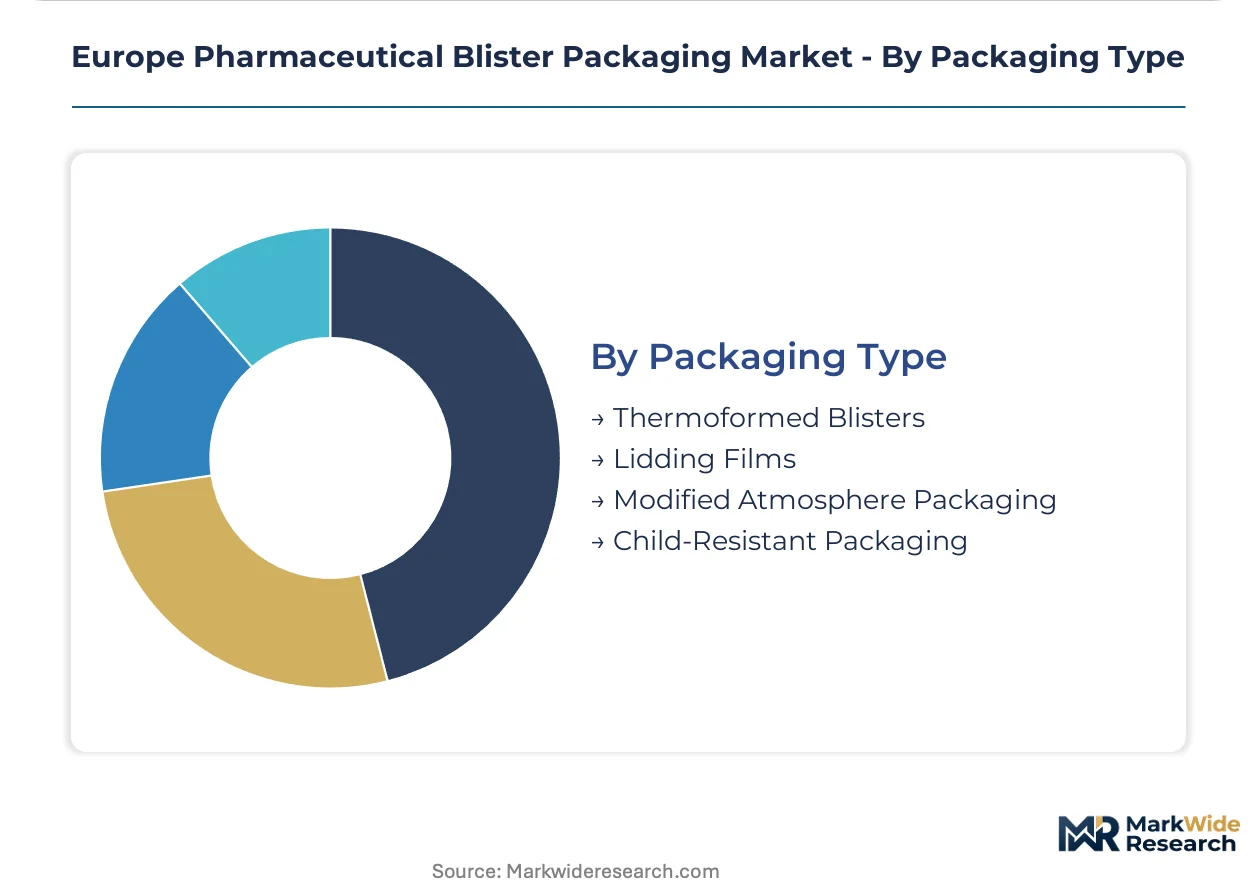
Packaging Type:
Application focus separates primary cavity structures from functional overlay films and safety-certified formats.
- Thermoformed Blisters:Heated-sheet vacuum or pressure-formed cavities constitute the foundational primary package for tablet and capsule presentation. Conversion lines across Italy's Emilia-Romagna packaging cluster process PVC, PET, and PP substrates at speeds exceeding 600 cavities per minute.
- Lidding Films:Aluminum-polymer composites and peelable structures seal thermoformed bases with controlled peel-force consistency. French converters specialize in push-turn and slide mechanisms qualifying for ANSM child-resistant senior-friendly certification.
- Modified Atmosphere Packaging:Nitrogen-flushed cavity environments extend stability for oxidation-sensitive APIs.
- Child-Resistant Packaging:Senior-friendly access mechanisms satisfy France ANSM and Germany BfArM regulatory pathways for controlled substances.
Thermoformed Blisters handle the majority of throughput; Lidding Films command the steepest expansion trajectory on functional premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical blister packaging exports flow primarily to French and Italian drug manufacturers, establishing a north-south trade corridor that channels high-barrier films and cold-form laminates toward Mediterranean formulation sites.
Germany
Hospital pharmacy networks in North Rhine-Westphalia and Bavaria mandate unit-dose compliance formats for chronic disease management programs. The BfArM enforces child-resistant certification pathways that push manufacturers toward peelable aluminum-polypropylene structures. The Rhine-Main cluster around Frankfurt hosts concentrated analytical chemistry capacity for EMA extractables testing.
France
ANSM certification for senior-friendly access mechanisms drives premium positioning in retail pharmacy procurement. The EU Packaging and Packaging Waste Regulation's 2030 recyclability targets force rapid conversion from non-separable aluminum-PVC composites. The Isère region maintains pharmaceutical-grade aluminum rolling capacity for lidding foil supply.
Italy
Specialty pharmaceutical manufacturers in Lombardy and Piedmont require sub-0.1 g/m²/day water vapor transmission rates for hygroscopic oncology APIs. EMA quality guidelines on leachables testing compress development timelines for local formulation houses. The Emilia-Romagna packaging cluster processes thermoformed substrates at speeds exceeding 600 cavities per minute.
Netherlands
Hospital procurement consortia consolidate supplier panels around carbon footprint disclosure and recycled-content minimums. The country's central logistics position enables just-in-time delivery to German and Belgian pharmaceutical distribution hubs. Rotterdam-area converters specialize in nitrogen-flushed modified atmosphere configurations for oxidation-sensitive compounds.
Poland
Underpenetrated pharmaceutical manufacturing clusters seek EU-accessible contract packaging capacity with competitive labor economics. REACH phthalate restrictions accelerate local qualification of polypropylene alternatives to conventional PVC. The Warsaw-Łódź corridor attracts multi-client service providers managing format conversion across substrate types.
Europe Pharmaceutical Blister Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated film-to-packaging workflows and specialized barrier technology tiers. Three strategic archetypes dominate: diversified materials conglomerates with European manufacturing networks, mid-sized converters focused on aluminum-polymer composite lidding, and rigid film specialists supplying recycled-content substrates. Competitive moves concentrate on backward integration into resin and foil production, plus strategic partnerships with pharmaceutical contract packagers for co-development of mono-material formats.
Among diversified packaging conglomerates, Amcor Plc and WestRock Company occupy positions spanning multiple substrate technologies and geographic markets. Specialized European converters include Constantia Flexibles GmbH, whose Austrian-German footprint exemplifies the aluminum-lidding tier, and Klockner Pentaplast Group, which anchors rigid PET and recycled-content film supply to major pharmaceutical contract packagers. These three represent distinct competitive vectors: scale-driven material integration, regional barrier specialization, and substrate innovation for sustainability mandates.
| Leading Market Players |
|---|
| Amcor Plc |
| Constantia Flexibles GmbH |
| Sonoco Products Company |
| Klockner Pentaplast Group |
| Bilcare Limited |
| WestRock Company |
| Ecobliss Pharmaceutical Packaging |
| Wonderpack Group |
| Tekni-Plex Inc |
| Others |
Pricing and Supply Chain Analysis
Aluminum foil supply concentration in Germany's Rhine-Ruhr cluster and France's Isère region determines both pricing tier spreads and supply chain shape, creating input cost volatility that propagates through cold-form laminates and lidding films during energy price spikes. This geographic tethering of pharmaceutical-grade rolling mill capacity forces converters to buffer margin compression through material substitution while buyers absorb premium volatility for barrier-certified formats.
Pricing Analysis
Current-generation cold-form aluminum-PVC-aluminum triplex laminates command substantial premiums over prior-generation PVC-PVDC push-through blisters, while next-generation mono-polypropylene structures with silicon oxide coatings occupy an emerging mid-tier. Three-tier pricing structure across premium, standard, and economy levels separates complete barrier laminates from conventional thermoformed bases and nascent recyclable alternatives. Cost compression in standard PVC formats is intensifying because REACH phthalate restrictions accelerate substrate substitution timelines. Hospital procurement consortia in France and the Netherlands exhibit lowest price sensitivity due to mandatory carbon disclosure and recycled-content specifications, while generic drug manufacturers in Germany face acute pressure on per-unit packaging economics.
Supply Chain Analysis
Contract packaging concentration in Poland and the Czech Republic holds capacity for format conversion across substrate types, with multi-client service providers managing PVC-to-PP transitions for EU-accessible production. Raw material dependencies rest on pharmaceutical-grade aluminum foil from German and French rolling mills, oriented polypropylene resin from Benelux petrochemical hubs, and post-consumer PET feedstock constrained by EFSA migration thresholds. Single-source vulnerability concentrates in aluminum lidding supply during energy price volatility. Distribution runs through pharmaceutical contract packagers in Central and Eastern Europe, hospital procurement consortia in France and Germany, and retail pharmacy chains in the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement consortia in France, Germany, and the Netherlands, which now mandate sustainability certification and carbon footprint disclosure as mandatory award criteria in three-year framework agreements exceeding 50 million annual units.
For Market Incumbents: Entrench barrier technology leadership through backward integration into aluminum foil rolling capacity in Germany's Rhine-Ruhr cluster, insulating margin pools from energy-driven input volatility. Accelerate qualification of mono-polypropylene formats with vapor-deposited oxide coatings to preempt regulatory displacement of multi-material laminates under EU Packaging and Packaging Waste Regulation recyclability mandates. Prioritize certification investment for child-resistant senior-friendly mechanisms qualifying through France's ANSM pathway. For New Entrants and Emerging Players: Establish a beachhead in Central and Eastern European contract packaging, where underpenetrated pharmaceutical manufacturing clusters in Poland and the Czech Republic seek EU-accessible capacity with competitive labor economics. Target oncology and cardiovascular therapeutic categories where hospital tender volumes exceed 50 million annual units and sustainability specifications have not yet fully consolidated supplier panels. Deploy digital watermarking integration for unit-level traceability as a differentiated go-to-market angle aligned with EU Falsified Medicines Directive compliance. For Investors and Strategic Acquirers: EMA's evolving extractables and leachables testing mandates reshape the acquisition landscape toward analytical chemistry capabilities in Germany's Rhine-Main cluster, where forced extraction protocol expertise commands premium compensation. Long-term viability over the next decade hinges on positioning for mono-material format transition as fluorinated barrier films phase down under F-Gas Regulation timelines. Target acquisition archetypes include mid-sized converters with qualified oxide-coated polypropylene films and established pharmaceutical manufacturer relationships. Monitor EMA guidance publication cadence on novel barrier coatings as the critical inflection signal for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil Rolling | Captures margin pools concentrated in Germany's Rhine-Ruhr and France's Isère regions. |
| Mono-Polypropylene Format Qualification | Positions converters ahead of EU Packaging and Packaging Waste Regulation 2030 recyclability enforcement. |
| Child-Resistant Senior-Friendly Certification | Unlocks premium positioning in France's ANSM-regulated retail pharmacy procurement. |
| Digital Watermarking Integration | Enables unit-level traceability compliance with EU Falsified Medicines Directive anti-counterfeiting requirements. |
| Central and Eastern European Capacity Expansion | Addresses underpenetrated pharmaceutical clusters in Poland and Czech Republic seeking EU-accessible contract packaging. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging specification managers at German and Swiss originator companies, contract packaging operations directors in Poland and the Czech Republic, hospital pharmacy procurement leads in France and the Netherlands, and analytical chemistry heads conducting EMA extractables studies in the Rhine-Main cluster. Secondary validation drew from EMA quality guideline publications, EU Packaging and Packaging Waste Regulation draft texts, REACH restriction dossiers, F-Gas Regulation implementation schedules, and rolling mill capacity disclosures from German and French aluminum producers. Bottom-up unit economics for substrate conversion were triangulated against top-down market sizing from pharmaceutical production volume data.
Calibration against historical qualification timelines for cold-form laminates and mono-polypropylene alternatives anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled encompassed product type, material substrate, end-user archetype, and packaging format complexity, with additional stratification by regional regulatory cluster reflecting EMA versus national agency enforcement variation. CAGRs were derived from elasticity-adjusted volume projections tied to pharmaceutical manufacturing output and packaging format conversion rates. Industry-specific forecast inputs included EFSA migration threshold evolution for recycled-content PET and BfArM child-resistant certification pathway updates.
Stress conditions across aluminum foil input costs, energy price volatility, and EMA extractables testing timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and material substitution elasticity. Quarterly review of EMA guidance publication cadence, EU Packaging and Packaging Waste Regulation delegated act releases, and hospital procurement consortium tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market