
 Disk-Based Backup System Market | 2026-2036
Disk-Based Backup System Market Size, Share, and Industry Trends Forecast 2026-2036
Disk-Based Backup System Market Outlook
Modular appliance-plus-software bundling is pivoting buyer evaluation criteria toward total cost of ownership rather than raw capacity metrics. Dell PowerProtect Data Domain leverages inline deduplication to sustain throughput leadership in enterprise data centers. ExaGrid EX anchors its position through differentiated scale-out architecture that competes on recovery time objectives against monolithic alternatives.
A disk-based backup system stores redundant copies of digital information on magnetic hard disk drives, solid-state arrays, or hybrid media, employing block-level deduplication and snapshot scheduling to achieve recovery point objectives measured in minutes rather than hours. The technology serves commercial and industrial users by eliminating tape retrieval latency and enabling granular file restoration. NAS and SAN product types occupy the mature volume tier where margin pools have compressed, while cloud backup technology leads growth as organizations distribute retention across on-premise and offsite tiers. Hybrid deployment segments attract the fastest expansion as regulated industries balance latency requirements with geographic redundancy mandates.
FDA 21 CFR Part 11, SEC cybersecurity disclosure rules, and NIST SP 800-53 shape product certification requirements and procurement checklists for backup systems handling regulated records. HIPAA security rule enforcement tightens access logging and encryption standards across healthcare deployments, narrowing vendor qualification to architectures with native compliance tooling. Stakeholders must weigh deduplication efficiency against immutable snapshot capabilities when architecting defenses against ransomware encryption of secondary data stores.
Market Dynamics
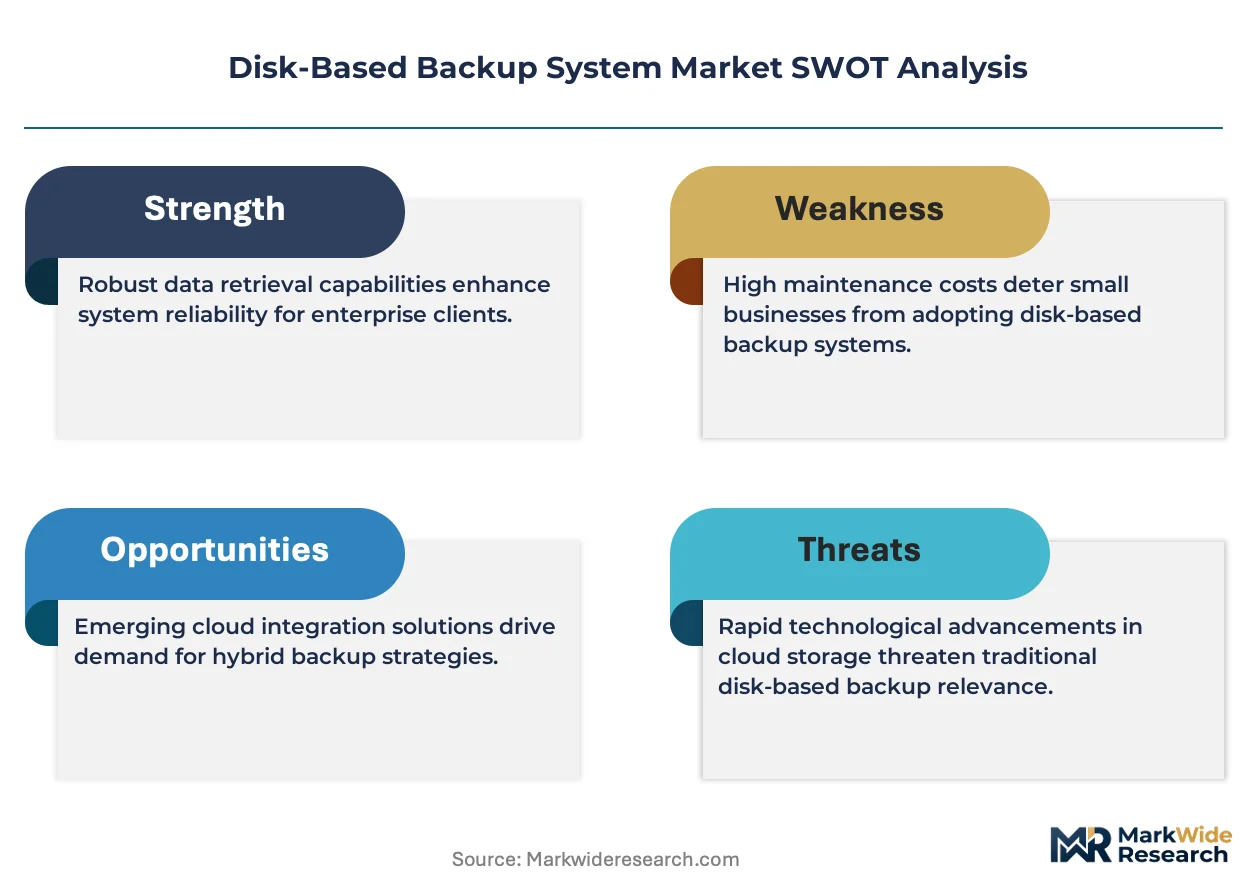
Hybrid deployment architectures are compressing procurement cycles as financial services firms replace legacy tape infrastructure with unified on-premise and cloud retention tiers. NIST cybersecurity frameworks and SEC disclosure mandates now appear on every enterprise RFP, forcing vendors to bundle compliance tooling with deduplication hardware.
Growth Catalysts
- FDA 21 CFR Part 11:Life sciences organizations require immutable snapshot capabilities for electronic records, expanding qualified vendor pools for validated backup environments.
- Inline deduplication:Block-level data reduction technologies cut storage overhead by eliminating redundant copies across backup windows.
- Japan:METI industrial data security guidelines accelerate enterprise migration from tape to disk-based recovery systems in manufacturing and automotive sectors.
Market Restraints
- Flash memory cost volatility:NAND pricing swings compress margins on all-flash backup arrays and delay enterprise refresh cycles.
- Supply concentration in Taiwan:Controller ASIC and high-capacity HDD component sourcing creates single-point vulnerability for appliance manufacturers.
- Cloud-native substitution:Object storage and serverless backup services divert mid-market spend away from on-premise disk appliances.
Strategic Opportunities
- Germany:Bundesdatenschutzgesetz enforcement and CSRD reporting requirements drive demand for sovereign cloud-integrated backup with local encryption key custody.
- AI/ML data protection:Training dataset versioning and model checkpoint preservation create new workload categories requiring petabyte-scale immutable storage.
- Utility pricing models:Consumption-based backup-as-a-service contracts displace capital-intensive appliance purchases in mid-market healthcare and legal verticals.
Industry Challenges
- Immutable architecture integration:Retrofitting air-gapped snapshot capabilities into legacy scale-up arrays requires firmware rewrites that extend certification timelines.
- Ransomware recovery expertise:Shortage of incident responders who understand granular file restoration from deduplicated stores slows enterprise deployment confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disk-Based Backup System Market |
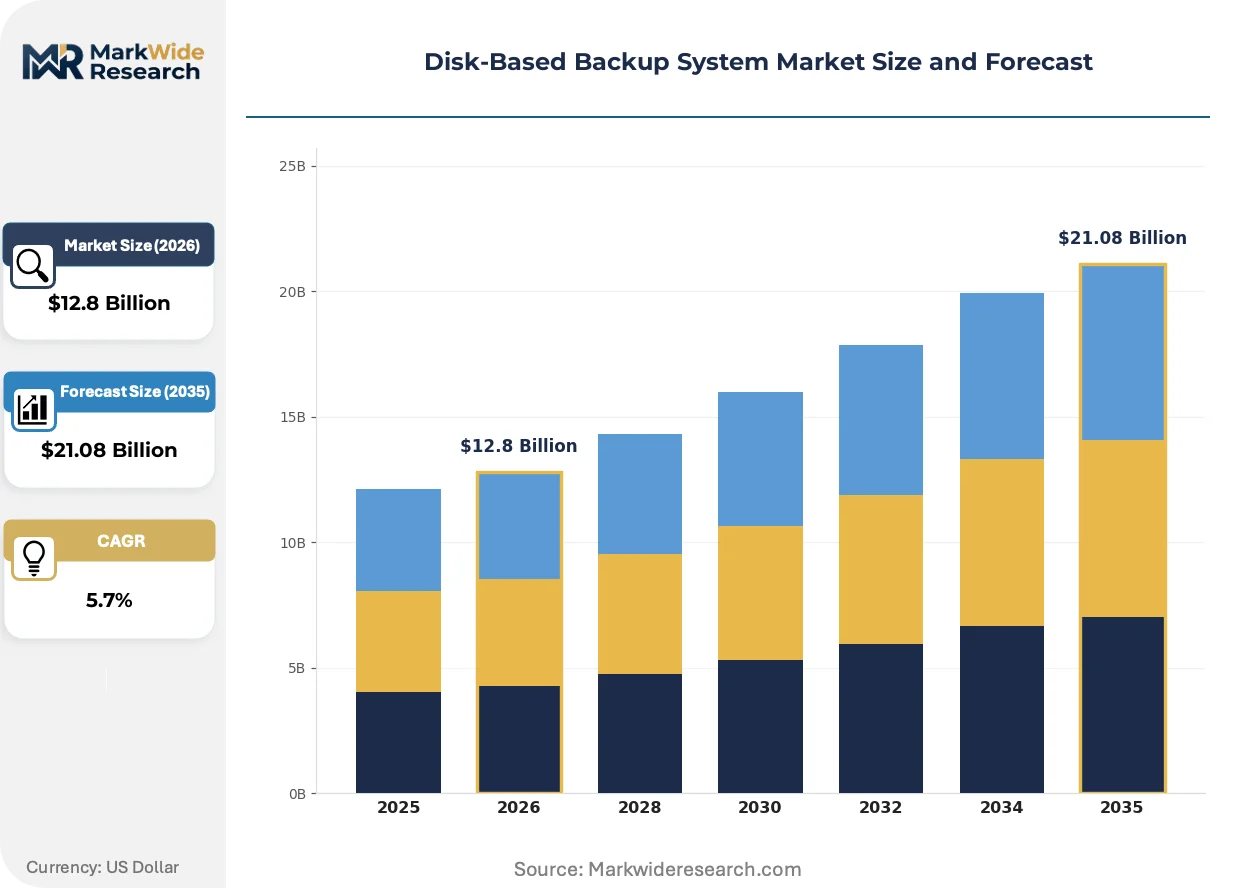
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External HDD, NAS, RAID, SAN Deployment: On-Premise, Hybrid, Cloud, Offsite End User: SMBs, Enterprises, Government, Education Technology: Data Deduplication, Encryption, Snapshot, Cloud Backup |
| Companies Covered | Dell PowerProtect Data Domain, HPE StoreOnce, ExaGrid EX, Datto SIRIS, NetApp Cloud Backup, Veeam Software, Commvault Systems, Veritas Technologies, Cohesity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disk-Based Backup System Market Strategic Shifts
Software-defined storage controllers are collapsing the distinction between primary and secondary data tiers. Vendors now compete on unified data management rather than backup-specific feature sets.
Immutable snapshot technology is unifying ransomware defense with long-term retention compliance. Healthcare providers and financial institutions deploy these architectures fastest, with Germany and Japan showing quarter-over-quarter acceleration. The convergence is unifying procurement decisions under chief information security officers rather than infrastructure managers alone.
SEC cybersecurity disclosure rules now mandate material incident reporting within four business days. Public companies must demonstrate backup integrity and recovery testing documentation to auditors. Healthcare and asset management segments in the United States are restructuring vendor evaluation scorecards around these attestations.
Buyer committees now require total cost of ownership models spanning seven-year retention horizons. Tape elimination business cases dominate capital approval processes in manufacturing and energy verticals. This pattern is most pronounced in Japan, where METI guidelines explicitly discourage magnetic tape for critical operational technology data.
Disk-Based Backup System Market Segmentation
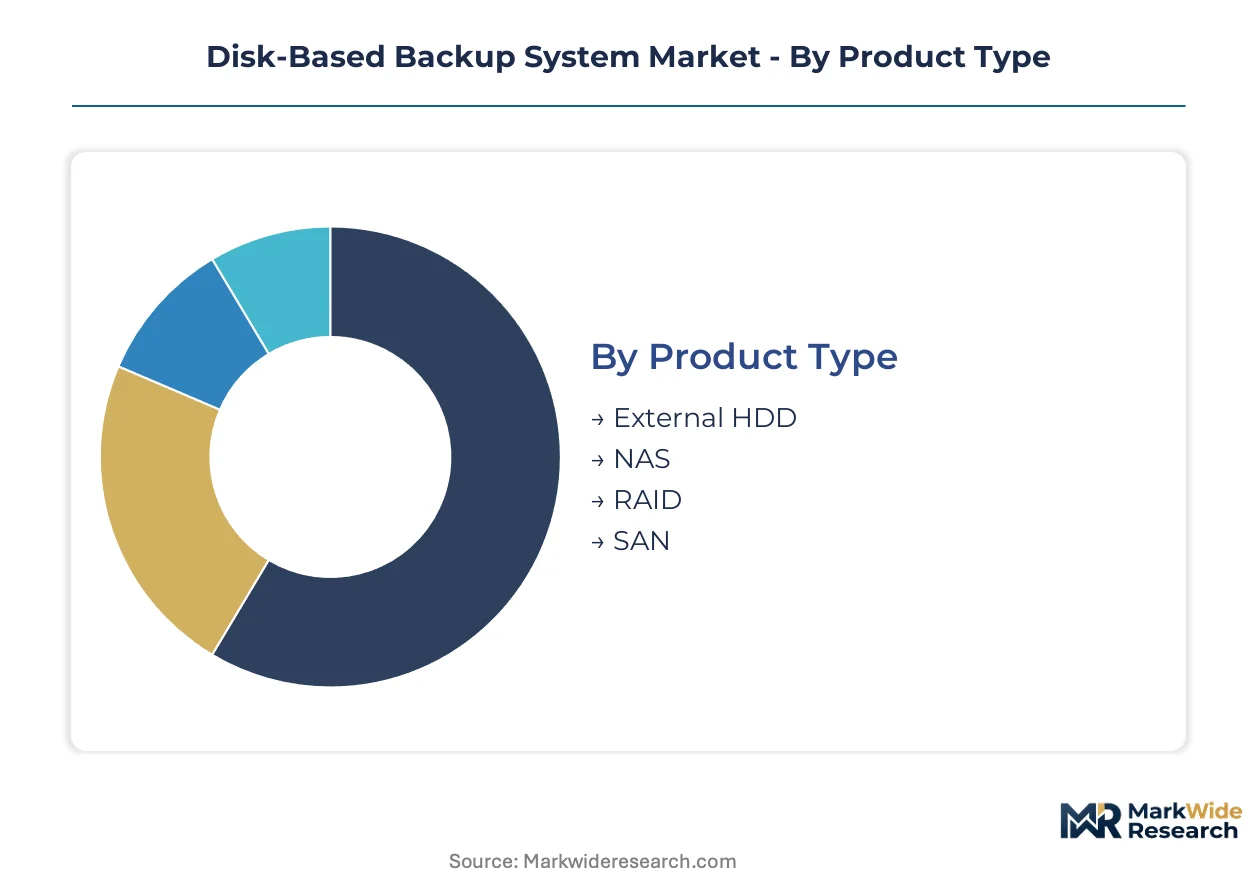
Disk-based backup architectures fragment across hardware form factors, deployment topologies, and data protection methodologies. Procurement committees evaluate these dimensions against recovery time objectives, compliance mandates, and total cost of ownership horizons spanning seven-year retention cycles.
Product Type:
Standardized appliance configurations dominate high-volume procurement, while modular scale-out architectures command premium positioning through customization flexibility.
- External HDD:Standalone magnetic storage enclosures connect via USB or SAS interfaces for departmental backup workloads. Demand concentrates in education and small business segments across the United States where capital constraints limit appliance investments.
- NAS:Network-attached storage appliances integrate file-level protocols with snapshot scheduling for distributed office environments. German manufacturing clusters favor these systems for operational technology data protection under Bundesdatenschutzgesetz retention requirements.
- RAID:Redundant array configurations stripe data across multiple drives for fault tolerance in single-site deployments.
- SAN:Storage area networks deliver block-level access for enterprise database and virtualization infrastructure backup.
Most installed capacity flows through NAS appliances. Expansion is steepest in SAN configurations supporting virtualization density.
Deployment:
Capital intensity decreases across the spectrum from owned infrastructure to consumption-based service models, reshaping customer acquisition economics.
- On-Premise:Physically controlled hardware residing in enterprise data centers or colocation facilities. Japanese automotive manufacturers under METI guidelines deploy these systems for air-gapped operational technology protection against ransomware.
- Hybrid:Unified architectures synchronizing local retention with cloud tiering for geographic redundancy. Financial services firms in the United States favor this topology for SEC cybersecurity disclosure rule compliance with sub-four-day recovery attestations.
- Cloud:Fully managed backup-as-a-service eliminating hardware ownership.
- Offsite:Secondary data center replication for disaster recovery scenarios.
Hybrid deployments capture the majority of new enterprise commitments. Cloud-native substitution is climbing the fastest among mid-market healthcare and legal verticals.
End User:
Compliance burden intensity varies sharply across organizational scale and regulatory exposure, concentrating vendor R&D toward certified environments.
- SMBs:Organizations under 500 employees prioritize ease of deployment and minimal IT staffing overhead.
- Enterprises:Multi-site corporations require petabyte-scale deduplication and immutable snapshot capabilities. HIPAA security rule enforcement drives healthcare system procurement in the United States toward architectures with native access logging and encryption tooling.
- Government:Federal and state agencies mandate FIPS-certified encryption and domestic data residency.
- Education:Universities and K-12 districts balance budget constraints against ransomware recovery requirements.
Enterprises account for the dominant share of absolute spending. Government verticals are gaining share fastest as NIST SP 800-53 frameworks tighten procurement specifications.
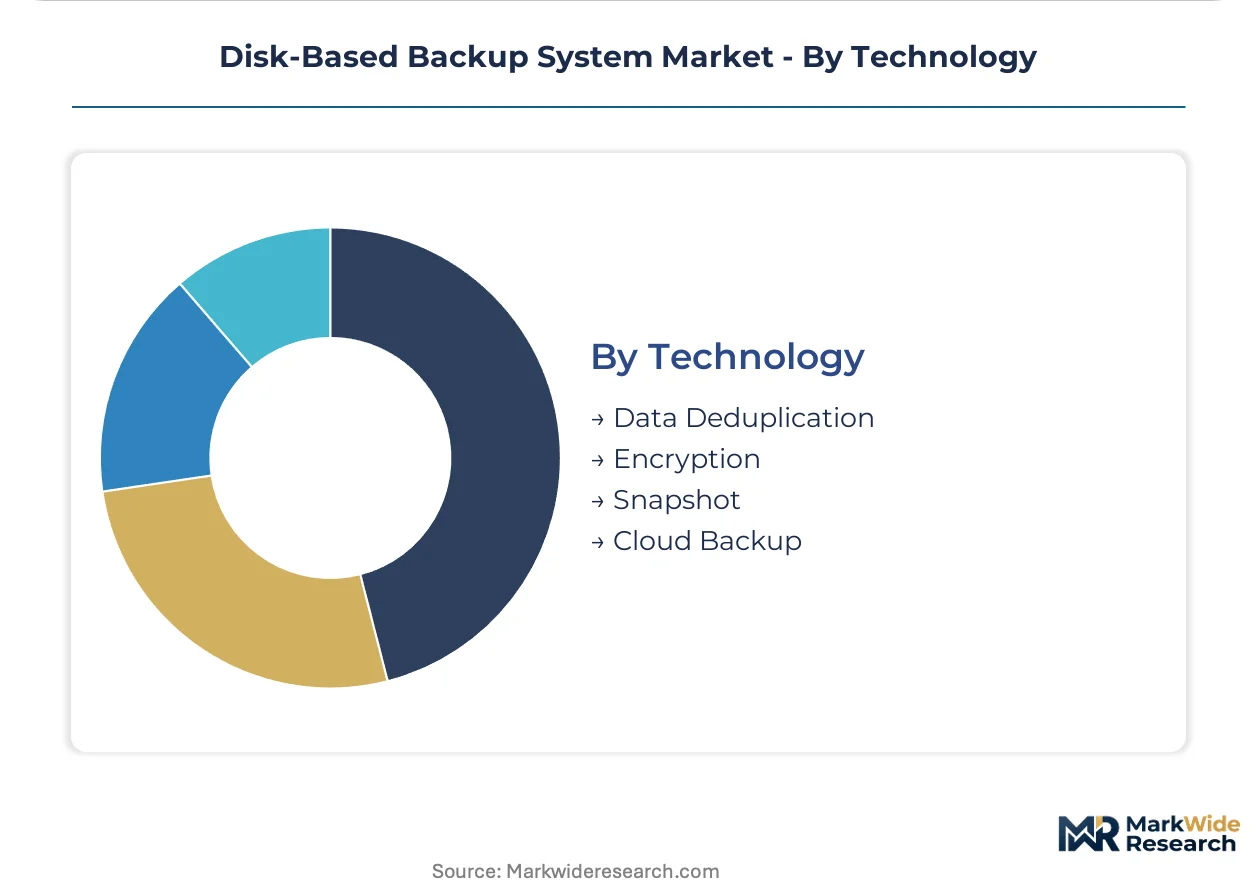
Technology:
Functional sophistication determines margin capture, with basic compression commoditizing while immutable architectures sustain premium pricing.
- Data Deduplication:Block-level redundancy elimination reduces storage overhead across backup windows. Inline implementations from Dell PowerProtect Data Domain sustain throughput leadership in enterprise data centers requiring sustained ingest rates.
- Encryption:AES-256 and proprietary algorithms protect data at rest and in transit. German enterprises under CSRD reporting requirements demand sovereign key custody integrated with local encryption modules.
- Snapshot:Point-in-time copies enable granular file restoration without full backup retrieval.
- Cloud Backup:Object storage tiering and serverless orchestration for distributed retention.
Data deduplication underpins the largest installed base. Immutable snapshot capabilities are expanding most quickly as ransomware defense converges with long-term retention compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise data protection infrastructure originated in United States technology corridors during the 1990s tape-to-disk transition, with subsequent scaling across German manufacturing hubs and Japanese automotive centers as regulatory frameworks hardened.
United States
Financial services firms and healthcare systems drive hybrid deployment procurement under SEC cybersecurity disclosure mandates. HIPAA security rule enforcement tightens encryption and access logging requirements for backup architectures. Boston and New York metro corridors concentrate enterprise data center modernization projects eliminating legacy tape infrastructure.
Germany
Automotive and industrial machinery clusters demand sovereign cloud-integrated backup with local encryption key custody. Bundesdatenschutzgesetz enforcement and CSRD reporting requirements shape procurement specifications. Bavaria and Baden-Württemberg manufacturing belts anchor migration from tape to disk-based recovery systems for operational technology protection.
Japan
Automotive and electronics manufacturers accelerate enterprise migration from magnetic tape under METI industrial data security guidelines. Air-gapped operational technology protection requirements concentrate demand in Nagoya and Osaka industrial corridors. Domestic appliance vendors compete on recovery time objectives against multinational alternatives.
United Kingdom
Financial services and legal sectors restructure vendor evaluation scorecards around SEC-aligned recovery attestations and GDPR retention mandates. London and Southeast technology corridors concentrate cloud backup-as-a-service adoption among mid-market professional services firms. NHS digital transformation programs drive healthcare infrastructure refresh cycles.
India
IT services exporters and domestic banking networks expand data protection infrastructure under RBI cybersecurity guidelines. Mumbai and Bangalore technology corridors concentrate enterprise backup deployments supporting cloud migration workloads. Mid-market manufacturing in Gujarat and Tamil Nadu adopts utility-priced backup services to bypass capital-intensive appliance procurement.
Disk-Based Backup System Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with storage heritage. Appliance vendors and software-defined specialists divide the landscape between hardware-centric and cloud-native delivery models. Three archetypes dominate: inline deduplication appliance manufacturers, scale-out architecture specialists, and unified data management platform vendors. Consolidation through strategic acquisitions and portfolio diversification into immutable snapshot capabilities represent the primary competitive vectors reshaping vendor positioning.
Within the appliance-centric tier, Dell PowerProtect Data Domain and HPE StoreOnce exemplify throughput-optimized architectures competing on sustained ingest rates in enterprise data centers. ExaGrid EX occupies a differentiated position through scale-out engineering that competes on recovery time objectives against monolithic alternatives. Among software-defined specialists, Veeam Software and Commvault Systems anchor cloud-native and hybrid deployment segments with platform approaches collapsing primary-secondary storage boundaries. Cohesity represents the converged data management archetype unifying backup, file, and object services under single-pane orchestration.
| Leading Market Players |
|---|
| Dell PowerProtect Data Domain |
| HPE StoreOnce |
| ExaGrid EX |
| Datto SIRIS |
| NetApp Cloud Backup |
| Veeam Software |
| Commvault Systems |
| Veritas Technologies |
| Cohesity |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent concentration in Taiwan and South Korea widens pricing spreads between premium inline-deduplication appliances and economy-tier external HDD configurations. Labor-cost differentials in controller ASIC design centers translate directly into margin structures across deployment tiers.
Pricing Analysis
Consumption-based backup-as-a-service contracts anchor the dominant pricing structure across mid-market healthcare and legal verticals. Price differentiation rests on deduplication efficiency grades and FIPS certification tiers rather than raw capacity metrics. Cost compression in all-flash backup arrays intensifies because NAND pricing volatility compresses hardware margins. SMB buyers exhibit highest price sensitivity, while financial services enterprises prioritize recovery time objectives over unit economics.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Japan anchor hub-and-spoke fulfillment patterns for controller ASICs and high-capacity HDD components. Raw material dependencies center on NAND flash wafers, rare earth magnets for spindle motors, and specialized power management semiconductors. Single-source vulnerability in Taiwan-based controller fabrication exposes appliance manufacturers to geopolitical disruption. Distribution runs through authorized value-added resellers and direct OEM channels into enterprise data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disk-based backup system market functions as a geographic-arbitrage play where German CSRD compliance costs and Japanese METI guideline enforcement create 15-20% pricing premiums versus North American deployments.
For Market Incumbents: Deepen immutable snapshot firmware development to defend against cloud-native substitution threatening mid-market appliance sales. Prioritize backward integration into controller ASIC supply chains to mitigate Taiwan concentration risk. Accelerate certification timelines for NIST SP 800-53 and SEC cybersecurity disclosure rule alignment. For New Entrants and Emerging Players: Enter via utility-priced backup-as-a-service targeting Indian mid-market manufacturing under RBI cybersecurity guideline pressure. White-space concentrates in AI/ML training dataset versioning workloads requiring petabyte-scale immutable storage. Lead with consumption-based contracts displacing capital-intensive appliance procurement in Gujarat and Tamil Nadu industrial corridors. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, consolidating software-defined backup platforms to unify primary-secondary storage orchestration. Long-term viability hinges on immutable architecture differentiation rather than deduplication throughput alone. Monitor FDA 21 CFR Part 11 validation pipeline acceleration as inflection indicator for life sciences vertical expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Snapshot Architecture Development | FDA 21 CFR Part 11 compliance expands qualified vendor pools for validated backup environments in life sciences. |
| Hybrid Deployment Platform Integration | SEC cybersecurity disclosure rules mandate sub-four-day recovery attestations driving financial services procurement. |
| Backward Integration into Controller ASIC Supply | Taiwan concentration risk in high-capacity HDD components threatens appliance manufacturer delivery timelines. |
| Consumption-Based Pricing Model Expansion | Utility contracts displace capital-intensive purchases in mid-market healthcare verticals under HIPAA enforcement. |
| AI/ML Data Protection Capability Addition | Training dataset versioning creates petabyte-scale immutable storage demand from autonomous vehicle manufacturers. |
Study Parameters
Direct dialogue with data center infrastructure directors, CISO procurement committees, backup software integration specialists, and hyperscaler storage architects grounded qualitative findings. Secondary validation drew from SEC cybersecurity disclosure filings, NIST SP 800-53 revision documentation, FDA 21 CFR Part 11 guidance updates, and METI industrial data security guideline releases. Bottom-up appliance shipment estimates and top-down enterprise IT spending patterns underwent cross-triangulation.
Segment-level value outputs across hardware form factors, deployment topologies, and end-user scales were derived through structured projection frameworks. CAGRs were computed from modeled annual growth trajectories incorporating inline deduplication adoption curves, immutable snapshot penetration rates, and cloud-native substitution elasticities. Forecast inputs included ransomware incident frequency data and regulatory compliance deadline clustering.
Inputs from primary stakeholder interviews and regulatory agency documentation were available through the study window; gaps in real-time NAND pricing volatility data introduce uncertainty bands around all-flash array forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Storage Software Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Brazil Data Center Storage Market