
 Global in-Memory Database Market | 2026-2036
Global in-Memory Database Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Memory Database Market Foresight
Enterprise-grade throughput specifications are rotating toward sub-millisecond latency benchmarks as the baseline expectation for competitive in-memory database offerings. SAP SE leverages its HANA platform to dominate high-performance analytical workloads across European manufacturing clients. Oracle Corporation anchors its position through in-house production of Sparc-optimized silicon that accelerates in-memory processing. Redis Ltd. specializes in key-value architectures that sustain developer preference for caching and session management at internet scale.
An in-memory database stores data directly in RAM rather than on disk, enabling microsecond-range read/write speeds through columnar compression and parallel query execution across multi-core architectures. Its primary purpose is to power real-time decision systems where disk-based latency would invalidate operational value. Cloud-native deployment now leads expansion as hyperscaler integration and elastic scaling reshape procurement patterns for enterprise buyers. NoSQL database types represent the fastest-growing category as graph and time-series variants capture fraud detection and IoT telemetry workloads. Relational in-memory engines retain the largest margin pools within BFSI end-user industries due to ACID compliance requirements and established vendor relationships.
The EU AI Act and GDPR data-localization mandates are forcing European enterprises toward hybrid cloud architectures that keep sensitive training data within jurisdictional boundaries. The FCC's spectrum management rules and the SEC's market data infrastructure standards in the United States shape latency requirements for financial trading applications. ISO 27001 and IEC 62304 certifications increasingly determine market access for vendors serving regulated healthcare and telecommunications sectors. Stakeholders must monitor how divergent national data sovereignty laws will fragment deployment standards and complicate multi-cloud strategies.
Market Dynamics
Cloud-native deployment architectures are displacing legacy on-premises installations across financial services hubs, compressing procurement cycles and forcing incumbent vendors to restructure pricing models around consumption-based metering rather than perpetual licensing.
Growth Catalysts
- EU AI Act data-localization mandates:European enterprises must maintain sensitive training data within jurisdictional boundaries, accelerating hybrid cloud in-memory database deployments that satisfy sovereignty requirements.
- Real-time fraud detection workloads:Banking and payment processors require sub-millisecond transaction analysis, pulling columnar in-memory engines into core operational infrastructure.
- India's domestic data sovereignty framework:RBI guidelines and proposed data protection legislation are compelling financial institutions to localize processing infrastructure, expanding addressable market for regional deployment specialists.
Market Restraints
- DRAM cost volatility:Memory-intensive architectures expose total cost of ownership to semiconductor input price swings, compressing margin predictability for enterprise buyers.
- GDPR compliance friction:Right-to-erasure requirements complicate persistent in-memory data structures, forcing architectural workarounds that degrade performance advantages.
- Relational engine substitution threat:Disk-optimized databases with intelligent caching layers narrow the latency gap for non-critical workloads, limiting addressable use cases.
Strategic Opportunities
- Underpenetrated German manufacturing sector:Industrial IoT telemetry and predictive maintenance applications remain nascent, creating whitespace for time-series optimized in-memory platforms.
- 5G network slicing monetization:Telecommunications operators in the United States require edge-resident databases for latency-guaranteed services, opening distributed deployment models.
- Convergence with confidential computing:Hardware-based enclaves from Intel SGX and AMD SEV enable encrypted in-memory processing, unlocking regulated healthcare and government verticals previously blocked by security requirements.
Industry Challenges
- Distributed systems engineering talent scarcity:Shortage of engineers proficient in consensus protocols and partition tolerance limits vendor scaling velocity and implementation quality.
- ISO 27001 certification timeline compression:Healthcare and telecommunications procurement gates require updated documentation cycles that delay product release schedules by quarters.
- Legacy mainframe integration complexity:COBOL-era transaction systems in United States banking resist API modernization, forcing costly middleware layers that erode in-memory latency advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Memory Database Market |
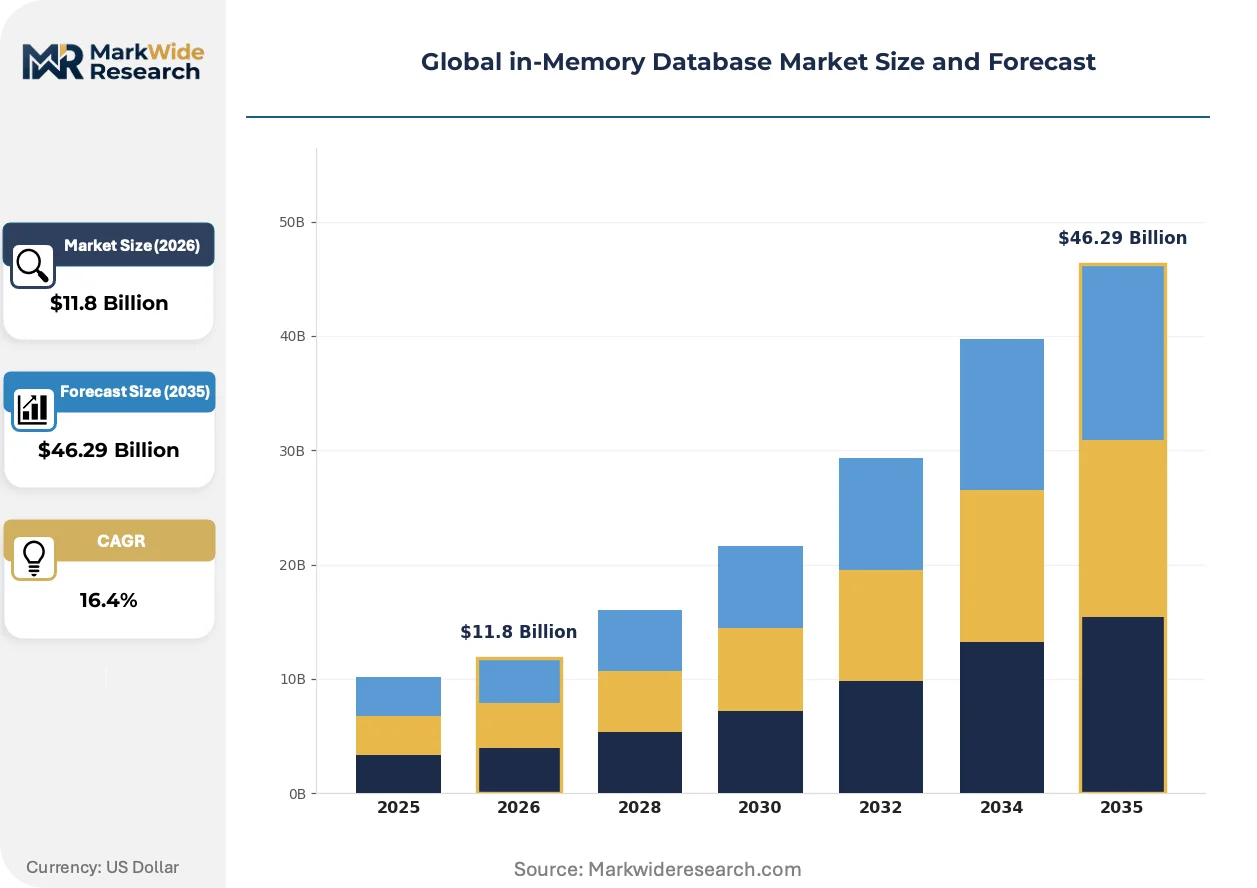
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $46.29 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Native, Hybrid Cloud, Multi-Cloud Database Type: Relational, NoSQL, Key-Value Store, Graph, Time Series Application: Real-Time Analytics, Fraud Detection, Customer 360, Supply Chain Optimization End User Industry: BFSI, Telecommunications, Manufacturing, Media & Entertainment |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, IBM Corporation, Amazon Web Services, Redis Ltd., TIBCO Software Inc., Couchbase, SingleStore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Memory Database Market Shifts & Advancements
Query execution architectures are fragmenting as specialized engines displace general-purpose platforms, with columnar, graph, and vector variants each capturing distinct workload types previously consolidated under relational umbrellas.
Hybrid transaction/analytical processing is fragmenting workload consolidation assumptions that dominated prior-generation database procurement. Financial services firms in Germany and the United States now deploy separate engines for operational and analytical streams rather than converging on single platforms. This specialization is fragmenting vendor account control and expanding multi-database environments within single enterprises.
The EU AI Act's training data governance requirements are forcing architectural modifications to in-memory systems that cache model inputs. European enterprises must implement automated data lineage tracking and jurisdictional tagging within RAM-resident datasets. Healthcare AI developers in France and Germany face the steepest compliance burdens, driving preference toward vendors with pre-certified sovereign cloud integrations.
Consumption-based pricing is replacing perpetual licensing across North American and European enterprise procurement. Buyers in United States banking and German automotive sectors now meter in-memory capacity by actual query throughput rather than provisioned hardware. This behavioral shift compresses vendor revenue recognition cycles and accelerates customer switching between cloud-native alternatives.
Global in-Memory Database Market Segmentation
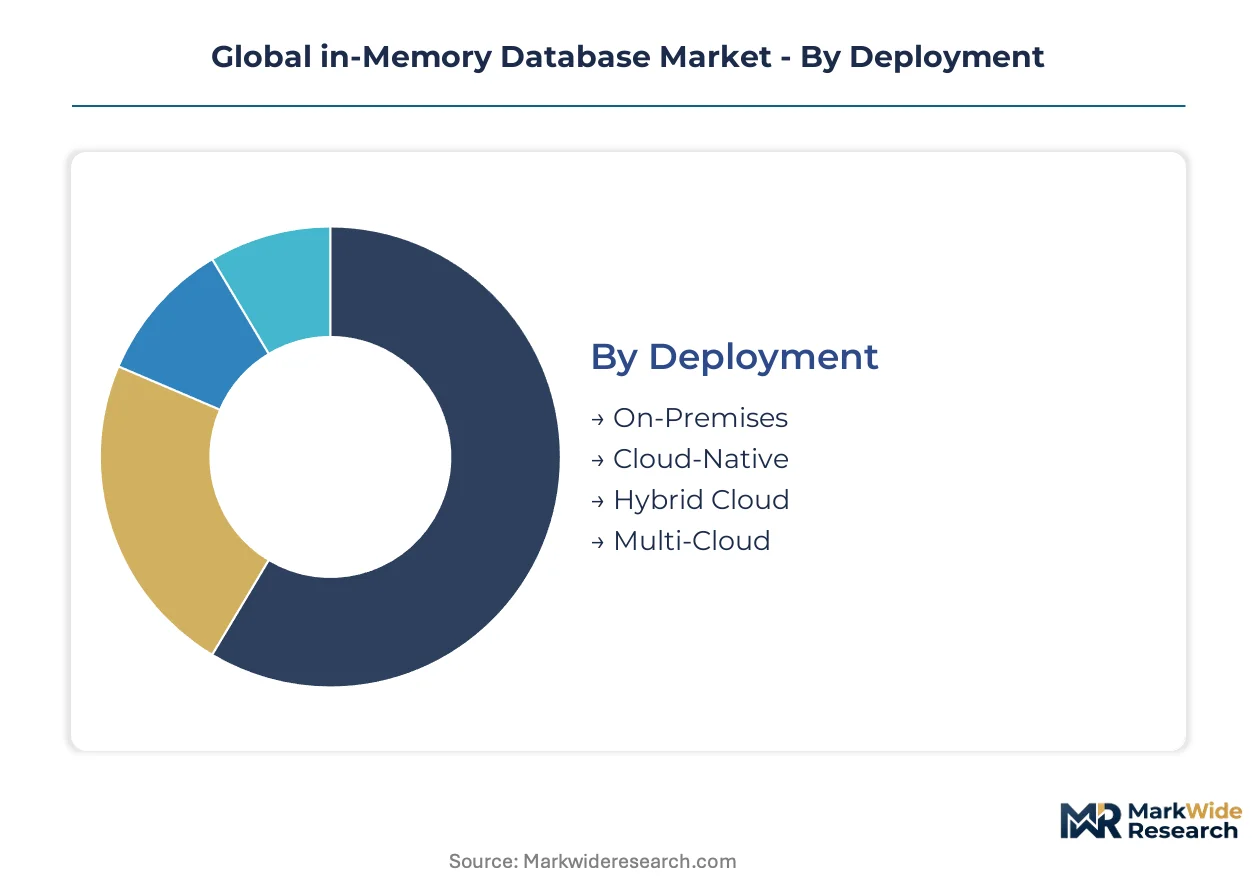
In-memory database procurement fractures along deployment topology, data model architecture, and workload specificity. Buyers now select purpose-built engines rather than consolidating on single platforms, fragmenting vendor account control and expanding multi-database estates within single enterprises.
Deployment:
Substitution pressure from intelligent disk caching and tiered storage architectures threatens on-premises installations most acutely, while cloud-native variants capture elastic workload expansion.
- On-Premises:Dedicated hardware deployments in sovereign data centers deliver deterministic latency for algorithmic trading and classified government workloads. United States banking hubs in New York and Chicago retain these installations for SEC market data infrastructure compliance, though procurement cycles compress as cloud alternatives mature.
- Cloud-Native:Containerized architectures with hyperscaler integration enable elastic scaling across transaction spikes and analytical batch windows. German automotive manufacturers in Stuttgart and Munich are migrating production telemetry pipelines to these platforms to satisfy EU AI Act data-localization mandates through regional cloud zones.
- Hybrid Cloud:Split architectures keep sensitive operational data on-premises while bursting analytical workloads to public cloud. India's RBI guidelines are compelling Mumbai financial institutions toward this topology for domestic data sovereignty.
- Multi-Cloud:Distributed deployments across AWS, Azure, and GCP reduce vendor lock-in and improve resilience for internet-scale applications. Telecommunications operators in the United States leverage these for 5G network slicing monetization.
On-Premises retains volume leadership; Cloud-Native holds the steepest expansion curve.
Database Type:
Cost tier stratification separates high-margin relational engines from commodity key-value alternatives, with specialized variants capturing premium pricing for analytical and temporal workloads.
- Relational:ACID-compliant engines with SQL interfaces dominate BFSI core banking systems where transaction integrity overrides raw throughput. These platforms command the largest margin pools due to established vendor relationships and certification requirements for ISO 27001 and IEC 62304.
- NoSQL:Schema-flexible architectures with document and wide-column stores accelerate internet-of-things telemetry ingestion and customer profile unification. Graph and time-series variants within this category are climbing the fastest as fraud detection and predictive maintenance workloads proliferate.
- Key-Value Store:Lightweight structures optimized for caching and session management sustain developer preference at internet scale. Redis architectures dominate this tier with sub-millisecond latency for e-commerce and gaming applications.
- Graph:Native edge-vertex storage enables real-time relationship traversal for anti-money laundering and recommendation engines. Financial services firms in Germany deploy these for complex counterparty risk analysis.
- Time Series:Compressed columnar formats with temporal indexing optimize industrial IoT and observability data streams. Manufacturing clients in India are piloting these for predictive maintenance on production lines.
Relational engines dominate revenue concentration; Time Series is gaining share fastest among specialized variants.
Application:
Application maturity diverges sharply, with real-time analytics approaching commoditization while customer unification and supply chain optimization remain underpenetrated whitespace.
- Real-Time Analytics:Sub-second query execution across streaming and historical datasets powers operational dashboards and automated decision systems. United States financial services firms have saturated this use case, compressing differentiation and pricing power for general-purpose platforms.
- Fraud Detection:Millisecond-range transaction scoring with machine learning inference requires columnar in-memory engines with vectorized execution. Banking and payment processors in India are pulling these into core infrastructure as digital transaction volumes surge.
- Customer 360:Unified profile aggregation across touchpoints demands graph and document stores with flexible schema evolution. European retailers under GDPR constraints are expanding deployments with automated data lineage tracking.
- Supply Chain Optimization:Multi-echelon inventory and logistics modeling with simulation capabilities remains nascent. German manufacturing hubs represent significant whitespace as industrial IoT telemetry volumes accelerate.
Real-Time Analytics saturates procurement attention; Supply Chain Optimization presents the largest untapped expansion opportunity.
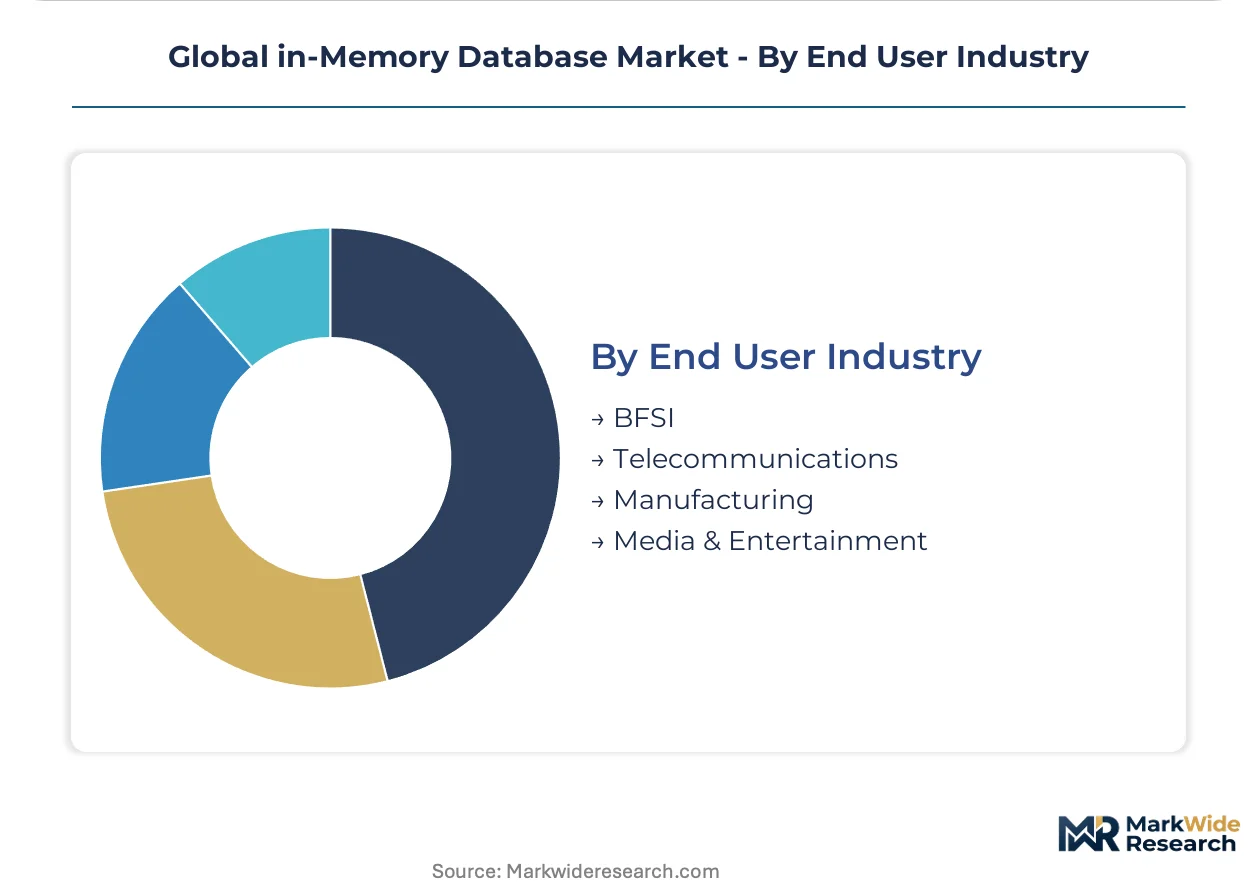
End User Industry:
Customer type concentration varies by compliance burden and latency sensitivity, with BFSI and telecommunications anchoring premium pricing while manufacturing and media segments price-shop commoditized alternatives.
- BFSI:Trading systems, risk engines, and regulatory reporting infrastructure demand the highest reliability tiers with sub-millisecond guarantees. United States and German institutions concentrate procurement spend here, driving relational engine preference for ACID compliance.
- Telecommunications:Subscriber data management, billing mediation, and 5G edge services require distributed in-memory grids with geographic redundancy. FCC spectrum management rules shape latency requirements for United States operators deploying network slicing.
- Manufacturing:Predictive maintenance and quality control applications are emerging from pilot phases as industrial IoT sensor densities increase. Time-series optimized platforms are penetrating this segment in Germany and India.
- Media & Entertainment:Real-time personalization and content recommendation engines operate at lower reliability tiers with higher tolerance for eventual consistency. Key-value and document stores dominate this price-sensitive vertical.
BFSI commands premium pricing concentration; Manufacturing is expanding most quickly as Industry 4.0 investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering talent clusters in the United States, Germany, and India, while cloud infrastructure investments concentrate in financial hubs subject to data sovereignty mandates. Procurement patterns diverge sharply between mature banking centers and emerging manufacturing digitization zones.
United States
Algorithmic trading platforms and real-time risk engines drive demand for sub-millisecond latency systems. SEC market data infrastructure standards shape procurement specifications for New York and Chicago banking hubs. Cloud-native deployments are displacing legacy installations as FCC spectrum rules enable 5G edge monetization.
Germany
Industrial IoT telemetry and predictive maintenance applications are accelerating time-series database adoption. EU AI Act data-localization mandates force hybrid architectures that keep sensitive training data within regional cloud zones. Stuttgart and Munich automotive manufacturers are migrating production pipelines to sovereign cloud integrations.
India
Digital payment volume surges are pulling columnar in-memory engines into core banking infrastructure. RBI guidelines and proposed data protection legislation compel Mumbai financial institutions toward hybrid cloud topologies. Manufacturing clusters in Pune and Bengaluru are piloting predictive maintenance platforms.
United Kingdom
Financial services firms in London are fragmenting workload consolidation assumptions across separate operational and analytical engines. GDPR compliance friction shapes architectural decisions for persistent in-memory data structures. The capital's fintech corridor is driving preference toward consumption-based pricing models.
Japan
Telecommunications operators require edge-resident databases for latency-guaranteed 5G services. METI industrial digitization programs are expanding addressable markets for manufacturing analytics. Tokyo and Osaka financial centers maintain relational engine preference for ACID-compliant core systems.
Global in-Memory Database Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated relational incumbents defending margin pools against cloud-native challengers. The vendor base stratifies across three tiers: established enterprise software conglomerates with certification depth, hyperscaler-integrated platforms with consumption-based metering, and specialized key-value architects with developer ecosystem lock-in. Strategic moves concentrate on M&A for workload-specific engines and restructuring pricing models around elastic capacity.
Among established European software conglomerates, SAP SE exemplifies the high-performance analytical workload archetype through its vertically integrated platform approach. Oracle Corporation anchors the silicon-optimized tier with in-house processor production. Redis Ltd. occupies the specialized caching tier with developer-preferred architectures for internet-scale session management.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Redis Ltd. |
| TIBCO Software Inc. |
| Couchbase |
| SingleStore |
| Others |
Supply & Pricing Matrix
ISO 27001 certification timelines gate both supply qualification and price differentiation simultaneously, as vendors serving regulated BFSI and healthcare sectors must absorb documentation cycles that compress margin pools while justifying premium tiers through compliance depth.
Pricing Analysis
GDPR right-to-erasure mandates dictate the pricing tier structure across European deployments, forcing architectural workarounds that degrade performance and push buyers toward premium certified tiers. Consumption-based metering now dominates cloud-native procurement, separating hyperscaler-integrated platforms from perpetual-licensed on-premises alternatives. Pricing pressure stems from intelligent disk caching narrowing latency gaps for non-critical workloads. Mid-market manufacturing buyers exhibit highest price sensitivity, while United States banking hubs tolerate premium tiers for SEC-compliant sub-millisecond guarantees.
Supply Chain Analysis
Container availability fluctuations across Asia-Pacific trade lanes expose DRAM module procurement to volatility, as memory-intensive architectures anchor total cost of ownership to semiconductor input swings. Supply concentrates in South Korea, Taiwan, and United States for advanced DRAM fabrication, with downstream assembly drawing from China and Malaysia. Raw material dependencies span silicon wafers, specialized packaging substrates, and rare earth elements for chip fabrication. Single-source vulnerability around EUV lithography equipment creates chokepoint risk. Distribution runs through hyperscaler procurement channels and direct enterprise sales with regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as DRAM pricing normalizes following supply glut absorption, with memory-intensive infrastructure investments resuming across financial services modernization programs.
For Market Incumbents: Consolidate certification depth around ISO 27001 and IEC 62304 to defend relational engine margin pools against cloud-native challengers. Deepen backward integration into silicon optimization, following Oracle's Sparc production model, to escape commodity DRAM cost volatility. Lock in United States banking hubs through SEC-compliant latency guarantees that emerging vendors cannot replicate without certification timelines. For New Entrants and Emerging Players: Differentiate on sovereign cloud integrations targeting EU AI Act compliance burdens in Germany and France where incumbent architectures require retrofit. Target India's domestic data sovereignty framework as the most penetrable geography, where RBI guidelines compel localization without established vendor relationships. Pursue manufacturing analytics whitespace in German automotive clusters through time-series optimized platforms with predictive maintenance bundling. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as consumption-based metering reduces upfront infrastructure commitments. Long-term viability favors hyperscaler-integrated platforms with elastic scaling architectures over hardware-dependent on-premises specialists. Target acquisition archetypes include confidential computing specialists with Intel SGX or AMD SEV enclave capabilities. Monitor 5G network slicing monetization progress among United States telecommunications operators as inflection signal for edge-resident database demand.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Hardware-based enclaves unlock regulated healthcare and government verticals previously blocked by security requirements. |
| Sovereign Cloud Partnership | Regional cloud zone integrations satisfy EU AI Act data-localization mandates for German automotive manufacturers. |
| Time-Series Engine Acquisition | Specialized temporal indexing capabilities capture industrial IoT telemetry growth in manufacturing analytics. |
| Consumption-Based Pricing Restructure | Elastic capacity metering aligns vendor revenue with actual query throughput in United States banking procurement. |
| 5G Edge Deployment Model | Distributed architectures enable latency-guaranteed services for FCC-regulated network slicing monetization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across financial services, telecommunications, and manufacturing verticals. Secondary validation drew from SEC filings, hyperscaler capex disclosures, regulatory agency guidance documents, and industry certification registries. Bottom-up deployment estimates triangulated against top-down market sizing across deployment topology, data model architecture, and end-user industry segments.
Across the analysis window, volume and value outputs reflect modeling across deployment model, organization size, vertical integration complexity, workload specificity, and regional adoption pattern. CAGRs were derived from segmented growth trajectory analysis with cross-validation against infrastructure investment cycles. Forecast inputs incorporated DRAM pricing elasticity, regulatory compliance timeline compression, and cloud migration velocity indicators specific to financial services modernization.
Material uncertainties — DRAM cost volatility, data sovereignty law divergence, and consensus protocol engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline stability and hyperscaler regional expansion continuity. Recalibration cycles align with material shifts in semiconductor supply conditions and jurisdictional compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
5D Data Storage Market