
 Global Cloud Object Storage Market | 2026-2036
Global Cloud Object Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Object Storage Market Analysis
Flash memory is repositioning disk-based archive economics in cloud object storage tiers. Amazon Web Services Inc. leverages its S3 Glacier Deep Archive to anchor cold storage pricing at fractions of spinning-disk cost. Microsoft Corporation sustains competitive pressure through Azure Blob Storage's intelligent tiering that automates data movement across hot, cool, and archive states. Google LLC differentiates with dual-region buckets that reduce latency for analytics workloads without replication overhead.
Cloud object storage is a flat-address data architecture that stores unstructured content as discrete objects with metadata, unique identifiers, and HTTP-accessible APIs, typically scaling to exabyte capacity across distributed server clusters. Its primary commercial purpose is to replace hierarchical file systems for machine-generated data, media libraries, and backup repositories where horizontal scalability outweighs latency sensitivity. Public cloud deployment captures the dominant revenue share as enterprises exit owned data centers, while hybrid cloud configurations are expanding fastest among regulated industries requiring on-premises encryption key control. Backup and recovery services generate the largest service-type revenue pool, though digital asset management is emerging as a margin-rich segment for media and entertainment clients managing 8K video and game engine assets.
FDA 21 CFR Part 11, EU GDPR, and HIPAA constrain where patient records and clinical trial data may reside, directly shaping multi-cloud procurement patterns among healthcare and pharmaceutical buyers. The EU AI Act adds algorithmic audit-trail requirements that expand immutable object storage demand for model versioning and training-data provenance. Stakeholders must weigh sovereign cloud certifications against hyperscaler interoperability when selecting regional deployment architectures.
Market Dynamics
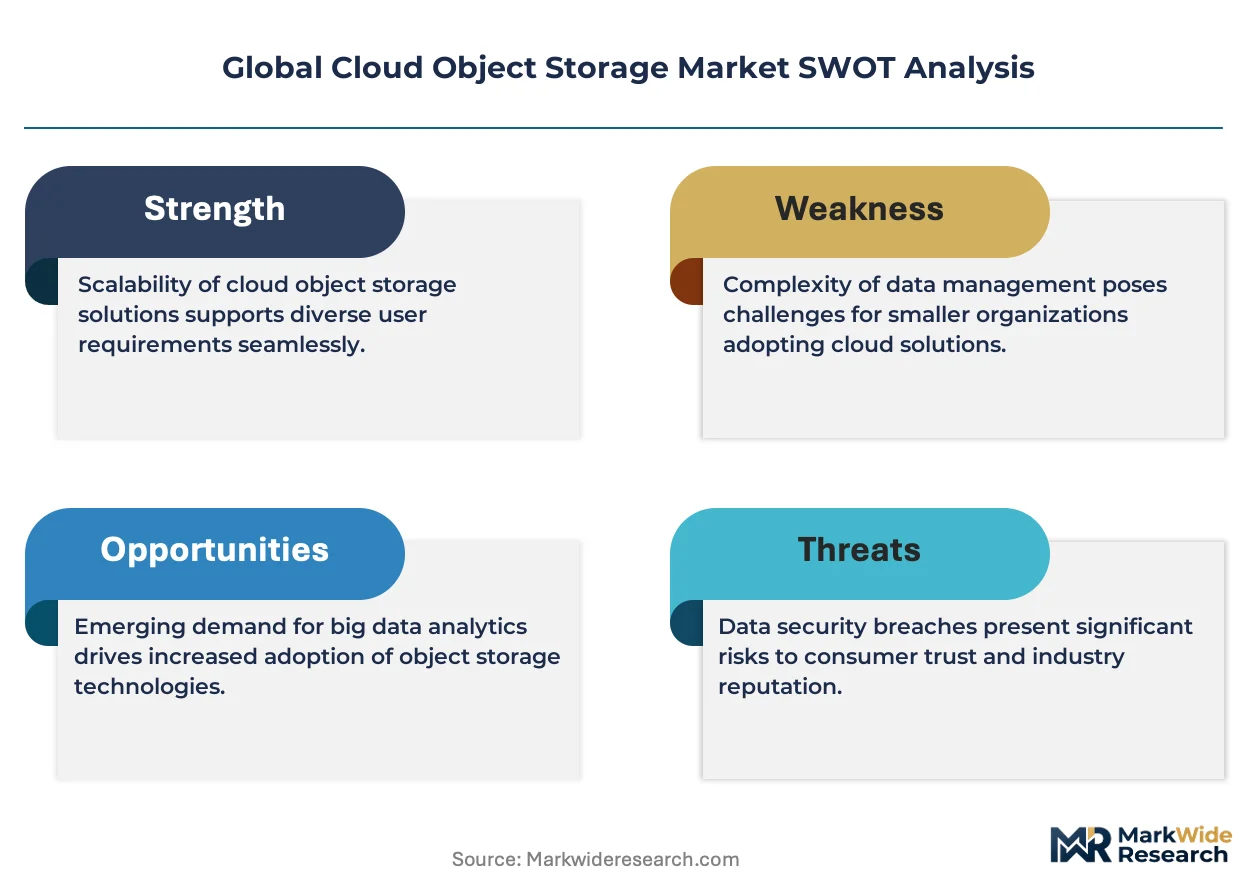
Immutable storage architectures are compressing compliance timelines across financial services and healthcare, forcing infrastructure buyers to reconfigure data sovereignty strategies around specific jurisdictional mandates rather than latency optimization alone.
Growth Catalysts
- EU AI Act audit-trail mandates:Algorithmic provenance requirements are expanding object storage footprints for model versioning and training-data lineage in European AI deployments.
- Flash memory cost curves:Solid-state archive tiers are repositioning cold storage economics, displacing magnetic tape in regulatory retention workloads.
- Healthcare data gravity:FDA 21 CFR Part 11 and HIPAA constraints are pulling pharmaceutical and clinical trial data into sovereign-certified object storage architectures.
Market Restraints
- Egress fee structures:Hyperscaler data retrieval pricing creates lock-in friction for enterprises evaluating multi-cloud portability.
- Encryption key sovereignty:Regulatory demands for customer-managed keys fragment procurement across hybrid and on-premises configurations.
- Tape archive persistence:Magnetic libraries retain cost advantages for petabyte-scale infrequently accessed scientific datasets.
Strategic Opportunities
- German sovereign cloud certifications:Gaia-X compliance frameworks are creating preferred vendor status for EU-data-resident storage operators.
- 8K media pipeline convergence:Game engine and broadcast workflows are merging into unified object storage lakes for real-time rendering.
- Edge-to-core tiering automation:Intelligent lifecycle policies are enabling new consumption models for IoT-generated sensor archives.
Industry Challenges
- Cross-border data localization expertise:Shortage of architects capable of mapping GDPR, HIPAA, and sector-specific retention rules onto unified infrastructure.
- Legacy NAS migration complexity:POSIX-dependent applications resist flat-namespace refactoring, prolonging parallel file system coexistence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Object Storage Market |
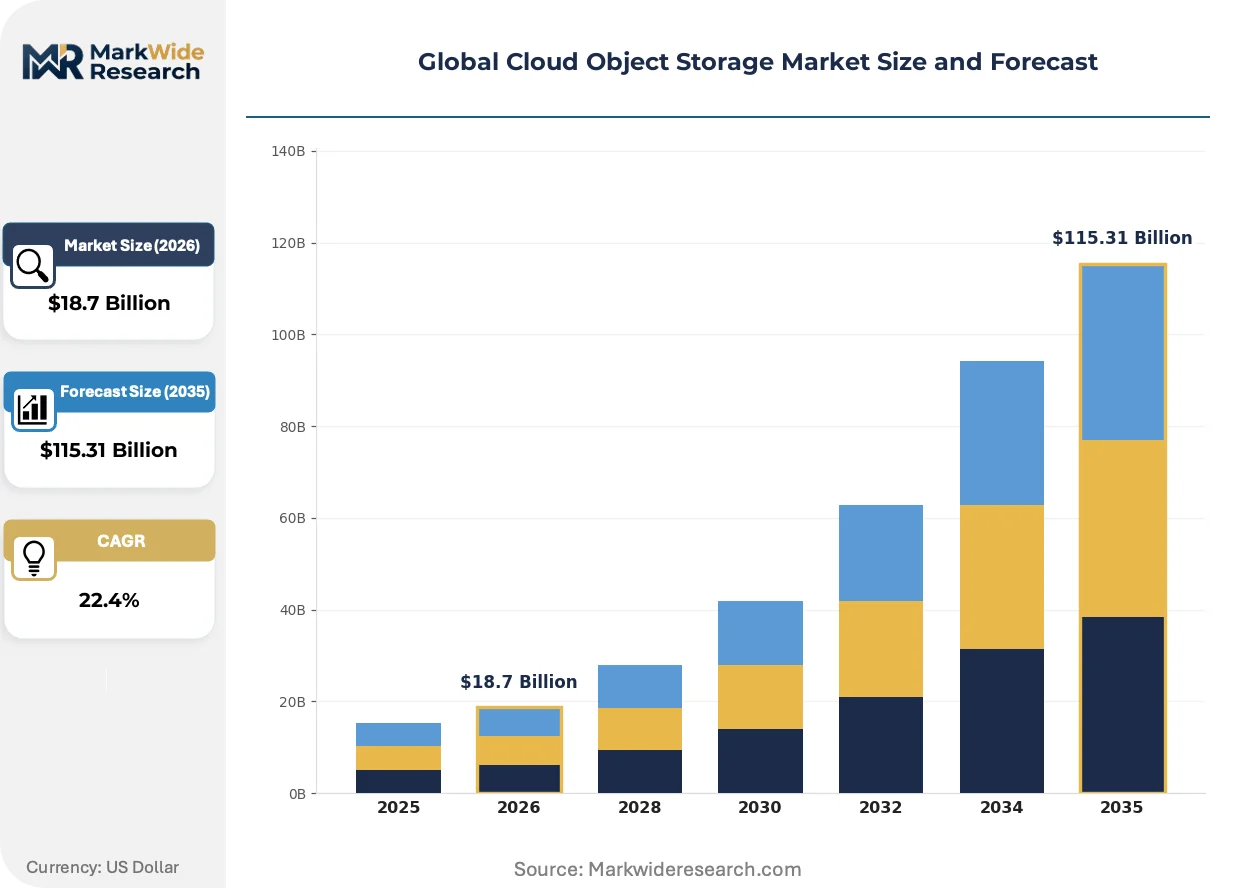
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Backup & Recovery, Data Archiving, Digital Asset Management, Disaster Recovery End User: IT, Media & Entertainment, Healthcare, Retail Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Amazon Web Services Inc., Microsoft Corporation, Google LLC, International Business Machines Corporation, Oracle Corporation, Dell Technologies Inc., Alibaba Cloud Computing, NetApp Inc., Hewlett Packard Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Object Storage Market Emerging Trajectories
Storage-class memory and computational storage drives are collapsing the latency hierarchy between hot and archive tiers, erasing the traditional performance boundaries that once dictated separate infrastructure investments.
Computational storage drives with embedded processing capability are decentralizing analytics execution from centralized compute clusters to the storage layer itself. Media and entertainment studios handling uncompressed 8K footage are adopting these devices to eliminate data movement bottlenecks in color grading pipelines. This architecture is decentralizing the historical separation between storage and compute procurement decisions.
GDPR Article 17 right-to-erasure conflicts with blockchain-anchored immutability requirements are forcing architectural splits in European deployments. Financial services firms in Frankfurt and Amsterdam are segmenting workloads between mutable and immutable object buckets to satisfy competing legal obligations. Healthcare providers are most affected, with clinical trial sponsors maintaining parallel storage environments for different data categories.
Consumption-based capacity contracts are replacing committed-use discounts as the dominant enterprise procurement mechanism. Media streaming platforms and SaaS backup providers are negotiating pay-as-you-grow terms that transfer utilization risk to vendors. Singapore and US East Coast cloud regions show the strongest contract structure migration, driven by venture-backed buyers prioritizing cash-flow flexibility over unit-cost minimization.
Global Cloud Object Storage Market Segmentation
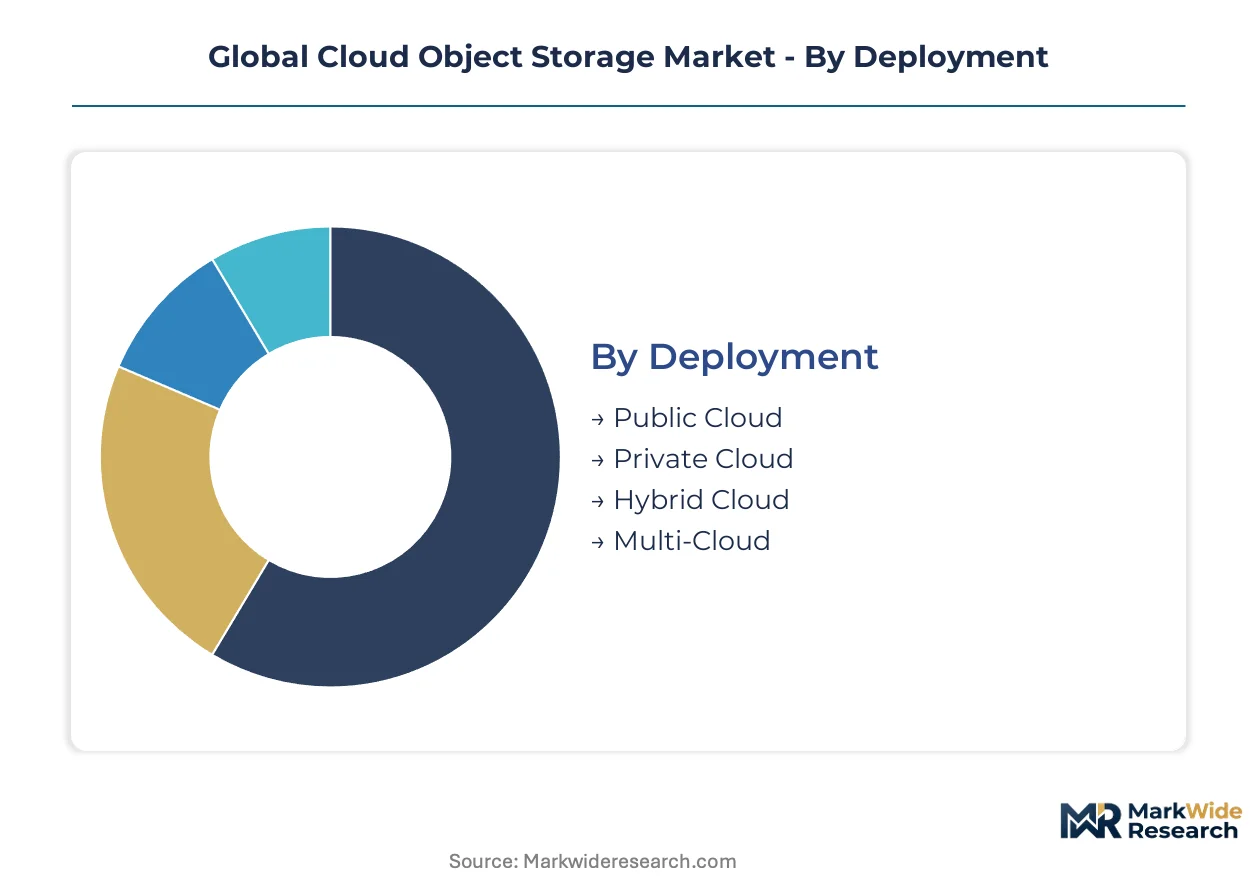
Cloud object storage procurement patterns diverge sharply across deployment models and service types, with regulatory constraints and workload latency requirements driving category-specific vendor selection. Buyers segment infrastructure decisions around data sovereignty mandates, recovery time objectives, and the economics of flash versus tape archive tiers.
Deployment:
Cost tier separates hyperscale buyers from regulated enterprises requiring encryption key custody.
- Public Cloud:Shared infrastructure with metered consumption and API-native access patterns. Demand concentrates among SaaS backup providers and media streaming platforms in Singapore and US East Coast cloud regions, driven by pay-as-you-grow contract structures that prioritize cash-flow flexibility.
- Hybrid Cloud:Split architecture maintaining on-premises encryption key control with burst capacity to public endpoints. Financial services firms in Germany and healthcare providers across the United States favor this model for HIPAA and GDPR compliance, constrained by cross-border data localization expertise shortages.
- Private Cloud:Dedicated hardware deployments within customer-controlled facilities. Sovereign-certified operators in Frankfurt and Amsterdam maintain Gaia-X compliant instances for EU AI Act audit-trail requirements.
- Multi-Cloud:Distributed workloads across competing hyperscaler platforms to mitigate egress fee lock-in. Enterprise procurement is expanding most quickly here as buyers negotiate portability clauses against retrieval pricing friction.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Service Type:
Application criticality determines margin structure, with operational recovery services commanding premium pricing over long-term retention.
- Backup & Recovery:Operational data protection with sub-hour recovery point objectives. This segment captures the largest revenue pool as enterprises exit tape-dependent legacy infrastructure, though flash memory cost curves are repositioning archive economics.
- Digital Asset Management:Metadata-rich repositories for unstructured creative content. Media and entertainment studios in Los Angeles and London are expanding deployments for 8K video and game engine asset pipelines, making this the margin-richest service tier.
- Data Archiving:Immutable long-term retention for regulatory compliance. FDA 21 CFR Part 11 and EU GDPR constraints are pulling pharmaceutical trial data into sovereign-certified architectures.
- Disaster Recovery:Geographically distributed replication for business continuity. Dual-region bucket configurations reduce latency without replication overhead for analytics workloads.
Revenue concentrates in Backup & Recovery; Digital Asset Management climbs the fastest.
End User:
Customer type dictates compliance surface area and data gravity patterns.
- Healthcare:Clinical records and trial data constrained by HIPAA and FDA retention rules. Patient data gravity is forcing architectural splits between mutable and immutable buckets to satisfy GDPR Article 17 erasure conflicts.
- Media & Entertainment:Uncompressed 8K footage and real-time rendering pipelines. Computational storage drives with embedded processing are eliminating data movement bottlenecks in color grading workflows.
- IT:General-purpose infrastructure and DevOps tooling. This segment shows the broadest deployment mix across all capacity tiers.
- Retail:Customer behavior analytics and supply chain sensor archives. Edge-to-core tiering automation is enabling new consumption models for IoT-generated data lakes.
Healthcare leads absolute spend; Media & Entertainment shows steepest expansion trajectory.
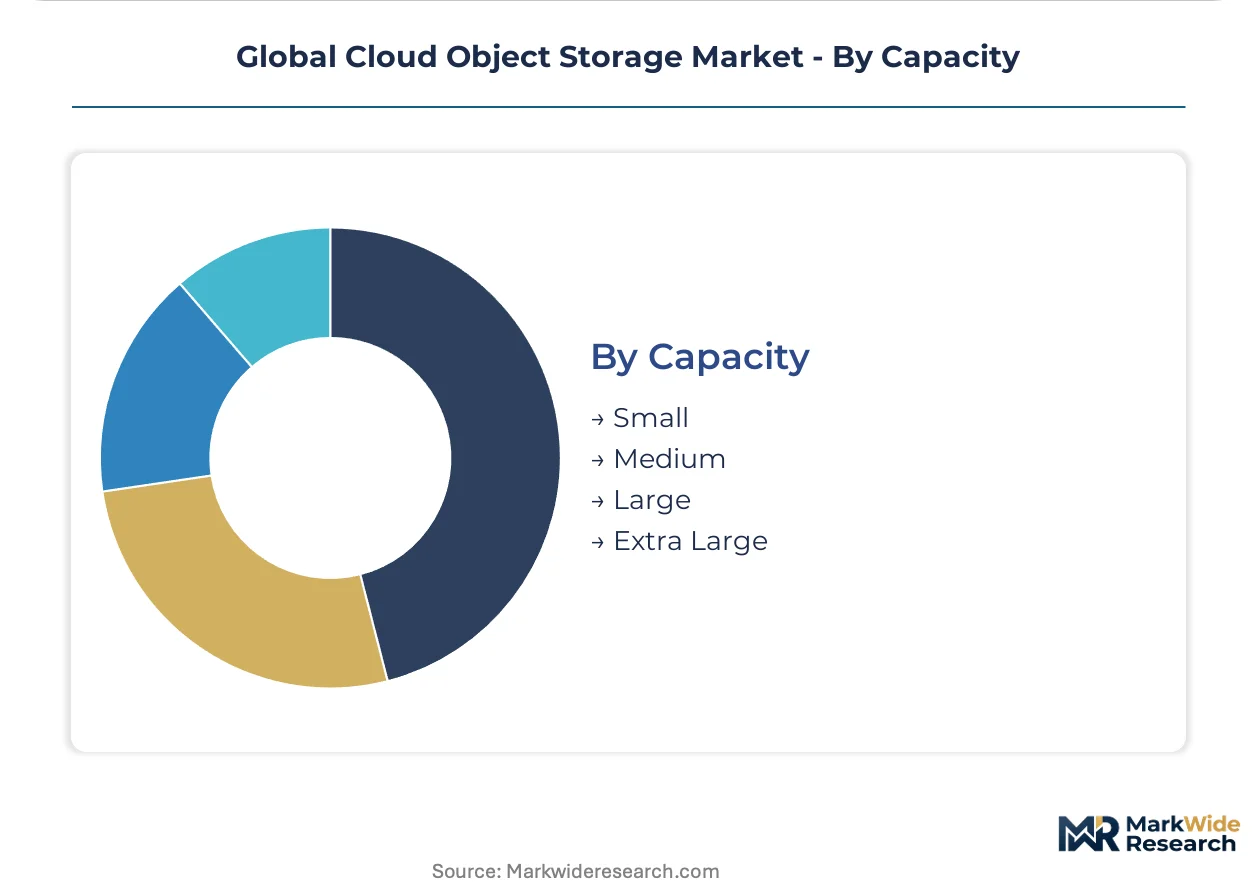
Capacity:
Volume scale determines infrastructure procurement mechanism and vendor negotiation leverage.
- Large:Petabyte-scale deployments with custom lifecycle policies. Scientific research institutions and broadcast archives dominate, though tape retains cost advantages for infrequently accessed datasets.
- Extra Large:Exabyte-scale repositories spanning distributed server clusters. Hyperscale cloud operators and national archives in the United States and Germany anchor demand here.
- Medium:Hundreds of terabytes with intelligent tiering automation. Mid-market enterprises transitioning from NAS file systems represent the core buyer set.
- Small:Sub-terabyte workloads with standard API access. Developer sandboxes and departmental pilots populate this tier.
Deployment value concentrates in Extra Large; Medium capacity gains share fastest among transitioning enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Singapore, and the United States as cloud regions multiply and regulatory mandates reshape procurement patterns. Financial services firms and healthcare providers are driving sovereign data residency architectures across these markets.
United States
Healthcare data gravity and FDA 21 CFR Part 11 compliance are pulling pharmaceutical trial data into certified object storage architectures. HIPAA constraints shape multi-cloud procurement among hospital networks and clinical research organizations. The Boston-Cambridge biotech corridor and Seattle cloud engineering clusters anchor hyperscale deployment decisions.
Germany
Gaia-X compliance frameworks are creating preferred vendor status for EU-data-resident storage operators serving Frankfurt's financial district. The EU AI Act's algorithmic audit-trail mandates expand immutable object storage footprints for model versioning. Bavaria's automotive engineering centers and North Rhine-Westphalia's industrial IoT deployments drive edge-to-core tiering automation.
Singapore
Venture-backed SaaS backup providers and media streaming platforms are negotiating pay-as-you-grow contracts that prioritize cash-flow flexibility. The Monetary Authority of Singapore's digital banking licensing is accelerating fintech object storage procurement. The city-state's status as a Southeast Asia cloud hub concentrates regional data lake investments from Indonesian and Vietnamese digital enterprises.
United Kingdom
GDPR Article 17 right-to-erasure conflicts with blockchain-anchored immutability are forcing architectural splits between mutable and immutable buckets. London's media and entertainment studios handling 8K video pipelines drive computational storage adoption for real-time rendering workflows. The UK's clinical trial regulatory framework maintains parallel storage environments for different data categories across Cambridge and Oxford research parks.
Japan
METI's data free flow with trust initiatives are shaping cross-border object storage architectures for multinational manufacturers. Tokyo's financial services firms are expanding object storage footprints for regulatory data retention under Japan's Banking Act. Osaka's precision manufacturing clusters and Fukuoka's gaming industry drive digital asset management demand for game engine pipelines.
Global Cloud Object Storage Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud operators commanding volume while sovereign-certified providers capture regulated vertical premiums. The vendor base organizes around three strategic archetypes: full-stack hyperscalers with global region density, compliance-focused regional specialists, and infrastructure-agnostic software layer vendors. Competitive moves concentrate on M&A for data sovereignty certifications and strategic partnerships for edge-to-core orchestration capabilities.
Within the hyperscaler tier, Amazon Web Services Inc., Microsoft Corporation, and Google LLC anchor global capacity expansion and pricing benchmarks for archive tiers. These entities exemplify the scale-driven archetype through distributed server cluster investments across Frankfurt, Singapore, and US East Coast availability zones. Their positioning reflects the tension between egress fee structures that create lock-in friction and intelligent tiering automation that reduces customer switching costs.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| Microsoft Corporation |
| Google LLC |
| International Business Machines Corporation |
| Oracle Corporation |
| Dell Technologies Inc. |
| Alibaba Cloud Computing |
| NetApp Inc. |
| Hewlett Packard Enterprise Company |
| Others |
Supply Flow & Price Mechanics
Financial services firms in Frankfurt and Singapore anchor cloud object storage procurement volumes, tying pricing power to sovereign certification tiers rather than raw capacity scale alone. Their compliance-driven buying concentrates negotiating leverage among Gaia-X certified operators and hyperscalers with EU data residency guarantees.
Pricing Analysis
Volume concentrates in metered consumption tiers while margin accrues to intelligent tiering automation and sovereign-certified private deployments. Three-tier pricing structure across hot, cool, and archive levels differentiates retrieval latency commitments, with flash-based archive tiers commanding premiums over magnetic alternatives. Pricing pressure stems from egress fee transparency mandates and multi-cloud portability clauses that erode hyperscaler lock-in. SaaS backup providers and venture-backed streaming platforms exhibit highest price sensitivity; healthcare and pharmaceutical buyers prioritize certification over unit cost.
Supply Chain Analysis
Flash memory supply rests on fabrication capacity concentrated in South Korea, Japan, and Taiwan, with NAND wafer output determining archive tier cost curves. Enterprise solid-state drives, high-density storage servers, and specialized cooling systems constitute critical hardware inputs. Single-source vulnerability in advanced node semiconductor manufacturing creates exposure to geopolitical export controls. Distribution runs through hyperscaler-owned data center footprints and sovereign-certified colocation facilities in Frankfurt, Singapore, and US East Coast availability zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud object storage is consolidating around compliance-certified operators as EU AI Act and GDPR mandates force subscale players from European markets. Egress fee structures and encryption key sovereignty requirements accelerate this winnowing.
For Market Incumbents: To counter multi-cloud portability clauses eroding lock-in revenue, hyperscalers should deepen sovereign certification investments in Frankfurt and Singapore while embedding intelligent tiering automation as a switching cost. Hybrid cloud orchestration capabilities and customer-managed encryption key architectures defend position against regional specialists.
For New Entrants and Emerging Players: EU AI Act audit-trail mandates in Germany open a window for immutable object storage specialists with Gaia-X compliance. Edge-to-core tiering automation for industrial IoT sensor archives in Bavaria and North Rhine-Westphalia represents the most penetrable white space. Go-to-market should target automotive engineering centers with sovereign data residency guarantees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid cloud software layer vendors with healthcare and financial services channel relationships in the United States and Germany. Long-term viability hinges on regulatory certification moats rather than raw infrastructure scale. Watch for EU AI Act enforcement actions as inflection indicator for sovereign cloud demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Certification Investment | Gaia-X compliance in Frankfurt creates preferred vendor status for EU data residency. |
| Intelligent Tiering Automation | Automated lifecycle policies reduce customer switching costs for hyperscalers. |
| Hybrid Cloud Orchestration | On-premises encryption key control satisfies HIPAA and GDPR fragmentation mandates. |
| Computational Storage Integration | Embedded processing in 8K media pipelines eliminates data movement bottlenecks. |
| Edge-to-Core Tiering Deployment | IoT sensor archive automation unlocks new consumption models for manufacturing. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and sovereign cloud certification registries formed the secondary backbone, cross-referenced with primary interviews across cloud infrastructure architects, healthcare compliance officers, financial services procurement leads, and media pipeline engineers. Bottom-up capacity deployment tracking and top-down enterprise IT spend analysis enabled triangulation across public cloud, hybrid, and private deployment models.
Historical trendline analysis of metered consumption growth and committed-use contract migration informed projection frameworks across deployment type, service tier, capacity scale, and end-use vertical. Modeled segmentation incorporated data sovereignty requirements, recovery time objectives, and flash versus tape archive economics. CAGRs derived from capacity expansion announcements, cloud region buildout schedules, and regulatory compliance timeline acceleration.
The model assumes a particular technology adoption path; alternative pathways for computational storage and storage-class memory would alter the outlook for archive tier pricing structures. Forecasts reflect assumptions regarding EU AI Act enforcement timing, flash memory cost curve trajectories, and hyperscaler egress fee policy evolution. Regulatory action on data localization, semiconductor export controls, and sovereign cloud procurement mandates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Denmark Data Center Storage Market