
 Cloud Based Backup Services Market | 2026-2036
Cloud Based Backup Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Backup Services Market Outlook
GDPR data-localization mandates and sector-specific retention rules are expanding the addressable market for compliant cloud backup architectures. Microsoft Corporation leverages its Azure Sovereign Regions to anchor government and healthcare contracts requiring jurisdictional data control. Amazon Web Services sustains leadership through backward integration into custom Nitro security chips that encrypt backup streams at the hardware layer. Veeam Software specializes in hybrid-cloud orchestration, occupying a distinct niche for enterprises running mixed VMware and containerized workloads.
Cloud based backup services constitute distributed data protection systems that replicate, encrypt, and store enterprise information across off-site server infrastructure, typically employing AES-256 encryption and immutable snapshotting to ensure recoverability after ransomware or hardware failure. Their primary commercial purpose is to replace tape-centric disaster recovery with automated, geographically redundant retention that slashes recovery time objectives from days to minutes. Hybrid cloud deployment is attracting the largest capital commitments as organizations retain sensitive primary backups on-premises while archiving cold data to public cloud object storage. Disaster Recovery as a Service represents the fastest-expanding service type because it bundles compute failover with data restoration, commanding premium pricing over basic backup tiers. Large enterprises dominate end-user spending, though government agencies are emerging as a high-growth vertical driven by classified-cloud accreditation programs.
The EU AI Act and GDPR impose strict cross-border data flow restrictions that shape product architecture decisions for vendors serving European clients. In the United States, FedRAMP authorization and SEC cybersecurity disclosure rules are tightening procurement standards for financial and federal buyers. Stakeholders must monitor evolving encryption export controls and quantum-resistant algorithm timelines to avoid stranded infrastructure investments.
Market Dynamics
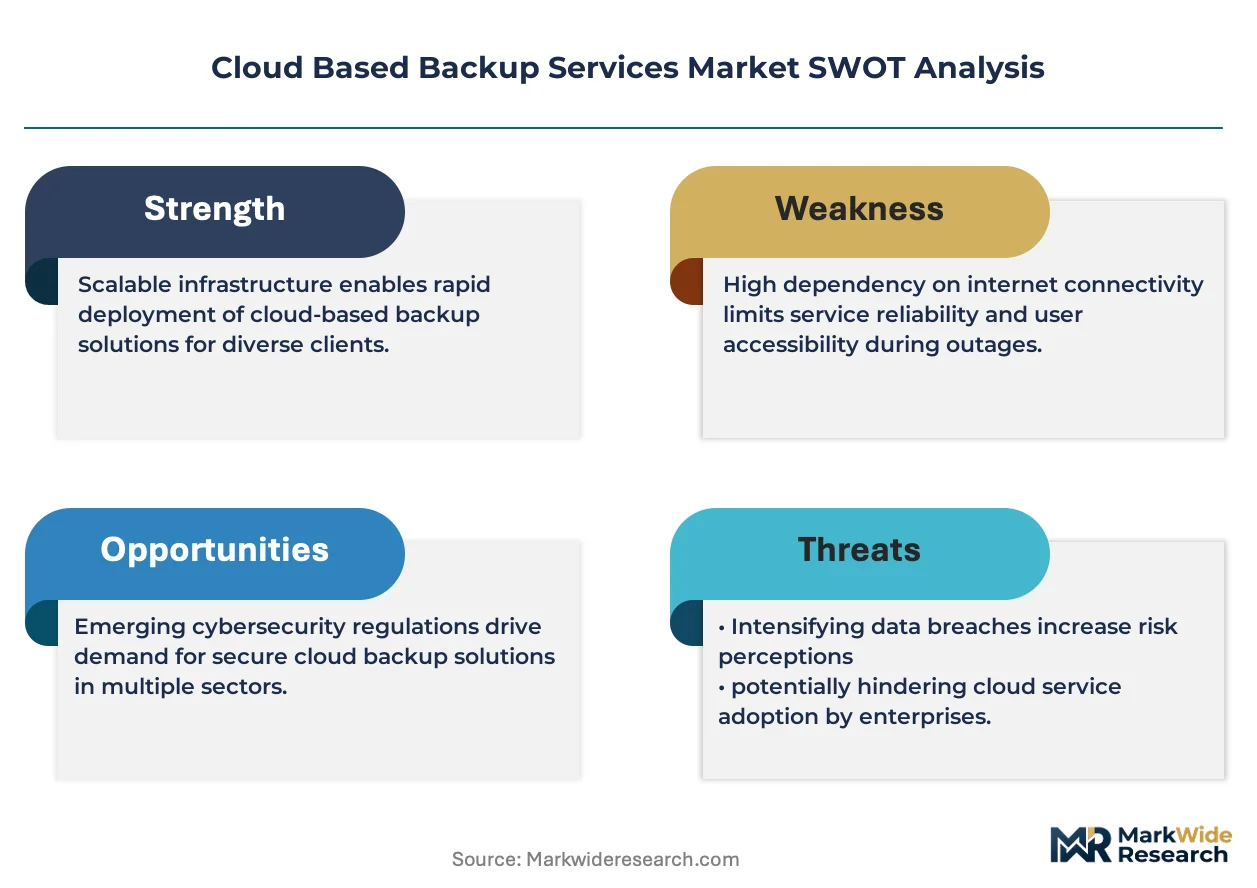
Ransomware frequency is compressing recovery time objectives from days to minutes, forcing enterprises to abandon tape-centric disaster recovery architectures in favor of immutable cloud-native snapshotting with instant compute failover capabilities.
Growth Catalysts
- HIPAA Retention Mandates:Healthcare providers must retain patient records for six years minimum, driving automated tiered archiving to compliant cloud object storage with audit-ready chain-of-custody documentation.
- EU GDPR Data Localization:Cross-border transfer restrictions compel enterprises to deploy sovereign cloud regions, expanding addressable market for jurisdictional backup architectures with EU-stored encryption keys.
- Hyperscale Data Center Clustering:Northern Virginia and Oregon concentration enables sub-10ms latency for synchronous replication, making real-time disaster recovery economically viable for mid-market enterprises.
Market Restraints
- Egress Cost Volatility:Cloud providers charge per-gigabyte retrieval fees that spike during mass restoration events, creating unpredictable total cost of ownership that exceeds on-premises tape economics at scale.
- Encryption Export Controls:US Bureau of Industry and Security restrictions on AES-256 implementations complicate deployment for multinational corporations with distributed engineering teams.
- Substitution by Air-Gapped Storage:Financial institutions with highest-sensitivity data retain physical tape vaults as ransomware-proof alternatives, capping cloud penetration in the premium segment.
Strategic Opportunities
- Container-Native Backup Convergence:Kubernetes persistent volume snapshotting integrated with serverless compute restoration opens whitespace for DevOps-centric platforms serving cloud-native application teams.
- SEC Cybersecurity Disclosure Rules:Material incident reporting requirements create compliance-driven demand for immutable backup verification with third-party attestation services.
- India Data Protection Bill:Pending localization mandates position the country as an underpenetrated geography requiring domestic cloud infrastructure partnerships.
Industry Challenges
- FedRAMP Authorization Timelines:Federal contractors face 12-18 month certification cycles for cloud backup services, delaying revenue recognition and requiring dedicated compliance engineering functions.
- Quantum-Resistant Algorithm Migration:NIST post-quantum cryptography standards force infrastructure re-encryption roadmaps that risk stranded investments if timelines accelerate unexpectedly.
- Legacy Mainframe Integration:Financial services and government agencies running IBM z/OS environments require specialized gateway appliances, fragmenting vendor development resources across disparate protocol stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Backup Services Market |
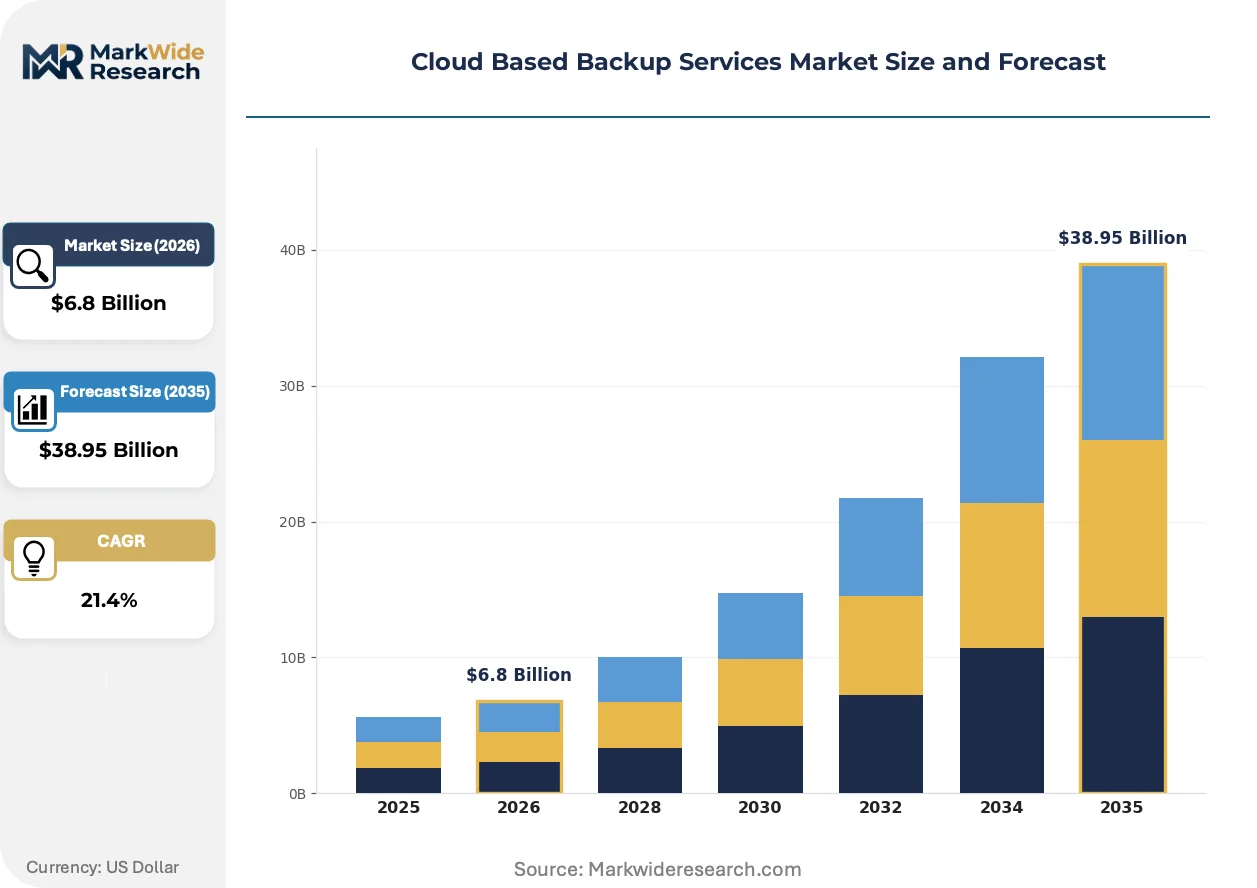
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Backup as a Service, Disaster Recovery as a Service, Data Migration, Data Archiving End User: SMBs, Large Enterprises, Government Agencies, Educational Institutions Technology: Block Storage, Object Storage, Tape Backup, Virtualization |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, Veeam Software, Commvault, Acronis, Druva, Backblaze Inc., Veritas Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Backup Services Market Strategic Shifts
Immutable object storage with write-once-read-many enforcement is displacing mutable disk arrays as the primary defense against ransomware encryption attacks. This architectural pivot demands hardware-rooted trust mechanisms and cryptographic verification chains that complicate procurement while elevating security specifications.
Object-locking with legal-hold capabilities is overtaking traditional backup software agents as the dominant data protection paradigm. Healthcare systems and legal firms with litigation-readiness requirements are adopting S3-compatible object stores with governance policies that prevent administrator override. This shift is compressing market share for legacy backup applications while expanding demand for cloud-native data lakes with embedded compliance controls.
REACH chemical substance restrictions and EU AI Act data governance requirements are reshaping backup retention policies for manufacturing and algorithmic trading environments. Industrial IoT sensor data classified as high-risk under AI Act Article 10 must maintain complete provenance records, forcing backup systems to capture metadata lineage alongside raw payloads. German automotive suppliers and Dutch agritech operators are deploying edge-to-cloud pipelines with embedded regulatory tagging to preempt enforcement actions.
Consumption-based pricing with committed-use discounts is replacing perpetual licensing for enterprise backup procurement. Channel partners and managed service providers are unbundling hardware resale from operational support, shifting margin capture toward ongoing data management services. This transition is most visible among US mid-market manufacturers consolidating vendor relationships under single-source IT outsourcing contracts with backup-as-a-service components.
Cloud Based Backup Services Market Segmentation
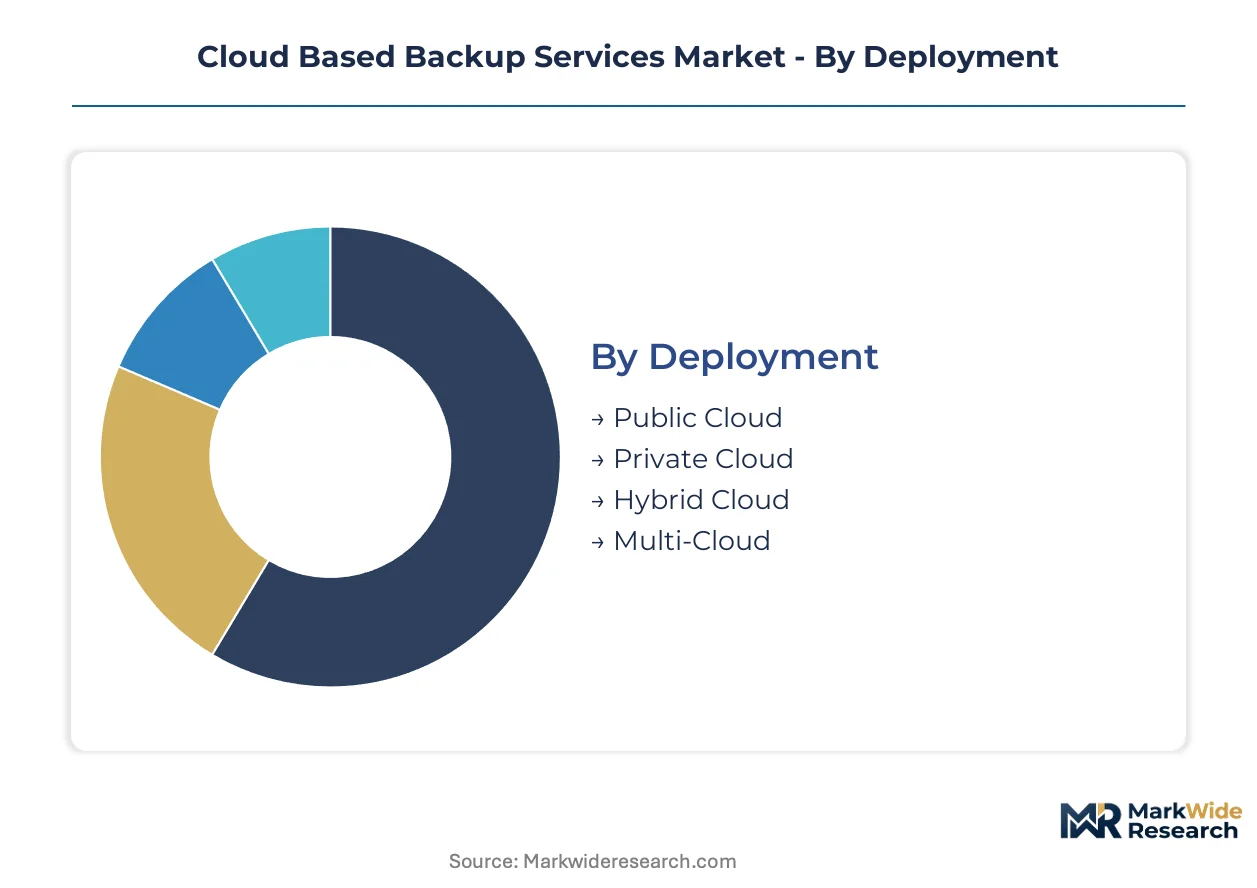
Cloud backup procurement patterns diverge sharply across deployment architectures and compliance burdens. Segmentation reveals which configurations demand FedRAMP authorization, GDPR sovereign regions, or HIPAA business associate agreements.
Deployment:
FedRAMP Moderate authorization applies exclusively to public and hybrid configurations, while private cloud deployments face lighter compliance thresholds.
- Public Cloud:Third-party managed infrastructure with shared tenancy pools. Demand concentrates among US mid-market manufacturers seeking rapid provisioning without capital expenditure, constrained by SEC cybersecurity disclosure rules requiring immutable verification.
- Private Cloud:Single-tenant dedicated infrastructure with isolated compute and storage stacks. Healthcare systems in Germany and France deploy this architecture to satisfy GDPR data localization mandates with EU-stored encryption keys.
- Hybrid Cloud:On-premises primary storage paired with public cloud archival tiers. Financial services firms in New York and London favor this model for hot data sovereignty with cold cost optimization.
- Multi-Cloud:Workload distribution across two or more hyperscale providers. Australian mining operators and Japanese automotive suppliers adopt this to avoid vendor lock-in and meet diverse national sovereignty requirements.
Hybrid Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest.
Service Type:
Pricing tiers separate premium bundled offerings from commodity backup tiers based on compute failover inclusion.
- Backup as a Service:Automated data replication with point-in-time recovery capabilities. SMBs in India and Brazil drive volume adoption through consumption-based pricing without upfront licensing.
- Disaster Recovery as a Service:Integrated compute failover with sub-hour recovery time objectives. US federal contractors and UK financial institutions pay premium rates for FedRAMP and FCA-aligned attestation services.
- Data Migration:One-time or recurring transfer services between storage platforms. Cloud-native enterprises in Singapore and South Korea leverage these tools during Kubernetes persistent volume migrations.
- Data Archiving:Long-term retention with legal-hold and e-discovery capabilities. German legal firms and Dutch healthcare providers require this for litigation readiness under EU AI Act provenance rules.
Backup as a Service commands the largest revenue pool, though Disaster Recovery as a Service expands most steeply.
End User:
Procurement sophistication scales directly with internal compliance engineering headcount.
- SMBs:Organizations under 500 employees with limited IT specialization. Indian manufacturing clusters and US regional healthcare networks adopt managed service provider bundles to outsource backup operations entirely.
- Large Enterprises:Fortune 1000 and equivalent global corporations with dedicated security teams. These buyers in Northern Virginia and Frankfurt negotiate committed-use discounts across petabyte-scale deployments.
- Government Agencies:Federal, state, and municipal entities with classified data requirements. US agencies face 12-18 month FedRAMP timelines, while UK public sector bodies navigate NCSC Cloud Security Principles.
- Educational Institutions:Universities and K-12 districts with research data and student records. Canadian and Australian institutions lead adoption driven by national research infrastructure grants.
Large Enterprises dominate current spending, with Government Agencies gaining share fastest.
Technology:
Storage protocol selection determines ransomware resilience and retrieval latency profiles.
- Block Storage:Fixed-size raw storage volumes mounted to compute instances. Database administrators in Tokyo and Sydney prefer this for transactional workloads requiring consistent low-latency access.
- Object Storage:Flat namespace architecture with metadata-rich addressing. S3-compatible implementations with write-once-read-many enforcement displace mutable arrays across healthcare and legal verticals.
- Tape Backup:Linear magnetic storage with air-gapped physical isolation. Swiss banking vaults and US defense contractors retain this for highest-sensitivity data despite cloud migration pressures.
- Virtualization:Hypervisor-agnostic snapshotting for VMware and container environments. DevOps teams in Seattle and Bangalore integrate this with Kubernetes persistent volume orchestration.
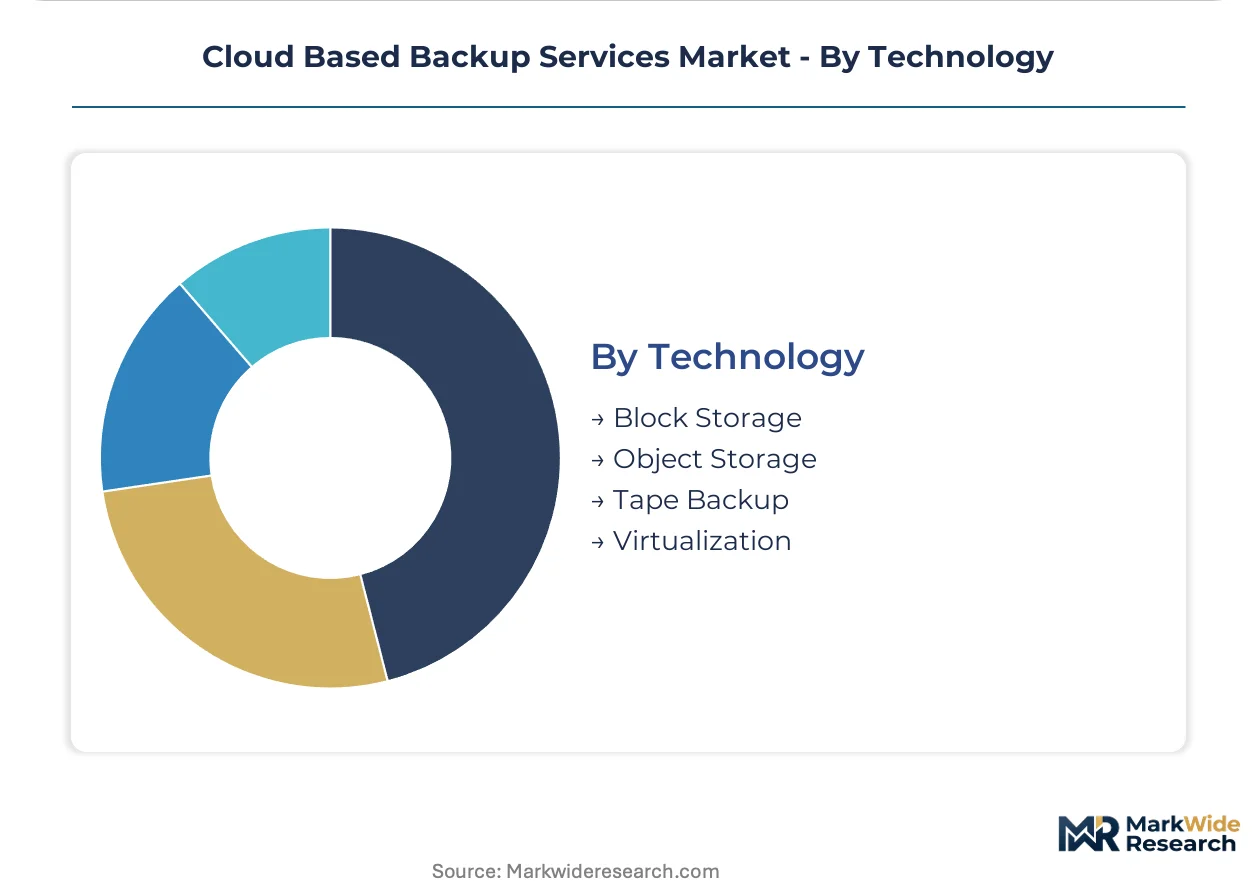
Object Storage leads deployment volume, with Virtualization expanding most quickly among cloud-native workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud backup services trace their commercial origins to Northern Virginia's data center corridor, where federal cloud-first policies and hyperscale infrastructure investments created the template for geographically redundant replication architectures now replicated worldwide.
United States
FedRAMP authorization programs and SEC cybersecurity disclosure rules drive procurement sophistication among federal contractors and financial institutions. The Bureau of Industry and Security administers encryption export controls affecting multinational deployment architectures. Northern Virginia and Oregon host the densest hyperscale clusters, enabling sub-10ms synchronous replication for enterprise disaster recovery.
Germany
GDPR data localization mandates and the EU AI Act's provenance requirements compel healthcare systems and automotive suppliers to deploy sovereign cloud regions. The Federal Financial Supervisory Authority enforces retention standards for trading data. Frankfurt's financial district and Munich's industrial corridor anchor compliance-focused backup infrastructure investments.
United Kingdom
NCSC Cloud Security Principles and FCA-aligned attestation requirements shape procurement for financial services and public sector bodies. Post-Brexit data adequacy negotiations influence cross-border replication strategies. London's fintech concentration and Edinburgh's government data centers represent high-compliance deployment zones.
India
Pending data localization provisions in the Digital Personal Data Protection Bill position domestic cloud infrastructure partnerships for expansion. The Reserve Bank of India mandates retention standards for financial transaction records. Bangalore's technology corridor and Mumbai's financial district drive hybrid cloud adoption among IT services exporters.
Japan
METI's cybersecurity framework and sector-specific critical infrastructure protections elevate backup requirements for manufacturing and energy operators. Amendments to the Act on Protection of Personal Information restrict cross-border data flows. Tokyo's enterprise concentration and Osaka's industrial belt sustain demand for immutable object storage with localized encryption key management.
Cloud Based Backup Services Market Competitive Environment
Capital-heavy hyperscale operators compete with asset-light software specialists across divergent economic models. The market structure consolidates around three tiers: infrastructure owners with captive data center assets, independent software vendors with multi-platform orchestration capabilities, and managed service providers wrapping operational support around third-party platforms. Strategic differentiation centers on compliance certification velocity and hybrid architecture flexibility. M&A activity targets container-native backup capabilities, while strategic partnerships address sovereign cloud localization requirements.
Within the hyperscale infrastructure tier, Microsoft Corporation and Amazon Web Services anchor jurisdictional control offerings through dedicated government cloud regions. Veeam Software occupies a distinct position among independent specialists, exemplifying the hybrid-cloud orchestration archetype for enterprises running mixed virtualization environments. These three entities represent the dominant competitive anchors: infrastructure owners leveraging backward integration into custom security hardware, and software specialists capturing value through platform-agnostic deployment flexibility.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Veeam Software |
| Commvault |
| Acronis |
| Druva |
| Backblaze Inc. |
| Veritas Technologies |
| Others |
Value Chain & Pricing Dynamics
Federal contractors and financial institutions with FedRAMP authorization requirements anchor pricing power for compliant cloud backup tiers, compressing margins for vendors unable to secure government cloud accreditation. Consumption-based SaaS models with committed-use discounts dominate procurement, while egress cost volatility during mass restoration events creates unpredictable total cost of ownership that exceeds on-premises tape economics at petabyte scale.
Pricing Analysis
Subscription-based consumption models with tiered service levels dominate enterprise procurement, separating Disaster Recovery as a Service bundles from basic backup tiers through compute failover inclusion. Price differentiation hinges on FedRAMP authorization status and immutable verification capabilities with third-party attestation. Pricing pressure stems from hyperscale providers absorbing infrastructure costs to capture market share, squeezing independent software vendors. SMBs in emerging markets exhibit highest price sensitivity, while US federal contractors tolerate premium rates for jurisdictional control.
Supply Chain Analysis
Hyperscale data center infrastructure rests on concentrated server and storage hardware manufacturing in Taiwan, South Korea, and China, with custom security chip fabrication anchored in US and Israeli facilities. Nitro encryption processors, high-density flash arrays, and sovereign region networking equipment constitute critical input dependencies. Single-source vulnerability in advanced semiconductor lithography equipment creates supply chain risk. Distribution runs through direct enterprise sales organizations and managed service provider channels with unbundled hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud backup services function as a geographic-arbitrage play where vendors can exploit cost differentials between US hyperscale infrastructure and emerging sovereign cloud buildouts in India and Southeast Asia, while regulatory fragmentation between GDPR localization mandates and FedRAMP authorization timelines creates pricing premiums for compliant architectures.
For Market Incumbents: Anchor government cloud contracts through accelerated FedRAMP Moderate and High authorization timelines, defending against emerging sovereign cloud specialists by deepening backward integration into custom encryption hardware. Prioritize hybrid-cloud orchestration capabilities to capture enterprises running mixed VMware and containerized workloads, as substitution by air-gapped tape storage caps penetration in highest-sensitivity financial segments. For New Entrants and Emerging Players: Begin with container-native backup convergence targeting DevOps-centric platforms in Bangalore and Singapore, where Kubernetes persistent volume snapshotting remains underpenetrated relative to legacy agent-based approaches. White-space exists in SEC cybersecurity disclosure compliance services with immutable verification attestation, particularly among mid-market manufacturers consolidating under single-source IT outsourcing contracts. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking container-native backup capabilities and sovereign cloud localization partnerships. Target asset-light software specialists with multi-platform orchestration and FedRAMP authorization velocity rather than infrastructure-heavy data center operators. Watch NIST post-quantum cryptography standard timelines as inflection indicator for infrastructure re-encryption investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Captures federal contractor revenue streams with 12-18 month certification cycles under Bureau of Industry and Security oversight. |
| Sovereign Cloud Partnership | Addresses EU GDPR and pending India Data Protection Bill localization mandates with EU-stored encryption keys. |
| Container-Native Backup Acquisition | Integrates Kubernetes persistent volume orchestration for cloud-native application teams in Seattle and Bangalore. |
| Immutable Verification Service Launch | Satisfies SEC cybersecurity disclosure rules with third-party attestation for litigation-ready healthcare and legal verticals. |
| Quantum-Resistant Cryptography Roadmap | Preempts stranded infrastructure investments as NIST post-quantum standards force re-encryption timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud infrastructure procurement officers, FedRAMP compliance engineers, healthcare IT security directors, and managed service provider channel heads with secondary validation against hyperscaler capex disclosures, SEC cybersecurity filings, and EU regulatory guidance documents. Bottom-up deployment volume estimates and top-down market sizing triangulated across public cloud, private cloud, hybrid cloud, and multi-cloud configurations.
Segment-weighting applied deployment architecture, service type, end-user scale, and storage technology dimensions across the projection horizon, with growth rates derived from elasticity modeling of compliance-driven procurement and ransomware frequency impacts on recovery time objective compression. Forecast inputs incorporated FedRAMP authorization pipeline data, GDPR sovereign region buildout timelines, and hyperscale data center clustering patterns in Northern Virginia and Oregon.
Caveats apply where quantum-resistant algorithm migration timelines or encryption export control revisions could materially shift the outlook for infrastructure investment cycles. Egress cost volatility and air-gapped tape substitution in premium financial segments represent additional revision triggers. A small set of named triggers including NIST post-quantum standards, India data localization enforcement, and FedRAMP authorization velocity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
VM Service Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Cloud Management Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Virtual Private Cloud (VPC) Market