
 Storage and Backup Software Market | 2026-2036
Storage and Backup Software Market Size, Share, and Industry Trends Forecast 2026-2036
Storage and Backup Software Market Analysis
The capital-intensity divergence between legacy hardware-integrated vendors and cloud-native software specialists is reorganizing competitive hierarchies in data protection. Dell Technologies leverages its server and storage hardware ecosystem to anchor bundled backup sales in enterprise accounts. Veeam competes through pure-software subscription models that decouple backup licensing from physical infrastructure commitments.
Storage and backup software encompasses applications that create redundant copies of digital data across primary, secondary, and tertiary storage tiers, typically employing compression algorithms to reduce payload size and deduplication to eliminate redundant blocks before transmission. These systems serve the commercial purpose of ensuring business continuity during hardware failures, cyber incidents, or natural disasters. Cloud-based deployment now leads growth velocity as organizations retire tape libraries and on-premises vaults, while data recovery solutions command premium pricing due to stringent recovery time objective requirements in financial services. Disaster recovery as a segment is maturing into integrated cyber-resilience platforms that combine backup with forensic analytics and automated failover orchestration.
The EU GDPR and the EU AI Act impose data localization and breach-notification mandates that directly expand backup software procurement across regulated industries. The US SEC cybersecurity disclosure rules and HIPAA data integrity standards similarly compel healthcare and publicly traded firms to maintain immutable, auditable backup repositories. Stakeholders must monitor how sovereign cloud requirements in France, Germany, and India fragment vendor architectures and inflate compliance engineering costs.
Market Dynamics
Immutable backup architectures are compressing recovery time objectives across financial services and healthcare, forcing vendors to engineer air-gapped repositories that satisfy SEC cybersecurity disclosure rules and HIPAA data integrity mandates simultaneously.
Growth Catalysts
- Ransomware Frequency:Escalating encryption attacks against municipal governments and hospital networks are mandating offline backup vaults with forensic logging capabilities.
- EU AI Act Data Residency:Training dataset localization requirements are compelling AI developers in Germany and France to maintain sovereign backup infrastructure with audit trails.
- Tape Retirement Cycles:Magnetic media end-of-life programs at Fortune 500 manufacturers are accelerating cloud-native backup migration timelines.
Market Restraints
- Hyperscaler Concentration:AWS, Azure, and Google Cloud control over seventy percent of object storage backends, creating single-point-of-failure exposure for multi-tenant backup services.
- Encryption Key Escrow Costs:Hardware security module procurement and FIPS 140-2 certification cycles add eighteen to thirty-six months to product launch timelines.
- Staffing Bottlenecks:Certified disaster recovery architects command premium compensation in London and Frankfurt, inflating implementation service margins.
Strategic Opportunities
- India Data Localization:The Digital Personal Data Protection Act is forcing multinationals to establish in-country backup regions, opening greenfield infrastructure contracts.
- Container-Native Protection:Kubernetes persistent volume snapshot orchestration remains underserved among mid-market SaaS providers operating microservices architectures.
- Green Data Center Incentives:The EU Green Deal taxonomy is steering backup procurement toward liquid-cooled, renewable-powered colocation facilities in the Netherlands and Denmark.
Industry Challenges
- Cross-Platform Integration:Heterogeneous environments mixing VMware, Hyper-V, and Nutanix AHV require vendor-agnostic backup agents that complicate quality assurance matrices.
- Immutable Credential Management:Compromised administrative accounts can delete even air-gapped backups, demanding zero-trust architecture redesigns that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage and Backup Software Market |
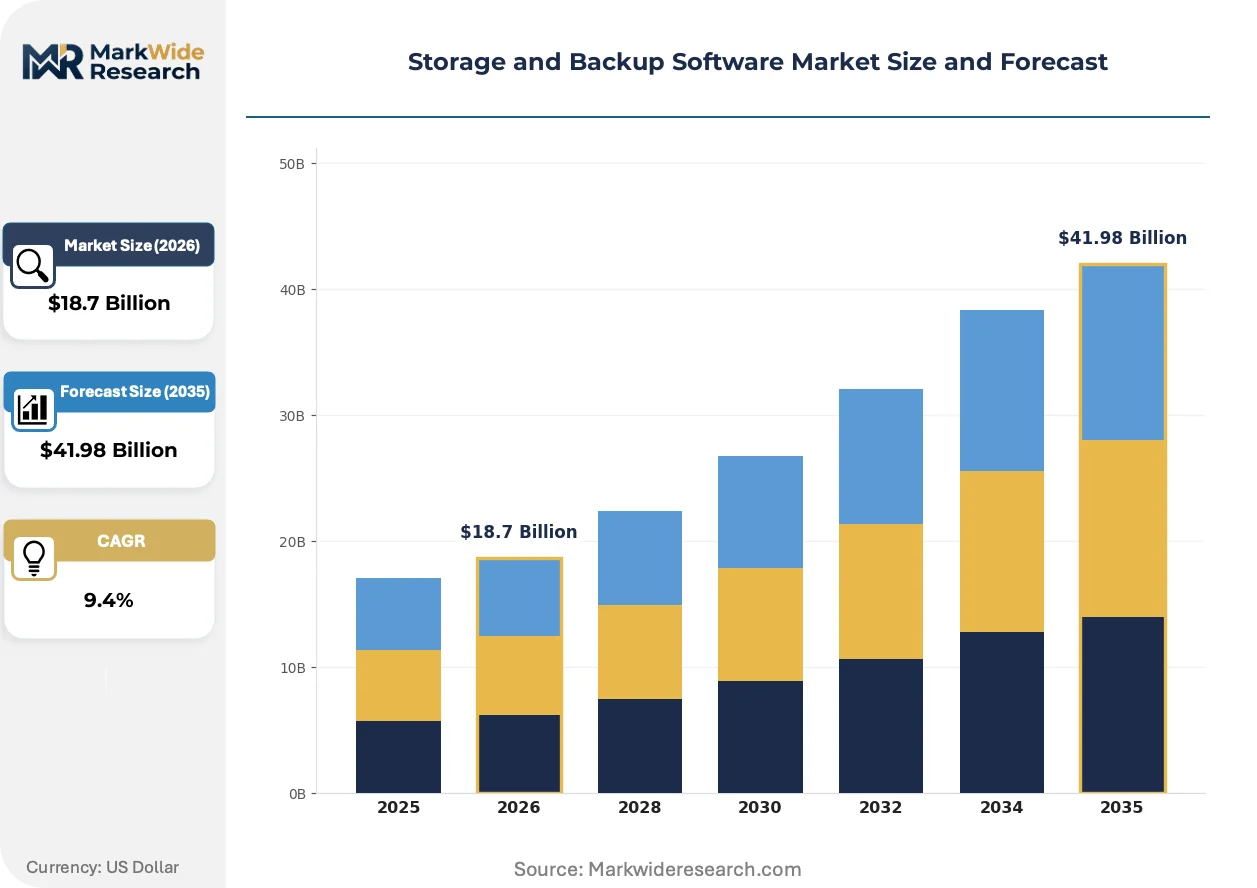
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Solution: Data Recovery, Disaster Recovery, File Backup, Archiving Technology: Compression, Deduplication, Encryption, Replication |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM, Commvault, Veeam, Cohesity, Rubrik, Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage and Backup Software Market Emerging Trajectories
Artificial intelligence is infiltrating backup operations through predictive failure detection and automated tiering algorithms that anticipate ransomware patterns before encryption completes.
Object-lock immutability protocols are displacing traditional grandfather-father-son tape rotation schemes in regulated industries. Healthcare providers in the United States are deploying S3-compatible repositories with WORM attributes to satisfy HIPAA audit requirements. This transition is compressing vendor margins as perpetual license models yield to consumption-based pricing tied to storage growth rates.
The EU AI Act's training data provenance mandates are reshaping backup retention policies for machine learning pipelines. Organizations must now reconstruct model development histories during regulatory examinations, extending retention periods from seven to fifteen years. Pharmaceutical firms operating in France and Germany are provisioning dedicated ML metadata archives to satisfy ANSM and BfArM inspection protocols.
Subscription-based backup licensing is eroding perpetual entitlement sales in mid-market accounts. Value-added resellers in the United Kingdom are bundling managed recovery services with software seats, capturing recurring revenue streams that hardware-centric distributors cannot match. This reconfiguration is visible most acutely among professional services firms in London and Manchester replacing three-year capital leases with monthly operational expenditures.
Storage and Backup Software Market Segmentation
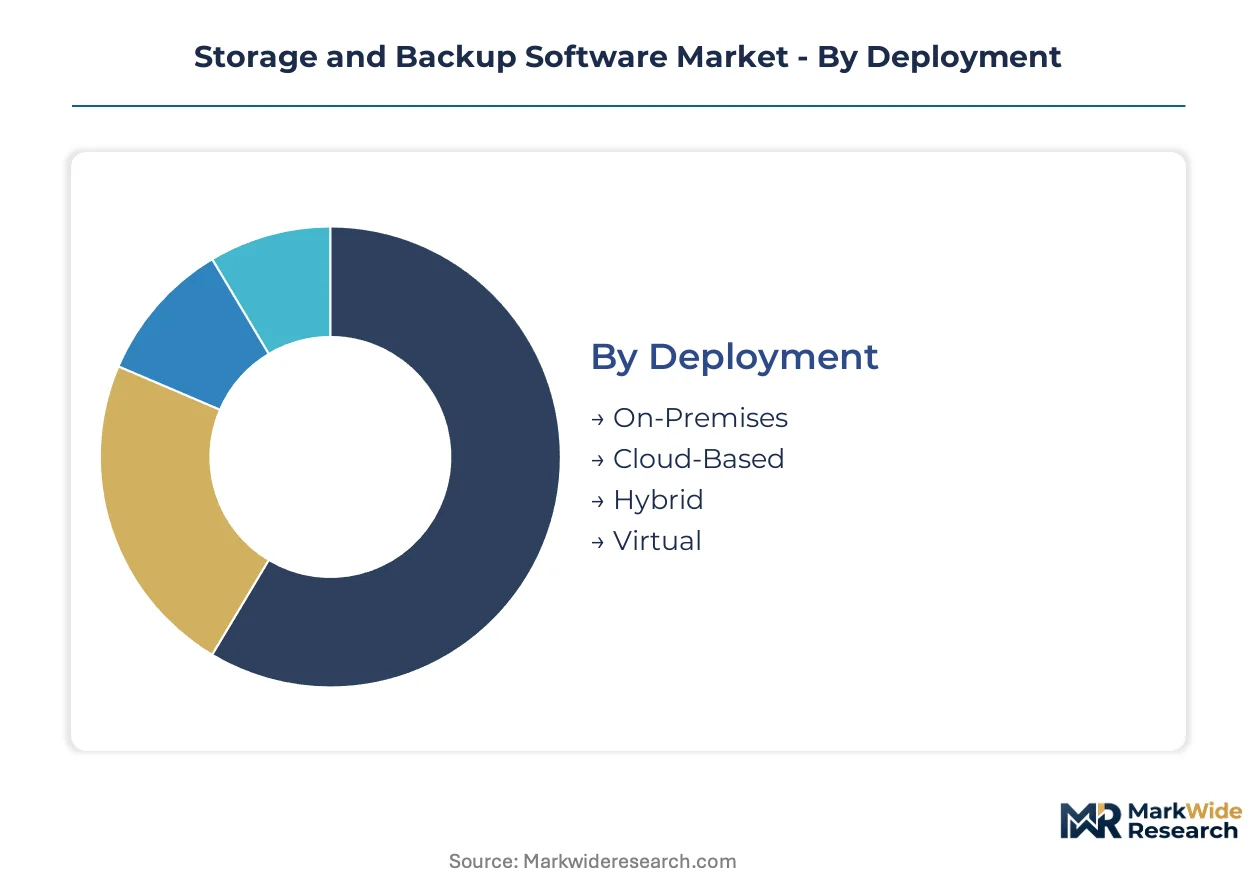
Backup software procurement patterns diverge sharply across deployment models and organizational scale, with regulatory mandates in Germany and India reshaping infrastructure requirements. Technology choices in deduplication and encryption now determine vendor selection more than brand recognition.
Deployment:
Domestic data sovereignty requirements in France and Germany favor on-premises and hybrid architectures, while cloud-native adoption concentrates among UK financial services firms with established AWS and Azure contracts.
- On-Premises:Hardware-integrated backup appliances with tape library connectivity persist in German automotive manufacturing and French pharmaceutical operations subject to ANSM inspection protocols. BfArM mandates for immutable audit trails sustain demand despite cloud migration pressure.
- Cloud-Based:Object storage backends with S3-compatible APIs dominate new procurement in London fintech clusters and Amsterdam SaaS providers. Consumption-based pricing aligns with EU Green Deal sustainability reporting requirements for energy-efficient infrastructure.
- Hybrid:Tiered retention policies spanning local flash and cloud archive tiers address GDPR Article 32 security obligations across Dutch healthcare networks.
- Virtual:Agentless backup for VMware and Hyper-V environments serves mid-market manufacturing in Stuttgart and Munich with limited IT staffing.
On-premises deployments command the established base. The steepest expansion runs through cloud-based configurations.
End User:
Cost tier stratification separates enterprise procurement with dedicated disaster recovery architects from SME reliance on managed service providers.
- SMEs:Subscription-based backup-as-a-service bundles dominate procurement among Manchester professional services firms and Birmingham logistics operators, with monthly operational expenditure replacing three-year capital leases.
- Large Enterprises:Immutable backup architectures with air-gapped vaults satisfy SEC cybersecurity disclosure rules for publicly traded firms and HIPAA data integrity mandates for US healthcare systems. Recovery time objective requirements below four hours command premium pricing.
- Government Agencies:Municipal governments across Texas and California mandate offline backup vaults with forensic logging following ransomware encryption attacks against hospital networks and school districts.
- Educational Institutions:Research universities in Massachusetts and California provision dedicated ML metadata archives to satisfy emerging training data provenance requirements under the EU AI Act.
Large enterprises capture the highest per-seat revenue. SMEs are expanding most quickly as managed service penetration deepens.
Solution:
Application maturity separates commoditized file backup from integrated cyber-resilience platforms combining forensic analytics with automated failover.
- Data Recovery:Granular restore capabilities for databases and virtual machines command premium pricing in Frankfurt banking clusters where recovery point objectives must compress below fifteen minutes.
- Disaster Recovery:Automated orchestration platforms with runbook automation serve London insurance underwriters and Edinburgh asset managers facing PRA operational resilience deadlines.
- File Backup:Endpoint protection for distributed workforces concentrates demand among professional services firms in Madrid and Milan with hybrid office requirements.
- Archiving:WORM-compliant repositories with fifteen-year retention periods address EU AI Act training dataset provenance mandates for pharmaceutical ML pipelines in Basel and Paris.
File backup retains the largest installed base. Disaster recovery solutions are climbing the fastest as integrated cyber-resilience platforms displace point tools.
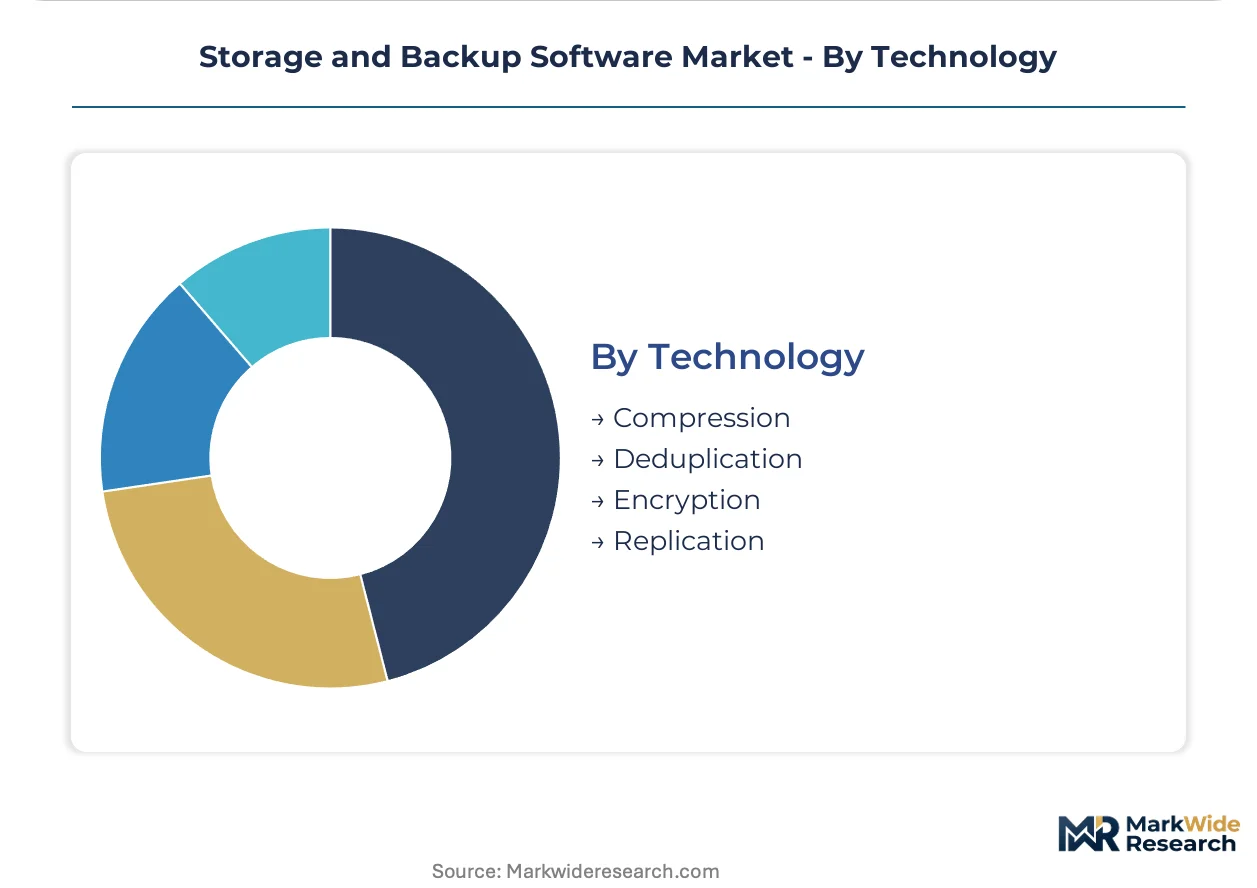
Technology:
Supply concentration in encryption hardware security modules extends product launch timelines and fragments vendor certification roadmaps.
- Compression:Algorithm optimization for unstructured data streams reduces payload size in media and entertainment workflows across Los Angeles and Vancouver post-production facilities.
- Deduplication:Source-side block elimination minimizes bandwidth consumption for remote office backup across Australian mining operations and Indonesian plantation networks with satellite connectivity constraints.
- Encryption:FIPS 140-2 certification requirements and hardware security module procurement add eighteen to thirty-six months to product launch timelines, favoring established vendors with existing certification portfolios.
- Replication:Synchronous mirroring between availability zones serves Tokyo financial exchanges and Singapore trading venues with sub-second failover requirements.
Compression and deduplication anchor the mature technology base. Encryption capabilities are gaining share fastest as immutable credential management and zero-trust architectures reshape procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate the lowest price elasticity, accepting premium licensing for sovereign compliance, while mid-market operators in India and the United Kingdom drive hard bargains on per-terabyte rates.
United States
SEC cybersecurity disclosure rules and HIPAA data integrity mandates compel Fortune 500 firms and healthcare systems to maintain immutable, auditable backup repositories. Municipal governments across Texas and California mandate offline backup vaults with forensic logging following ransomware attacks against hospital networks. The Boston-Cambridge research corridor provisions dedicated ML metadata archives to satisfy emerging training data provenance requirements.
Germany
BfArM mandates for immutable audit trails sustain demand for hardware-integrated backup appliances in automotive manufacturing and pharmaceutical operations. The EU AI Act's training dataset localization requirements compel AI developers to maintain sovereign backup infrastructure with fifteen-year retention periods. Stuttgart and Munich manufacturing clusters favor agentless virtual backup for VMware environments with limited IT staffing.
United Kingdom
PRA operational resilience deadlines drive automated disaster recovery orchestration among London insurance underwriters and Edinburgh asset managers. Value-added resellers bundle managed recovery services with subscription software seats, displacing three-year capital leases with monthly operational expenditures. Manchester professional services firms and Birmingham logistics operators concentrate demand for backup-as-a-service bundles.
India
The Digital Personal Data Protection Act forces multinationals to establish in-country backup regions, opening greenfield infrastructure contracts with consumption-based pricing. Mumbai financial services firms and Bengaluru SaaS providers negotiate aggressively on per-terabyte rates while demanding FIPS 140-2 certified encryption. Delhi-NCR enterprise accounts balance cost pressure against data sovereignty requirements.
France
ANSM inspection protocols sustain demand for WORM-compliant repositories with tape library connectivity in pharmaceutical operations. The EU AI Act and CNIL guidance on training data provenance reshape backup retention policies for machine learning pipelines. Paris and Lyon pharmaceutical firms provision dedicated ML metadata archives to satisfy regulatory examination requirements.
Storage and Backup Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in storage and backup software. Dell Technologies leverages server and storage hardware ecosystems to anchor bundled backup sales, while pure-software vendors compete through subscription models that decouple licensing from physical infrastructure. Strategic archetypes include hardware-integrated platform vendors, cloud-native software specialists, and cyber-resilience platform builders. Competitive moves concentrate on portfolio diversification into immutable architectures and geographic expansion through sovereign cloud partnerships.
Within the integrated platform tier, Dell Technologies and Hewlett Packard Enterprise exemplify hardware-anchored strategies, while Veeam occupies a position representing pure-software subscription approaches. Cohesity and Rubrik anchor the cloud-native specialist segment, with Veritas and Commvault sitting within the transition zone between legacy tape-centric portfolios and modern object-storage architectures.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM |
| Commvault |
| Veeam |
| Cohesity |
| Rubrik |
| Veritas |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-thirty-six-month hardware security module procurement cycles compress vendor pricing power while amplifying cost pass-through to enterprise buyers. This lead-time band reflects concentrated encryption component sourcing and FIPS 140-2 certification bottlenecks that tether pricing flexibility to semiconductor foundry scheduling and compliance engineering capacity.
Pricing Analysis
Managed recovery service bundles now drive lifetime value as value-added resellers in the United Kingdom displace perpetual licenses with monthly operational expenditures. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped immutable architectures with sub-four-hour recovery time objectives from consumption-based cloud tiers and basic file backup subscriptions. Cost compression in mid-market SaaS tiers intensifies because hyperscaler object storage concentration limits vendor differentiation. SMEs negotiating in India and the United Kingdom exhibit highest price sensitivity, while German automotive manufacturers accept premium licensing for BfArM-compliant audit trails.
Supply Chain Analysis
Strategic stockpile preferences dominate encryption hardware procurement as vendors buffer against eighteen-month FIPS 140-2 certification delays. Hardware security module fabrication concentrates in the United States, Taiwan, and Germany, drawing from specialized semiconductor foundries and cryptographic component specialists. Supply chain risk centers on single-source vulnerability for certified encryption engines. Distribution runs through direct enterprise sales forces for large accounts and value-added reseller networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified disaster recovery architects command premium compensation in London and Frankfurt, creating a structural talent gap that constrains implementation velocity and inflates service margins.
For Market Incumbents: Secure immutable credential management capabilities through zero-trust architecture investments that close the compromised-administrator deletion vulnerability. Defend against cloud-native specialists by anchoring bundled hardware-software sales in German automotive and French pharmaceutical accounts where BfArM and ANSM mandates sustain appliance demand. Channel control through certified implementation partnerships protects service margin capture. For New Entrants and Emerging Players: Anchor in container-native persistent volume protection for mid-market SaaS providers operating Kubernetes microservices architectures, a segment underserved by legacy virtualization-centric vendors. Target India greenfield infrastructure contracts created by Digital Personal Data Protection Act localization mandates. Lead with consumption-based pricing and sovereign cloud partnerships to bypass incumbent certification portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy tape-centric backup portfolios stranded between declining hardware attachment and incomplete cloud-native transitions. Long-term viability favors vendors with immutable architecture roadmaps and established FIPS 140-2 certification pipelines. Watch hyperscaler backup service pricing moves as the inflection signal for independent software vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Architecture Roadmap | Air-gapped repositories satisfy SEC cybersecurity disclosure rules and HIPAA mandates simultaneously. |
| Sovereign Cloud Partnership | EU AI Act data residency requirements in France and Germany demand in-country backup regions. |
| Container-Native Protection Launch | Kubernetes persistent volume snapshots address underserved mid-market SaaS microservices deployments. |
| Managed Recovery Service Bundle | Monthly operational expenditures displace three-year capital leases among UK professional services firms. |
| Certification Portfolio Expansion | FIPS 140-2 and GDPR Article 32 compliance accelerates procurement in regulated financial and healthcare verticals. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners in financial services, healthcare, and manufacturing verticals. Secondary validation drew from SEC cybersecurity disclosure filings, hyperscaler capex disclosures, EMA and FDA regulatory guidance documents, and EU AI Act implementation protocols. Bottom-up deployment model sizing and top-down market aggregation were triangulated against vendor revenue disclosures and channel partner volume estimates.
Across the analysis window, forecasts model deployment mode, organization scale, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific inputs include ransomware incident frequency curves, tape retirement cycle schedules, and sovereign cloud infrastructure build-out timelines.
Material uncertainties — regulatory enforcement intensity, hyperscaler pricing aggression, encryption hardware supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about compliance deadline adherence and migration velocity from legacy tape architectures. Revision becomes warranted when sovereign data localization mandate expansion crosses thresholds that fragment vendor architectures beyond current provisioning capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Belgium Data Center Storage Market