
 Global Server Storage Area Network Market | 2026-2036
Global Server Storage Area Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Server Storage Area Network Market Foresight
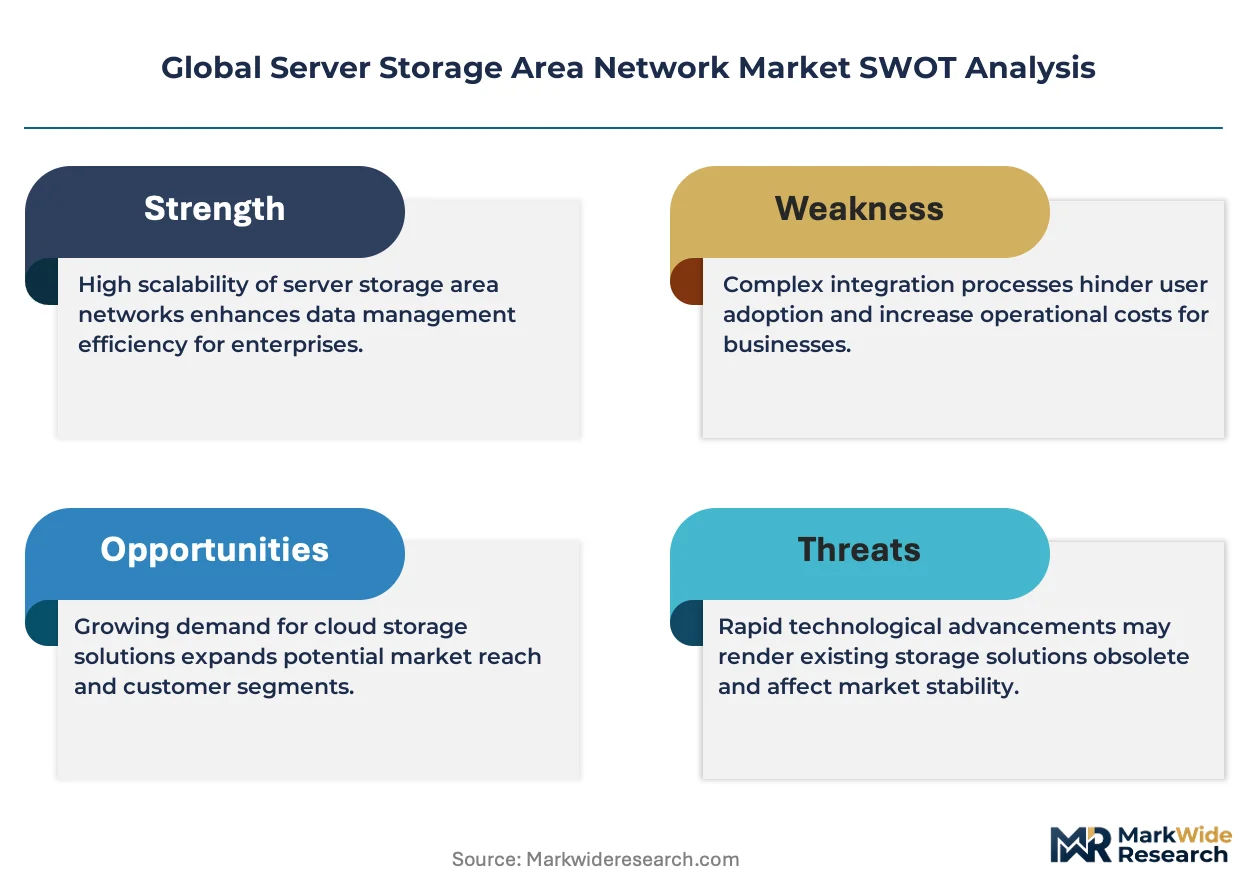
NVMe over Fabrics is rebalancing the cost-performance equation for high-throughput storage fabrics, displacing traditional SAS-based backplanes in performance-sensitive deployments. Dell Technologies leverages its end-to-end infrastructure stack to dominate integrated SAN deployments across enterprise data centers. Hewlett Packard Enterprise anchors its position through in-house development of intelligent storage fabrics with embedded AI-driven tiering. Pure Storage differentiates via all-flash array architectures that eliminate hybrid media complexity for cloud-native workloads.
A server storage area network constitutes a dedicated high-speed network that interconnects shared storage devices to multiple servers, operating through Fibre Channel, iSCSI, or InfiniBand protocols with latency thresholds typically below one millisecond for mission-critical transactions. Fibre Channel SAN maintains structural leadership in financial services and telecommunications due to its deterministic performance and mature ecosystem of host bus adapters and switch fabrics. iSCSI SAN captures growth in mid-market virtualization deployments where IP network convergence reduces dedicated infrastructure overhead. Asynchronous Replication technology expands fastest among enterprise buyers seeking geographically distributed resilience without synchronous bandwidth costs.
FCC equipment authorization rules shape electromagnetic compatibility standards for SAN switching hardware sold into US federal contracts, while REACH and RoHS compliance in Europe restrict hazardous substance use in printed circuit boards and connector assemblies. China's GB standards and MIIT cybersecurity reviews create market access conditions for foreign SAN vendors seeking public sector procurement eligibility. Buyers must monitor how divergent data localization regimes across Washington, Brussels, and Beijing fragment storage architecture standardization and force region-specific product certifications.
Market Dynamics
NVMe over Fabrics is compressing Fibre Channel's latency advantage while hyperscale operators demand storage fabrics that scale linearly with GPU clusters. This protocol shift is forcing incumbent switch vendors to redesign backplane architectures for RDMA convergence.
Growth Catalysts
- EU AI Act data sovereignty mandates:Frankfurt's banking sector is accelerating SAN refresh cycles to ensure training data never crosses jurisdictional boundaries.
- AI training workload density:Hyperscale operators in Northern Virginia and Singapore are deploying petabyte-scale Fibre Channel fabrics to feed GPU clusters with checkpoint storage.
- Financial services transaction volumes:Latency-sensitive derivatives trading in Chicago and London is sustaining premium SAN deployments despite cloud migration elsewhere.
Market Restraints
- Copper and rare earth price volatility:Connector assemblies and high-speed PCB substrates face input cost swings that compress hardware margins.
- FCC equipment authorization timelines:Federal procurement channels require 14-18 month certification cycles that delay new switch introductions.
- Software-defined storage substitution:VMware vSAN and Ceph deployments are capturing mid-market virtualization workloads that previously required dedicated SAN fabrics.
Strategic Opportunities
- India's data center buildout:Mumbai and Hyderabad clusters lack mature SAN ecosystems, creating first-mover positioning for Fibre Channel vendors.
- Storage-class memory convergence:Intel Optane and CXL 2.0 fabrics are merging persistent memory tiers with traditional block storage.
- Japan's METI green data center incentives:Power efficiency certifications favor all-flash arrays over hybrid disk configurations.
Industry Challenges
- Fibre Channel skill scarcity:Enterprise storage administrators with FICON and FC zoning expertise are aging out faster than certification programs replace them.
- Legacy mainframe integration:IBM z/OS environments require proprietary FICON gateways that complicate hybrid cloud architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Server Storage Area Network Market |
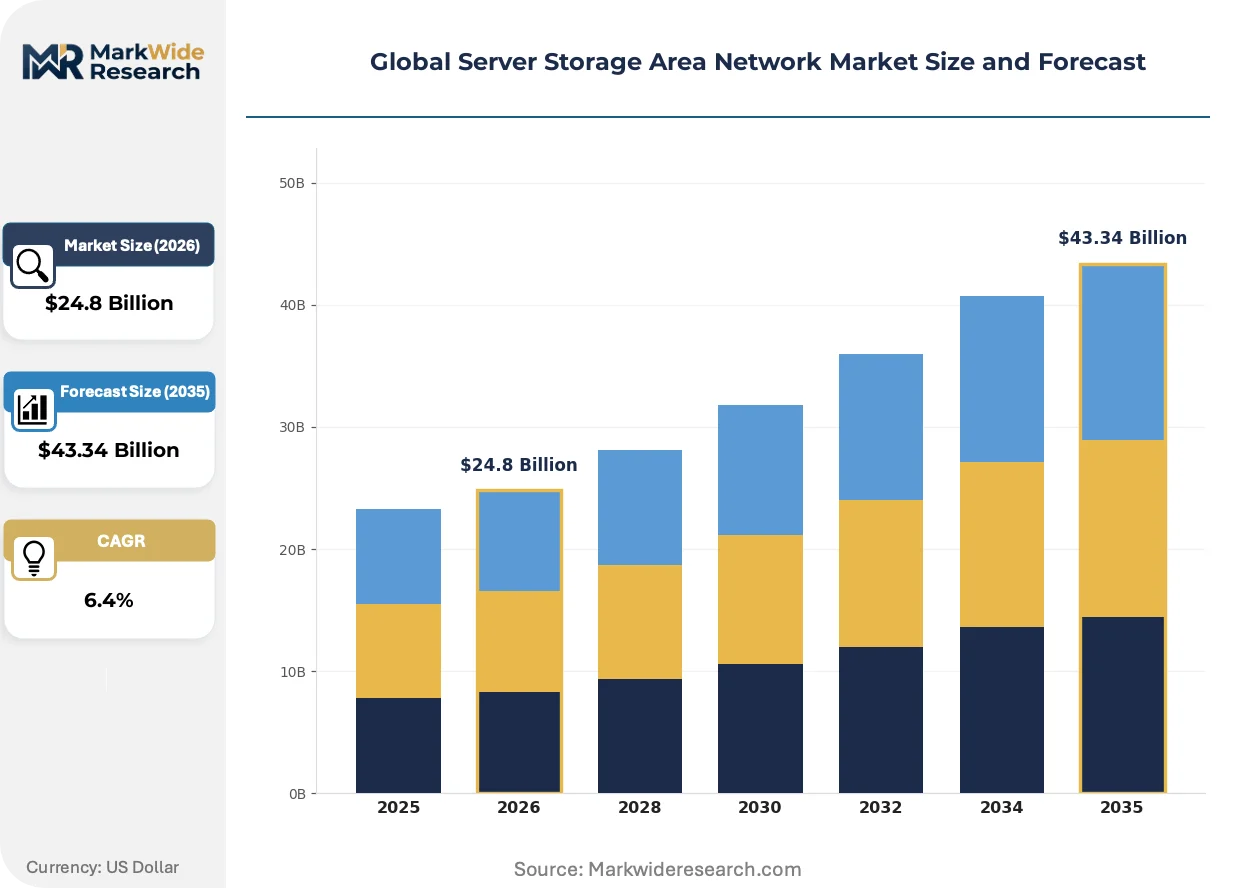
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibre Channel SAN, iSCSI SAN, InfiniBand SAN, Fibre Channel over Ethernet SAN, FCoE SAN Technology: Synchronous Replication, Asynchronous Replication, Thin Provisioning, Snapshot, Tiering Application: Data Center Consolidation, Disaster Recovery, Cloud Data Storage, Backup and Archive, Virtualization End User Industry: Telecommunication Providers, Financial Institutions, Government Agencies, Media Production Firms, Academic Research Centers |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, IBM Corporation, Cisco Systems, NetApp, Hitachi Ltd., Pure Storage, Broadcom, Nutanix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Server Storage Area Network Market Shifts & Advancements
Storage fabric intelligence is migrating from discrete controllers into software layers, decoupling data services from hardware refresh cycles. This abstraction is enabling consumption models that sever capital deployment from capacity scaling.
Computational storage drives with embedded processing capabilities are expanding into AI inference pipelines, filtering datasets before they traverse network fabrics. Automotive manufacturers in Germany and South Korea are piloting these devices for real-time quality inspection. The technology is expanding into edge deployments by eliminating round-trip latency to centralized arrays.
China's MIIT cybersecurity review framework for critical information infrastructure is mandating domestic encryption modules in SAN hardware sold to state-owned enterprises. Foreign vendors must establish joint ventures with local partners to achieve procurement eligibility. State-backed financial institutions in Shanghai and Shenzhen are now prioritizing GB-compliant switch fabrics over international standards.
Enterprise storage procurement is consolidating through managed service contracts that bundle hardware, software, and operational support into single-vendor relationships. Mid-market buyers in Australia and Canada are abandoning three-year capital leases for consumption-based arrangements. This behavioral shift is compressing vendor sales cycles while extending customer lifetime value metrics.
Global Server Storage Area Network Market Segmentation
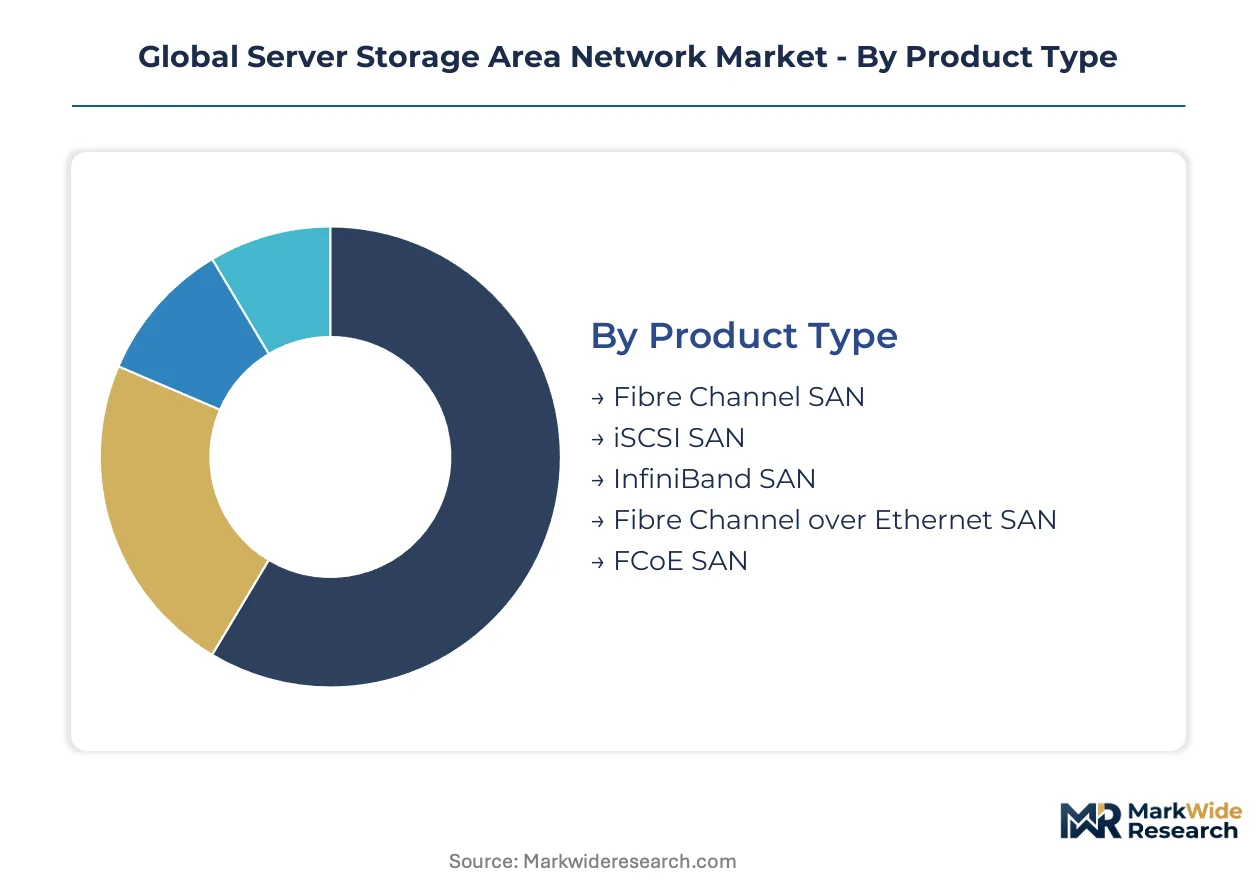
Storage fabric segmentation reveals how protocol choices, replication strategies, and workload requirements fragment procurement decisions across enterprise buyers. Understanding these divisions exposes where vendor specialization creates pricing power versus where standardization erodes margins.
Product Type:
Enterprise buyers differentiate primarily by latency tolerance and existing network infrastructure investment rather than raw capacity needs.
- Fibre Channel SAN:Dedicated 32G/64G switching fabrics deliver sub-millisecond latency through lossless transport. Financial institutions in Chicago and London sustain premium deployments for derivatives trading platforms despite cloud migration pressure elsewhere.
- iSCSI SAN:IP-converged block storage rides existing Ethernet infrastructure, cutting dedicated switch hardware costs. Mid-market virtualization clusters in Germany and Australia favor this protocol where Fibre Channel administrative expertise remains scarce.
- InfiniBand SAN:RDMA-capable fabrics serve GPU cluster checkpoint storage in hyperscale deployments. Northern Virginia and Singapore operators deploy petabyte-scale configurations for AI training workloads.
- Fibre Channel over Ethernet SAN:Converged network adapters reduce cabling complexity in brownfield data center expansions. Early-stage cloud providers in India pilot FCoE to bridge legacy FC assets with IP-based operations.
Fibre Channel SAN leads volumes today; iSCSI SAN is gaining share fastest.
Technology:
Data service sophistication separates enterprise-tier deployments from mid-market commodity configurations.
- Synchronous Replication:Real-time block-level mirroring across metro distances enforces zero recovery point objectives. Frankfurt banking consortia deploy synchronous replication to satisfy EU AI Act data sovereignty mandates without cross-border transfer.
- Asynchronous Replication:Scheduled or journal-based replication tolerates seconds-to-minutes of data loss in exchange for geographic flexibility. This approach expands most quickly among buyers seeking disaster resilience without dedicated dark fiber between sites.
- Thin Provisioning:Virtual capacity allocation defers physical disk purchases until actual write operations occur. Storage administrators in Japanese enterprise data centers favor thin provisioning to optimize capital deployment under METI efficiency guidelines.
- Snapshot:Point-in-time volume copies enable rapid recovery from logical corruption without full backup restoration. Media production firms in South Korea leverage snapshots for non-linear editing workflow protection.
- Tiering:Automated data placement across flash, disk, and cloud storage layers matches cost to access frequency. Academic research centers with mixed workload profiles deploy tiering to balance grant-funded equipment budgets.
Synchronous Replication dominates financial services procurement; Asynchronous Replication shows steepest expansion trajectory.
Application:
Workload consolidation patterns determine whether buyers prioritize raw throughput, geographic redundancy, or operational simplicity.
- Data Center Consolidation:Storage fabric centralization collapses distributed server rooms into fewer facilities. Telecommunication providers in Germany execute consolidation programs to reduce real estate footprints across former state-owned infrastructure.
- Disaster Recovery:Geographically separated storage arrays ensure business continuity against site-level failures. Financial institutions in Singapore and London maintain active-passive SAN pairs across 100+ kilometer distances.
- Cloud Data Storage:Hybrid architectures extend on-premises SAN capacity with public cloud object storage tiers. Government agencies in Washington navigate FedRAMP authorization requirements when selecting cloud-integrated solutions.
- Backup and Archive:Secondary storage targets replace tape libraries with disk-based deduplication appliances. Media production firms in Los Angeles archive petabyte-scale raw footage to SAN-backed repositories.
- Virtualization:Shared block storage enables live migration and high availability for VMware and Hyper-V clusters. Mid-market enterprises in Canada abandon dedicated fabrics for software-defined alternatives in this use case.
Data Center Consolidation commands the largest project budgets; Cloud Data Storage demonstrates the most rapid adoption acceleration.
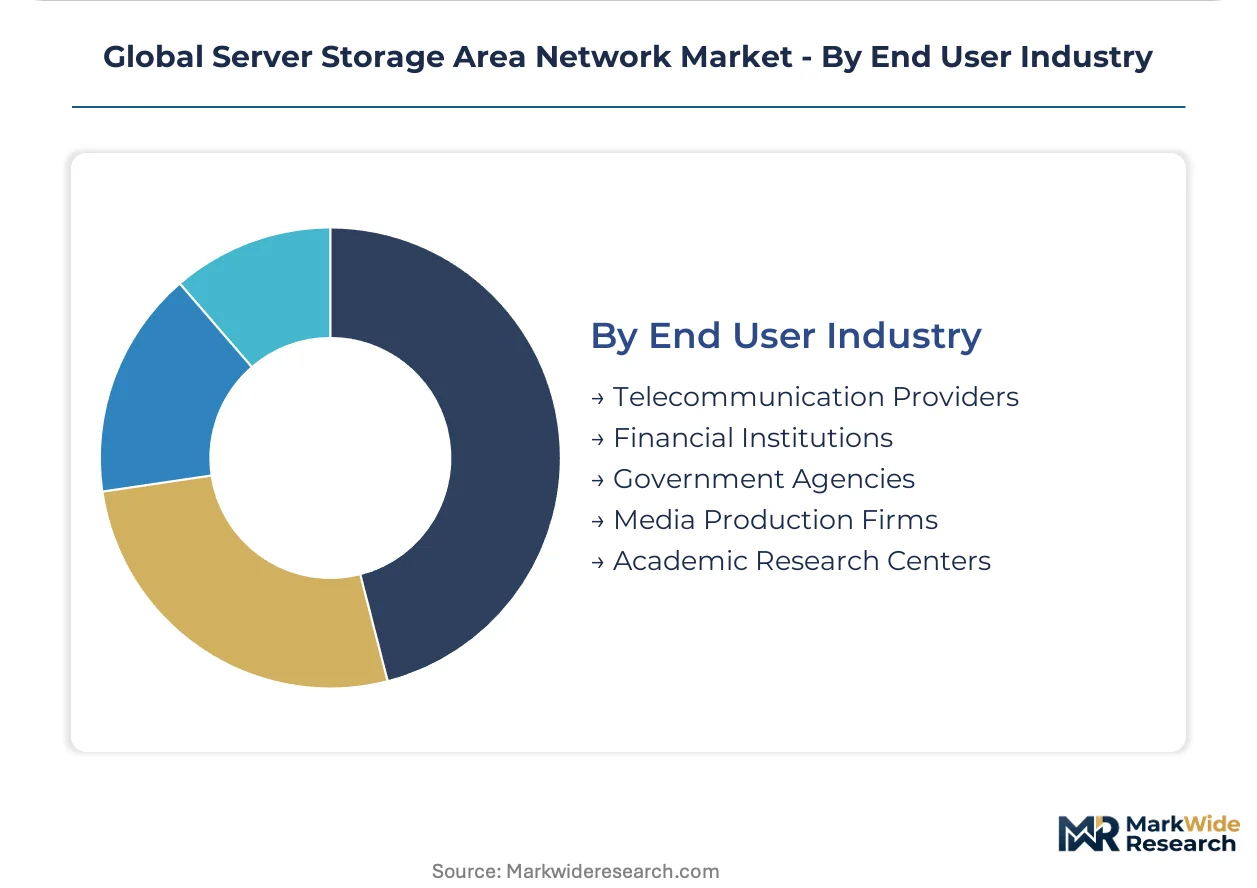
End User Industry:
Regulatory exposure and transaction velocity shape procurement sophistication across vertical markets.
- Telecommunication Providers:5G core network functions and subscriber databases drive sub-millisecond storage requirements. German operators in Frankfurt and Düsseldorf refresh SAN infrastructure to support network function virtualization rollouts.
- Financial Institutions:Algorithmic trading and real-time risk calculation demand deterministic latency. Chicago Mercantile Exchange participants and London clearinghouses sustain premium Fibre Channel deployments despite cloud encroachment elsewhere.
- Government Agencies:Classified and citizen data handling imposes encryption and access logging mandates. US federal buyers navigate FCC equipment authorization timelines extending 14-18 months for new switch hardware.
- Media Production Firms:4K/8K video editing and rendering pipelines require sequential throughput exceeding single-disk performance. South Korean content studios and Los Angeles post-production houses deploy all-flash arrays for real-time playback.
- Academic Research Centers:Grant-funded HPC and genomic sequencing workloads demand scalable capacity without enterprise support contracts. German Max Planck institutes and US National Laboratory facilities favor open-source management tools.
Financial Institutions generate the highest revenue per petabyte deployed; Government Agencies impose the most complex certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's data center cluster anchors global SAN deployment velocity, with hyperscale operators and financial institutions driving infrastructure refresh cycles across three continents.
United States
Northern Virginia's hyperscale corridor and Chicago's financial exchanges sustain dual demand vectors for Fibre Channel fabrics. FCC equipment authorization timelines extending 14-18 months delay new switch introductions for federal procurement channels. Chicago Mercantile Exchange participants maintain premium SAN deployments for algorithmic trading platforms.
Germany
Frankfurt's banking consortia and Düsseldorf-based telecommunications operators anchor European SAN demand. EU AI Act data sovereignty mandates accelerate refresh cycles to ensure training data remains within jurisdictional boundaries. Max Planck institutes favor open-source management tools for grant-funded genomic sequencing workloads.
China
MIIT cybersecurity reviews and GB standards compliance reshape procurement eligibility for state-owned enterprises. Shanghai and Shenzhen financial institutions prioritize domestic encryption modules in switch fabrics. Joint venture requirements with local partners determine market access for foreign vendors.
Japan
METI green data center incentives favor all-flash arrays over hybrid disk configurations in enterprise deployments. Tokyo and Osaka metropolitan areas concentrate demand from automotive manufacturers piloting computational storage for quality inspection pipelines. Power efficiency certifications drive vendor selection criteria.
Singapore
Petabyte-scale Fibre Channel fabrics serve GPU cluster checkpoint storage for AI training operators. Financial institutions maintain active-passive SAN pairs across 100+ kilometer distances for disaster resilience. Government agencies navigate data localization requirements when selecting cloud-integrated solutions.
Global Server Storage Area Network Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to compress R&D cycles for NVMe over Fabrics convergence. The vendor base stratifies across three tiers: diversified infrastructure conglomerates with end-to-end stacks, specialized storage architects with protocol-specific expertise, and component suppliers capturing switch silicon margins. Two archetypes prevail: integrated platform vendors bundling hardware, software, and operational support; and pure-play innovators decoupling data services from hardware refresh cycles. Portfolio diversification and technology licensing represent the dominant competitive vectors.
Among diversified infrastructure providers, Dell Technologies and Hewlett Packard Enterprise occupy positions as archetypal integrated platform vendors, exemplifying the bundling strategy that extends customer lifetime value through managed service contracts. Pure Storage represents the pure-play innovation archetype, anchoring the all-flash segment where simplified architectures eliminate hybrid media complexity. IBM Corporation sits within the legacy integration tier, navigating mainframe connectivity requirements that complicate hybrid cloud transitions for enterprise buyers.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Cisco Systems |
| NetApp |
| Hitachi Ltd. |
| Pure Storage |
| Broadcom |
| Nutanix |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators and Frankfurt banking consortia anchor procurement volumes, locking in contract-based long-term offtake arrangements that stabilize pricing floors for Fibre Channel switch vendors. This buyer concentration shifts bargaining power toward volume purchasers while squeezing margins for mid-tier hardware suppliers serving fragmented enterprise accounts.
Pricing Analysis
Copper and rare earth input-cost pass-through dominates pricing dynamics for connector assemblies and high-speed PCB substrates. Three-tier pricing structure across premium, standard, and economy levels separates deterministic-latency Fibre Channel fabrics from IP-converged iSCSI alternatives. Cost compression in mid-market iSCSI segments intensifies because VMware vSAN and Ceph deployments capture virtualization workloads. Government agencies exhibit lowest price sensitivity due to 14-18 month FCC certification cycles that freeze procurement decisions.
Supply Chain Analysis
China's MIIT cybersecurity reviews and GB standards compliance reshape sourcing for encryption modules in switch fabrics sold to state-owned enterprises. Manufacturing concentrates in China, Taiwan, and South Korea for high-speed switch silicon and connector assemblies. Rare earth magnet supply draws from Chinese processing facilities, creating single-source vulnerability for advanced PCB substrates. Distribution runs through direct OEM relationships with hyperscale operators and systems integrators serving enterprise data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act data sovereignty mandates compound procurement urgency, forcing Frankfurt financial institutions into accelerated refresh cycles that sustain vendor pricing power across the analysis window.
For Market Incumbents: Hedge Fibre Channel revenue exposure by deepening software-defined storage integration and securing CXL 2.0 fabric certifications before NVMe over Fabrics displaces legacy protocols. Incumbents should anchor backward integration into switch silicon design to defend margins against Broadcom's component dominance. For New Entrants and Emerging Players: Enter via India's Mumbai and Hyderabad data center buildouts where mature SAN ecosystems remain underdeveloped and Fibre Channel administrative expertise is scarce. Target mid-market virtualization deployments with consumption-based managed service contracts that bundle hardware, software, and operational support. For Investors and Strategic Acquirers: Diversified infrastructure conglomerates are the most active acquirer in this space, seeking pure-play storage innovators to fill all-flash and NVMe over Fabrics capability gaps. Acquisition targets should demonstrate CXL fabric roadmaps and regional certification progress in China or India. Watch Intel Optane discontinuation effects on persistent memory tier convergence as an inflection indicator for storage-class memory valuations.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe over Fabrics Certification | Protocol convergence enables RDMA-capable fabrics to capture GPU cluster checkpoint storage from legacy Fibre Channel. |
| CXL 2.0 Fabric Integration | Memory pooling architectures merge persistent tiers with traditional block storage for AI training workloads. |
| China Joint Venture Formation | MIIT compliance through local partnerships unlocks procurement eligibility at Shanghai and Shenzhen state-owned banks. |
| Managed Service Contract Expansion | Consumption-based bundling extends customer lifetime value among Australian and Canadian mid-market buyers. |
| Computational Storage Drive Development | Embedded processing capabilities eliminate round-trip latency for German automotive quality inspection pipelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center infrastructure architects, storage administrators, procurement officers at financial institutions, and channel partners with secondary validation. SEC filings from Dell Technologies and Hewlett Packard Enterprise, hyperscaler capex disclosures from Northern Virginia and Singapore operators, and FCC equipment authorization databases anchored supply-side estimates. Bottom-up SAN deployment tallies triangulated against top-down infrastructure spending projections.
Historical reference periods spanning pre-pandemic baseline through AI workload acceleration anchored the forecast window. The analytical framework modeled segmentation across protocol type, replication technology, workload application, and end-user vertical throughout the projection horizon. CAGRs derived from fitted growth curves incorporating Fibre Channel refresh cycle timing, EU AI Act compliance deadlines, and hyperscale GPU cluster expansion rates.
The model holds under stable copper and rare earth pricing; deviation in FCC certification timeline extensions or MIIT cybersecurity review intensification would shift vendor entry sequencing. Forecasts reflect documented assumptions regarding protocol transition velocity and regional procurement authorization progress. A small set of named triggers—CXL 3.0 specification release, India data center PLI scheme expansion, and Intel persistent memory roadmap discontinuation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Storage Software Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Stand Alone Cloud Storage Market