
 United Arab Emirates Data Center Storage Market | 2026-2036
United Arab Emirates Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Data Center Storage Market Insights
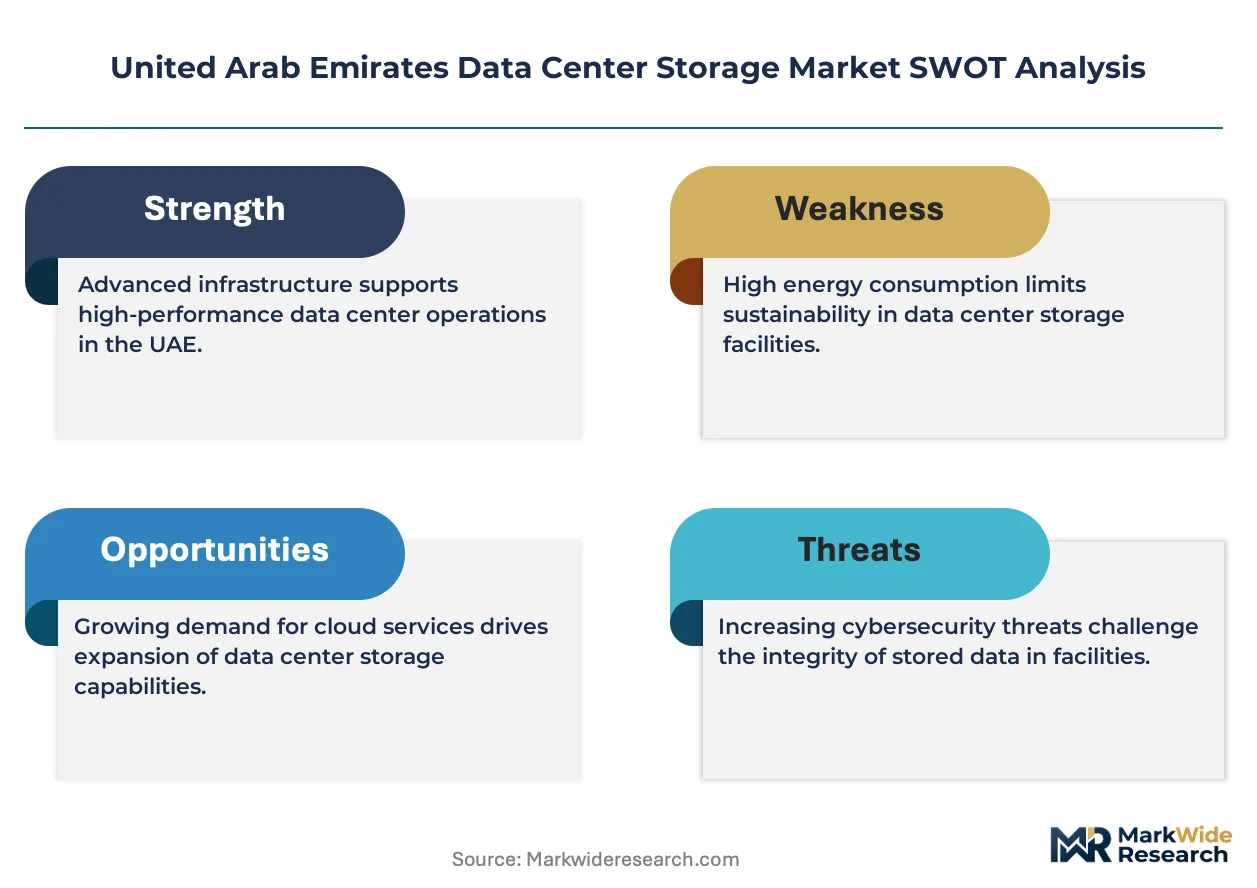
The UAE is tilting its infrastructure investment toward hyperscale and enterprise-grade data center campuses across Abu Dhabi and Dubai. Dell Technologies leverages its integrated server-storage portfolio to anchor large federal contracts. Hewlett Packard Enterprise competes through its GreenLake as-a-service platform tailored to local enterprise consumption models. Huawei Technologies sustains its position via aggressive pricing on all-flash arrays and established relationships with UAE telecom operators.
Data center storage encompasses hardware and software systems engineered to retain, manage, and retrieve digital information across networked computing environments, typically supporting capacities from petabyte-scale archives to sub-millisecond latency flash tiers for transactional workloads. These systems serve as the foundational layer for cloud services, enterprise analytics, and mission-critical application continuity. Software-Defined Storage is capturing disproportionate attention as organizations decouple storage software from proprietary hardware to improve capital efficiency. Flash Storage leads technology procurement for latency-sensitive workloads, while Hybrid Storage configurations dominate cost-optimized tiering strategies across mid-market deployments. The BFSI end-user segment represents a concentrated margin pool given stringent audit and recovery-point requirements.
MOHAP, the UAE's national health regulator, mandates localized patient data residency that directly expands compliant storage procurement. The NESA Information Assurance standards and ADGM data protection rules impose encryption and access-control specifications that vendors must certify before market participation. Stakeholders should monitor how evolving federal AI strategies reshape storage architecture requirements for training data pipelines and inference workloads.
Market Dynamics
Data sovereignty mandates under NESA and ADGM frameworks are forcing immediate infrastructure localization, compressing procurement timelines for compliant storage systems across federal and financial verticals. This regulatory pressure is reshaping vendor qualification criteria and capital allocation patterns.
Growth Catalysts
- NESA Information Assurance Standards:Federal encryption and access-control certifications create mandatory refresh cycles for legacy storage infrastructure. Government entities must deploy certified systems to maintain operational authorization.
- Smart City Data Aggregation:Abu Dhabi and Dubai municipal IoT networks generate petabyte-scale telemetry streams requiring real-time storage tiering. Government-led digitization programs directly expand capacity requirements.
- All-Flash Array Performance:Sub-millisecond latency specifications for transactional workloads are displacing hybrid configurations in high-frequency trading and real-time analytics deployments.
Market Restraints
- Semiconductor Supply Concentration:NAND flash and DRAM component sourcing remains concentrated among East Asian foundries, exposing UAE integrators to allocation volatility and extended lead times.
- Certification Timeline Friction:NESA and ADGM compliance validation processes extend vendor onboarding by 8-14 months, constraining competitive entry and technology refresh velocity.
- Skilled Workforce Scarcity:Local talent pools lack depth in software-defined storage architecture and federal security hardening, forcing reliance on expatriate specialists and inflating implementation costs.
Strategic Opportunities
- Ras Al Khaimah and Fujairah Expansion:Secondary emirates offer greenfield campus development with lower land and power costs than saturated Abu Dhabi and Dubai clusters.
- AI Training Data Pipelines:Federal artificial intelligence strategies mandate localized data lakes for model development, creating demand for high-throughput object storage and parallel file systems.
- Consumption-Based Procurement Models:As-a-service storage contracts align with enterprise preference for operational expenditure treatment, enabling vendor capture of multi-year recurring revenue streams.
Industry Challenges
- Legacy SAN Integration Complexity:Federal entities operate heterogeneous storage estates spanning three architectural generations, complicating unified management and data mobility.
- Compliance Documentation Burden:ADGM data protection rules require granular audit trails and residency attestation that inflate administrative overhead and system design complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Data Center Storage Market |
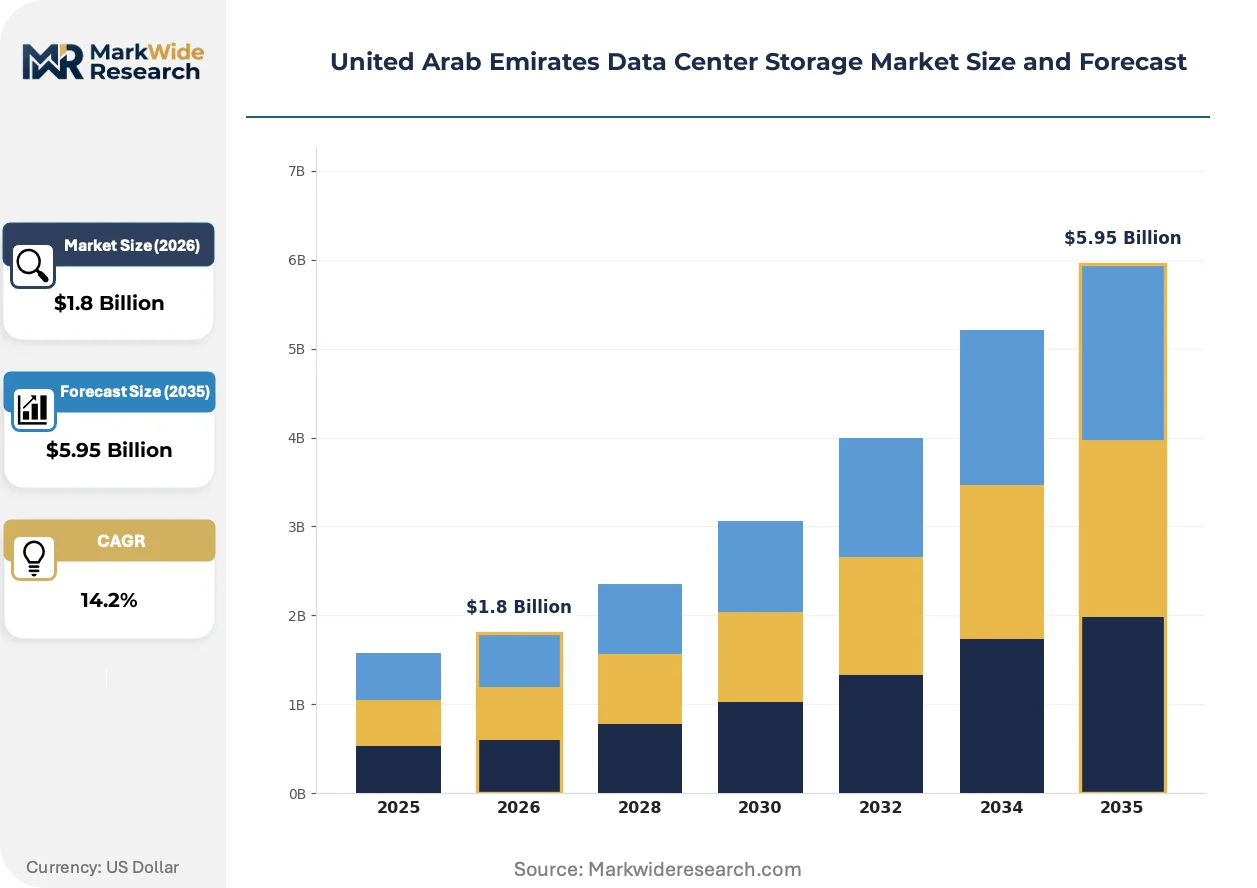
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Software-Defined Storage Technology: Flash Storage, HDD, Hybrid Storage, Cloud Storage End User: Telecommunications, BFSI, Media & Entertainment, Government Deployment Model: On-Premises, Colocation, Managed Services, Hybrid Solutions |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Pure Storage, Huawei Technologies, Lenovo Group, Cisco Systems, Nutanix, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Data Center Storage Market Trends and Innovations
Software-defined architectures are decoupling storage intelligence from hardware substrates, enabling Emirati enterprises to source commodity infrastructure while retaining vendor-agnostic data services. This abstraction layer is compressing traditional array margins while expanding systems integrator influence.
Software-Defined Storage is virtualizing capacity management across disaggregated server fleets. Federal data centers are adopting these platforms to pool NVMe and HDD resources under unified control planes. The technology is virtualizing procurement patterns by allowing compute and storage scaling on independent cycles rather than locked appliance refresh.
ADGM data protection regulations mandate granular residency controls and cross-border transfer documentation for financial institutions. These rules are forcing storage architecture redesigns with explicit geo-fencing and encryption key localization. Wealth management and insurance verticals are responding by deploying air-gapped object storage with immutable snapshot policies.
Enterprise buyers are consolidating vendor relationships around integrated infrastructure stacks rather than best-of-breed component sourcing. Systems integrators and telco cloud divisions are capturing this preference shift through managed storage service bundles. This concentration pattern is most visible among mid-market BFSI entities seeking single-accountability support models.
United Arab Emirates Data Center Storage Market Segmentation
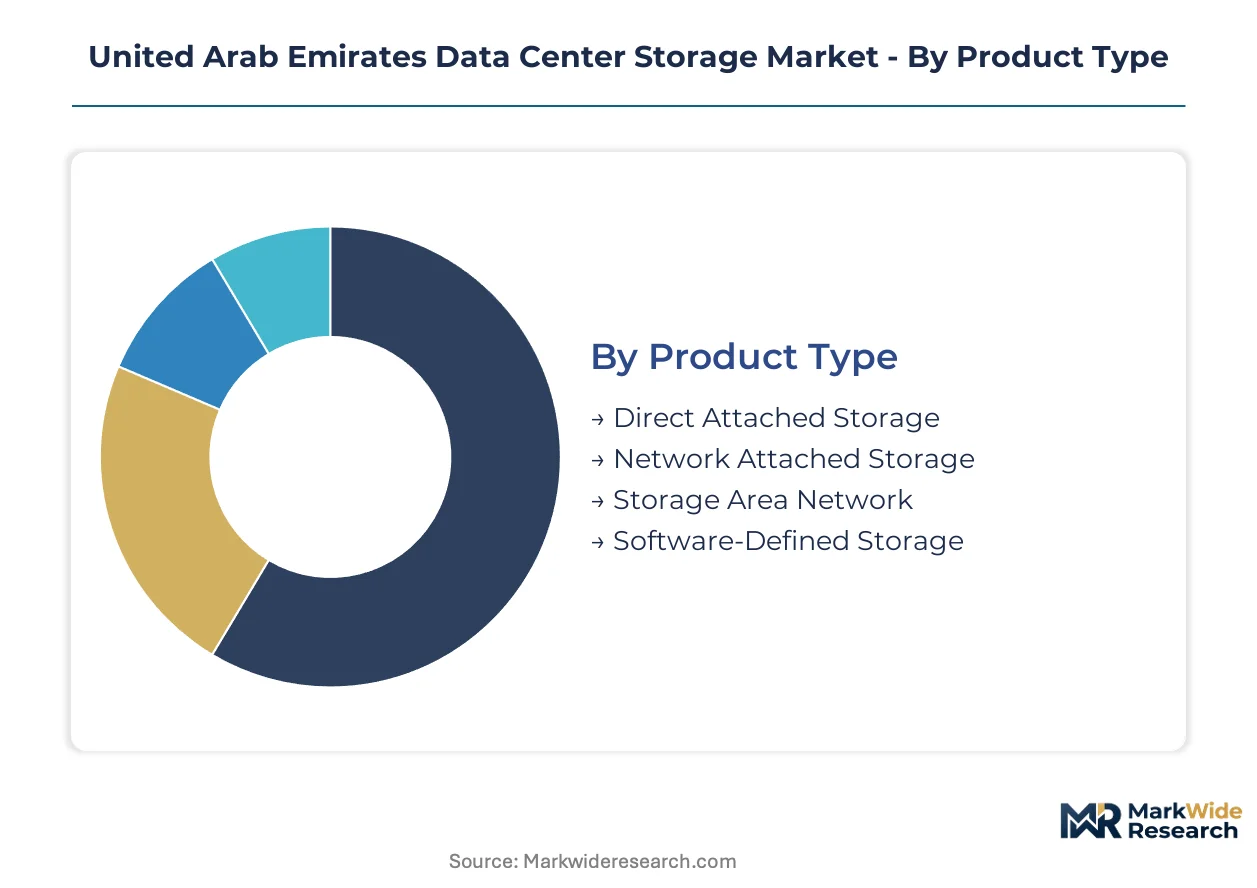
Storage procurement patterns across the Emirates diverge sharply by workload sensitivity, compliance exposure, and capital deployment preferences. Understanding these segment boundaries enables vendors to align certification investments with buyer decision criteria.
Product Type:
Mature architectures dominate federal and financial procurement, while emerging platforms are capturing greenfield enterprise deployments.
- Direct Attached Storage:Localized drive arrays attached directly to individual servers without network intermediation. Abu Dhabi government data centers specify DAS for classified workloads requiring physical air-gapping under NESA standards.
- Network Attached Storage:File-level storage appliances serving multiple clients over standard Ethernet protocols. Dubai Media City content producers deploy NAS for collaborative video editing pipelines demanding concurrent multi-user access.
- Storage Area Network:Block-level storage networks utilizing Fibre Channel or iSCSI fabrics. BFSI transaction processing in DIFC relies on SAN infrastructure for sub-millisecond database response requirements.
- Software-Defined Storage:Decoupled storage software layers abstracting capacity management from underlying hardware. Emirates Development Bank piloted SDS to pool dissimilar vendor arrays under unified policy control.
Storage Area Network retains volume leadership; Software-Defined Storage holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium performance tiers from capacity-optimized archives.
- Flash Storage:Solid-state media delivering microsecond access latencies through NAND or emerging memory technologies. ADGM-regulated high-frequency trading platforms mandate all-flash configurations for competitive execution speeds.
- HDD:Rotating magnetic media offering cost-per-gigabyte economics for cold data retention. Federal archives in Al Ain deploy enterprise HDD for decade-long document retention with minimal access frequency.
- Hybrid Storage:Tiered architectures combining flash and disk media with automated data placement. Dubai SME cloud providers favor hybrid configurations balancing performance guarantees against constrained infrastructure budgets.
- Cloud Storage:Off-premises capacity delivered through subscription models with metered consumption. Etisalat and du enterprise divisions are expanding sovereign cloud storage to meet data residency requirements.
HDD retains volume leadership; Flash Storage holds the steepest expansion curve.
End User:
Application criticality varies dramatically across verticals, with compliance intensity driving procurement specifications.
- Telecommunications:Carrier infrastructure supporting subscriber data, billing systems, and network analytics. du's 5G rollout is expanding edge storage requirements for low-latency content caching across northern emirates.
- BFSI:Banking, financial services, and insurance institutions subject to stringent audit and recovery mandates. First Abu Dhabi Bank maintains geographically separated storage clusters satisfying ADGM business continuity rules.
- Media & Entertainment:Content creation, distribution, and streaming operations generating petabyte-scale unstructured data. twofour54 production facilities require high-throughput storage for 4K and emerging 8K post-production workflows.
- Government:Federal and emirate-level entities managing citizen services, security, and smart city infrastructure. Dubai's RTA telemetry aggregation depends on resilient storage for real-time traffic optimization.
Government retains volume leadership; BFSI holds the steepest expansion curve.
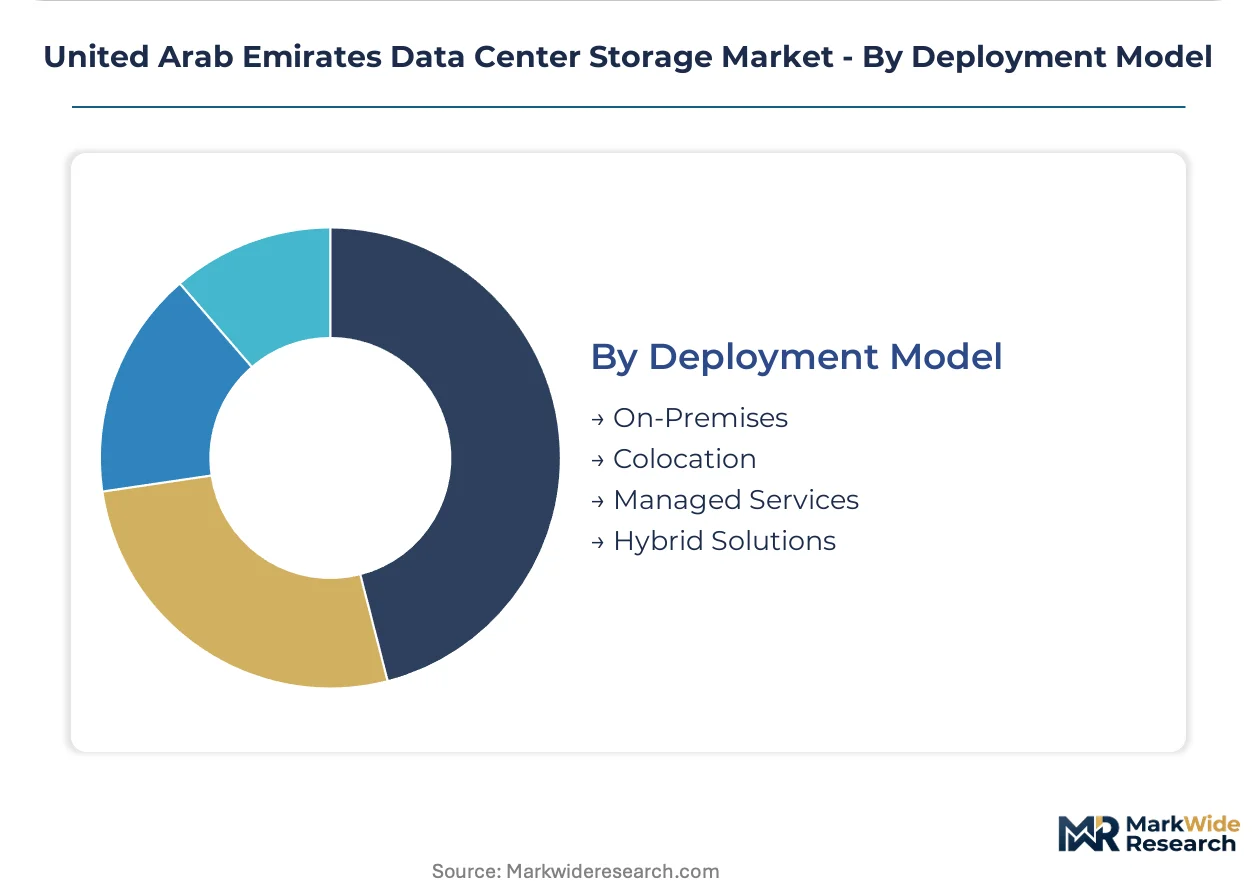
Deployment Model:
Customer type preferences split between capital-retentive institutions and operational-expenditure-oriented enterprises.
- On-Premises:Wholly owned infrastructure within buyer-controlled facilities. Ministry of Interior mandates on-premises storage for national security classifications prohibiting third-party physical access.
- Colocation:Buyer-owned equipment housed in third-party data center facilities. Dubai Internet City enterprises favor colocation to avoid facility construction while retaining hardware control.
- Managed Services:Fully outsourced storage operations with vendor assumption of maintenance and refresh cycles. Emirates NBD reduced internal storage headcount through managed service contracts with tier-one integrators.
- Hybrid Solutions:Workload-distributed architectures spanning on-premises and off-premises capacity. Mashreq Bank deploys hybrid models keeping sensitive core banking on-site while bursting analytics to cloud tiers.
On-Premises retains volume leadership; Managed Services holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NESA and ADGM data sovereignty mandates anchor storage infrastructure deployment across the Emirates, compressing procurement timelines and reshaping vendor qualification criteria throughout the federal and financial verticals.
Dubai
Dubai Internet City and Dubai Media City generate concentrated demand from content producers and cloud providers requiring high-throughput collaborative storage. DIFC regulations impose granular data residency attestation for wealth management institutions. Smart city telemetry aggregation at RTA facilities expands real-time storage tiering requirements.
Abu Dhabi
Abu Dhabi government data centers specify Direct Attached Storage for classified workloads under NESA physical air-gapping standards. ADGM compliance rules mandate encryption key localization for financial institutions operating from Al Maryah Island. Masdar City and Yas Island clusters anchor hyperscale campus development with sovereign cloud mandates.
Sharjah
Sharjah Research Technology and Innovation Park attracts mid-market enterprises seeking colocation alternatives to saturated Dubai and Abu Dhabi clusters. SRTI Park free zone regulations align with federal data protection frameworks while offering competitive facility costs. Industrial and logistics verticals in Hamriyah Free Zone drive archive storage procurement for decade-long document retention.
Northern Emirates
Ras Al Khaimah and Fujairah offer greenfield data center development with lower land and power costs than primary emirates. Federal AI training pipeline initiatives mandate localized data lakes in secondary locations for geographic redundancy. Fujairah's submarine cable landing stations position the emirate as an emerging interconnection hub with edge storage requirements.
United Arab Emirates Data Center Storage Market Competitive Landscape
Integrated infrastructure vendors and cloud-native specialists split the market into distinct procurement channels. Dell Technologies leverages its server-storage portfolio to anchor large federal contracts, while Hewlett Packard Enterprise competes through GreenLake consumption models tailored to local enterprise preferences. Huawei Technologies sustains position via aggressive flash array pricing and established telecom operator relationships. Strategic moves concentrate on certification acceleration under NESA frameworks and consumption-based contract structuring to capture multi-year recurring revenue.
Among the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify vendors competing through comprehensive hardware-software portfolios aligned to federal procurement specifications. Huawei Technologies occupies a distinct position leveraging established relationships with Etisalat and du to penetrate carrier and government verticals. Pure Storage and NetApp represent the all-flash and hybrid cloud-native specialists respectively, competing on latency specifications and software-defined abstraction layers.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Pure Storage |
| Huawei Technologies |
| Lenovo Group |
| Cisco Systems |
| Nutanix |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Semiconductor supply concentration across East Asian foundries creates allocation volatility that compresses pricing spreads between enterprise all-flash arrays and mid-market hybrid configurations while forcing UAE integrators into long-term component pre-commitments. This single-source dependency for NAND flash and DRAM modules simultaneously widens premium tier premiums and constrains supply chain flexibility for secondary emirate deployments.
Pricing Analysis
Abu Dhabi and Dubai command 15-25% price premiums over Ras Al Khaimah and Fujairah for equivalent storage configurations due to facility scarcity and power cost differentials. The market operates on a three-tier pricing structure across premium certified, standard enterprise, and economy tiers, with NESA and ADGM certification levels driving the primary price differentiation. Cost compression in economy-tier hybrid storage is intensifying because Chinese vendors are flooding the UAE channel with uncertified arrays. Government verticals show least price sensitivity given sovereign mandate compliance requirements, while Dubai SME cloud providers exhibit highest sensitivity to per-terabyte acquisition costs.
Supply Chain Analysis
Contract manufacturing for storage controllers and flash modules concentrates among Taiwan Semiconductor Manufacturing Company, Samsung Electronics foundries in South Korea, and SK Hynix fabrication complexes. Component sourcing draws from Malaysia for PCB assembly, Thailand for power supply units, and Vietnam for enclosure manufacturing. Single-source vulnerability for advanced NAND flash nodes creates exposure to foundry allocation decisions and geopolitical trade restrictions. Distribution runs through Dubai-based systems integrators and Etisalat's enterprise divisions, with direct vendor relationships reserved for hyperscale federal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public cloud object storage substitutes threaten on-premises array incumbents as ADGM-regulated financial institutions pilot sovereign cloud migration for tier-two workloads. Incumbents must articulate data residency compliance advantages to defend installed base erosion.
For Market Incumbents: Pre-empt cloud substitution by accelerating NESA certification timelines for software-defined storage platforms that mirror hyperscaler consumption economics. Anchor federal renewals through integrated server-storage bundles that embed multi-year managed service commitments. Defensive consolidation around Emirates Development Bank-style reference architectures strengthens position against Huawei's aggressive flash pricing.
For New Entrants and Emerging Players: Establish a beachhead in Sharjah Research Technology and Innovation Park colocation facilities where incumbent saturation is lowest and facility costs undercut Dubai by 30-40%. Target mid-market BFSI entities seeking single-accountability support models with consumption-based procurement structures. Lead with AI training data pipeline storage configurations aligned to federal artificial intelligence strategies.
For Investors and Strategic Acquirers: The market sits at a regulatory acceleration phase that favors compliance-certified specialists over commodity hardware vendors. Acquisition targets should demonstrate established NESA certification pathways and managed service revenue streams exceeding 40% of total storage bookings. Watch for ADGM amendments expanding cross-border data transfer restrictions as the inflection signal for localized infrastructure demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| NESA Certification Acceleration | Shortens vendor onboarding from 14 months to capture federal refresh cycles before competitors. |
| Ras Al Khaimah Campus Development | Exploits 40% lower land costs than Dubai to anchor sovereign cloud capacity for AI training pipelines. |
| Managed Service Bundling | Captures Emirates NBD-style operational expenditure preference through multi-year recurring revenue streams. |
| All-Flash Array Localization | Meets ADGM sub-millisecond mandates for DIFC high-frequency trading platforms displacing hybrid configurations. |
| Software-Defined Storage Partnership | Enables vendor-agnostic pooling of dissimilar arrays under unified policy control for federal data centers. |
Research Methodology
Operator-level perspectives from data center infrastructure directors, federal procurement officers at NESA-regulated entities, ADGM compliance leads, systems integrator solution architects, and Etisalat enterprise division heads anchored the qualitative base. These primary interviews combined with secondary validation against UAE customs import records for storage hardware, SEC 10-K filings of listed infrastructure vendors, hyperscaler capex disclosure tracking, and federal smart city tender documentation. Bottom-up capacity installation tracking across Abu Dhabi and Dubai facilities triangulated against top-down vendor shipment estimates.
Scenario-bracketing framed the analytical approach with regulatory enforcement intensity and sovereign cloud adoption pace as primary variance drivers across the projection horizon. Segmentation dimensions modeled include storage architecture type, technology tier, end-user vertical, and deployment model complexity alongside emirate-level facility clustering patterns. CAGRs were derived from installation base growth rates adjusted for technology refresh cycles and compliance-mandated replacement timelines. Federal AI training pipeline capacity requirements and BFSI data residency rule evolution served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows, dirham-dollar peg stability, or federal infrastructure budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding NESA certification timeline standardization and ADGM cross-border restriction maintenance. Quarterly review of federal tender award patterns and hyperscaler facility announcement cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Cloud Native Storage Market