
 Hybrid Cloud Storage Market | 2026-2036
Hybrid Cloud Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cloud Storage Market Outlook
Storage as a Service subscription models is recalibrating how enterprises procure capacity and manage operational expenditure. Dell Technologies leverages its server-hardware heritage to anchor on-premises integration points for hybrid workloads. Nutanix competes through software-defined storage layers that unify public and private cloud pools. Cloudian specializes in object-storage gateways that extend S3-compatible APIs into customer data centers.
Hybrid cloud storage combines on-premises infrastructure with public cloud resources through unified management planes, typically orchestrated via software-defined controllers that automate data tiering, encryption, and replication across heterogeneous environments. Block storage retains dominance in transactional database workloads where latency thresholds sit below five milliseconds, while object storage captures the fastest expansion as unstructured data volumes from AI training pipelines and media archives multiply. Managed Services commands the deepest margin pools because recurring operational contracts embed migration, monitoring, and compliance automation that customers struggle to replicate in-house.
GDPR enforcement by European data protection authorities and HIPAA oversight from the US Department of Health and Human Services compel enterprises to maintain geo-fenced data copies with auditable access logs. ISO 27001 certification has become a de facto procurement gate for hybrid cloud vendors serving regulated industries. Stakeholders must weigh data-residency commitments against cloud-portability safeguards before locking into multi-year service contracts.
Market Dynamics
Data sovereignty mandates from GDPR and HIPAA are forcing enterprises to maintain geo-fenced storage architectures that span on-premises and public cloud environments. This regulatory pressure is compressing procurement cycles and elevating compliance automation to a primary vendor selection criterion.
Growth Catalysts
- GDPR Enforcement:European data protection authorities impose fines that compel financial services firms to deploy hybrid architectures with auditable access logs and localized data copies.
- AI Training Pipelines:Unstructured data volumes from machine learning workloads are accelerating object storage deployment across media and technology sectors.
- ISO 27001 Certification:This framework has become a de facto procurement gate for vendors serving healthcare and banking sectors in Germany and Japan.
Market Restraints
- Encryption Key Management Complexity:Multi-cloud key synchronization creates operational friction that extends deployment timelines by months.
- Bandwidth Cost Volatility:Egress fees from hyperscale providers constrain data mobility between on-premises and cloud tiers.
- Technical Debt in Legacy SAN:Block storage arrays from prior decades resist API-driven orchestration without costly controller upgrades.
Strategic Opportunities
- Edge Computing Convergence:Kubernetes-native storage controllers are integrating with 5G edge nodes to enable low-latency processing for manufacturing IoT.
- Japan's METI Digital Infrastructure Push:Government incentives for data localization are creating demand for S3-compatible object gateways in Tokyo and Osaka.
- Managed Services White Space:Mid-market enterprises in the United States lack in-house migration expertise, opening recurring revenue streams for operational contracts.
Industry Challenges
- Multi-Cloud Orchestration Talent:Shortage of engineers fluent in Terraform and cloud-native storage APIs extends implementation timelines.
- Interoperability Certification Delays:Vendor-specific API extensions fragment the ecosystem and complicate buyer evaluation.
- Legacy NAS Integration:File protocol translation between POSIX-compliant systems and object APIs requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cloud Storage Market |
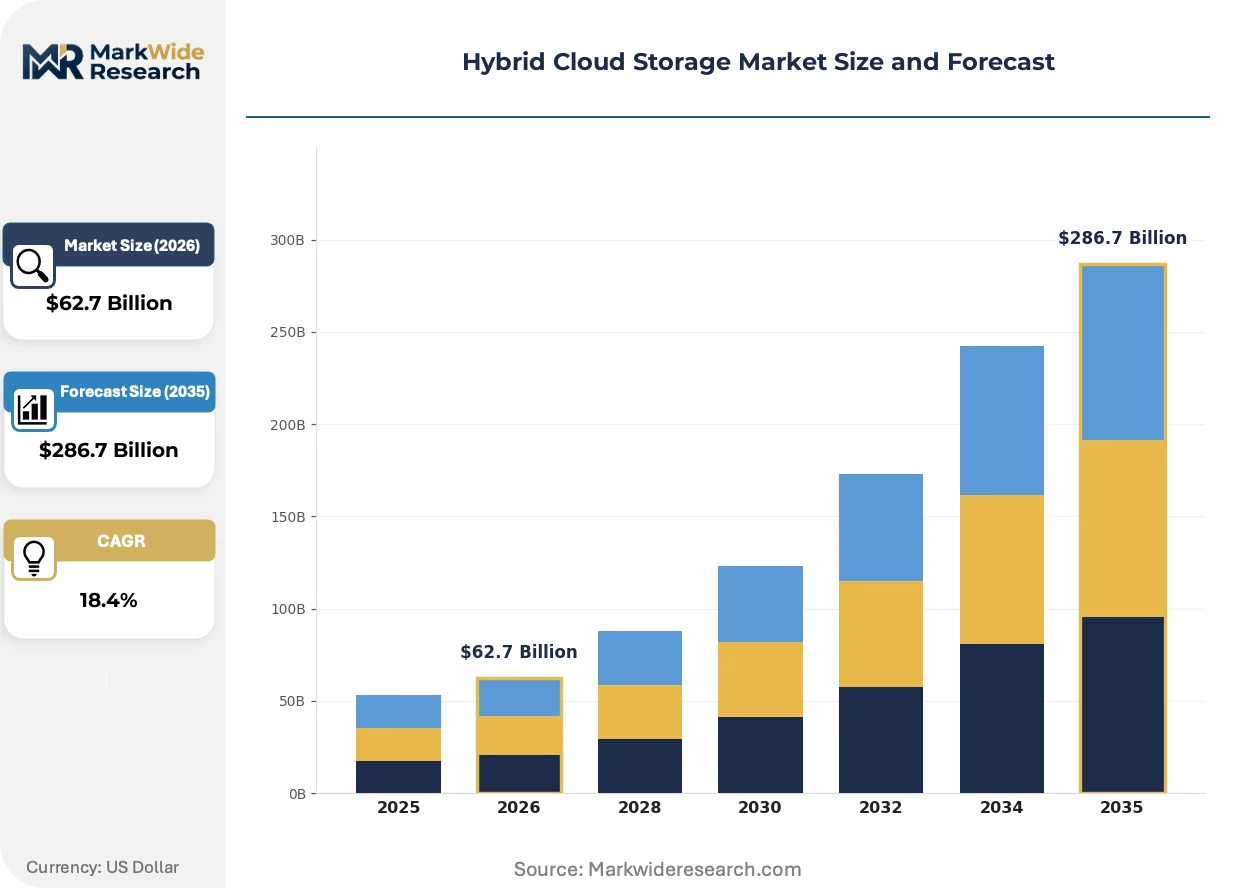
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $286.7 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, On-Premises Storage Type: Block Storage, Object Storage, File Storage, Backup Storage End User: Small Enterprises, Large Enterprises, Government, Healthcare Service Type: Managed Services, Professional Services, Storage as a Service, Data Migration Services |
| Companies Covered | Oracle Cloud Infrastructure, Cohesity, Dell Technologies, Hedvig, Cloudian, Nutanix, Infinidat, HPE, VMware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cloud Storage Market Strategic Shifts
Software-defined storage controllers are displacing hardware-centric procurement models, while policy-driven data tiering automates movement across cost-optimized infrastructure layers. These shifts are compressing the traditional boundary between on-premises and public cloud operations.
Immutable object storage with WORM capabilities is integrating ransomware protection into primary storage workflows. Healthcare providers and financial institutions in the United States are adopting these architectures to satisfy HIPAA and SEC record-keeping requirements. This integration is compressing the separate backup and primary storage budget lines into unified capital planning.
CSRD disclosure requirements from the European Union are mandating carbon footprint reporting across IT infrastructure. Enterprises must now track energy consumption per terabyte across hybrid environments, affecting vendor selection in Germany and France. Storage vendors are responding with power-efficiency certifications and renewable energy matching programs.
Consumption-based capacity contracts are replacing upfront capital purchases among mid-market buyers. Managed service providers in Japan and the United States are unbundling migration, monitoring, and optimization into separate subscription tiers. This pattern is most visible in financial services, where CFOs prioritize operational expenditure predictability over asset ownership.
Hybrid Cloud Storage Market Segmentation
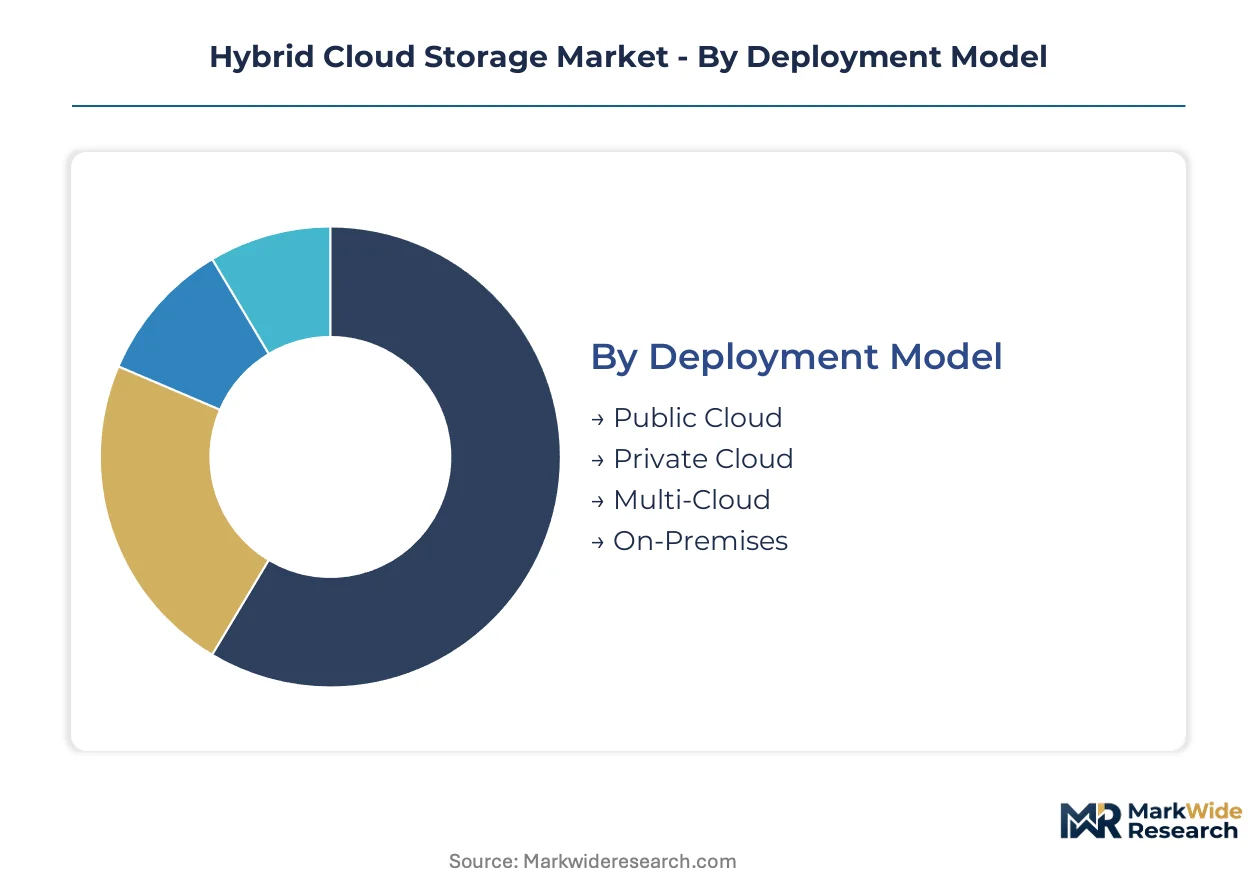
Hybrid cloud storage procurement patterns diverge sharply across deployment models and service tiers, with regulatory mandates and workload latency requirements dictating architecture choices. Vendors must map their portfolios against four distinct segmentation axes to capture wallet share in this fragmented landscape.
Deployment Model:
Supply concentration in hyperscale infrastructure is reshaping how enterprises architect hybrid environments, with procurement decisions increasingly driven by data residency requirements rather than pure cost optimization.
- Public Cloud:Hyperscale providers operate shared infrastructure pools with elastic capacity scaling and consumption-based metering. Financial services firms in Germany and the United States deploy public tiers for non-regulatory workloads while maintaining geo-fenced copies on sovereign infrastructure to satisfy GDPR and HIPAA localization mandates.
- Private Cloud:Dedicated infrastructure environments deliver single-tenant isolation with customizable security postures. Healthcare providers in Japan favor private deployments for patient record systems governed by METI data localization guidelines and institutional privacy policies.
- Multi-Cloud:Orchestrated workloads span two or more public or private cloud domains through unified control planes. This architecture mitigates vendor lock-in risks but introduces encryption key synchronization complexity that extends deployment timelines.
- On-Premises:Customer-owned data center infrastructure retains full physical control over hardware and data placement. Manufacturing IoT deployments in Germany leverage on-premises storage for sub-five-millisecond latency requirements in predictive maintenance pipelines.
Today's leader: Private Cloud. Tomorrow's challenger: Multi-Cloud.
Storage Type:
Cost tier differentiation separates transactional workloads from archival repositories, with price per gigabyte varying by an order of magnitude across the spectrum.
- Block Storage:Fixed-size data blocks with direct-attached performance characteristics serve database and virtual machine workloads. Transactional systems in United States financial institutions demand sub-five-millisecond latency thresholds that block arrays uniquely satisfy.
- Object Storage:Flat address spaces with metadata-rich addressing accommodate unstructured data at massive scale. AI training pipelines across media and technology sectors are expanding object storage volumes fastest as machine learning datasets multiply.
- File Storage:Hierarchical directory structures with POSIX-compliant access protocols support legacy applications and user home directories. Enterprise content management systems in Japanese government agencies rely on file semantics for document collaboration workflows.
- Backup Storage:Immutable retention targets with WORM capabilities protect against ransomware and satisfy regulatory record-keeping. HIPAA and SEC requirements in United States healthcare and financial sectors are compressing separate backup budget lines into unified storage planning.
Block Storage commands current revenue concentration. Object Storage is climbing the fastest as unstructured data volumes accelerate.
End User:
Volume concentration among regulated enterprises with complex compliance obligations creates margin premiums that mid-market buyers cannot replicate.
- Small Enterprises:Organizations with limited IT headcount favor consumption-based contracts and managed service overlays. Migration expertise shortages in the United States mid-market open recurring revenue streams for operational subscription tiers.
- Large Enterprises:Multi-national corporations with distributed operations require geo-redundant architectures and centralized policy governance. ISO 27001 certification has become a de facto procurement gate for vendors serving banking and healthcare sectors in Germany and Japan.
- Government:Public sector entities mandate sovereign data placement with auditable access controls and domestic encryption key custody. CSRD disclosure requirements from the European Union now mandate carbon footprint tracking across government IT infrastructure in France and Germany.
- Healthcare:Patient data systems operate under strict confidentiality regimes with immutable audit trails and breach notification protocols. HIPAA oversight from the US Department of Health and Human Services compels geo-fenced storage with localized data copies and access logging.
Large Enterprises dominate procurement value today. Healthcare is gaining share fastest as digital health records expand and regulatory enforcement tightens.
Service Type:
Margin structure varies dramatically across service tiers, with recurring operational contracts embedding expertise that customers struggle to replicate in-house.
- Managed Services:Ongoing operational contracts covering monitoring, optimization, and incident response with defined service level agreements. These engagements command the deepest margin pools through multi-year commitments and embedded compliance automation.
- Professional Services:Project-based consulting for architecture design, migration planning, and implementation support. Kubernetes-native storage controller deployments for 5G edge manufacturing IoT in Germany rely on professional services for integration complexity.
- Storage as a Service:Subscription capacity models with utility-based metering and minimal upfront capital requirements. CFOs in United States financial services prioritize operational expenditure predictability over asset ownership in procurement decisions.
- Data Migration Services:Specialized tooling and expertise for workload transition between on-premises and cloud environments. Legacy SAN technical debt from prior decades resists API-driven orchestration without costly controller upgrades that migration services must navigate.
Managed Services anchors vendor profitability today. Storage as a Service is expanding most quickly as consumption-based procurement displaces capital purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting hybrid cloud storage procurement toward jurisdictions with clearer compliance cost structures. Enterprises migrate workload placement based on data-localization enforcement intensity and sovereign infrastructure availability.
United States
HIPAA oversight from the US Department of Health and Human Services compels healthcare providers to maintain geo-fenced storage with auditable access logs. Financial services firms face SEC record-keeping requirements that favor immutable object architectures. The Dallas-Fort Worth metroplex hosts expanding data center clusters serving mid-market enterprises seeking operational expenditure predictability.
Germany
GDPR enforcement by European data protection authorities imposes fines that accelerate hybrid procurement cycles among banking and insurance sectors. The EU AI Act adds algorithmic audit trail requirements that storage vendors must satisfy. Frankfurt's financial district anchors sovereign cloud demand, with Bavarian manufacturing hubs adopting edge-integrated storage for predictive maintenance pipelines.
Japan
METI data localization guidelines drive patient record systems toward private cloud deployments with domestic encryption key custody. Government incentives under the Digital Infrastructure Push create demand for S3-compatible object gateways. Tokyo and Osaka metropolitan areas concentrate managed services contracts as mid-market enterprises lack in-house migration expertise.
United Kingdom
Post-Brexit data adequacy negotiations with the EU compel enterprises to maintain UK-resident storage copies alongside continental infrastructure. Financial services regulators in the City of London emphasize operational resilience directives affecting backup architecture design. Manchester and Birmingham emerging as secondary cloud regions reducing latency to northern industrial corridors.
India
RBI guidelines on data localization mandate financial transaction records remain within national boundaries, stimulating domestic hybrid cloud deployment. The country's national data protection framework under parliamentary review adds compliance uncertainty that vendors navigate through modular architecture offerings. Bangalore and Hyderabad technology corridors host enterprise headquarters driving object storage demand for AI training pipelines.
Hybrid Cloud Storage Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with infrastructure incumbents defending position through hardware-software integration while software-defined challengers capture growth in multi-cloud orchestration. The vendor base concentrates among three tiers: hyperscale cloud operators with elastic capacity pools, legacy hardware vendors extending on-premises integration points, and pure-play software vendors unifying heterogeneous environments. Strategic archetypes include platform consolidators seeking end-to-end control, API-native specialists enabling portability, and managed service wrappers embedding compliance automation. Dominant competitive moves encompass strategic partnerships between hardware and cloud operators, plus portfolio diversification into edge-native storage controllers.
Within the platform consolidator tier, Dell Technologies and Oracle Cloud Infrastructure exemplify hardware-cloud bundling strategies that anchor enterprise procurement decisions. HPE occupies a position bridging legacy SAN integration with consumption-based service models. Among software-defined specialists, Nutanix and VMware represent the API-native archetype, while Cohesity and Cloudian sit within the data management layer where immutable retention and ransomware protection differentiate offerings. Hedvig and Infinidat exemplify targeted architectural approaches to distributed storage challenges.
| Leading Market Players |
|---|
| Oracle Cloud Infrastructure |
| Cohesity |
| Dell Technologies |
| Hedvig |
| Cloudian |
| Nutanix |
| Infinidat |
| HPE |
| VMware |
| Others |
Value Chain & Pricing Dynamics
CSRD disclosure requirements from the European Union gate qualified supply and premium-tier pricing access by mandating carbon footprint tracking per terabyte across hybrid environments. Vendors lacking renewable energy matching programs or power-efficiency certifications face exclusion from procurement shortlists in Germany and France, compressing margins for non-compliant suppliers while rewarding certified players with pricing power.
Pricing Analysis
Capacity additions in hyperscale regions are reshaping price floors as hyperscalers expand sovereign cloud infrastructure in Frankfurt and Tokyo. Consumption-based subscription models dominate procurement, with ISO 27001 certification and data residency guarantees driving premium-mid-economy pricing differentiation. Cost compression in standard tiers is intensifying because managed service providers unbundle migration and monitoring into separate subscription tiers. Small enterprises exhibit highest price sensitivity due to limited IT headcount, while large financial institutions in Germany prioritize compliance predictability over unit cost.
Supply Chain Analysis
ISO 27001 and CSRD certification requirements gate supplier qualification, filtering hardware vendors and software-defined specialists before procurement engagement. Supply concentrates in the United States, Germany, and Japan where sovereign infrastructure investments cluster. Component sourcing draws from Taiwan for server-grade semiconductors, South Korea for memory modules, and domestic fabs for encryption processors. Single-source vulnerability in specialized controller chips creates exposure during geopolitical trade restrictions. Distribution runs through direct enterprise sales teams and hyperscale marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward immutable object storage with WORM capabilities that satisfy HIPAA and SEC record-keeping requirements. Premium specifications now command margin premiums that commodity block storage cannot replicate.
For Market Incumbents: Deploy software-defined controller investments to defend against API-native specialists threatening hardware-centric revenue streams. Consolidate position through backward integration into encryption processor supply chains, reducing exposure to Taiwan semiconductor bottlenecks. Acquire managed services capabilities to capture recurring operational contracts that mid-market buyers cannot replicate in-house. For New Entrants and Emerging Players: Capture white space in Japan's METI Digital Infrastructure Push by offering S3-compatible object gateways with domestic encryption key custody. Target mid-market healthcare providers in the United States lacking in-house migration expertise for HIPAA-compliant deployments. Lead with consumption-based capacity contracts that prioritize operational expenditure predictability over upfront capital purchases. For Investors and Strategic Acquirers: Roll-up economics work for software-defined storage specialists because multi-cloud orchestration talent scarcity extends implementation timelines and embeds switching costs. Platform consolidation across Kubernetes-native controllers and edge-integrated architectures offers five-to-ten-year viability as manufacturing IoT expands. Watch hyperscaler sovereign cloud announcements in Frankfurt and Tokyo as inflection indicators for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies on-premises and public cloud pools through software-defined controllers that automate data tiering. |
| Strategic Partnership | Hardware vendors ally with hyperscalers to anchor sovereign cloud integration points in Frankfurt and Tokyo. |
| Acquisition of Specialist Firm | Managed services providers buy migration tooling vendors to capture mid-market operational subscription tiers. |
| Geographic Expansion | S3-compatible object gateway vendors enter Osaka and Dallas-Fort Worth to serve data localization mandates. |
| Product Launch | Immutable object storage with WORM capabilities integrates ransomware protection into primary storage workflows. |
Study Parameters
Multiple input streams — CTO interviews, IT procurement officer surveys, hyperscaler capex disclosures, and SEC filings — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged storage architects, compliance officers at financial institutions, channel partners, and integration specialists across Germany, the United States, and Japan. Secondary validation drew from GDPR enforcement records, HIPAA audit reports, METI policy documents, and ISO certification databases. Bottom-up capacity deployment tracking and top-down enterprise IT spend analysis were triangulated against vendor-reported subscription metrics.
Historical capacity shipment patterns were cross-referenced against panel input from infrastructure planners to anchor growth trajectories across the projection horizon. Segmentation modeling spanned deployment model, storage type, organization size, vertical compliance intensity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with AI training pipeline expansion and edge computing convergence serving as volume-scaling inputs.
Regulatory enforcement intensity shifts, hyperscaler pricing actions on egress fees, and encryption standard updates are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding sustained GDPR and HIPAA localization mandates without material relaxation. A model refresh is warranted upon material change in sovereign cloud infrastructure deployment timelines or METI incentive program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Hard Disk Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Disk-Based Backup System Market