
 Sweden Data Center Storage Market | 2026-2036
Sweden Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Storage Market Insights
Swedish financial services is repositioning data center storage requirements as algorithmic trading and real-time risk analytics expand capacity needs. Dell Inc. leverages its direct attached storage portfolio to serve Stockholm-based banking clusters. Hewlett Packard Enterprise anchors enterprise hybrid deployments through its GreenLake platform presence in Nordic facilities. NetApp Inc. specializes in cloud-adjacent storage architectures that appeal to Sweden's software-as-a-service exporters.
Data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention across enterprise IT environments, with NVMe protocols delivering sub-100-microsecond latency for transactional workloads. SSD technology leads technology segment value contribution as Swedish operators phase out mechanical drives from performance tiers. Hybrid deployment models capture expanding margin pools by bridging on-premises compliance requirements with public cloud burst capacity. Object storage architectures compete for unstructured data growth from national research institutions and media archives.
BIS certification requirements for imported storage hardware intersect with Sweden's implementation of EU CSRD sustainability disclosure rules, elevating energy efficiency metrics in procurement evaluations. The Swedish Energy Agency enforces PUE reporting standards that favor flash-based storage over power-intensive disk arrays. Stakeholders must monitor evolving EU AI Act infrastructure classifications that could reclassify training-data repositories as high-risk system components.
Market Dynamics
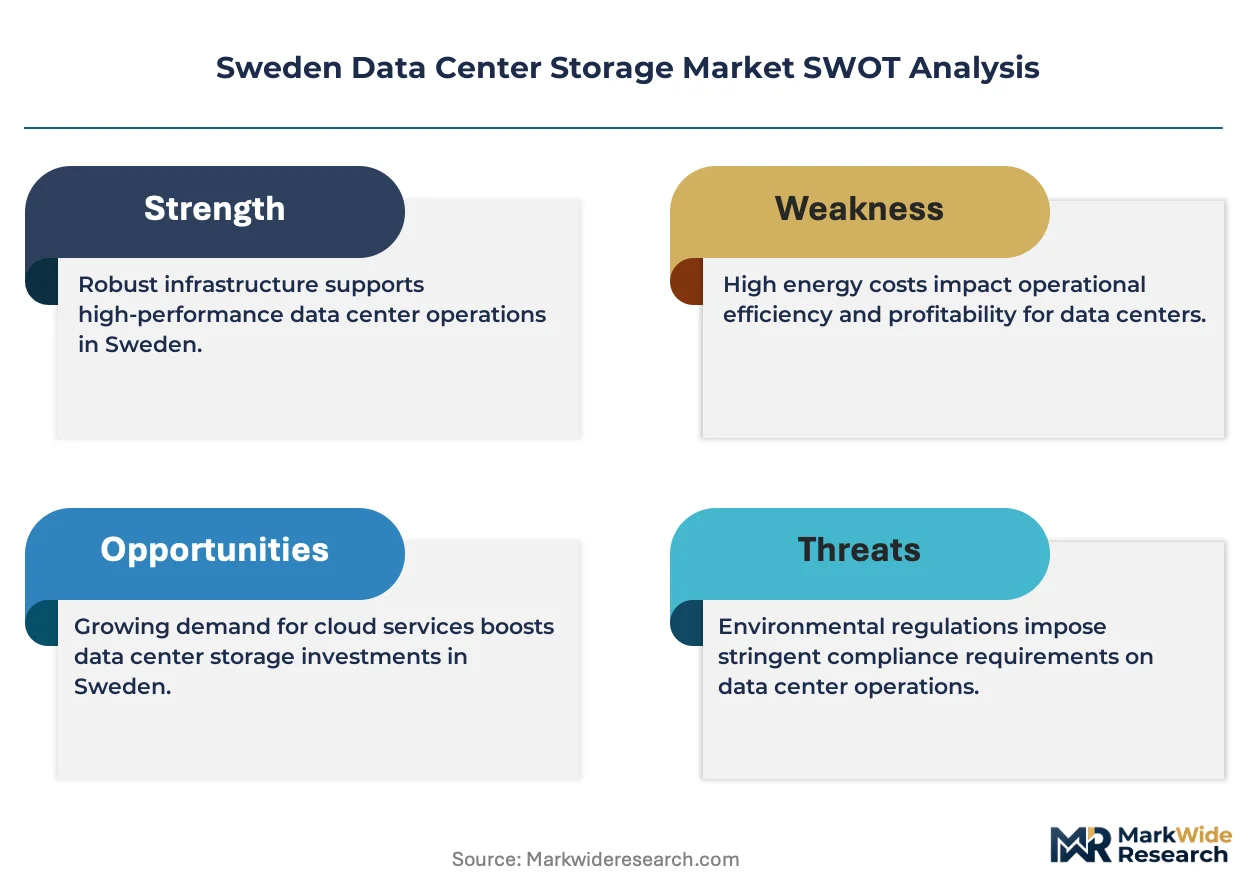
EU AI Act infrastructure classifications and Swedish Energy Agency PUE mandates are compressing procurement timelines while elevating flash storage specifications above legacy disk architectures. Stockholm's data center corridor operators now face dual pressure: compliance velocity and carbon intensity reduction.
Growth Catalysts
- AI Training Workloads:Swedish cloud service providers are accelerating storage procurement to support generative model development, with NVMe-based systems capturing preference for sub-100-microsecond latency requirements.
- EU CSRD Disclosure Rules:Sustainability reporting mandates are reshaping infrastructure procurement standards, forcing energy efficiency metrics into vendor evaluation scorecards ahead of mechanical drive phaseouts.
- Hyperscale Facility Investments:Low-carbon energy access in Stockholm's data center corridor attracts international facility operators expanding Nordic footprints.
Market Restraints
- Import Certification Friction:BIS certification requirements for foreign-manufactured storage hardware extend procurement cycles and constrain vendor pool flexibility.
- Flash Memory Cost Structure:NAND supply concentration in East Asian fabrication facilities exposes Swedish operators to input cost volatility and currency fluctuation risk.
- Mechanical Drive Stranding:PUE reporting standards disadvantage power-intensive disk arrays, creating asset write-down pressure for operators with recent spinning-disk investments.
Strategic Opportunities
- Gothenburg Secondary Cluster:Underpenetrated western Sweden data center capacity offers expansion runway as Stockholm land and power constraints tighten.
- Research Institution Object Storage:Unstructured data growth from national scientific archives and media repositories creates demand for cloud-adjacent S3-compatible architectures.
- EU Green Deal Funding:Carbon-neutral infrastructure incentives subsidize heat-reuse datacenter designs that pair flash storage with district heating systems.
Industry Challenges
- AI Act Classification Ambiguity:Evolving definitions of high-risk system components create uncertainty whether training-data repositories trigger enhanced compliance obligations.
- Hybrid Integration Complexity:Bridging on-premises compliance requirements with public cloud burst capacity demands specialized engineering talent scarce in Nordic labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Storage Market |
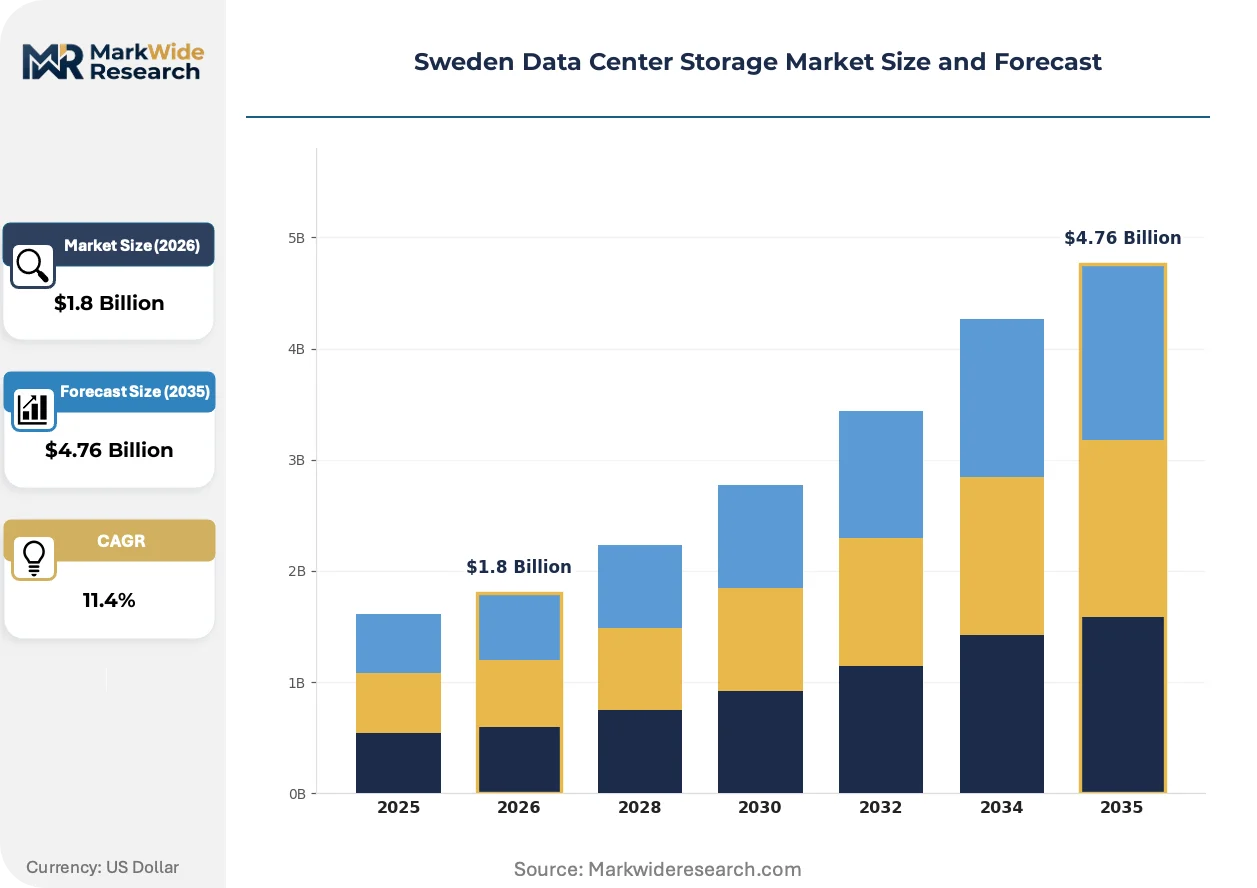
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage End User: Enterprises, Government, Service Providers, Research Institutions Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud Technology: SSD, HDD, NVMe, Object Storage |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies Co. Ltd., Hitachi Vantara LLC, Schneider Electric, ABB, Vertiv, Cisco Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Storage Market Trends and Innovations
Storage architecture evolution in Sweden centers on latency compression, regulatory alignment, and procurement model transformation. Three developments dominate vendor positioning and buyer decision frameworks.
NVMe-over-Fabrics protocols are extending sub-100-microsecond performance beyond local attached storage into networked environments. Swedish financial services clusters in Stockholm are adopting these architectures for algorithmic trading and real-time risk analytics. This performance tier is converging with software-defined storage controllers, collapsing the historical separation between speed and scale.
The EU AI Act's infrastructure classifications are redefining which storage systems qualify as high-risk components requiring enhanced documentation. Swedish operators must now maintain audit trails for training-data repositories that feed into regulated AI applications. National research institutions and SaaS exporters face the steepest compliance burden as they scale machine learning operations.
Buyers are unbundling hardware acquisition from operational management, favoring consumption-based arrangements that transfer capacity planning risk to vendors. Stockholm-based banking clusters and hyperscale facilities are driving this transition, replacing capital-intensive refresh cycles with service contracts indexed to actual utilization. This reconfiguration is most visible among operators with carbon-neutral commitments seeking to outsource PUE optimization.
Sweden Data Center Storage Market Segmentation
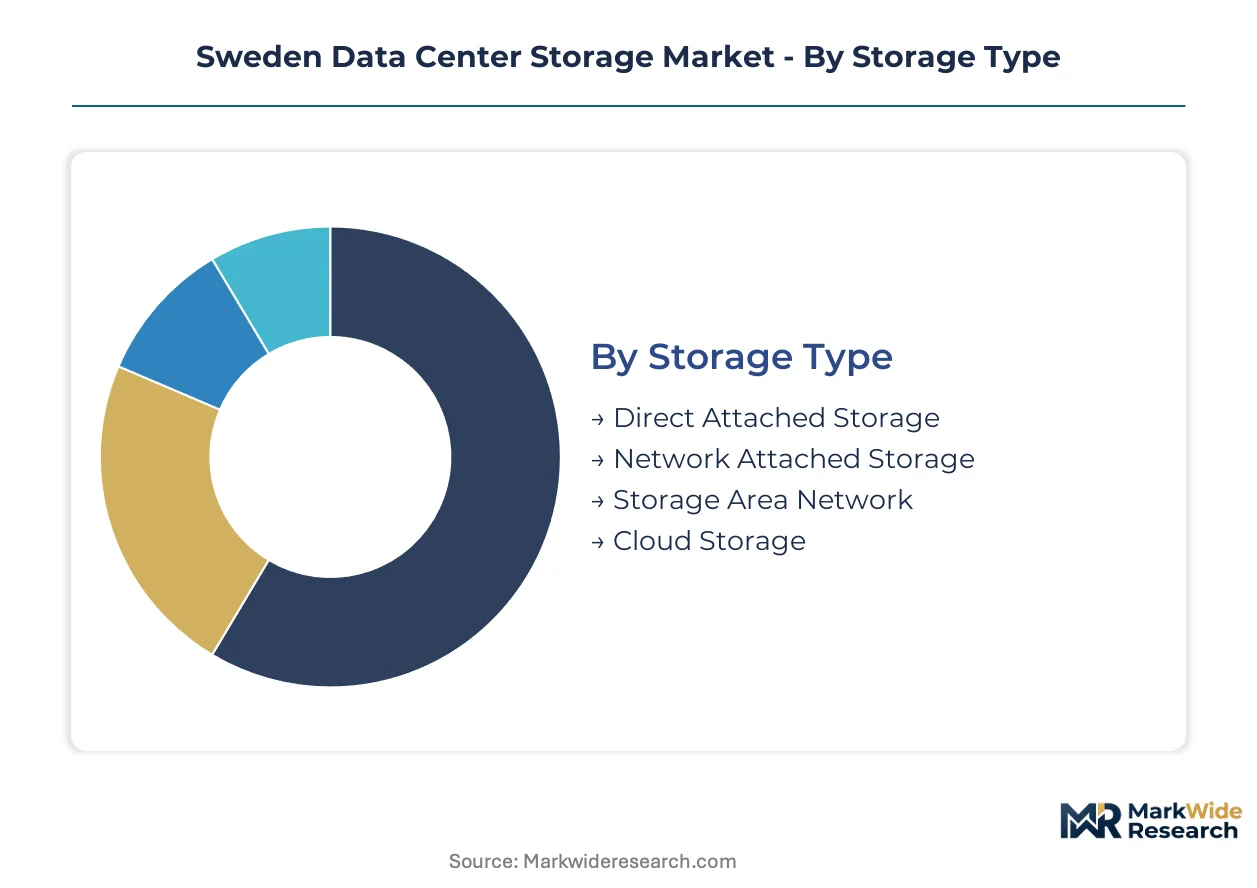
Storage procurement decisions in Sweden cluster around latency requirements, carbon intensity, and compliance architecture. Buyers weigh these factors differently across deployment scales and workload types.
Storage Type:
Latency tolerance and capital efficiency separate buyer preferences across the four architectures.
- Direct Attached Storage:Local flash arrays deliver deterministic performance without network overhead. Swedish algorithmic trading clusters in Stockholm deploy these for sub-50-microsecond tick-to-trade execution where nanoseconds translate to profit capture.
- Storage Area Network:Fibre Channel and NVMe-over-Fabrics fabrics consolidate block storage across multiple compute hosts. Large enterprises with legacy mainframe footprints favor SAN architectures for their mature replication tooling and deterministic failover behavior.
- Network Attached Storage:File-level protocols serve general-purpose enterprise workloads and departmental shares. NFS and SMB implementations dominate midsize organizations consolidating siloed file servers.
- Cloud Storage:S3-compatible object tiers and managed block services shift operational burden to hyperscale operators. SaaS exporters leverage these for burst capacity without facility expansion.
Volume sits with Storage Area Network installations; growth tilts toward Cloud Storage as consumption-based procurement expands.
End User:
Procurement sophistication and compliance burden vary sharply across organizational types.
- Service Providers:Multi-tenant infrastructure demands elastic capacity with metered billing. Swedish cloud operators building AI training clusters drive NVMe procurement at scale, prioritizing density and power efficiency.
- Enterprises:Banking and manufacturing verticals balance legacy application support against cloud migration timelines. Hybrid storage fabrics bridge mainframe-era compliance tooling with modern analytics pipelines.
- Government:National agencies enforce sovereign data residency through accredited on-premises deployments. CSRD disclosure requirements now penetrate public sector procurement scorecards.
- Research Institutions:Scientific computing archives generate petabyte-scale unstructured growth. Object storage architectures capture this demand as national labs expand climate and genomics datasets.
Service Providers command the largest absolute capacity; Research Institutions are climbing the fastest as grant-funded AI initiatives multiply.
Deployment Model:
Control retention versus operational offload defines the architectural spectrum.
- Hybrid:Tiered data placement across on-premises flash and public cloud object pools. Financial services clusters deploy this model for regulatory data on-site with analytics burst to cloud.
- On-Premises:Fully captive infrastructure with direct hardware ownership and facility control. Government and defense-adjacent workloads mandate this architecture for classified data handling.
- Private Cloud:Dedicated resources within colocation or managed service frameworks. Enterprises seeking consumption economics without multi-tenant exposure favor this middle path.
- Public Cloud:Shared infrastructure with hyperscale operators managing all physical layers. Startups and SaaS exporters with variable workloads minimize capital commitment here.
On-Premises retains the installed base; Hybrid deployments are expanding most quickly as compliance and agility requirements converge.
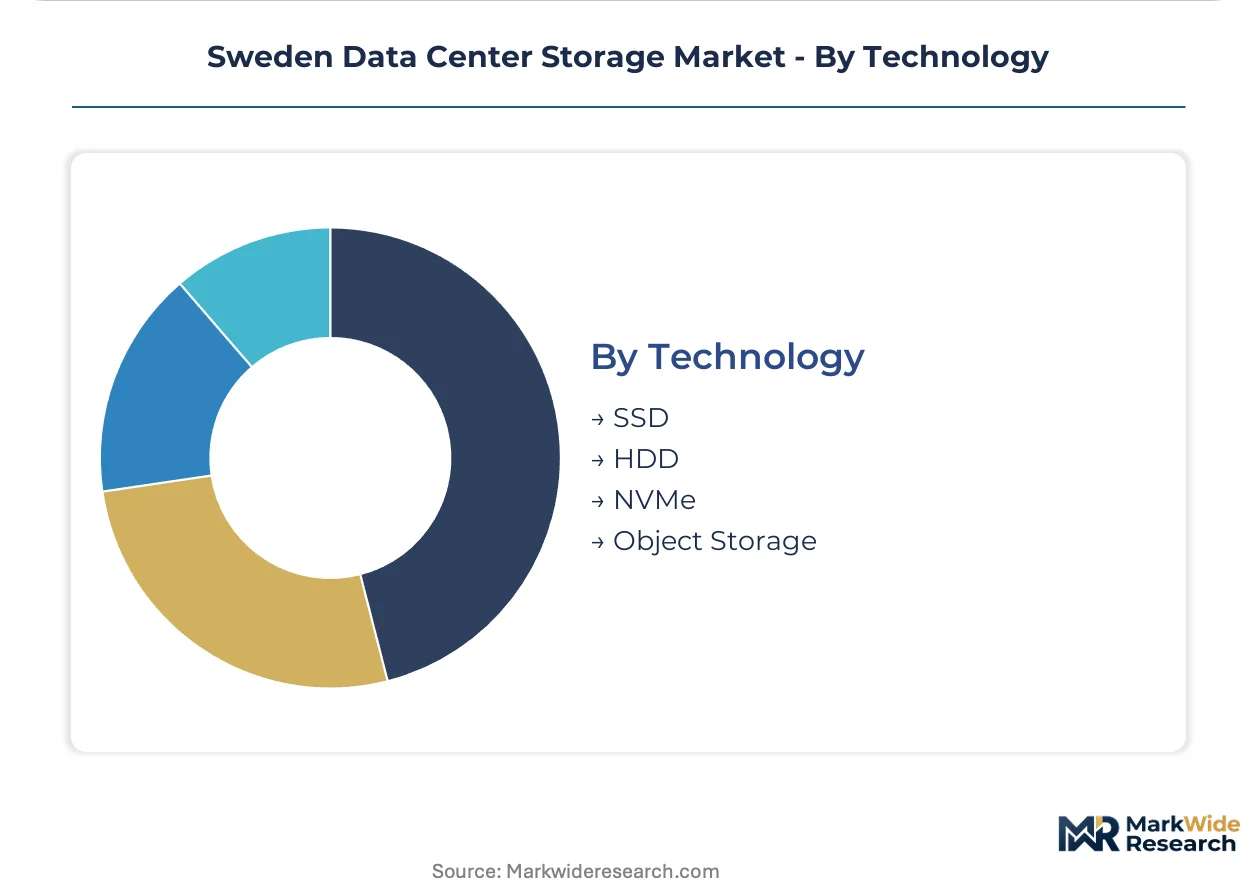
Technology:
Media physics and protocol efficiency determine performance ceilings and sustainability profiles.
- SSD:NAND-based solid-state drives dominate performance tiers with no moving parts and superior power efficiency. Swedish Energy Agency PUE reporting favors flash over mechanical alternatives.
- NVMe:PCIe-attached protocol eliminates SCSI translation overhead, delivering sub-100-microsecond latency. AI training pipelines and real-time analytics clusters specify NVMe as baseline infrastructure.
- HDD:Rotating magnetic media retains cost advantage for cold archival and sequential workloads. Capacity-optimized tiers still deploy high-density helium drives for infrequently accessed datasets.
- Object Storage:Flat namespace architectures scale to exabytes with erasure-coded durability. Media archives and scientific repositories adopt S3-compatible implementations for unstructured growth.
SSD commands current revenue concentration; NVMe is gaining share fastest as latency-sensitive workloads proliferate across Swedish data centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's data center corridor operates as Sweden's primary tax-advantaged zone for digital infrastructure, drawing international operators through subsidized renewable energy access and streamlined municipal permitting. This concentration pattern replicates across Nordic markets with varying regulatory intensities.
Norway
Hyperscale facility construction accelerates around Oslo and Stavanger as operators seek hydroelectric power at industrial tariffs. The Norwegian Water Resources and Energy Directorate enforces strict efficiency standards that favor flash storage deployments over legacy disk arrays. Lefdal Mine Datacenter anchors western Norway's expansion, converting former mineral extraction sites into underground server halls with natural cooling advantages.
Finland
AI training cluster demand surges near Helsinki as national research institutions expand supercomputing partnerships with cloud operators. Finnish Energy Authority carbon reporting requirements mandate PUE disclosure for facilities exceeding 500kW capacity. The CSC Kajaani datacenter complex drives northern Finland's emergence as a cold-climate computing hub with direct district heating integration.
Denmark
Pharmaceutical and life sciences verticals dominate Copenhagen's enterprise storage procurement as Novo Nordisk scales computational biology pipelines. Danish Business Authority CSRD implementation timelines compress infrastructure refresh cycles for publicly listed firms. Fredericia's industrial park hosts Facebook's Nordic facility, establishing a secondary corridor outside capital region constraints.
Germany
Frankfurt's banking infrastructure creates cross-border demand spillover into Swedish facilities as Bafin regulatory timelines extend domestic deployment schedules. German Energy Efficiency Act mandates for data centers intensify interest in Nordic cooling advantages. Deutsche Börse's proximity drives latency-sensitive storage specifications that Swedish operators replicate for algorithmic trading clients.
Sweden Data Center Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated systems vendors commanding premium tiers while component suppliers capture replacement cycle volumes. Market structure tilts toward consolidation at the high-performance tier where NVMe protocol expertise creates technical moats. Three archetypes dominate: full-stack infrastructure vendors, storage-focused specialists, and electrical infrastructure integrators. Capacity expansion and sustainability certification partnerships constitute the primary competitive vectors as operators race to meet PUE disclosure deadlines.
Among US-based systems vendors, Dell Inc., Hewlett Packard Enterprise, and NetApp Inc. exemplify differentiated positioning archetypes within the Swedish market. Dell Inc. occupies a position representing direct-attached storage integration for financial services clusters. Hewlett Packard Enterprise exemplifies the hybrid cloud platform approach through consumption-based service models. NetApp Inc. anchors the cloud-adjacent specialist tier, serving SaaS exporters with software-defined architectures. These three entities collectively represent the spectrum of procurement models now displacing traditional capital-intensive refresh cycles.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| Schneider Electric |
| ABB |
| Vertiv |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
NVMe protocol adoption across Swedish financial services clusters compresses both procurement economics and supplier concentration toward flash-specialized vendors. The Swedish Energy Agency's PUE reporting standards simultaneously elevate energy efficiency specifications and narrow the qualified vendor pool, reshaping how buyers negotiate capacity contracts.
Pricing Analysis
Short-lead-time premiums dominate Swedish data center storage procurement as BIS certification delays extend standard delivery windows by months. Three-tier pricing structure across premium, standard, and economy levels separates NVMe arrays with sub-50-microsecond latency from SATA SSD tiers and residual HDD archival capacity. Cost compression in mechanical drive segments is intensifying because PUE reporting disadvantages power-intensive disk arrays. Cloud service providers building AI training clusters show lowest price sensitivity; midsize enterprises consolidating legacy file servers exhibit highest.
Supply Chain Analysis
Reverse-logistics flows for decommissioned storage hardware remain underdeveloped across Nordic markets, constraining circular economy participation and secondary market liquidity. NAND fabrication concentrates in South Korea, Taiwan, and Japan; controller silicon sources from Taiwan and USA foundries. Single-source vulnerability in advanced node semiconductor supply exposes Swedish operators to allocation risk during demand spikes. Distribution runs through Stockholm-based systems integrators with direct vendor relationships, bypassing traditional distribution layers for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish data center storage market consolidation accelerates as EU AI Act compliance costs force sub-scale operators toward exit. PUE reporting mandates and certification friction disproportionately burden smaller vendors lacking dedicated regulatory affairs capacity.
For Market Incumbents: Deepen vertical integration into controller firmware and cooling system design to capture PUE optimization value that compliance-driven buyers now mandate. Acquire specialist object-storage engineering teams to serve national research institution demand. Threat: Hyperscale cloud operators expanding direct Stockholm facility investments bypass traditional vendor channels. For New Entrants and Emerging Players: Begin with Gothenburg secondary cluster deployments where land and power constraints lag Stockholm severity, offering price-competitive alternatives to capital-constrained enterprises. Target research institution object storage procurement with S3-compatible architectures and transparent carbon accounting. Go-to-market: Direct engagement with CSC and national lab grant administrators. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to electrical infrastructure integrators seeking storage software capabilities. Long-term viability centers on vendors with certified EU AI Act documentation systems and established Swedish Energy Agency PUE audit relationships. Acquisition target archetype: NVMe-over-Fabrics specialists with Stockholm banking cluster references. Signal to watch: Accelerated hyperscale facility announcements in western Sweden indicating demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Reuse Datacenter Design | Swedish Energy Agency subsidies pair flash storage with district heating integration. |
| EU AI Act Certification Investment | Documentation systems for training-data repositories differentiate compliant vendors. |
| Gothenburg Facility Expansion | Secondary corridor capacity captures Stockholm-constrained demand migration. |
| Consumption-Based Service Transition | GreenLake-style platforms transfer capacity planning risk from operators to vendors. |
| Object Storage Architecture Development | S3-compatible systems serve national research institution unstructured data growth. |
Research Methodology
Multi-period observation of hyperscale facility announcements, PUE disclosure filings, and NVMe procurement volumes anchored the trend analysis, supplemented by interviews with data center infrastructure executives, cloud procurement officers, and Swedish Energy Agency compliance leads. Secondary validation drew from SEC 10-K filings, EU CSRD implementation guidance, and hyperscaler capex disclosures. Bottom-up capacity installation tracking and top-down market sizing triangulated volume estimates across deployment models.
Segment-weighting approaches distributed value projections across storage type, end user, deployment model, and technology dimensions throughout the forecast period. CAGR derivation incorporated technology transition curves for SSD displacement of HDD, regulatory compliance cost trajectories, and hyperscale facility investment pipelines. AI training workload intensity and EU AI Act implementation timelines served as primary demand-side forecast inputs.
Underlying measurement precision varies by segment; hyperscale facility deployments carry tighter precision than distributed enterprise installations due to disclosure requirements. Forecasts reflect assumptions regarding NAND supply elasticity, BIS certification processing timelines, and EU AI Act enforcement intensity. Material deviation in hyperscale investment commitments or NAND supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Network File System Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Storage Software Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Global in-Memory Database Market