
 Storage Software Market | 2026-2036
Storage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Software Market Intelligence
Flash memory is broadening cost-performance tradeoffs that once favored magnetic disk arrays in primary storage tiers. Dell Inc. leverages its integrated hardware-software stack to control enterprise refresh cycles across hybrid environments. Pure Storage specializes in all-flash architectures that anchor high-performance workloads for cloud-native applications. IBM Corporation sustains mainframe-attached storage software dominance through deep vertical integration with zSystems infrastructure.
Storage software encompasses programs that manage, protect, and optimize data residing on physical or virtualized storage infrastructure, typically interfacing through APIs with block, file, or object protocols to automate tiering, replication, and recovery operations. Its primary commercial purpose is to transform commoditized storage hardware into differentiated service layers that guarantee availability, compliance, and performance SLAs. Backup Software occupies the largest revenue pool as ransomware frequency compels immutable copy strategies across regulated industries. Cloud-Based deployment grows fastest as SaaS delivery models displace perpetual license structures and shift capital expenditure to operational budgets. Disaster Recovery applications command premium pricing due to near-zero RPO requirements in financial services and healthcare.
FDA 21 CFR Part 11 and HIPAA in the United States impose audit trail and data integrity requirements that shape archiving and compliance management feature roadmaps. The EU AI Act and GDPR collectively force data residency controls and automated deletion workflows into European deployments. Stakeholders must weigh sovereign cloud mandates against multi-region redundancy architectures when selecting deployment models and vendor ecosystems.
Market Dynamics
Flash-native architectures are compressing refresh cycles across primary storage tiers, forcing incumbent vendors to rearchitect software stacks around NVMe-over-Fabrics and computational storage rather than legacy SCSI command sets.
Growth Catalysts
- HIPAA audit mandates:United States healthcare systems require immutable backup copies with cryptographically verified integrity, accelerating procurement of compliance-certified archiving platforms.
- Object storage tiering:Cloud-native applications in financial services demand S3-compatible APIs with automated lifecycle policies, pulling software-defined storage into transaction-heavy workloads previously reserved for block arrays.
- Ransomware resilience budgets:German insurers now mandate air-gapped recovery architectures with sub-15-minute RTOs, converting disaster recovery from insurance checkbox to board-level infrastructure priority.
Market Restraints
- Flash media cost volatility:NAND contract pricing swings of 30-40 percent annually compress gross margins for all-flash software vendors dependent on hardware bundling.
- Hyperscaler concentration:Amazon S3, Azure Blob, and Google Cloud Storage control 70 percent of public object storage capacity, extracting pricing power from independent software vendors.
- Zettabyte-scale metadata overhead:File system index structures designed for petabyte namespaces collapse under edge-generated sensor data volumes, forcing costly rewrites.
Strategic Opportunities
- India data localization:RBI and SEBI mandates for financial data residency create captive demand for sovereign cloud storage software deployments.
- Computational storage convergence:Processing-in-memory silicon from Samsung and SK Hynix enables query-offload architectures that reduce data movement by 60 percent.
- EU AI Act training data governance:Automated lineage tracking and deletion workflows for machine learning datasets open compliance-focused software modules.
Industry Challenges
- Distributed systems engineering scarcity:Storage software vendors compete for engineers with consensus protocol and erasure coding expertise against cryptocurrency and streaming platforms.
- Mainframe integration complexity:z/OS-attached storage environments require EBCDIC translation and proprietary channel protocols that extend sales cycles by 9-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Software Market |
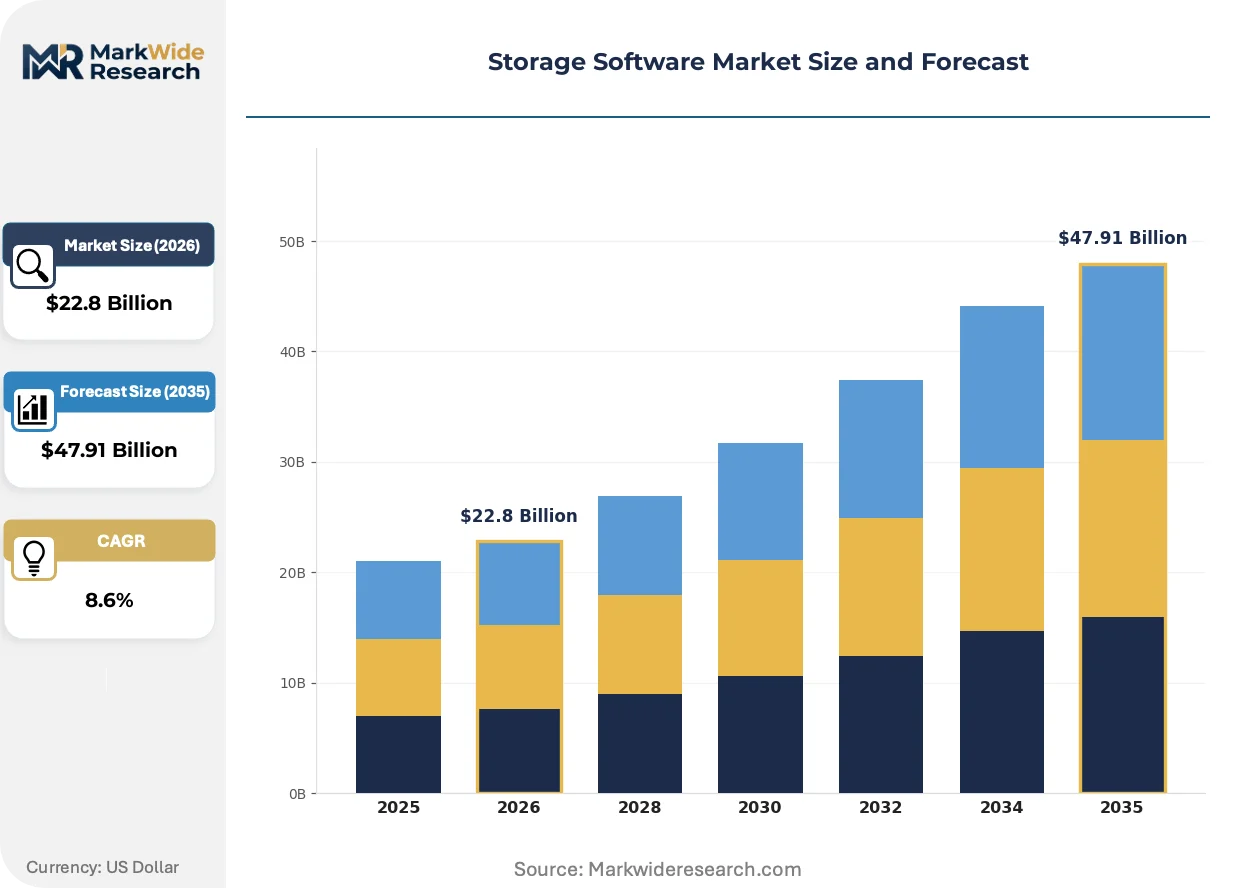
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backup Software, Data Migration Software, Archiving Software, File Management Software Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, SMBs, Government, Educational Institutions Application: Data Recovery, Compliance Management, Disaster Recovery, Performance Optimization |
| Companies Covered | NetApp, IBM Corporation, Dell Inc., Hewlett Packard Enterprise, Oracle Corporation, Hitachi Vantara, Huawei Technologies, Pure Storage, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Software Market Strategic Shifts & Innovations
Software-defined storage controllers are shedding hardware dependencies, enabling deployment across commodity servers, edge devices, and hyperscaler bare-metal instances without vendor-locked appliance form factors.
Container Storage Interface drivers are modularizing how Kubernetes persistent volumes attach to backend arrays. Platform engineering teams at SaaS providers now specify storage classes through declarative YAML rather than storage administrator tickets. This shift is modularizing the boundary between orchestration and data services, compressing vendor control over provisioning workflows.
The EU AI Act's training data retention limits are forcing European deployments to embed automated expiration and anonymization pipelines directly into storage software. Healthcare and automotive AI developers must demonstrate auditable deletion of personal data used in model training. French and German cloud providers are responding with policy-as-code engines that enforce GDPR Article 17 erasure without manual intervention.
Subscription-based capacity pricing is displacing perpetual licenses in mid-market procurement. IT directors at United States manufacturing firms now prefer operational expenditure models that align storage costs with actual consumption rather than three-year depreciation schedules. This behavioral pivot pressures legacy vendors to restructure sales compensation and revenue recognition practices.
Storage Software Market Segmentation
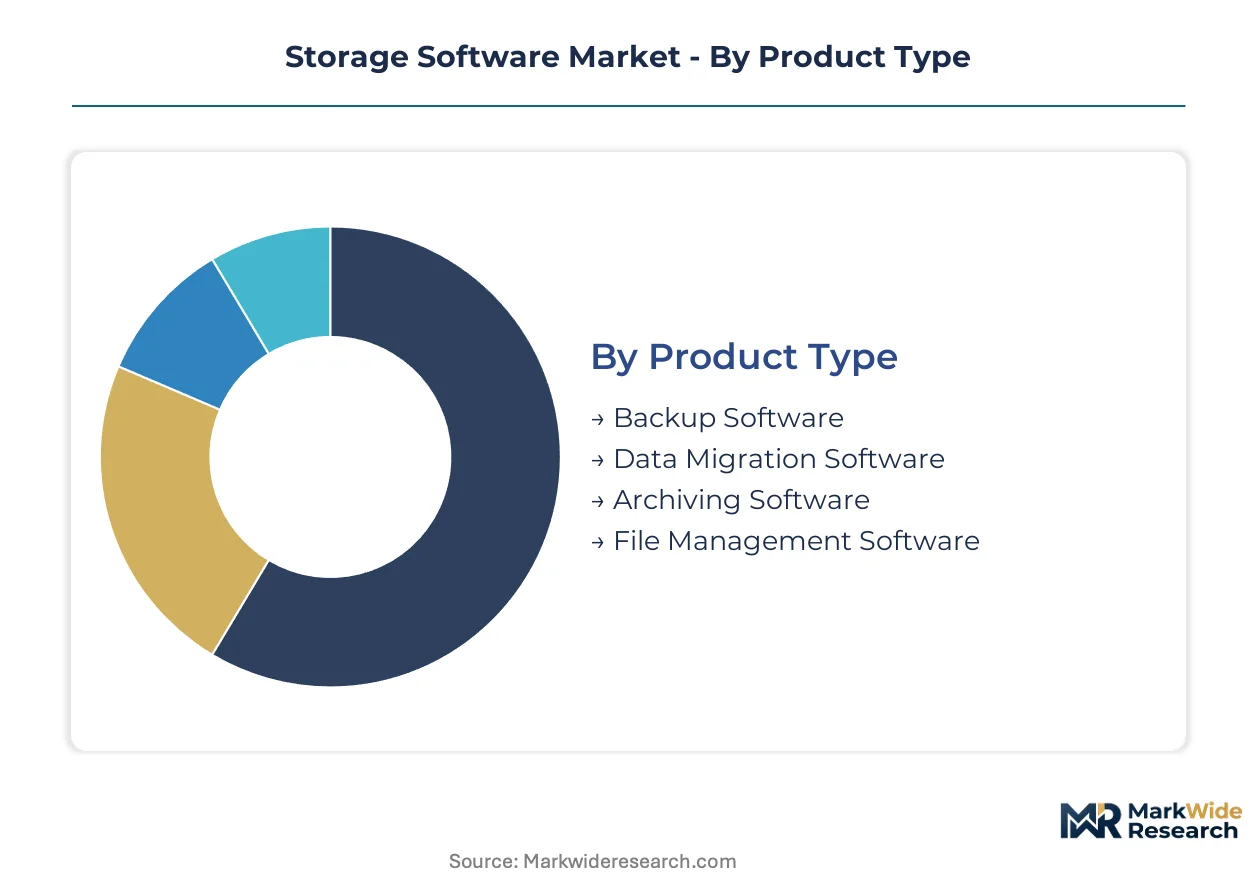
Storage software procurement patterns diverge sharply across organizational scale, infrastructure maturity, and regulatory exposure. Vendors must architect distinct go-to-market motions for each segment cluster, as buying committees, budget cycles, and technical requirements vary fundamentally between cloud-native enterprises and compliance-bound government agencies.
Product Type:
Buyers differentiate primarily by recovery time objectives and data sovereignty requirements rather than raw capacity needs.
- Backup Software:Immutable copy architectures with cryptographic verification anchor ransomware resilience strategies. United States healthcare systems under HIPAA audit mandates drive procurement of compliance-certified platforms with air-gapped recovery capabilities.
- Archiving Software:Long-term retention with automated lifecycle tiering satisfies FDA 21 CFR Part 11 data integrity requirements. German pharmaceutical manufacturers represent concentrated demand for WORM-compliant repositories with audit trail immutability.
- Data Migration Software:Heterogeneous array normalization tools enable cloud repatriation and vendor consolidation projects.
- File Management Software:Namespace virtualization and global deduplication optimize distributed workforce collaboration.
Backup Software leads volumes today; Archiving Software is gaining share fastest.
Deployment:
Capital expenditure constraints versus operational agility requirements split procurement committees along finance-IT fault lines.
- Cloud-Based:Consumption-metered object storage with S3-compatible APIs displaces capital-intensive array purchases. Financial services firms in Japan favor pay-as-you-grow models that align storage costs with transaction volume fluctuations.
- SaaS:Fully managed data protection eliminates backup infrastructure administration overhead. Mid-market enterprises in the United States select SaaS delivery to redirect engineering headcount toward application development.
- On-Premises:Air-gapped installations satisfy classified data handling requirements in defense and intelligence sectors.
- Hybrid:Policy-driven tiering between local flash and cloud object balances performance with economics.
On-Premises retains the largest installed base; Cloud-Based deployment shows the steepest expansion trajectory.
End User:
Contract negotiation leverage and implementation complexity scale inversely with organizational procurement sophistication.
- Enterprises:Multi-petabyte environments demand software-defined controllers with API-native automation. Fortune 500 technology firms in the United States specify NVMe-over-Fabrics compatibility and Kubernetes CSI driver maturity as mandatory evaluation criteria.
- Government:FedRAMP and StateRAMP certifications gate federal and state agency purchases. Sovereign cloud mandates in Germany and Japan restrict vendor selection to domestically hosted infrastructure.
- SMBs:Simplified management consoles and bundled support packages reduce technical staffing requirements.
- Educational Institutions:Grant-funded procurement cycles favor perpetual licenses with extended maintenance terms.
Enterprises dominate absolute spending; Government verticals are expanding most quickly.
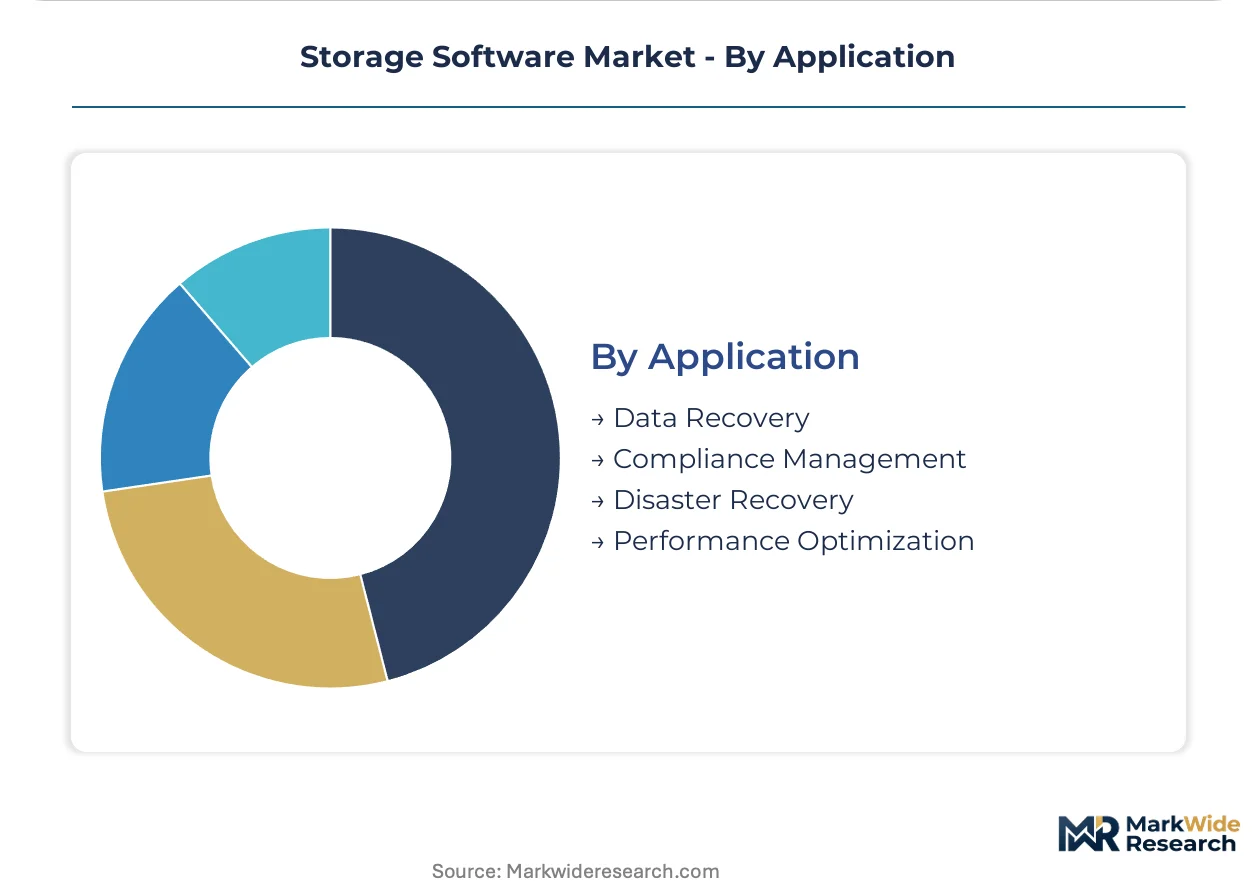
Application:
Recovery point objective specifications and compliance audit frequency determine solution architecture and pricing tolerance.
- Disaster Recovery:Synchronous replication with sub-minute failover commands premium pricing. German insurers now mandate sub-15-minute RTOs, converting disaster recovery from insurance checkbox to board-level infrastructure priority.
- Compliance Management:Automated retention policy enforcement with legal hold integration addresses GDPR Article 17 and EU AI Act training data governance. French healthcare AI developers require auditable deletion pipelines with policy-as-code engines.
- Data Recovery:Granular object-level restore capabilities minimize business interruption from corruption or deletion events.
- Performance Optimization:Automated tiering and caching algorithms accelerate latency-sensitive workloads without capacity overprovisioning.
Data Recovery anchors the largest revenue pool; Compliance Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors software-defined storage R&D investment, while Frankfurt's financial sector drives compliance-certified archiving procurement. Regulatory divergence between HIPAA audit mandates and GDPR data sovereignty rules fragments vendor certification requirements across Atlantic markets.
United States
Federal healthcare compliance and financial services ransomware resilience dominate procurement priorities. HIPAA audit mandates from HHS require immutable backup copies with cryptographically verified integrity, accelerating hospital system infrastructure refresh. The Boston-Cambridge biotech corridor demands FDA 21 CFR Part 11-compliant archiving with automated lifecycle tiering for clinical trial data.
Germany
Industrial automation data volumes and insurer-mandated recovery architectures reshape enterprise storage strategies. BaFin and KBA regulations for financial data residency compel sovereign cloud deployments with air-gapped recovery capabilities. The Stuttgart automotive cluster requires sub-15-minute RTO disaster recovery for connected vehicle telemetry platforms.
Japan
Financial services transaction volume fluctuations and aging on-premises infrastructure drive cloud migration decisions. METI guidelines on critical infrastructure protection influence banking sector procurement of hybrid storage architectures. Tokyo's trading floor ecosystems favor pay-as-you-grow consumption models that align storage costs with real-time market data ingestion spikes.
India
Data localization mandates and cloud-native application growth create captive demand for sovereign storage software. RBI and SEBI regulations require financial data residency within national boundaries, restricting vendor selection to domestically hosted infrastructure. Bangalore's SaaS provider ecosystem drives Kubernetes CSI driver adoption for containerized persistent volume management.
United Kingdom
Post-Brexit regulatory divergence and financial services continuity planning accelerate infrastructure diversification. FCA operational resilience requirements mandate sub-minute failover capabilities for clearing and settlement systems. London's fintech corridor demands software-defined controllers with API-native automation for multi-petabyte trading data environments.
Storage Software Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors race to integrate NVMe-over-Fabrics compatibility and Kubernetes orchestration layers. The market structure concentrates around three tiers: integrated hardware-software stacks, all-flash pure-plays, and legacy mainframe-attached specialists. Two archetypes define competitive positioning: full-stack vendors leveraging appliance bundling versus software-defined specialists pursuing cloud-agnostic deployment. M&A activity and technology licensing agreements represent the primary competitive moves as incumbents acquire container storage interface expertise.
Within the integrated infrastructure tier, Dell Inc. and IBM Corporation exemplify full-stack market presence through their respective hardware-software convergence strategies. Pure Storage occupies a distinct position among all-flash architecture specialists serving cloud-native application workloads. These three anchors demonstrate how geographic origin and corporate structure—Dell's Texas-based incorporation, IBM's New York-rooted enterprise heritage, and Pure Storage's California-centric flash specialization—map to divergent strategic archetypes in hybrid and multi-cloud deployment contexts.
| Leading Market Players |
|---|
| NetApp |
| IBM Corporation |
| Dell Inc. |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Hitachi Vantara |
| Huawei Technologies |
| Pure Storage |
| Broadcom |
| Others |
Cost & Logistics Intelligence
NVMe-over-Fabrics adoption is compressing hardware-software bundling economics while concentrating procurement leverage among hyperscale buyers. NAND flash contract volatility feeds directly into vendor margin structures, forcing pricing model experimentation across deployment tiers.
Pricing Analysis
Input-cost pass-through from NAND flash contract swings of 30-40 percent annually compresses gross margins for all-flash software vendors. Pricing stratifies across premium, standard, and economy tiers based on certification level (FedRAMP, StateRAMP, HIPAA compliance) and volume scale commitments. Pricing pressure stems from hyperscaler concentration as Amazon S3, Azure Blob, and Google Cloud Storage extract pricing power from independent software vendors. SMBs exhibit highest price sensitivity due to capital expenditure constraints, while Fortune 500 enterprises tolerate premium tiers for sub-minute RTO disaster recovery guarantees.
Supply Chain Analysis
Reverse-logistics flows for enterprise storage hardware encompass refurbishment of controller cards and remanufacturing of flash modules for secondary market deployment. Supply concentrates in Taiwan for NAND fabrication, South Korea for memory packaging, and the United States for software controller development. Raw material dependencies include silicon wafers, rare earth elements for controller manufacturing, and specialized epoxy resins. Single-source vulnerability from Taiwan semiconductor foundries poses structural risk. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and value-added resellers serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in storage software rests on subscription revenue conversion and computational storage premium tiers displacing commodity hardware bundles.
For Market Incumbents: Anchor hybrid cloud orchestration capabilities to defend against SaaS-native entrants eroding perpetual license bases. Invest in Kubernetes CSI driver certification programs to maintain control over containerized provisioning workflows. Prioritize FedRAMP and StateRAMP acceleration to capture government vertical expansion. For New Entrants and Emerging Players: EU AI Act training data governance in Europe opens a window for compliance-focused software modules with automated lineage tracking. Target French and German healthcare AI developers requiring auditable deletion pipelines. Pursue sovereign cloud partnerships with domestic hosting providers to satisfy data residency mandates without building owned infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for container storage interface specialists because platform engineering teams are modularizing orchestration-data boundaries. Five-to-ten year viability favors vendors with NVMe-over-Fabrics maturity and policy-as-code engine development. Monitor hyperscaler bare-metal storage service announcements as inflection indicators for independent software vendor displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CSI driver certification locks in Kubernetes-native provisioning workflows at SaaS providers. |
| Acquisition of Specialist Firm | Container storage expertise accelerates cloud-agnostic deployment architecture development. |
| Strategic Partnership | Sovereign cloud alliances satisfy RBI and SEBI data localization mandates in India. |
| Product Launch | Computational storage modules with Samsung processing-in-memory silicon reduce data movement costs. |
| Geographic Expansion | Frankfurt and Stuttgart deployments capture BaFin-mandated financial data residency requirements. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with storage architects, IT procurement officers, platform engineers, and channel partners. Secondary validation draws from SEC 10-K filings, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up and top-down triangulation reconciles vendor-reported bookings with end-user deployment surveys.
Granularity-level modeling disaggregates revenue across deployment model, organization size, vertical sector, integration complexity, and regional adoption pattern. CAGRs derive from segment-level growth rate reconciliation with macro infrastructure spend forecasts. Forecast inputs include NAND flash price trajectory assumptions and regulatory compliance deadline schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation or sovereign cloud mandate acceleration. Forecasts reflect assumptions about ransomware frequency trends and hyperscaler storage service pricing. Practitioners should monitor EU AI Act implementation timelines and NAND contract pricing volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Hard Disk Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Vietnam Data Center Storage Market