
 Saudi Arabia Data Center Storage Market | 2026-2036
Saudi Arabia Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Storage Market Insights
Enterprise buyer concentration in Saudi Arabia's data center storage sector is consolidating around hyperscale cloud operators and government-backed digital infrastructure projects. Dell Technologies leverages its integrated server-storage portfolio to anchor major smart city deployments across the Kingdom. Huawei Technologies competes aggressively on flash storage density and localized assembly capabilities. Pure Storage differentiates through subscription-based consumption models tailored to Saudi enterprises transitioning from capital-heavy procurement.
Saudi Arabia data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention across enterprise and cloud environments, with flash arrays now achieving sub-millisecond latency below 100 microseconds and HDD systems scaling beyond 20 terabytes per spindle for archival tiers. The technology dimension shows flash storage commanding premium positioning for transactional workloads while hybrid configurations bridge cost-performance requirements for mid-market adopters. Deployment patterns reveal colocation gaining traction as Saudi Telecom Company and Mobily expand carrier-neutral facilities, though on-premises retains dominance in government and defense applications where the National Cybersecurity Authority imposes strict data residency controls.
SFDA guidelines for healthcare data archiving, CITC cloud certification requirements, and NCA cybersecurity controls collectively shape product specifications and vendor qualification pathways for storage systems deployed within Saudi territory. The National Data Management Office's classification framework mandates tiered storage architectures that align retention policies with sovereignty risk levels. Stakeholders must weigh localization incentives against supply chain lead times as the Kingdom's domestic manufacturing capacity for advanced storage components remains nascent.
Market Dynamics
The National Data Management Office's data sovereignty framework is compressing procurement cycles as Saudi enterprises accelerate on-premises flash storage deployment to meet residency mandates before certification deadlines.
Growth Catalysts
- Vision 2030 Digital Transformation:Saudi banks under BFSI modernization programs are replacing legacy tape archives with all-flash arrays for core banking workloads. Government-backed smart city initiatives in Riyadh and Jeddah are embedding petabyte-scale storage into municipal data infrastructure.
- CITC Localization Mandates:The Communications and Information Technology Commission's cloud certification requirements are redirecting hyperscale investment toward domestic facilities with localized storage hardware assembly.
- NVMe-over-Fabrics:This protocol architecture is collapsing storage network latency for transactional databases, with Saudi telecom operators deploying RDMA-enabled fabrics in carrier-neutral colocation facilities.
Market Restraints
- Flash Memory Supply Concentration:NAND fabrication capacity concentrates in East Asian foundries, exposing Saudi deployments to 16-20 week lead times for high-density enterprise SSDs during supply tightness.
- NCA Cybersecurity Controls:The National Cybersecurity Authority's hardware certification timelines extend vendor qualification cycles by 8-12 months for defense and critical infrastructure sectors.
- Skilled Technician Scarcity:Domestic labor pools lack sufficient storage architects certified on software-defined and disaggregated infrastructure platforms, forcing reliance on expatriate engineering contracts.
Strategic Opportunities
- Eastern Province Industrial Zones:Aramco and SABIC petrochemical complexes are generating untapped demand for edge storage nodes to process sensor telemetry from automated refining operations.
- SFDA Healthcare Archiving Rules:The Saudi Food and Drug Administration's 10-year retention mandates for electronic health records are creating specialized compliance storage procurement outside traditional IT budgets.
- Storage-as-a-Service Convergence:Subscription consumption models are integrating with managed security services, allowing regional systems integrators to displace direct OEM relationships in mid-market accounts.
Industry Challenges
- Legacy SAN Migration Complexity:Saudi enterprises running 15-year-old Fibre Channel infrastructures face forklift upgrade costs and application re-certification burdens when transitioning to NVMe-based platforms.
- Localization Supply Chain Reconfiguration:Vendors must rebuild component sourcing and final assembly workflows to satisfy NDMO domestic content thresholds without sacrificing time-to-delivery against Asian competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Storage Market |
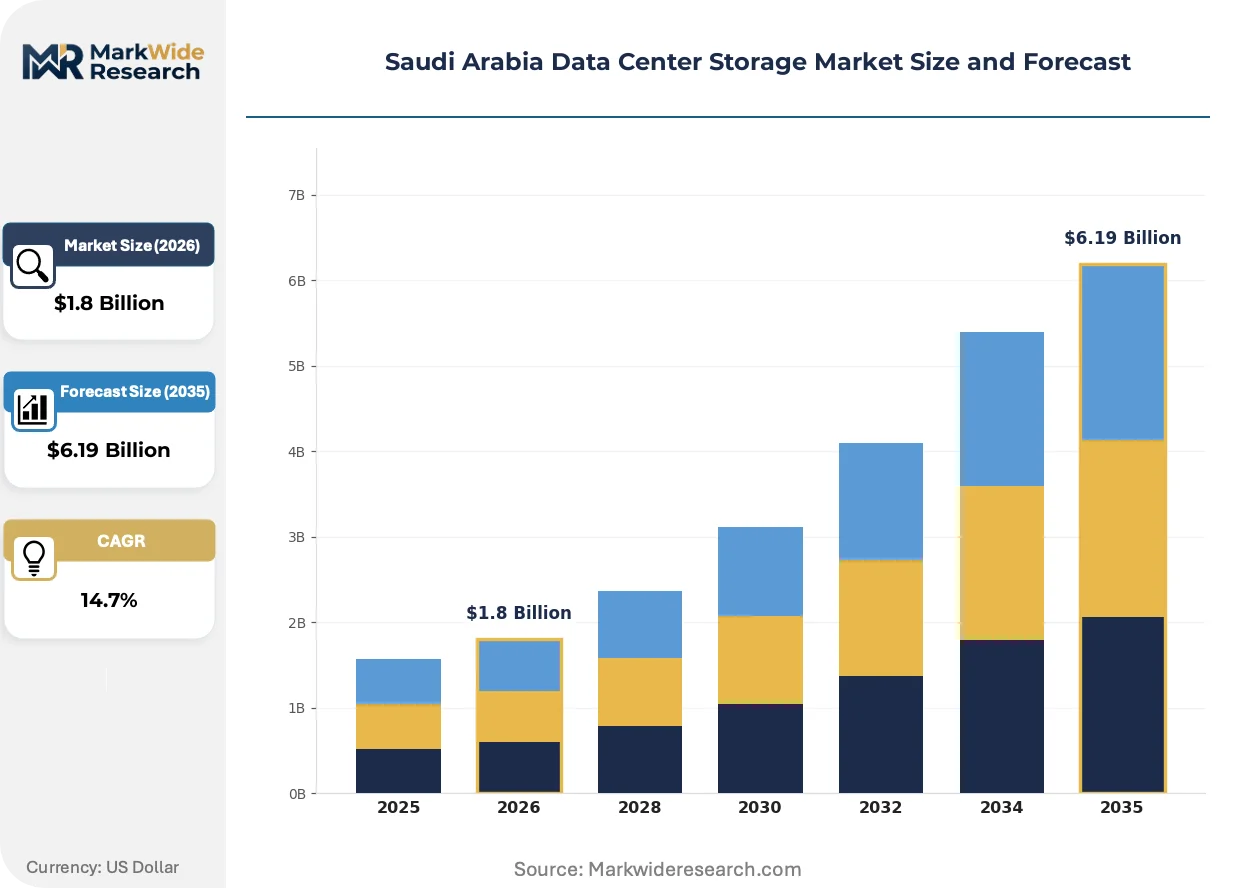
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Area Network, Network Attached Storage, Direct Attached Storage, Cloud Storage Technology: Flash Storage, Hard Disk Drive, Hybrid Storage, Object Storage End User: Telecommunications, Government, BFSI, Healthcare Deployment: On-premises, Hybrid, Colocation, Cloud |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM Corporation, Pure Storage, Hitachi Vantara, Huawei Technologies, Lenovo Group, Nutanix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Storage Market Trends and Innovations
Computational storage architectures and sovereign data frameworks are compressing the traditional separation between processing and persistence layers across Saudi enterprise infrastructure.
Computational storage drives with embedded processing capabilities are integrating directly into database query pipelines, allowing Saudi banks to push analytics operations to the storage layer rather than moving data to compute nodes. BFSI institutions in Riyadh are piloting these devices for real-time fraud detection workloads. This integration is collapsing the historical boundary between storage hardware and application logic, forcing infrastructure teams to acquire database engineering competencies.
The National Data Management Office's classification framework is mandating tiered storage architectures that align encryption standards and geographic replication with data sovereignty risk levels. Cloud service providers must now architect separate physical infrastructure zones for each classification tier. Government entities and defense contractors represent the most affected segments, with procurement specifications now requiring hardware-level attestation before contract award.
Consumption-based procurement is displacing capital-heavy storage acquisition as Saudi enterprises facing Vision 2030 transformation budgets prioritize operational expenditure flexibility. Managed service providers in Jeddah and Riyadh are capturing multi-year contracts that bundle hardware, software, and operational support into per-terabyte monthly rates. This shift is most visible in healthcare and education verticals where capital allocation cycles remain constrained despite archival data growth acceleration.
Saudi Arabia Data Center Storage Market Segmentation
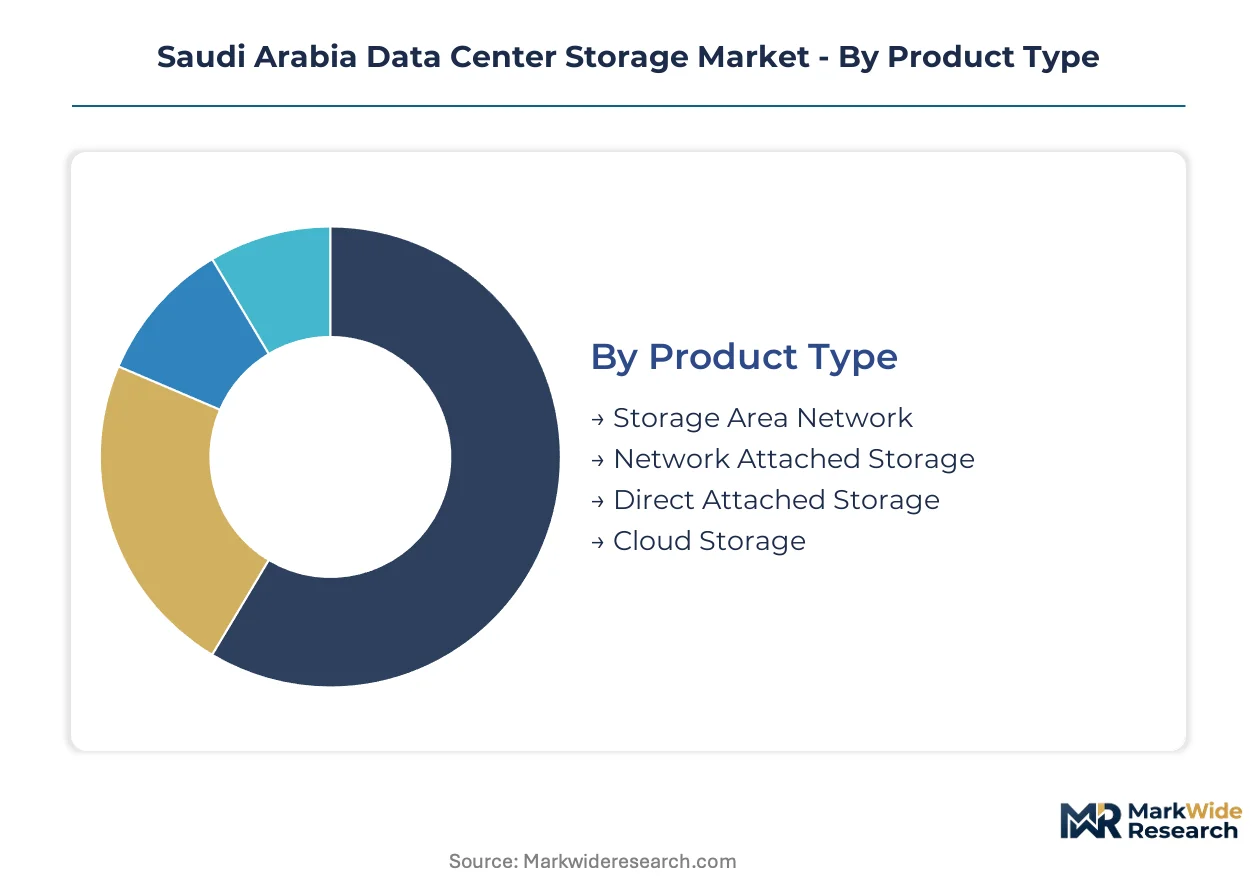
Storage procurement in Saudi Arabia fragments across architectural approaches, media technologies, and operational models. Understanding these divisions clarifies where Vision 2030 transformation budgets concentrate and which vendor configurations align with CITC localization mandates.
Product Type:
Upgrade cycles for legacy storage fabrics are accelerating as Saudi enterprises confront NVMe-over-Fabrics transitions and Fibre Channel obsolescence pressures.
- Storage Area Network:Fibre Channel and iSCSI fabrics engineered for block-level access across consolidated compute pools. Saudi banks under BFSI modernization programs are replacing 15-year-old SAN infrastructures with NVMe-enabled fabrics to meet sub-millisecond latency requirements for core banking workloads.
- Network Attached Storage:File-level storage systems serving unstructured data through NFS and SMB protocols. Healthcare institutions in Riyadh and Jeddah are deploying scale-out NAS clusters to satisfy SFDA electronic health record archiving mandates with 10-year retention guarantees.
- Direct Attached Storage:Internal or external drives connected directly to individual servers without network intermediation. Edge computing nodes in Aramco petrochemical facilities rely on DAS configurations for sensor telemetry processing.
- Cloud Storage:Consumption-based capacity delivered through hyperscale provider APIs or managed service overlays. STC Cloud and Mobily are expanding domestic availability zones to satisfy NDMO data sovereignty classification requirements.
Storage Area Network sits at the top of the volume ranking, with Cloud Storage climbing the fastest.
Technology:
Cost-performance positioning across media types determines procurement patterns for transactional versus archival workloads in Saudi enterprise infrastructure.
- Flash Storage:NAND-based solid-state systems delivering sub-100 microsecond latency for random read operations. Saudi banks are deploying all-flash arrays for real-time fraud detection, though NAND supply concentration in East Asian foundries exposes deployments to extended lead times.
- Hard Disk Drive:Electromechanical systems with spindle densities exceeding 20 terabytes for sequential access patterns. Government archives and surveillance systems in defense applications specify air-gapped HDD configurations to satisfy NCA cybersecurity hardware certification timelines.
- Hybrid Storage:Tiered architectures combining flash and HDD media with automated data placement algorithms. Mid-market enterprises facing capital constraints adopt hybrid configurations to bridge performance requirements and budget limitations.
- Object Storage:Flat-namespace architectures optimized for exabyte-scale unstructured data with erasure-coded durability. Smart city initiatives in Riyadh are embedding object storage for municipal video analytics and IoT sensor repositories.
Flash Storage commands the highest value concentration, with Object Storage expanding most quickly.
End User:
Customer type dictates procurement authority, budget cycles, and compliance overlay complexity across Saudi storage deployments.
- Telecommunications:STC, Mobily, and Zain operate carrier-neutral colocation facilities requiring petabyte-scale storage for subscriber data and content delivery caches. These operators are deploying NVMe-over-Fabrics in Riyadh and Jeddah metro facilities to collapse storage network latency.
- Government:Ministries and municipal authorities subject to NDMO classification frameworks and NCA cybersecurity controls. Defense contractors represent the most restrictive segment, requiring hardware-level attestation before contract award.
- BFSI:Banks and financial institutions under Vision 2030 digital transformation targets. Core system modernization programs are redirecting procurement toward all-flash configurations with sovereign data replication.
- Healthcare:Hospitals and clinics governed by SFDA archiving guidelines. Electronic health record retention mandates are creating specialized compliance storage procurement outside traditional IT capital cycles.
Telecommunications sits at the top of the volume ranking, with Healthcare climbing the fastest.
Deployment:
Operational model selection reflects sovereignty risk assessment, capital availability, and internal technical capability across Saudi organizations.
- On-premises:Fully owned infrastructure within facility-controlled environments. Government and defense applications retain this dominance where NCA imposes strict data residency controls and physical security requirements.
- Hybrid:Workload-distributed architectures spanning owned facilities and cloud resources. Enterprises are adopting hybrid configurations to balance sensitive data on-premises with burst capacity in CITC-certified domestic cloud zones.
- Colocation:Leased space in carrier-neutral facilities with customer-managed hardware. STC and Mobily facility expansions in Riyadh and Jeddah are capturing enterprise migrations from aging owned data centers.
- Cloud:Fully managed capacity with operational expenditure treatment. Healthcare and education verticals are prioritizing cloud consumption models where capital allocation cycles remain constrained.
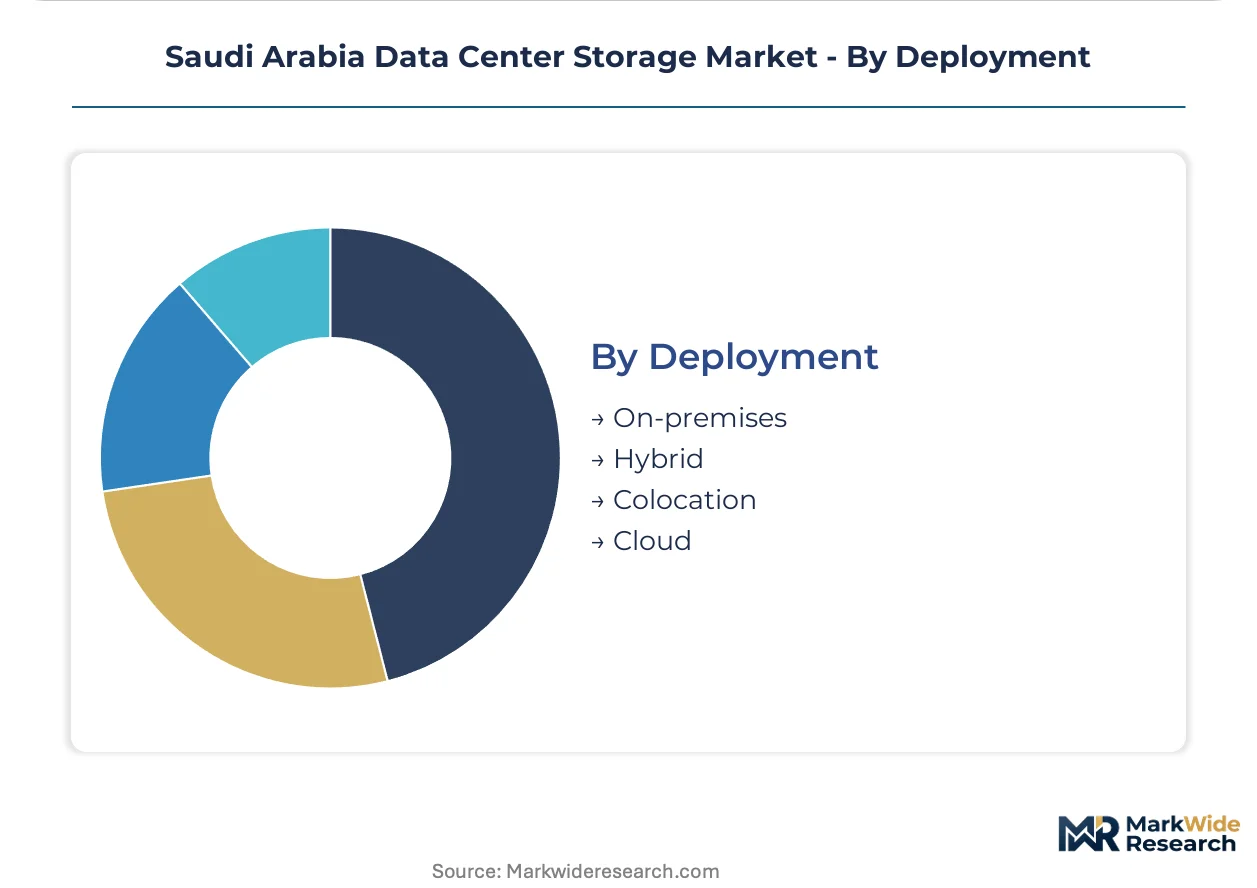
On-premises sits at the top of the volume ranking, with Hybrid climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia outpaces Gulf neighbors in storage infrastructure deployment velocity, while the UAE concentrates more hyperscale cloud capacity per capita. Both markets operate under distinct data sovereignty frameworks that reshape vendor qualification pathways.
Riyadh
Capital region ministries and financial institutions drive petabyte-scale flash storage procurement under Vision 2030 digital transformation mandates. The National Data Management Office's classification framework imposes tiered encryption standards on government data centers. Smart city infrastructure in King Abdullah Financial District embeds NVMe-over-Fabrics networks for municipal analytics.
Eastern Province
Aramco and SABIC petrochemical complexes generate specialized demand for edge storage nodes processing industrial sensor telemetry. The National Cybersecurity Authority extends hardware certification timelines for critical infrastructure operators. Dhahran Techno Valley clusters host defense contractor facilities requiring air-gapped HDD configurations.
Western Region
Jeddah's commercial hub concentrates healthcare and logistics sector storage procurement subject to SFDA archiving guidelines. CITC cloud certification requirements redirect hyperscale investment toward carrier-neutral colocation facilities. King Abdulaziz International Airport's smart logistics zone deploys object storage for cargo tracking systems.
NEOM Northwest
The giga-project's cognitive city blueprint mandates exabyte-scale sovereign data infrastructure with localized hardware assembly. NDMO domestic content thresholds force supply chain reconfiguration for participating vendors. THE LINE's linear urban corridor will embed computational storage architectures for real-time municipal AI workloads.
Saudi Arabia Data Center Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's data center storage sector. The vendor base clusters around three strategic archetypes: integrated infrastructure conglomerates with server-storage portfolios, flash storage specialists with subscription consumption models, and Chinese manufacturers with localized assembly capabilities. Competitive positioning hardens through CITC localization mandates and NDMO domestic content requirements. Market participants pursue strategic partnerships with Saudi Telecom Company and Mobily while expanding Riyadh and Jeddah service capabilities.
Among US-based technology conglomerates, Dell Technologies and Hewlett Packard Enterprise occupy positions anchoring enterprise and government segments through integrated server-storage portfolios. Pure Storage exemplifies the subscription-model specialist archetype targeting Saudi enterprises transitioning from capital-heavy procurement cycles. Huawei Technologies represents the localized manufacturing tier competing on flash storage density and domestic assembly compliance.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM Corporation |
| Pure Storage |
| Hitachi Vantara |
| Huawei Technologies |
| Lenovo Group |
| Nutanix |
| Others |
Pricing and Supply Chain Analysis
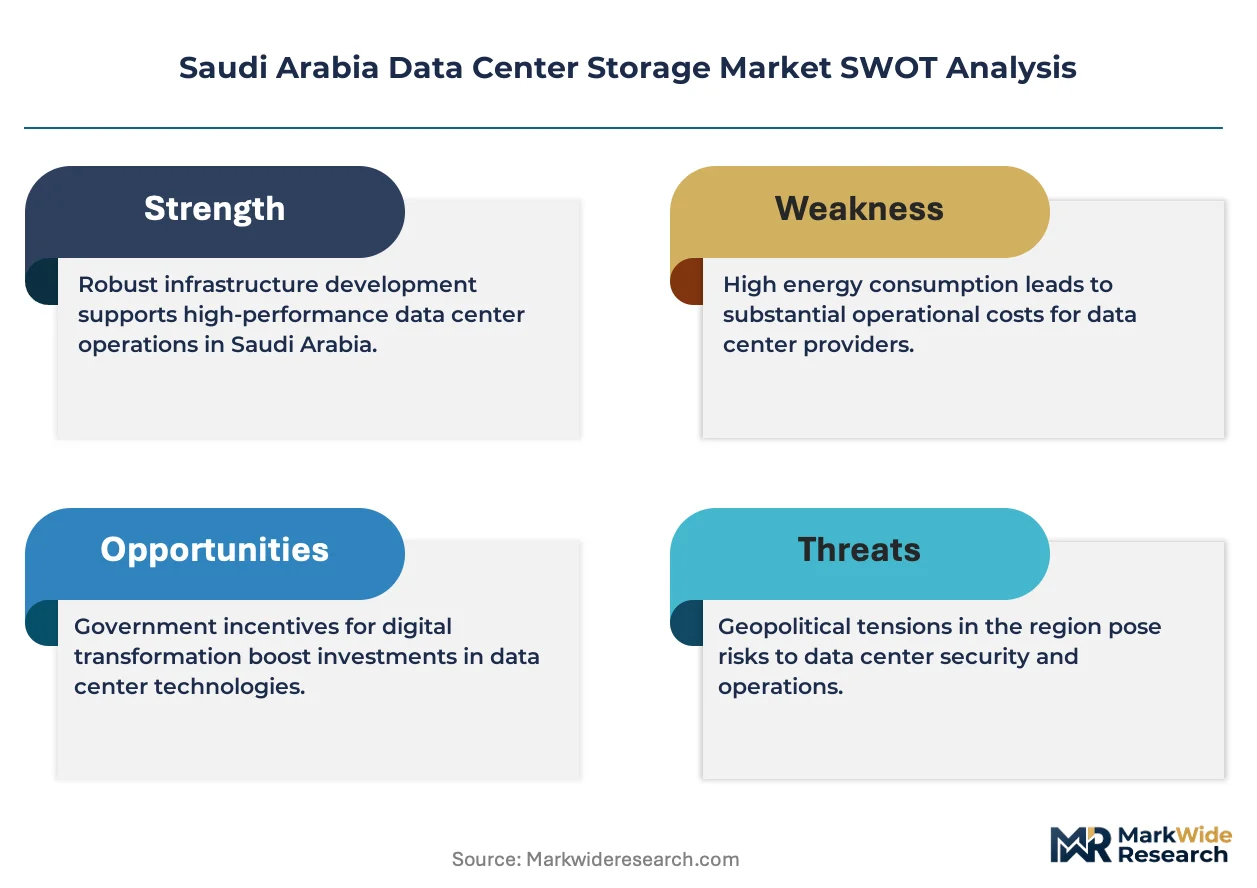
NDMO domestic content thresholds gate qualified supply access and premium-tier pricing eligibility for vendors serving Saudi government and defense contracts. CITC localization mandates compress procurement timelines while extending vendor qualification cycles, creating tiered market access where certified assemblers capture price premiums over import-dependent competitors.
Pricing Analysis
Capacity additions in Riyadh and Jeddah carrier-neutral facilities are reshaping price floors for colocation storage services. Three-tier pricing structure across premium, standard, and economy levels separates NVMe-enabled flash arrays with sovereign data replication from hybrid configurations and archival HDD tiers. Cost compression in standard-tier hybrid storage is intensifying because Chinese manufacturers with localized assembly capabilities are undercutting integrated infrastructure conglomerates on acquisition cost. Healthcare and education verticals exhibit highest price sensitivity due to constrained capital allocation cycles, while defense contractors show lowest sensitivity given NCA hardware certification requirements.
Supply Chain Analysis
Freight costs from East Asian NAND foundries to Jeddah Islamic Port add significant landed cost premiums for high-density enterprise SSDs. Component sourcing concentrates in South Korea, Taiwan, and China for flash memory controllers, NAND wafers, and HDD spindle motors. Raw material dependencies span rare earth elements for magnet assemblies, high-purity silicon for semiconductor fabrication, and specialized aluminum alloys for drive enclosures. Single-source vulnerability runs through East Asian controller ASIC suppliers, with distribution running through STC and Mobily logistics networks for domestic final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia data center storage functions as a stable compounder anchored by irreversible sovereign data localization mandates. Vision 2030 transformation budgets provide sustained demand visibility regardless of global technology capital expenditure cycles.
For Market Incumbents: Anchor government relationships through NDMO tiered classification compliance investments before certification deadlines compress procurement windows. Defend against Chinese manufacturers by deepening backward integration into localized flash assembly capabilities. Prioritize Riyadh and Jeddah service center expansion to match Huawei's domestic technical support footprint. For New Entrants and Emerging Players: The gap between premium all-flash arrays and economy-tier hybrid configurations creates white-space entry points for subscription-based consumption models. Target healthcare archiving procurement outside traditional IT capital cycles through managed compliance service bundling. Penetrate Eastern Province industrial zones with edge storage nodes for Aramco sensor telemetry processing, using direct sales to bypass entrenched systems integrator relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional managed service providers because CITC certification requirements create defensible moats against pure international competitors. Five-to-ten-year viability rests on recurring revenue from sovereign data infrastructure operations rather than transactional hardware margins. Watch for NDMO classification tier expansion as the inflection signal indicating accelerated compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Hardware Assembly | CITC certification requirements redirect hyperscale investment toward domestic facilities with sovereign assembly capabilities. |
| NVMe-over-Fabrics Deployment | Saudi telecom operators deploy RDMA-enabled fabrics in Riyadh and Jeddah colocation facilities to collapse storage latency. |
| Subscription Consumption Models | Pure Storage's as-a-Service approach captures healthcare and education verticals with constrained capital allocation cycles. |
| Edge Storage Node Expansion | Aramco and SABIC petrochemical complexes generate specialized demand for sensor telemetry processing outside metro hubs. |
| Computational Storage Integration | BFSI institutions pilot embedded processing drives for real-time fraud detection, collapsing storage-compute boundaries. |
Research Methodology
Direct dialogue with storage architects at Saudi banks, procurement leads at STC and Mobily, CITC certification officers, and NDMO compliance directors grounded qualitative insights. Secondary validation drew from hyperscaler capex disclosures, CITC cloud certification registries, SEC filings of listed storage vendors, and Saudi customs import data for storage component categories. Bottom-up demand modeling triangulated against top-down infrastructure investment forecasts across the analysis window.
Segmented outputs across product type, technology, end user, and deployment dimensions fed into analytical frameworks spanning the projection horizon. CAGRs derived from fitted growth curves applied to base-year market sizing, with NVMe adoption rates and localization compliance timelines serving as key forecast inputs. Deployment pattern shifts between on-premises, hybrid, colocation, and cloud models were modeled against NDMO classification tier expansion scenarios.
Caveats apply where NAND supply tightness, NCA hardware certification timeline extensions, or NDMO domestic content threshold adjustments could materially shift the outlook. Forecasts reflect assumptions regarding continued Vision 2030 budget execution and CITC enforcement consistency. A model refresh is warranted upon material change in sovereign data classification scope or East Asian semiconductor export control regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Hard Disk Market
Storage Solutions
Brazil Data Center Storage Market