
 Dipropylene Glycol (DPG) Market | 2026-2036
Dipropylene Glycol (DPG) Market Size, Share, and Industry Trends Forecast 2026-2036
Dipropylene Glycol (DPG) Market Analysis
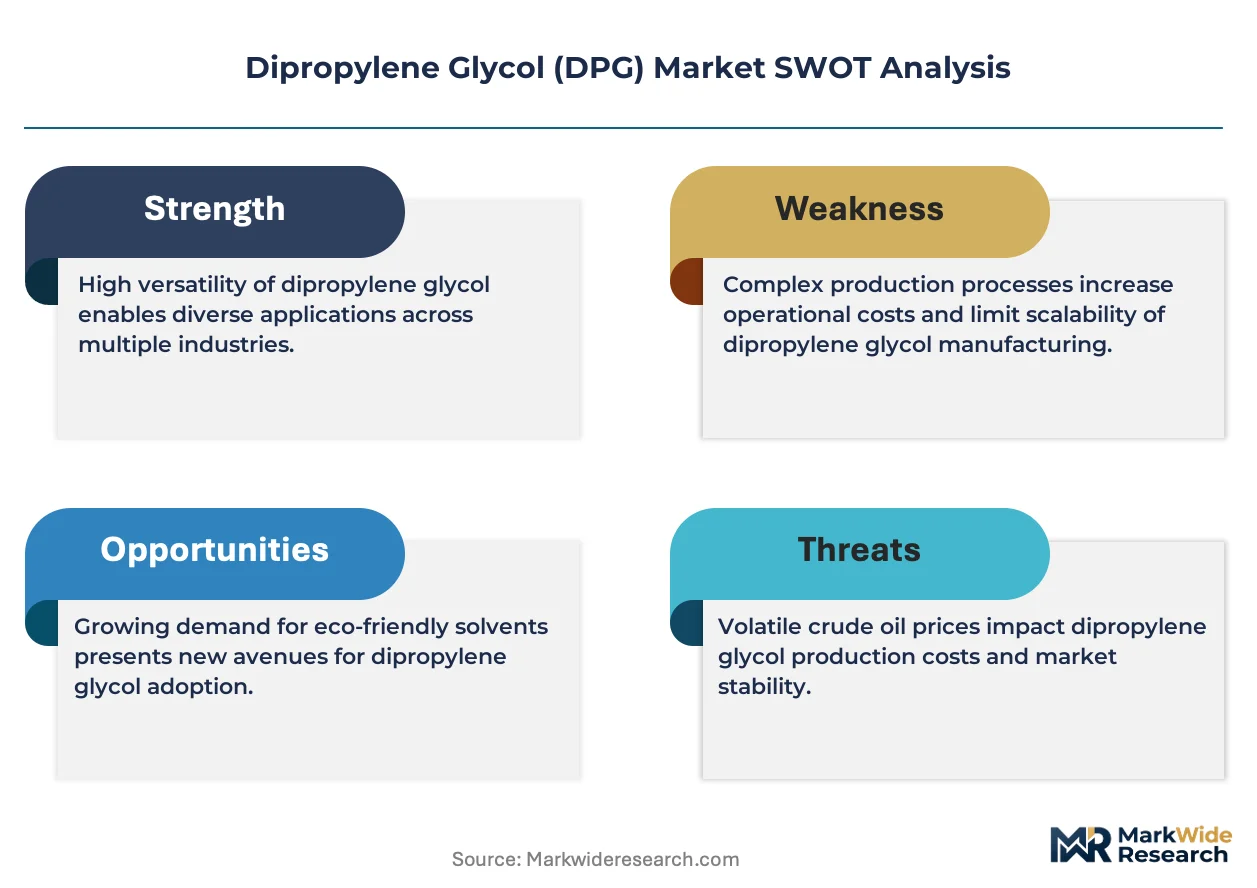
Asset-light leasing arrangements for propylene oxide feedstock is tilting competitive dynamics toward firms with flexible offtake contracts rather than captive crackers. Dow Inc. leverages its integrated propylene chain to sustain margin stability across DPG derivatives. Huntsman Corporation anchors its position through specialized industrial-grade supply to coatings and polyurethane intermediates. BASF SE differentiates via pharmaceutical-grade certification and controlled-substance handling protocols.
Dipropylene Glycol is a hygroscopic, colorless liquid with the molecular formula C6H14O3, produced through the hydration of propylene oxide and existing as a mixture of three isomeric forms; it functions primarily as a solvent, coupling agent, and viscosity reducer across cosmetic, industrial, and pharmaceutical applications. Cosmetic Grade DPG leads value contribution due to stringent purity requirements and brand-certified supply chains, while Industrial Grade dominates volume throughput in coatings and deicing formulations. Pharmaceutical Grade occupies a narrower but higher-margin niche governed by pharmacopeial compliance, with Food Grade trailing as a regulated but lower-growth segment.
EPA oversight in the United States and REACH registration in Europe impose divergent VOC-content thresholds and substance authorization requirements that reshape product specifications and regional sourcing strategies. FDA and EMA pharmacopeial standards for pharmaceutical-grade DPG create compliance moats that limit supplier entry and sustain premium pricing for certified producers. Stakeholders must monitor feedstock propylene oxide availability and regional regulatory divergence to optimize grade-mix decisions and capacity allocation across end-use segments.
Market Dynamics
Propylene oxide feedstock volatility and tightening VOC regulations across major economies are compressing margin structures while forcing rapid grade-mix reconfiguration toward cosmetic and pharmaceutical certifications.
Growth Catalysts
- REACH substance authorization:European purity mandates are accelerating reformulation demand in fragrance delivery systems, pulling cosmetic-grade DPG into premium personal care supply chains.
- China domestic scaling:Local chemical producers are expanding cosmetic-grade capacity to serve indigenous beauty brands and export markets simultaneously.
- EPA VOC thresholds:Lower allowable solvent emissions in industrial coatings are redirecting formulation demand toward higher-purity DPG alternatives with reduced volatile content.
Market Restraints
- Propylene oxide concentration:Feedstock supply clusters in Gulf Coast petrochemical corridors, exposing derivative producers to hurricane disruption and logistics bottlenecks.
- Pharmaceutical-grade compliance moats:FDA and EMA pharmacopeial certification timelines stretch 18-24 months, freezing out new entrants despite margin premiums.
- Glycol ether substitution:Dowanol and propylene glycol methyl ether acetate alternatives are capturing share in coatings applications where VOC flexibility exists.
Strategic Opportunities
- India personal care expansion:CDSCO streamlined cosmetic ingredient registrations are opening pathways for certified DPG suppliers into domestic formulation houses.
- Biobased propylene oxide:Renewable feedstock technologies are converging with conventional hydration processes to enable carbon-intensity labeling for brand-conscious buyers.
- Saudi downstream integration:SABIC and derivative producers are constructing propylene oxide capacity adjacent to cracking complexes, creating export-oriented DPG supply nodes.
Industry Challenges
- Analytical chemist scarcity:Pharmacopeial-grade DPG production requires specialized chromatography and impurity profiling expertise that outpaces current training pipelines.
- Multi-jurisdiction dossier maintenance:Simultaneous REACH, EPA TSCA, and China MEE registration updates drain regulatory affairs bandwidth without revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipropylene Glycol (DPG) Market |
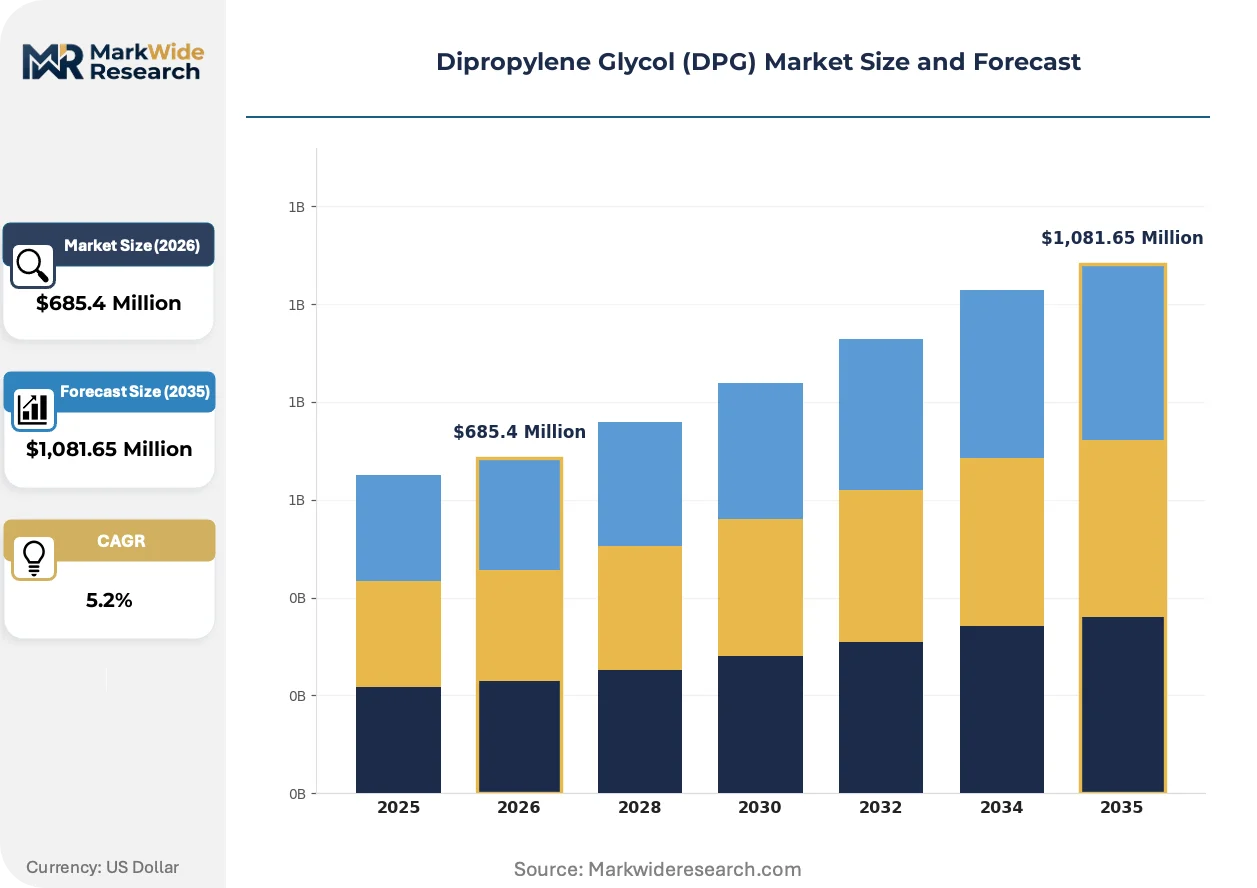
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Personal Care, Automotive, Industrial Solvents, Food Additives End User: Cosmetics Manufacturers, Food Processors, Chemical Companies, Pharmaceuticals Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers |
| Companies Covered | Eastman Chemical Company, Huntsman Corporation, Dow Inc., ExxonMobil Chemical, INEOS, BASF SE, Shell Plc, Manali Petrochemicals Limited, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipropylene Glycol (DPG) Market Emerging Trajectories
Membrane separation and continuous hydration reactor designs are displacing batch processing economics while regulatory data-sharing initiatives compress compliance overhead across supplier networks.
Continuous propylene oxide hydration with integrated isomer separation is rendering obsolete conventional batch reactor trains with downstream distillation columns. Korean and Japanese cosmetic ingredient houses are retrofitting existing assets at 18-month payback thresholds. This technology compression is collapsing capital intensity barriers for mid-scale entrants previously locked out by fixed-cost disadvantages.
ECHA's SCIP database mandate for article-level substance disclosure is forcing downstream cosmetic and coatings formulators to demand batch-level traceability from DPG suppliers. Industrial-grade buyers in automotive coatings are now requiring certificate-of-analysis integration into ERP procurement portals. European fragrance houses are responding by consolidating supplier panels to those with established SCIP workflows.
Brand-certified supply chain verification is replacing commodity spot purchasing in high-purity segments. Cosmetic multinationals are implementing blockchain-anchored batch documentation that disqualifies non-compliant intermediaries. This credential-driven procurement compression is most visible in German and French personal care manufacturing clusters where formulation houses now pre-qualify DPG sources against combined REACH-SCIP-audited standards before contract negotiation.
Dipropylene Glycol (DPG) Market Segmentation
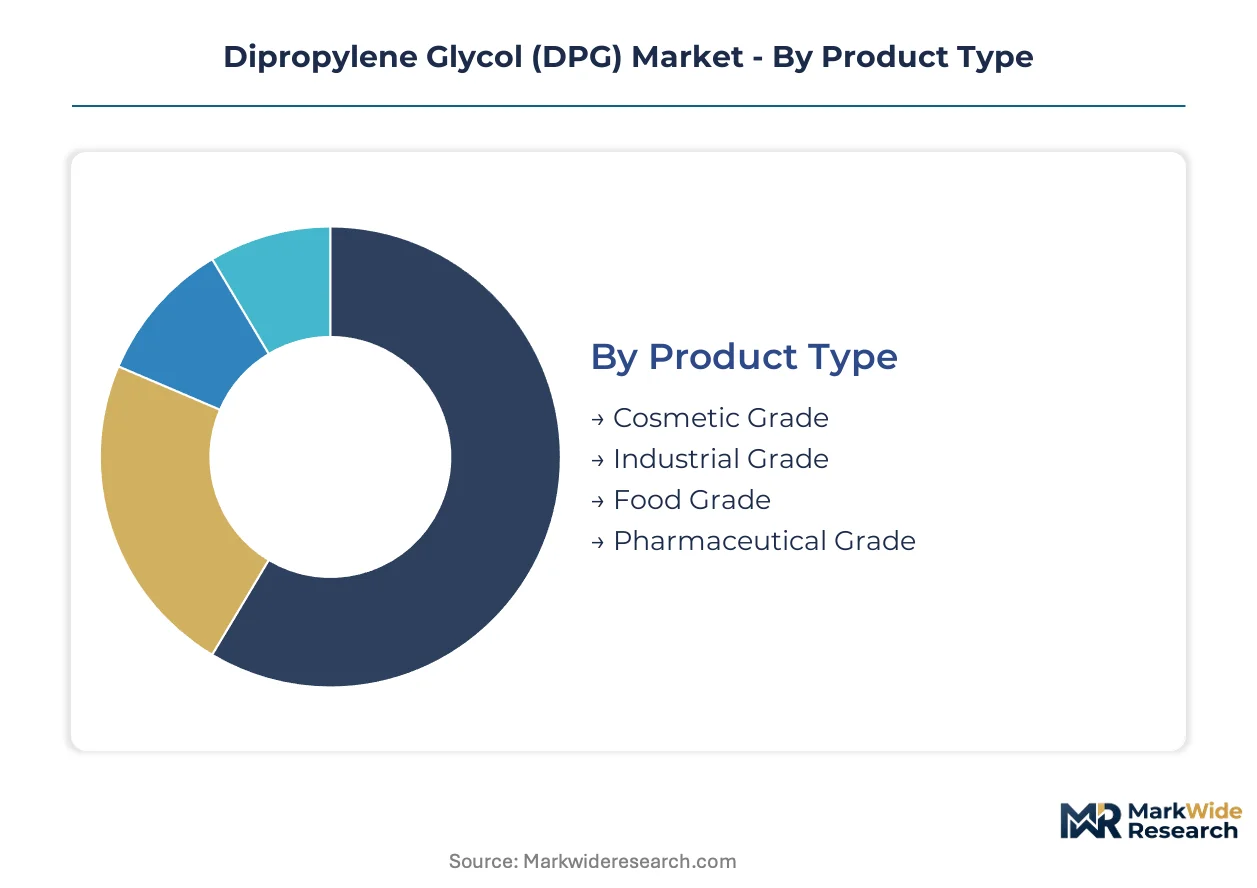
DPG segmentation reflects divergent purity specifications and compliance burdens across end-use verticals. Grade certification tiers create distinct margin architectures that reshape supplier positioning and procurement strategies.
Product Type:
Cost tier differentiation separates commodity industrial supply from premium-certified grades governed by pharmacopeial and cosmetic protocols.
- Cosmetic Grade:Stringent impurity limits below 0.1% and brand-audited supply chains satisfy ECHA REACH and FDA cosmetic ingredient standards. Fragrance houses in France and Germany consolidate procurement around certified producers with SCIP database integration.
- Industrial Grade:Standard hydration output serves coatings deicing and polyurethane intermediate applications without pharmacopeial overhead. Demand concentrates in automotive coatings clusters around Detroit and Stuttgart where EPA and REACH VOC thresholds drive reformulation.
- Food Grade:FDA and EFSA food additive compliance enables flavor carrier and processing aid applications with moderate purity requirements.
- Pharmaceutical Grade:USP-NF and EP monograph adherence with 18-24 month certification timelines limits supplier entry and sustains premium positioning.
Industrial Grade commands the established base. The steepest expansion runs through Cosmetic Grade.
Application:
Application clustering tracks how solvent coupling and viscosity reduction functions map onto regulatory exposure and formulation complexity.
- Personal Care:Fragrance delivery systems and skincare solvents demand batch-level traceability for ECHA SCIP compliance. Korean and Japanese cosmetic ingredient houses drive specification tightening through blockchain-anchored documentation requirements.
- Industrial Solvents:Coatings and cleaning formulations absorb volume throughput with lower purity tolerance. EPA VOC threshold reductions in the United States redirect demand toward higher-purity alternatives with reduced volatile content.
- Automotive:Deicing fluids and coolant intermediates require seasonal demand management and cold-chain logistics coordination.
- Food Additives:Flavor extraction and processing aids operate under FDA 21 CFR and EFSA food additive frameworks with distinct migration testing protocols.
Industrial Solvents anchors volume throughput. Personal Care delivers the fastest margin expansion.
End User:
Customer type stratification reveals how formulation complexity and regulatory scrutiny concentrate purchasing power across distinct buyer archetypes.
- Cosmetics Manufacturers:Multinationals implement pre-qualified supplier panels with combined REACH-SCIP-audited standards. German and French formulation houses now disqualify non-compliant intermediaries before contract negotiation.
- Pharmaceuticals:FDA and EMA pharmacopeial certification requirements create 18-24 month entry barriers that freeze out new suppliers despite margin premiums.
- Chemical Companies:Industrial coatings and polyurethane intermediate producers prioritize flexible offtake contracts over captive supply.
- Food Processors:Flavor and extraction applications demand migration testing documentation under divergent national food safety frameworks.
Chemical Companies command the volume base. Cosmetics Manufacturers drive the steepest specification escalation.
Distribution Channel:
Channel structure reflects how batch traceability requirements and geographic concentration reshape intermediary economics.
- Distributors:Regional chemical distributors with certificate-of-analysis integration into ERP procurement portals capture industrial-grade volume in automotive coatings.
- Direct Sales:Cosmetic and pharmaceutical grade supply chains consolidate around direct manufacturer relationships to satisfy brand-certified verification and blockchain documentation.
- Online Retailers:Specialty chemical platforms serve small-batch formulation houses with extended delivery timelines.
- Wholesalers:Bulk commodity movement serves industrial solvent applications with lower documentation burdens.
Direct Sales commands premium grade penetration. Distributors retain the broadest industrial coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and France runs substantially ahead of Chinese export benchmarks, reflecting REACH compliance premiums and brand-audited supply chain verification costs that commodity producers elsewhere cannot capture.
United States
Cosmetic formulators in New Jersey and California drive specification tightening for fragrance delivery systems. EPA VOC threshold reductions for industrial coatings redirect solvent demand toward higher-purity DPG alternatives. The Gulf Coast petrochemical corridor concentrates propylene oxide feedstock supply, exposing derivative producers to hurricane disruption risk.
Germany
Fragrance houses in Cologne and Düsseldorf consolidate procurement around REACH-certified producers with SCIP database integration. ECHA substance authorization mandates accelerate reformulation demand in personal care supply chains. The Rhine-Ruhr industrial cluster anchors cosmetic-grade DPG consumption for export-oriented formulation houses.
China
Domestic beauty brands in Shanghai and Guangzhou scale cosmetic-grade DPG adoption for indigenous fragrance and skincare formulations. MEE environmental standards tighten wastewater discharge requirements for hydration process operators. The Yangtze River Delta concentrates capacity expansion among state-backed chemical producers serving both local and export markets.
India
Personal care manufacturers in Maharashtra and Gujarat expand DPG sourcing for solvent and coupling agent applications. CDSCO streamlined cosmetic ingredient registrations reduce entry barriers for certified suppliers. The Mumbai-Pune industrial corridor attracts regional distributor investment for certificate-of-analysis integrated procurement portals.
Saudi Arabia
SABIC and downstream derivative producers construct propylene oxide capacity adjacent to cracking complexes for export-oriented DPG supply. SFDA pharmaceutical-grade standards create compliance benchmarks for regional formulation houses. The Eastern Province petrochemical cluster targets European and Asian cosmetic-grade markets through integrated supply nodes.
Dipropylene Glycol (DPG) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positions. The supplier base concentrates around three tiers: integrated petrochemical majors with captive propylene oxide supply, mid-scale hydration specialists with flexible offtake arrangements, and regional distributors with certificate-of-analysis integration capabilities. Two dominant competitive moves reshape positioning: backward integration into propylene oxide feedstock and blockchain-anchored batch documentation for brand-certified supply chains.
Within the integrated majors tier, Dow Inc., BASF SE, and Huntsman Corporation exemplify divergent strategic anchors. Dow represents margin stability through captive propylene chain control. BASF occupies the pharmaceutical-grade certification niche with pharmacopeial compliance protocols. Huntsman anchors industrial-grade supply to coatings and polyurethane intermediate applications. These three companies collectively illustrate how feedstock access, grade certification, and end-use specialization partition competitive terrain.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Huntsman Corporation |
| Dow Inc. |
| ExxonMobil Chemical |
| INEOS |
| BASF SE |
| Shell Plc |
| Manali Petrochemicals Limited |
| LyondellBasell Industries |
| Others |
Supply Flow & Price Mechanics
Gulf Coast propylene oxide concentration anchors upstream supply economics, pushing margin capture downstream toward cosmetic-grade certification holders in Germany and France. REACH compliance premiums and brand-audited supply chain verification costs create pricing power separation that commodity producers elsewhere cannot bridge.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade certified supply and standard industrial-grade spot transactions runs wide. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects certification burden divergence. Price differentiation hinges on pharmacopeial compliance timelines and batch-level traceability infrastructure. Cost compression in industrial-grade segments is intensifying because glycol ether substitutes capture coatings share where VOC flexibility exists. Chemical companies absorb the highest price sensitivity; cosmetics manufacturers show least elasticity due to brand-certified procurement mandates.
Supply Chain Analysis
Contract-manufacturing concentration among Korean and Japanese cosmetic ingredient houses with continuous hydration retrofit capabilities shapes midstream capacity. Feedstock supply clusters in the United States, Saudi Arabia, and China, with derivative production gravitating toward propylene oxide adjacency. Raw material dependencies center on propylene oxide, hydration catalysts, and isomer separation membranes. Single-source vulnerability runs through Gulf Coast hurricane exposure. Distribution runs through direct sales for premium grades and regional chemical distributors for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DPG market fragmentation creates entry niches as specification escalation across cosmetic and pharmaceutical grades outpaces consolidated supplier adaptation. Brand-certified supply chain verification demands and multi-jurisdiction dossier maintenance drain incumbent bandwidth without revenue offset.
For Market Incumbents: Harden pharmacopeial-grade certification moats through accelerated FDA and EMA dossier expansion before 18-24 month timelines freeze additional competitors. Deepen backward integration into propylene oxide feedstock to offset Gulf Coast concentration risk. Anchor direct sales relationships with blockchain-anchored batch documentation to disqualify distributor-dependent challengers.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat personal care manufacturing corridors offer underpenetrated white-space as CDSCO streamlined registrations reduce entry barriers. Target cosmetic-grade supply to indigenous beauty brands with flexible offtake contracts rather than captive crackers. Lead with certificate-of-analysis integration into ERP procurement portals to match automotive coatings distributor requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale hydration specialists with membrane separation retrofit capabilities and existing REACH-SCIP workflow infrastructure. Long-term viability favors assets positioned at the cosmetic-pharmaceutical grade intersection where compliance moats sustain premium capture. Watch for SABIC Eastern Province propylene oxide capacity completion as inflection signal for export-oriented supply node competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow and SABIC captive supply models neutralize feedstock volatility exposure. |
| Continuous Hydration Reactor Retrofit | Korean and Japanese cosmetic ingredient houses collapse batch processing economics. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA 18-24 month timelines freeze competitors despite margin premiums. |
| Blockchain-Anchored Batch Documentation | German and French fragrance houses disqualify non-compliant intermediaries pre-contract. |
| Long-Term Supply Agreement with Beauty Brands | Shanghai and Guangzhou indigenous brands lock in cosmetic-grade capacity allocation. |
Methodological Framework
A standing panel of plant managers at hydration facilities, procurement leads at downstream coatings OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA SCIP database disclosures. Bottom-up grade-mix modeling and top-down end-use demand aggregation enabled triangulation.
Scenario-bracketing framed projections across conservative, baseline, and aggressive regulatory enforcement pathways. Segmentation dimensions spanned grade tier, end-use industry, regional production hub, and certification protocol cluster. CAGRs were derived from propylene oxide feedstock availability assumptions, VOC threshold tightening trajectories, and cosmetic brand procurement pattern shifts throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Saudi export-oriented supply nodes or biobased propylene oxide technology developers would shift outcomes beyond modeled ranges. Quarterly review of ECHA substance authorization timelines, EPA VOC threshold revisions, and CDSCO registration processing speeds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market