
 Global Biochemical Market | 2026-2036
Global Biochemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biochemical Market Analysis
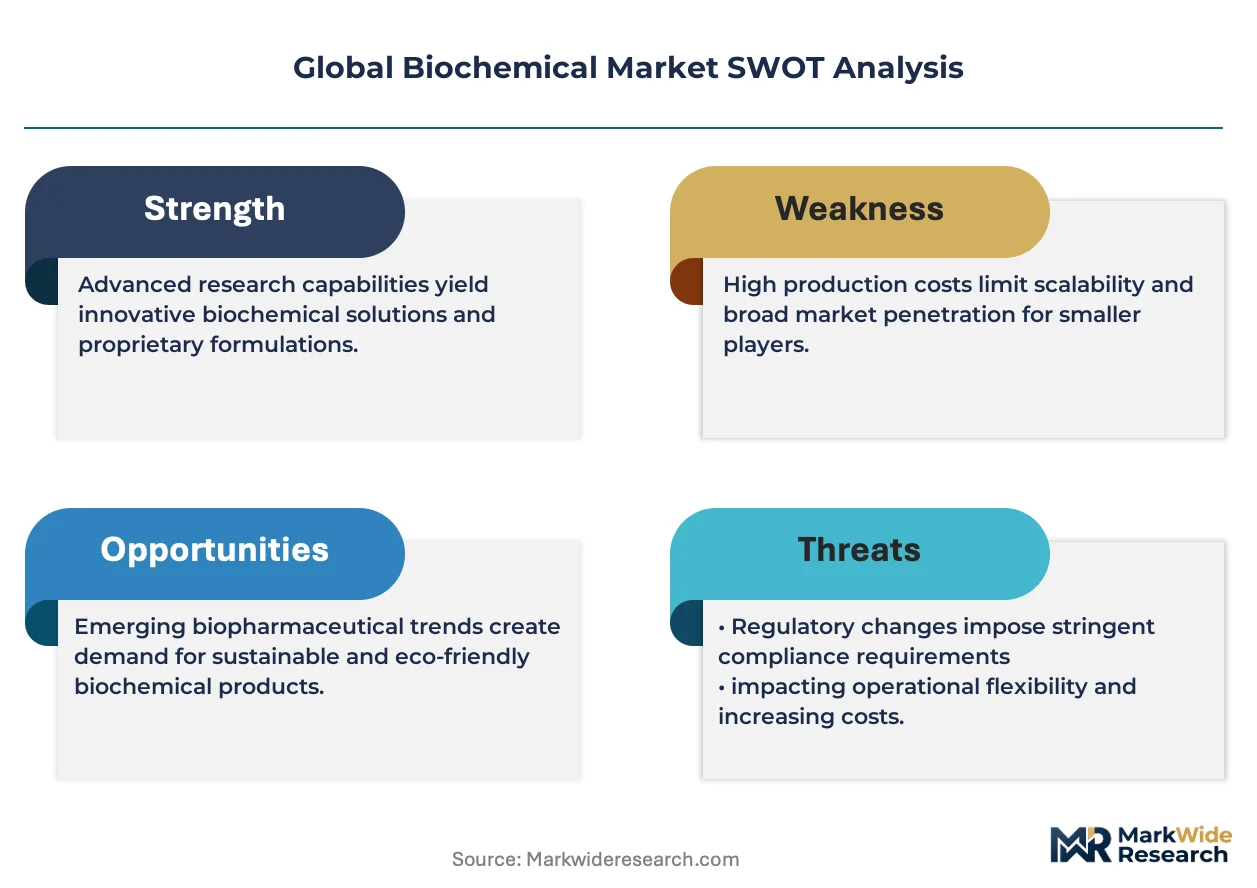
Project finance tied to green chemistry infrastructure is reshaping competitive entry in biochemical production, lowering capital barriers for specialized manufacturers. Thermo Fisher Scientific leverages its integrated supply chain to sustain reagent-grade biochemical output at scale. Novo Nordisk anchors insulin and enzyme production through captive fermentation capacity. CSL competes on plasma-derived biochemical fractionation with vertically controlled cold-chain logistics.
Biochemicals comprise biologically synthesized or extracted organic molecules—enzymes, amino acids, nucleotides, and peptides—typically manufactured via microbial fermentation, cell culture, or enzymatic catalysis with purity grades spanning research to pharmaceutical specifications. These molecules serve as active ingredients, process catalysts, and analytical reagents across industrial and therapeutic applications. Enzymes dominate current revenue pools due to their irreplaceable role in pharmaceutical synthesis and food processing workflows. Amino acids are expanding fastest in agriculture and animal nutrition as protein substitution pressures intensify. Peptides command premium positioning in targeted therapeutics, though nucleotides retain concentrated demand from biotechnology research institutions.
The EPA enforces emissions standards that push US manufacturers toward enzymatic processes with lower solvent intensity, while REACH and the EU Green Deal mandate substitution of petrochemical feedstocks in European production. China's MEE implements dual carbon goals that restrict energy-intensive fermentation operations, redirecting capacity toward efficiency-certified facilities. Stakeholders must monitor regulatory divergence across these jurisdictions to align capital deployment with evolving compliance thresholds and emerging bio-based procurement mandates.
Market Dynamics
The EU Green Deal and REACH compliance are forcing substitution of petrochemical feedstocks with bio-based alternatives, redirecting capital toward enzymatic process infrastructure and specialized fermentation capacity.
Growth Catalysts
- REACH Mandates:The EU Green Deal accelerates bio-based process substitutions across European manufacturing, creating pull for fermentation-derived intermediates.
- Enzyme Procurement Surge:Biopharma therapeutic manufacturing is expanding captive enzyme sourcing to secure supply chain control over critical catalytic inputs.
- Germany's Cluster Buildout:Dedicated biochemical manufacturing hubs in Germany concentrate R&D infrastructure and skilled technical labor pools.
Market Restraints
- Feedstock Volatility:Agricultural sugar and corn prices swing with climate events, squeezing fermentation input cost predictability.
- Chinese Capacity Concentration:MEE dual carbon goals restrict energy-intensive fermentation operations, creating supply uncertainty from efficiency-certified facility transitions.
- Petrochemical Substitution Limits:High-purity pharmaceutical-grade specifications resist full bio-based replacement for certain synthetic intermediates.
Strategic Opportunities
- US EPA Emissions Pathway:The EPA's solvent-intensity standards push domestic manufacturers toward enzymatic processes, opening equipment and catalyst retrofit demand.
- Peptide Therapeutics Expansion:Targeted biologics development drives premium-grade peptide production capacity expansion for oncology and metabolic indications.
- China's Efficiency Certification:MEE-certified facilities gain preferential operating permits, rewarding early capital deployment in energy-optimized fermentation infrastructure.
Industry Challenges
- Fermentation Scale-Up Expertise:Commercial-scale bioreactor operation requires rare combinations of microbial strain engineering and process engineering talent.
- Multi-Jurisdiction Compliance:Divergent EPA, REACH, and MEE standards force parallel certification tracks for globally distributed production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biochemical Market |
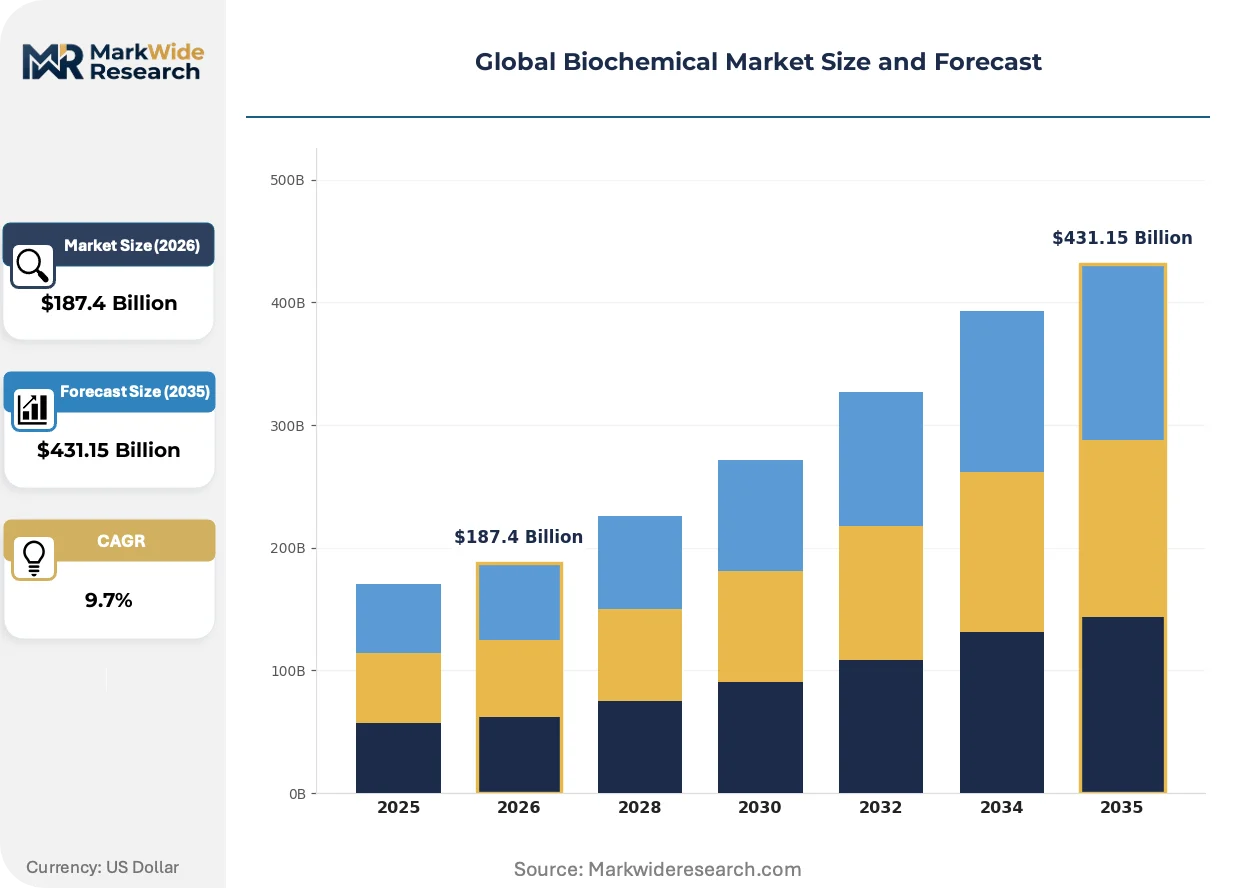
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Amino Acids, Nucleotides, Peptides Application: Biotechnology, Pharmaceuticals, Agriculture, Food Processing End User: Biopharma Companies, Research Institutions, Food Manufacturers, Chemical Industries Distribution Channel: Direct Sales, Online Retail, Distributors, Brokers |
| Companies Covered | Gilead Sciences, Chugai Pharmaceutical, Thermo Fisher Scientific, CSL, Regeneron Pharmaceuticals, Novo Nordisk, Vertex Pharmaceuticals, Jiangsu Hengrui Medicine, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biochemical Market Emerging Trajectories
Continuous processing architectures and synthetic biology toolsets are compressing batch cycle times and expanding the molecular addressability of microbial production platforms.
Cell-free enzymatic synthesis is migrating from research-scale peptide production to commercial manufacturing of complex glycosylated biologics. Contract development organizations are adopting these systems to reduce host-cell contamination risks. The technology is migrating from niche therapeutic applications toward broader pharmaceutical intermediate supply.
The EU AI Act introduces algorithmic transparency requirements for bioprocess optimization software used in GMP environments. Manufacturers deploying machine learning for strain improvement must now document training data provenance and decision audit trails. European enzyme producers are restructuring digital tool validation protocols to preempt regulatory friction.
Buyers are consolidating biochemical procurement through integrated supply agreements rather than spot-market purchasing. Large biopharma manufacturers are negotiating multi-year offtake contracts directly with fermentation specialists, bypassing traditional distributor networks. This pattern is most visible in the United States, where Thermo Fisher Scientific and similar integrated suppliers have captured preferred vendor status through captive manufacturing scale.
Global Biochemical Market Segmentation
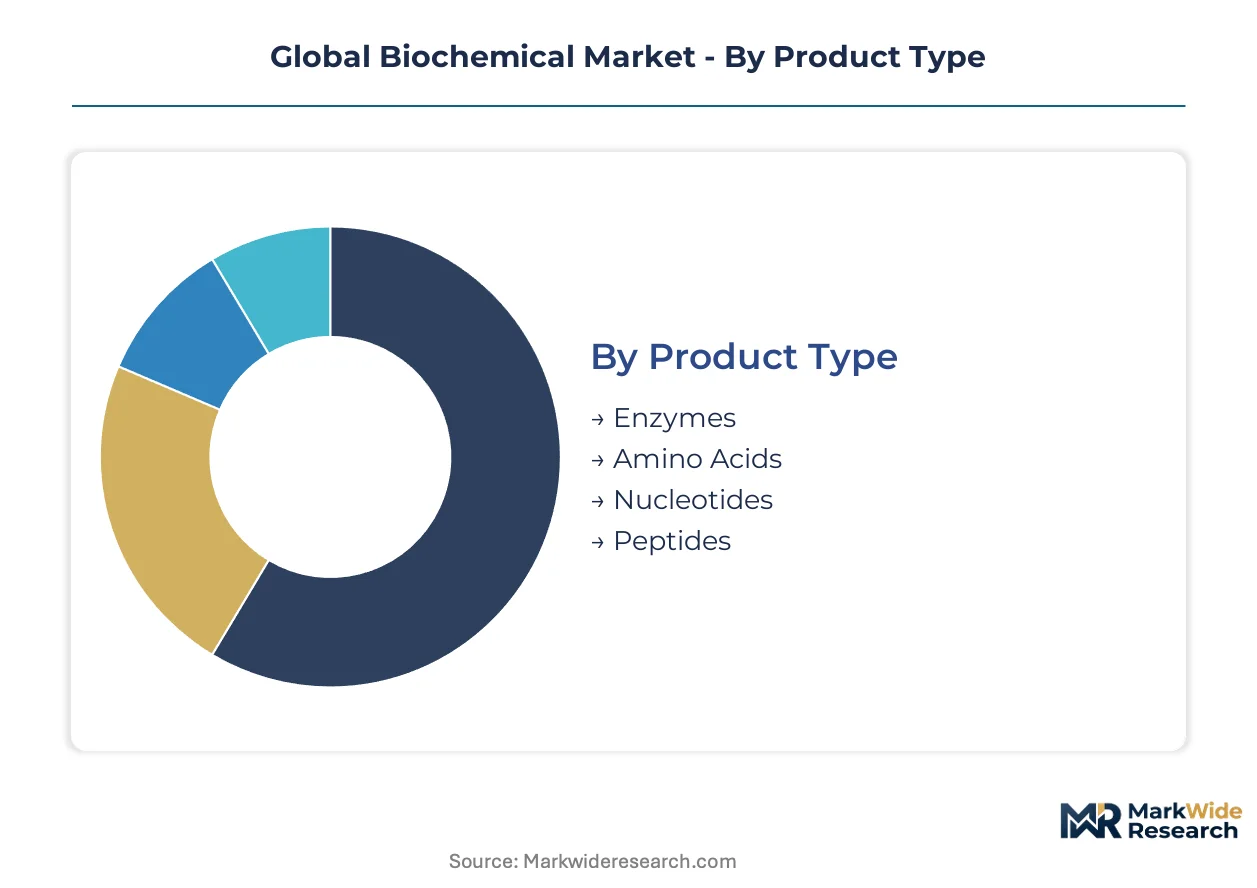
Biochemical segmentation reflects divergent purity requirements and regulatory exposure across therapeutic, industrial, and research applications. Each dimension—product chemistry, downstream use, procurement authority, and channel structure—carries distinct margin profiles and compliance burdens that shape supplier strategy.
Product Type:
Enzymes anchor pharmaceutical manufacturing workflows, while amino acids and peptides serve contrasting cost-performance thresholds in nutrition and therapeutics.
- Enzymes:Catalytic proteins manufactured via microbial fermentation or extraction, with specificity grades spanning food-grade to GMP-validated biopharma catalysts. Demand concentrates in insulin synthesis and statin production, where Novo Nordisk and Merck maintain captive sourcing to secure supply continuity against REACH feedstock substitution mandates.
- Amino Acids:Proteinogenic and non-proteinogenic molecules produced through fermentation or enzymatic conversion, differentiated by chirality and impurity profiles. China’s MEE efficiency certifications are redirecting lysine and methionine capacity toward energy-optimized facilities serving animal nutrition compounders in Germany and the United States.
- Nucleotides:Purine and pyrimidine derivatives for molecular biology reagents and antiviral therapeutics.
- Peptides:Short-chain amino acid polymers commanding premium positioning in GLP-1 agonists and oncology targeted therapies.
The dominant share belongs to Enzymes, while Amino Acids is closing the gap fastest.
Application:
End-use segmentation tracks regulatory stringency from GMP-validated therapeutics to commodity food processing.
- Biotechnology:Research-grade biochemicals for gene editing, cell culture, and diagnostic reagent manufacturing. Demand clusters in Boston, San Diego, and Cambridge UK corridors where CRISPR tool developers and mRNA vaccine manufacturers concentrate procurement.
- Pharmaceuticals:Active pharmaceutical ingredients and process catalysts subject to FDA, EMA, and NMPA validation requirements. Peptide API production is expanding fastest in Switzerland and Ireland to serve oncology and metabolic therapeutic pipelines.
- Agriculture:Biofertilizers, biocontrol agents, and feed additives with FIFRA and EU Fertilizing Products Regulation compliance paths.
- Food Processing:Enzymatic texturizers, preservatives, and flavor precursors operating under FSMA and EFSA safety thresholds.
Pharmaceuticals captures the highest margin pool, with Biotechnology expanding most quickly on cell and gene therapy infrastructure buildouts.
End User:
Procurement authority separates volume-committed manufacturers from spot-buying research entities.
- Biopharma Companies:Integrated therapeutic developers negotiating multi-year offtake agreements for fermentation-derived APIs and enzymes. Thermo Fisher Scientific and similar suppliers capture preferred vendor status through captive manufacturing scale and integrated cold-chain logistics.
- Research Institutions:Universities and national laboratories purchasing reagent-grade biochemicals through distributor networks or direct e-procurement portals.
- Food Manufacturers:Industrial enzyme buyers optimizing for cost-per-activity-unit in starch processing, dairy, and beverage applications.
- Chemical Industries:Specialty and commodity chemical producers substituting petrochemical routes with bio-based enzymatic catalysis under EPA and REACH emissions pressure.
Biopharma Companies command the largest procurement volumes, while Chemical Industries is gaining share fastest on green chemistry substitution mandates.
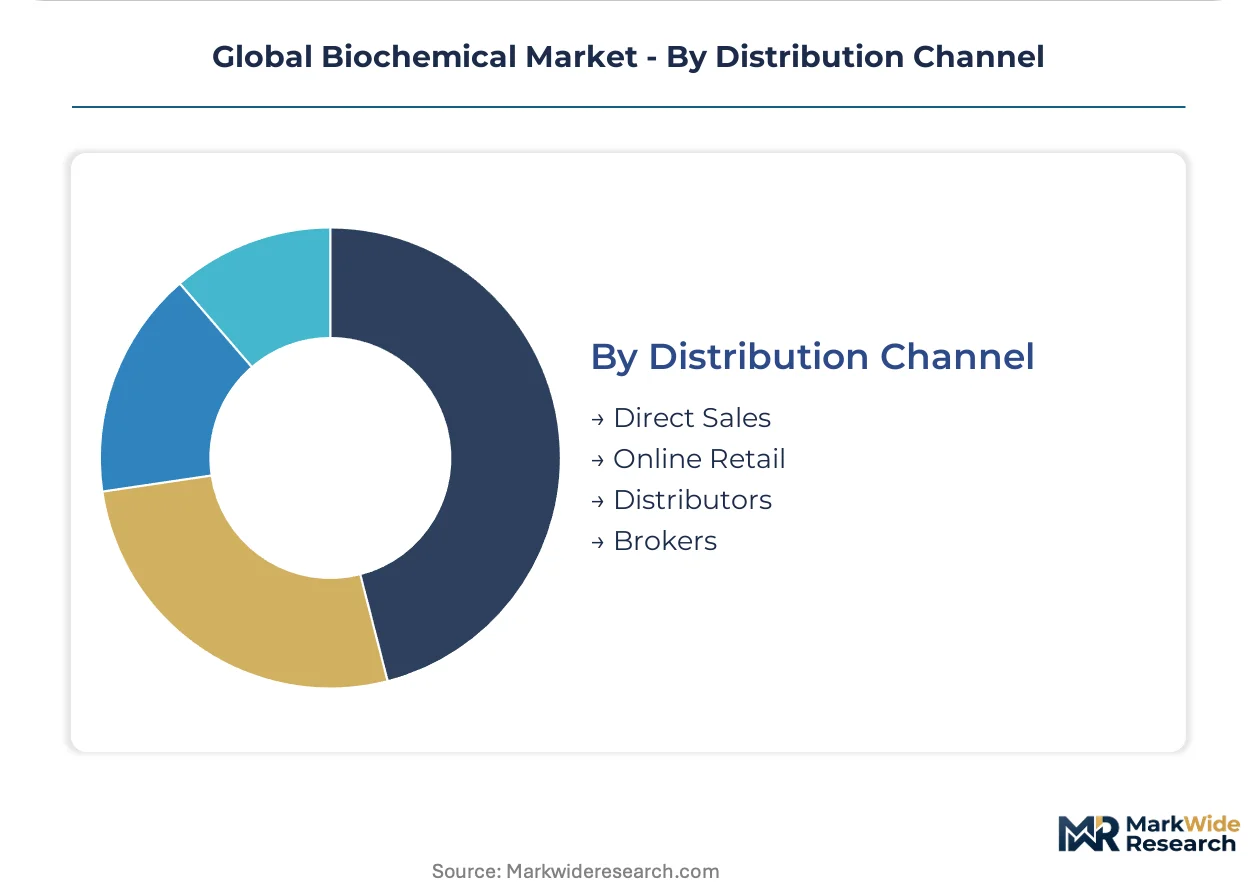
Distribution Channel:
Channel selection reflects order size predictability and technical service requirements.
- Direct Sales:Long-term supply agreements between fermentation specialists and large biopharma manufacturers, bypassing distributor markups. The pattern is most visible in the United States, where integrated suppliers negotiate multi-year contracts with guaranteed volume floors.
- Distributors:Regional warehousing networks serving mid-tier manufacturers and research institutions with fragmented SKU requirements.
- Online Retail:E-procurement platforms for catalog biochemicals with standardized specifications and rapid fulfillment.
- Brokers:Spot-market intermediaries for scarce or discontinued reagent grades.
Direct Sales holds the dominant position, though Online Retail is climbing the fastest on catalog expansion and self-service procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH mandates and EPA emissions pathways are redirecting capital toward enzymatic process infrastructure across multiple jurisdictions. Germany anchors European fermentation capacity buildouts. China's MEE efficiency certifications concentrate supply in certified facilities. The United States leverages integrated biopharma procurement clusters.
Germany
Enzyme procurement for insulin synthesis and statin production drives demand concentration. The EU Green Deal accelerates bio-based feedstock substitution mandates. Dedicated biochemical manufacturing hubs in North Rhine-Westphalia concentrate R&D infrastructure and skilled technical labor pools serving pharmaceutical synthesis workflows.
United States
Multi-year offtake agreements between fermentation specialists and large biopharma manufacturers expand procurement volume. EPA solvent-intensity standards push domestic manufacturers toward enzymatic processes with lower emissions profiles. Boston and San Diego biotechnology corridors cluster CRISPR tool developers and mRNA vaccine manufacturers with concentrated biochemical procurement.
China
Energy-optimized fermentation infrastructure serves animal nutrition compounders in Germany and the United States. MEE dual carbon goals restrict energy-intensive operations, redirecting lysine and methionine capacity toward efficiency-certified facilities. The Yangtze River Delta concentrates certified production assets with preferential operating permits.
Switzerland
Peptide API production expands fastest to serve oncology and metabolic therapeutic pipelines. Swissmedic validation requirements enforce GMP standards for active pharmaceutical ingredients. Basel and Zurich anchor premium-grade peptide manufacturing with vertically controlled cold-chain logistics serving European biopharma.
India
Contract development organizations adopt cell-free enzymatic synthesis systems for glycosylated biologics production. CDSCO regulatory pathways align with FDA and EMA validation requirements for export-oriented manufacturing. Hyderabad and Bangalore biotechnology clusters attract fermentation specialists establishing multi-year supply agreements with North American buyers.
Global Biochemical Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement consolidation and technical differentiation vectors. The vendor base organizes around integrated supply chain operators, captive fermentation capacity holders, and plasma-derived fractionation specialists. Three archetypes dominate: vertically integrated life science conglomerates, therapeutic developers with captive biomanufacturing, and research-grade reagent suppliers. Competitive moves concentrate on multi-year offtake negotiations and energy-certified facility buildouts.
Within the integrated supply tier, Thermo Fisher Scientific occupies a position exemplifying captive manufacturing scale and cold-chain logistics control. Novo Nordisk anchors the therapeutic-captive archetype through fermentation capacity dedicated to enzyme and insulin production. CSL represents plasma-derived biochemical fractionation with vertically controlled distribution infrastructure. These three entities illustrate divergent pathways to procurement preference status across pharmaceutical, research, and therapeutic end-use segments.
| Leading Market Players |
|---|
| Gilead Sciences |
| Chugai Pharmaceutical |
| Thermo Fisher Scientific |
| CSL |
| Regeneron Pharmaceuticals |
| Novo Nordisk |
| Vertex Pharmaceuticals |
| Jiangsu Hengrui Medicine |
| Amgen |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta's certified fermentation capacity concentrates lysine and methionine supply for animal nutrition compounders, translating upstream efficiency certifications into downstream pricing power over European and North American buyers. REACH feedstock substitution mandates and EPA solvent-intensity standards amplify cost pass-through leverage for producers with MEE-certified infrastructure.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade biochemicals. Three-tier pricing structure across GMP-validated, research-grade, and food-grade tiers reflects FDA, EMA, and ISO compliance burdens. Cost compression in research-grade enzymes is intensifying because Chinese capacity consolidation redirects spot-market volumes toward efficiency-certified facilities. Biopharma manufacturers negotiating multi-year offtake agreements show lowest price sensitivity, while food processing buyers optimizing cost-per-activity-unit exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for lysine and methionine importers. Fermentation capacity concentrates in China, Germany, and the United States, with agricultural sugar and corn feedstock sourcing tethered to climate-vulnerable Midwestern US and Brazilian harvests. Single-source vulnerability from Yangtze River Delta concentration amplifies disruption exposure from MEE efficiency certification transitions. Distribution runs through integrated life science conglomerates with captive cold-chain logistics serving biopharma clusters in Boston and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against petrochemical process substitution as synthetic chemistry routes retain cost advantages for high-purity pharmaceutical intermediates. The defensive imperative centers on securing fermentation scale-up expertise before cell-free enzymatic synthesis migrates to broader commercial manufacturing.
For Market Incumbents: Entrench supply continuity through captive sourcing agreements with MEE-certified fermentation facilities in the Yangtze River Delta. Deepen backward integration into agricultural feedstock procurement to buffer sugar and corn price volatility. Anchor preferred vendor status through integrated cold-chain logistics control against emerging CDMO competitors adopting cell-free synthesis systems.
For New Entrants and Emerging Players: India's Hyderabad and Bangalore biotechnology corridors offer underpenetrated contract manufacturing entry points for peptide API production serving North American oncology pipelines. Target research-grade nucleotide supply to CRISPR tool developers in San Diego and Cambridge UK corridors bypassing established distributor networks. Pursue direct sales channel establishment through e-procurement platform partnerships with mid-tier research institutions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded fermentation capacity outside MEE efficiency certification pathways. Long-term viability hinges on positioning for bio-based feedstock mandate expansion across the EU Green Deal implementation horizon. Monitor EPA enforcement intensity for solvent-intensity standards as inflection indicator for enzymatic process retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MEE Efficiency Certification | Preferential operating permits in China concentrate supply among early movers with energy-optimized infrastructure. |
| Multi-Year Offtake Agreements | Direct procurement contracts between fermentation specialists and biopharma manufacturers bypass traditional distributor markups. |
| Cell-Free Enzymatic Synthesis Scale-Up | Commercial migration from research-scale peptide production reduces host-cell contamination risks for glycosylated biologics. |
| Backward Integration into Feedstock Procurement | Captive agricultural sugar and corn sourcing buffers fermentation input cost predictability against climate-driven price swings. |
| Integrated Cold-Chain Logistics Investment | Vertically controlled distribution infrastructure secures plasma-derived biochemical fractionation margins for CSL and comparable specialists. |
Methodological Framework
Cross-validation between primary interviews with fermentation process engineers, biopharma procurement directors, regulatory affairs specialists, and CDSCO compliance officers anchors the qualitative findings. Secondary validation draws from FDA 483 inspection observations, EMA GMP certificates, MEE efficiency certification registries, and SEC 10-K disclosures from integrated life science suppliers. Bottom-up capacity modeling triangulates against top-down demand aggregation from animal nutrition compounders and therapeutic manufacturers.
Calibration against historical capacity utilization rates and certification timeline data refines projection outputs across the analysis window. Segmentation dimensions span product chemistry, downstream application, procurement authority, and distribution channel structure. CAGRs derive from elasticity-adjusted demand curves incorporating REACH substitution mandate compliance timelines and EPA emissions pathway enforcement patterns. Strain engineering talent scarcity and bioreactor scale-up failure rates inform supply-side constraint assumptions.
Practitioners should monitor MEE certification transition delays, EU Green Deal bio-based procurement mandate expansion, and cell-free synthesis technology cost curves for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Hydro Fluorocarbon Market