
 Urea Strippers Market | 2026-2036
Urea Strippers Market Size, Share, and Industry Trends Forecast 2026-2036
Urea Strippers Market Intelligence
A scarcity of specialized process engineers with high-pressure vessel and corrosion metallurgy expertise is reorganizing the competitive landscape for new plant construction and revamping projects. Technology licensors like Stamicarbon specialize in proprietary stripping process designs that maximize urea yield and minimize energy consumption. In contrast, large engineering, procurement, and construction (EPC) firms such as Saipem S.p.A. leverage their extensive project management and global supply chain capabilities to execute turnkey plant installations. Larsen & Toubro competes with its strong manufacturing base for heavy engineering equipment.
A urea stripper is a critical heat exchanger used in the synthesis section of a urea production plant. Its primary function is to decompose unreacted ammonium carbamate into gaseous ammonia and carbon dioxide under high pressure and temperature, typically above 180°C. This decomposition process is essential for maximizing urea conversion efficiency. High-pressure designs dominate the market due to superior energy integration within the overall plant. While fertilizer production constitutes the largest application by volume, the use of stripping technology for ammonia recovery in petrochemical processing represents a specialized, high-margin segment.
Regulations governing industrial emissions and energy efficiency directly influence equipment selection and investment cycles. The European Union's Industrial Emissions Directive and China's Ministry of Ecology and Environment (MEE) standards for nitrogen oxide emissions force plant operators to invest in modern, more efficient stripper technologies. These rules link market access to environmental performance. Consequently, material selection to mitigate corrosion and extend equipment operational life is becoming the central consideration in capital allocation decisions for plant upgrades.
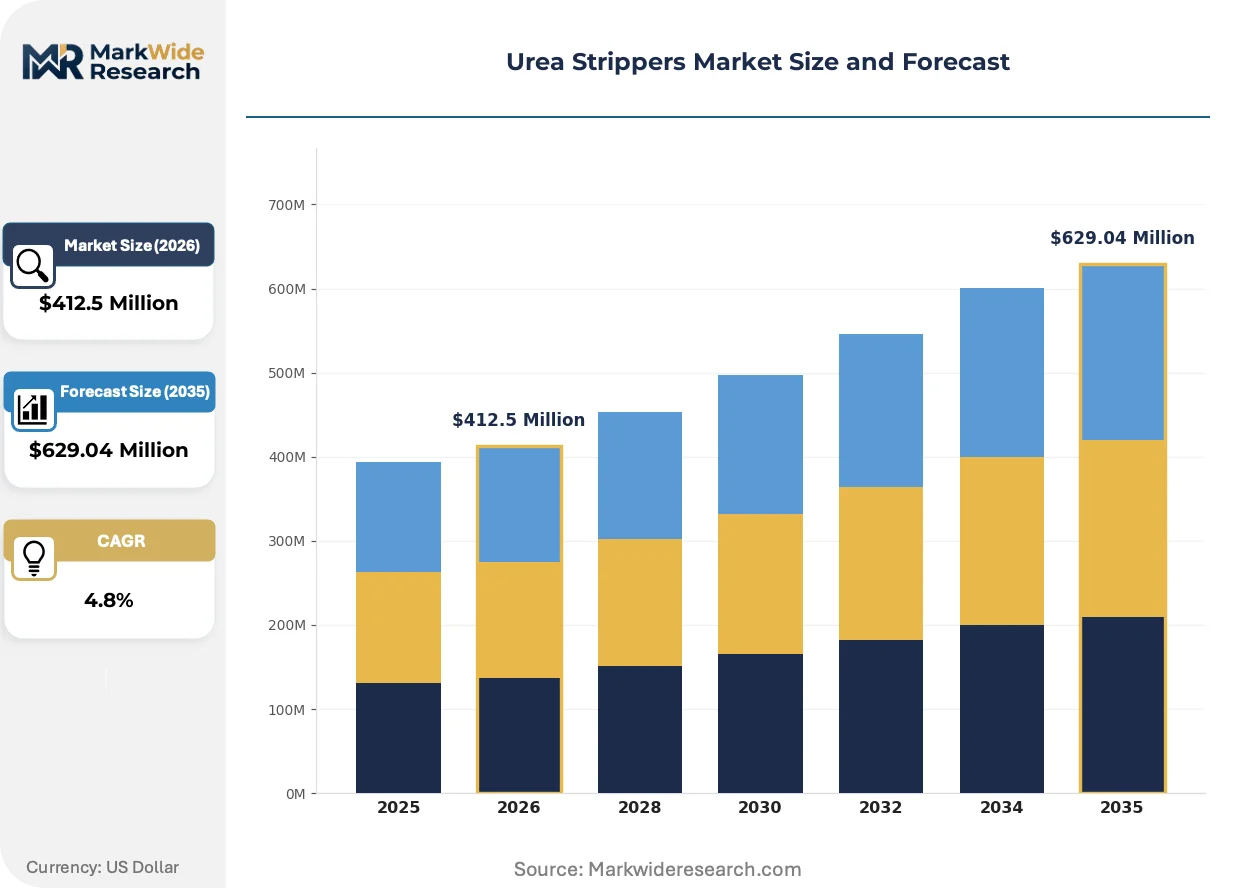
Market Dynamics
The urea strippers market is shaped by the technical tension between the drive for higher energy efficiency in urea production and a critical scarcity of specialized engineering talent. This shortage of experts in high-pressure metallurgy and process design concentrates power among a few technology licensors and EPC firms.
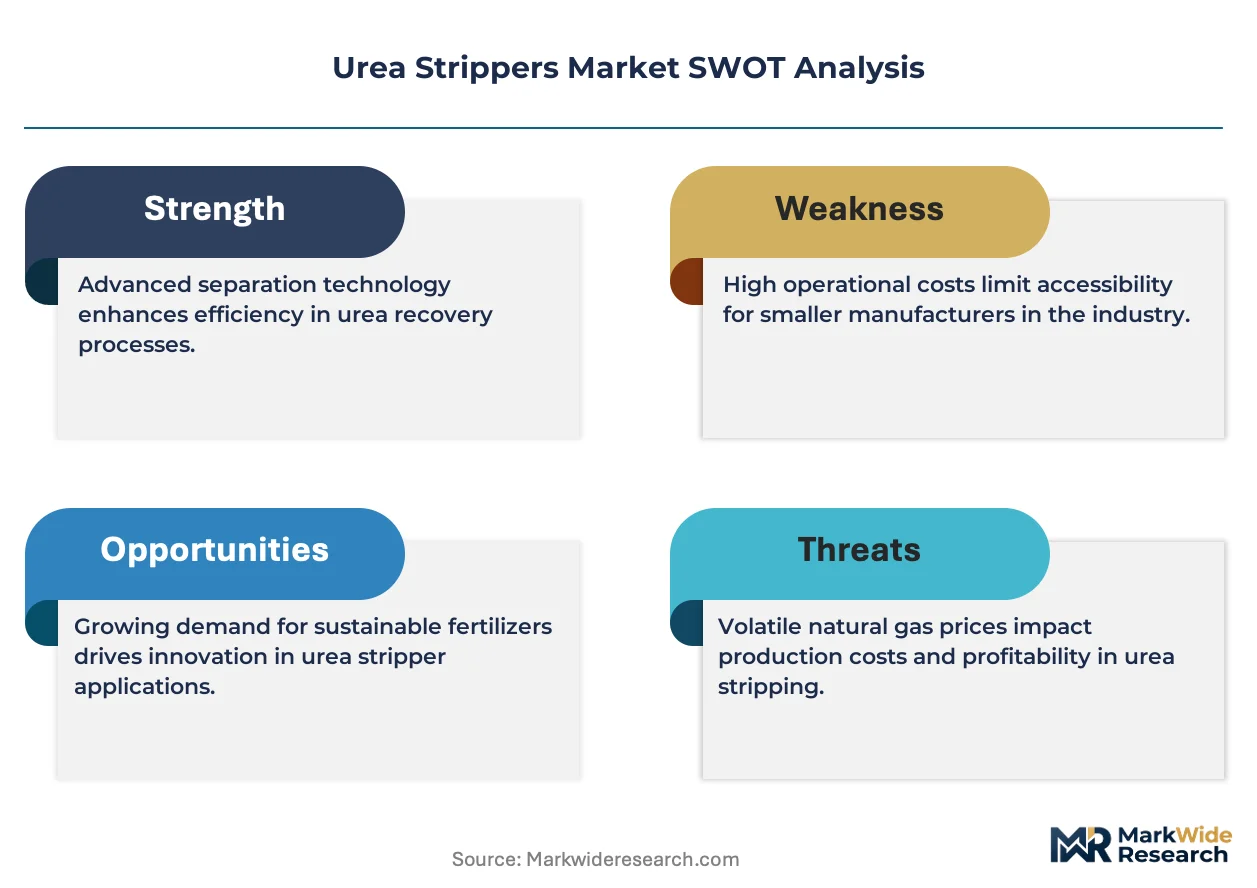
Growth Catalysts
- Stringent Emissions Regulations:Policies such as the European Union's Industrial Emissions Directive and China's MEE standards mandate reductions in nitrogen oxide emissions, compelling operators to invest in modern, high-efficiency stripper technologies to ensure compliance.
- Fertilizer Demand in Agriculture:Rising food demand in populous nations, particularly India, necessitates the expansion and modernization of domestic urea manufacturing capacity, directly fueling orders for new stripper units and plant revamping projects.
- Process Efficiency Innovations:The development of advanced high-pressure stripping processes that maximize the decomposition of ammonium carbamate and improve heat integration is a primary catalyst, as it reduces overall plant energy consumption.
Market Restraints
- High Capital Investment:The significant upfront cost associated with constructing new urea plants or undertaking major revamps with high-pressure stripping technology represents a substantial barrier for many operators, particularly in capital-constrained markets.
- Proprietary Technology Dependence:The market relies on a limited pool of technology licensors who control proprietary stripper designs, creating potential bottlenecks and limited negotiating power for plant owners during project development.
- Input Material Price Volatility:Fluctuations in the cost of specialized raw materials, such as high-grade stainless steels and titanium required for corrosion resistance in high-pressure vessels, can unpredictably inflate project budgets and timelines.
Strategic Opportunities
- Petrochemical Ammonia Recovery:Applying stripping technology for ammonia recovery in petrochemical processing streams offers a specialized, high-margin opportunity beyond the traditional fertilizer sector, targeting waste stream valorization.
- Modernization of Aging Plants:A significant installed base of older, less efficient urea plants in regions like Eastern Europe and parts of Southeast Asia presents a large opportunity for revamping projects driven by environmental compliance and energy costs.
- Advanced Material Lifecycle Services:Offering integrated services for corrosion monitoring, predictive maintenance, and material lifecycle management for stripper equipment provides a new revenue stream beyond initial equipment sales and installation.
Industry Challenges
- Specialized Talent Scarcity:A lack of process engineers and metallurgists with deep expertise in high-pressure vessel design and corrosion mechanisms under urea synthesis conditions constrains project execution capacity across the industry.
- Legacy System Integration:Integrating modern, high-efficiency strippers into the existing infrastructure of decades-old urea plants during revamping projects poses significant technical and logistical challenges, risking downtime and cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urea Strippers Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Pressure, High Pressure, Structured Packing, Random Packing, Tray Type Technology: Thermal Stripping, Vapor Recompression, Mechanical Stripping, Chemical Stripping, Adsorption Application: Natural Gas Sweetening, Fertilizer Production, Petrochemical Processing, Industrial Waste Treatment, Ammonia Recovery End User Industry: Oil & Gas Processing, Chemical Manufacturing, Power Generation, Water Treatment Plants, Ammonia Plants |
| Companies Covered | Larsen & Toubro, Saipem S.p.A., Stamicarbon, Urea Casale, TOYO Engineering India Private Limited, Isgec Heavy Engineering Ltd, ALFA LAVAL, thyssenkrupp, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urea Strippers Market Strategic Shifts & Innovations
A persistent drive for enhanced energy integration and stricter environmental performance is guiding innovation in the urea strippers market. This focus is accelerating advancements in material science for corrosion mitigation and reshaping how plant-scale projects are engineered and delivered.
Advanced corrosion-resistant materials are a key focus of product evolution. The use of proprietary duplex and super-duplex stainless steels provides superior resistance to the harsh conditions inside a high-pressure stripper. Plant operators in environmentally regulated markets are rapidly adopting these materials for both new builds and critical revamps. This intense focus on metallurgy is fragmenting the fabrication market, creating a clear division between standard vessel manufacturers and the specialized firms capable of welding and forming these advanced alloys.
The European Union's Green Deal and its associated industrial policies are influencing investment cycles. These frameworks incentivize lower energy consumption and emissions, directly promoting the adoption of superior stripper technologies that maximize heat recovery and minimize ammonia slip. The fertilizer production segment within the EU is most affected, as operators must now justify equipment selections based on long-term environmental performance and energy efficiency metrics, not just initial capital cost.
A notable behavioral shift is the move toward integrated project delivery models for new plant construction. This trend sees plant owners moving away from procuring individual equipment and services, instead favoring turnkey contracts with a single point of responsibility. This disrupts the component-supplier model, benefiting large EPC firms and technology licensors who can bundle design, engineering, procurement, and construction. This approach is most prominent for greenfield projects in India and the Middle East, where minimizing project risk and ensuring timely commissioning is critical.
Urea Strippers Market Segmentation
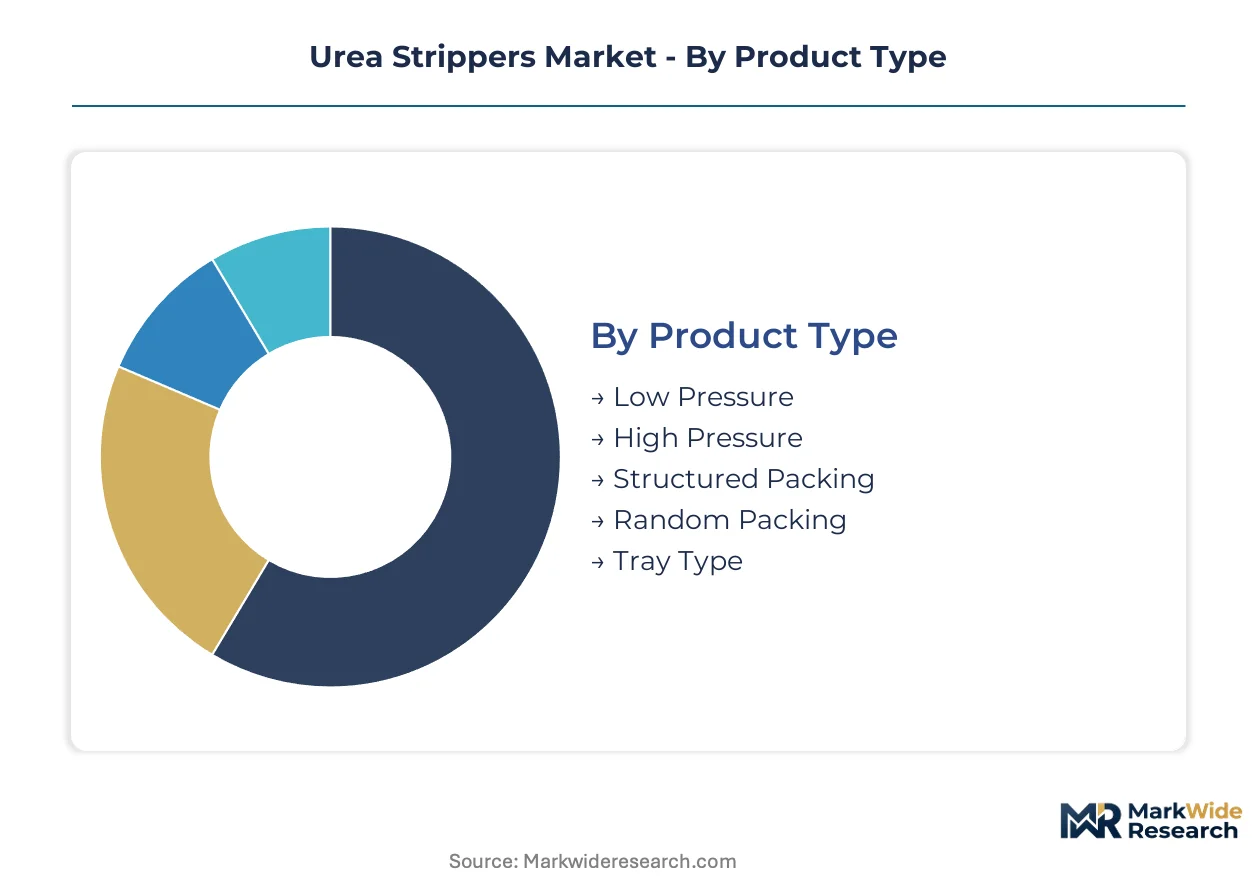
The urea strippers market is analyzed across various dimensions to provide a granular understanding of its structure and operational dynamics. Segmenting the market by product type, technology, application, and end-user industry reveals distinct demand patterns and competitive forces. This detailed breakdown helps identify areas of concentrated investment and emerging technological shifts.
Product Type:
Regulatory mandates for energy efficiency and emission reduction significantly differentiate demand across various stripper product types. Operators in regions like the European Union prioritize advanced designs to meet stringent environmental standards.
- High Pressure:These strippers operate above 180°C and are critical for maximizing urea conversion efficiency through effective ammonium carbamate decomposition. Demand concentrates in India, driven by large-scale fertilizer production facilities modernizing for energy integration.
- Structured Packing:This design incorporates engineered geometric arrangements to enhance mass transfer efficiency and reduce pressure drop. Plant upgrades in environmentally regulated markets increasingly adopt these materials for superior corrosion resistance and operational lifespan.
- Low Pressure:These units operate at lower pressures, typically for older plant designs or specific niche applications where energy integration is less critical.
- Random Packing:Utilizing randomly oriented elements, these strippers offer a cost-effective solution for certain process conditions but may have lower efficiency than structured alternatives.
- Tray Type:This traditional design employs plates or trays to facilitate gas-liquid contact, finding use in various industrial processes.
Established volume favors High Pressure designs; emerging adoption favors Structured Packing due to enhanced efficiency.
Technology:
Cost considerations and operational complexity heavily influence the selection of stripping technologies, creating distinct tiers based on initial investment and long-term energy savings. Advanced technologies offer superior performance at a higher capital outlay.
- Thermal Stripping:This foundational technology uses heat to decompose ammonium carbamate, forming gaseous ammonia and carbon dioxide for recycling. Fertilizer plants globally rely on thermal stripping for the primary separation step in urea synthesis.
- Vapor Recompression:Employing compressors to raise the pressure and temperature of vapor, this technology significantly improves energy efficiency by reusing latent heat. Modern urea facilities in China adopt vapor recompression to reduce overall energy consumption.
- Mechanical Stripping:This method uses mechanical means to enhance gas-liquid contact, often complementing thermal processes for specific applications.
- Chemical Stripping:Involving the use of chemical reagents to aid in the separation process, this technology addresses specific impurities or process requirements.
- Adsorption:This technology utilizes solid adsorbents to remove specific components from gas or liquid streams, often for purification or recovery purposes.
Operational stability prioritizes Thermal Stripping; Vapor Recompression is expanding most quickly for energy optimization.
Application:
The volume and criticality of processed materials dictate the specific requirements for urea strippers across diverse industrial applications. Each application presents unique challenges regarding corrosion, pressure, and temperature management.
- Fertilizer Production:This application represents the largest volume segment, where urea strippers are integral to the synthesis loop for manufacturing nitrogenous fertilizers. Global food demand necessitates continuous investment in new and revamped facilities for this sector.
- Petrochemical Processing:Stripping technology recovers ammonia from various petrochemical streams, offering a specialized and high-margin segment focused on waste valorization. Facilities in the Middle East utilize this for efficient resource management.
- Natural Gas Sweetening:Strippers remove acidic gases like H2S and CO2 from natural gas, ensuring its quality for pipeline transport and industrial use.
- Industrial Waste Treatment:These systems manage and recover valuable components or neutralize hazardous substances from industrial wastewater streams.
- Ammonia Recovery:This application focuses on extracting and purifying ammonia from process effluents, often for reuse within industrial cycles.
Mass market demand centers on Fertilizer Production; Petrochemical Processing shows significant margin potential.
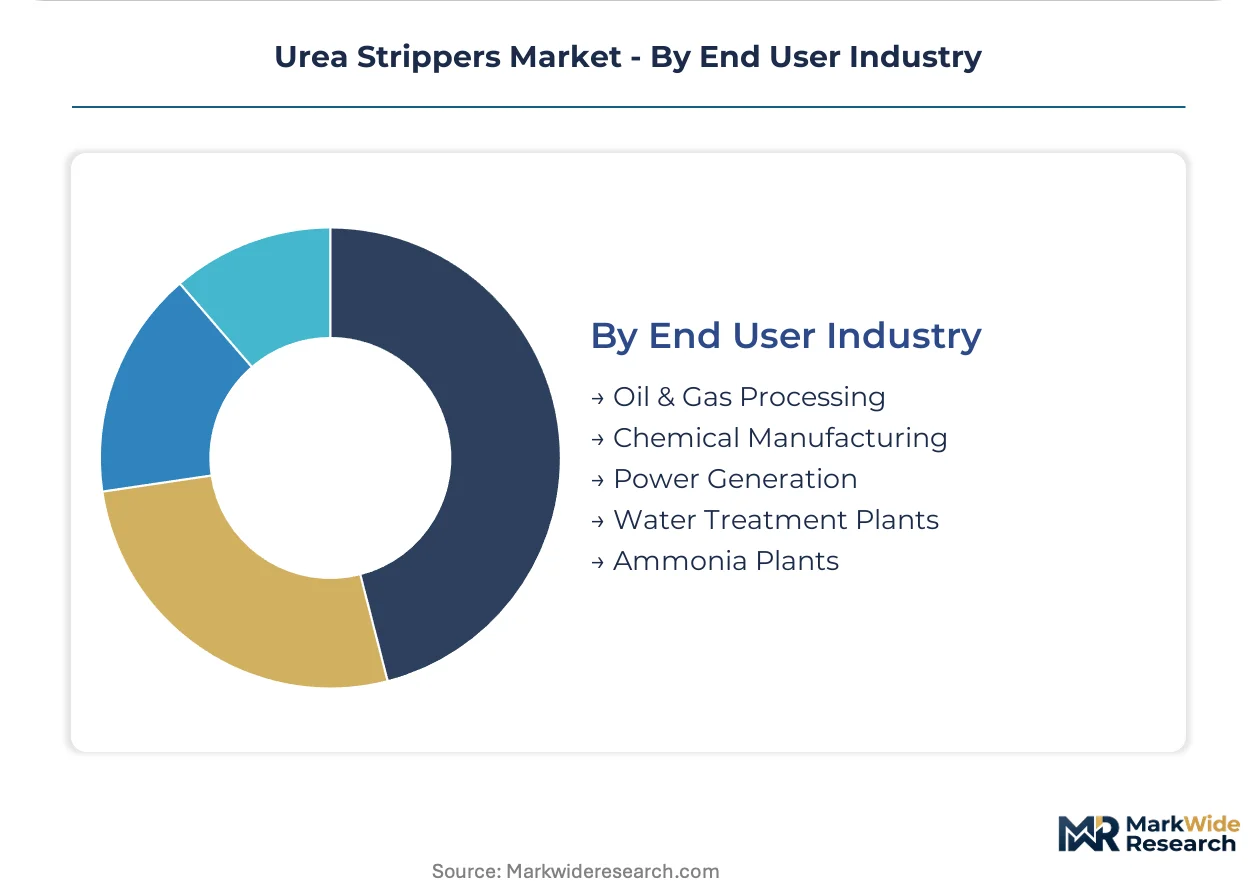
End User Industry:
The type of end-user industry directly shapes the procurement patterns and technological specifications for urea strippers, reflecting specialized operational needs and regulatory compliance requirements. Each industry has distinct material and design preferences.
- Ammonia Plants:These facilities are primary consumers of urea strippers, directly integrating them into the urea synthesis process to maximize conversion rates. Indian ammonia manufacturers are investing in advanced strippers for enhanced output and energy savings.
- Chemical Manufacturing:The broader chemical industry utilizes strippers for various separation and purification processes, including ammonia recovery and solvent regeneration. European chemical producers prioritize energy-efficient designs to meet EU Green Deal objectives.
- Oil & Gas Processing:This sector employs strippers for gas sweetening and other separation tasks within refineries and natural gas processing plants.
- Power Generation:Strippers can be found in power plants for flue gas desulfurization or water treatment applications to manage emissions.
- Water Treatment Plants:These plants use stripping technology to remove volatile organic compounds or ammonia from industrial and municipal wastewater.
Core demand originates from Ammonia Plants; Chemical Manufacturing is diversifying its stripper applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for urea strippers varies significantly, with India's volume-driven demand contrasting with Europe's premium segment. This asymmetry influences investment cycles and technology adoption across different continents. Plant operators in each region navigate distinct regulatory and economic landscapes.
India
Rising food demand necessitates the expansion and modernization of domestic urea manufacturing capacity. The Indian government's emphasis on self-sufficiency in fertilizers drives investment in new facilities and revamping projects. Major fertilizer complexes in Gujarat and Uttar Pradesh are actively adopting advanced stripper technologies for enhanced output.
China
China's Ministry of Ecology and Environment (MEE) standards for nitrogen oxide emissions compel operators to invest in modern, high-efficiency stripper technologies. Modern urea facilities increasingly adopt vapor recompression to reduce overall energy consumption. Key industrial clusters in Shandong and Jiangsu are hubs for such technological upgrades.
Germany
Stringent environmental regulations, particularly the European Union's Industrial Emissions Directive, drive demand for superior stripper technologies. German chemical producers prioritize energy-efficient designs to meet EU Green Deal objectives. The Rhine-Ruhr chemical hub sees continuous investment in advanced corrosion-resistant materials for critical equipment.
Saudi Arabia
The expansion of petrochemical processing facilities creates significant demand for stripping technology to recover ammonia from various streams. Saudi Vision 2030 initiatives promote industrial diversification and resource valorization. Jubail Industrial City and Yanbu are key centers for new plant construction and technology adoption.
United States
Modernization of aging chemical plants and increasing focus on energy efficiency drive investment in advanced stripper units. Environmental Protection Agency (EPA) regulations for industrial emissions influence equipment selection. The Gulf Coast chemical corridor remains a primary region for revamping projects and new installations.
Urea Strippers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in the urea strippers market. The competitive structure features a tiered landscape, with specialized technology licensors dominating high-value designs and large engineering, procurement, and construction (EPC) firms managing complex project execution. Vertically integrated heavy engineering manufacturers compete on scale and fabrication capabilities. Key competitive moves include strategic partnerships for project delivery and continuous innovation in material science.
On the premium-tier vector, Stamicarbon, a Dutch-based technology licensor, exemplifies proprietary stripping process designs that maximize urea yield. Large engineering, procurement, and construction firms like Saipem S.p.A., an Italian company, occupy a position for turnkey plant installations, leveraging global supply chain capabilities. Indian heavy engineering conglomerate Larsen & Toubro anchors the market for manufacturing critical equipment, often integrating local fabrication strength into project delivery.
| Leading Market Players |
|---|
| Larsen & Toubro |
| Saipem S.p.A. |
| Stamicarbon |
| Urea Casale |
| TOYO Engineering India Private Limited |
| Isgec Heavy Engineering Ltd |
| ALFA LAVAL |
| thyssenkrupp |
| Sandvik AB |
| Others |
Cost & Logistics Intelligence
The European Union's Industrial Emissions Directive directly gates supply qualification for advanced urea strippers and drives price differentiation for compliant, energy-efficient designs. This regulatory framework mandates investment in superior technologies, impacting equipment costs and availability.
Pricing Analysis
Configured-to-order pricing commands a premium in the urea strippers market. Project-based and licensing/royalty models dominate, reflecting the bespoke nature of plant installations. Customization level for integration into existing plants and the certification level for advanced corrosion-resistant materials are key differentiation drivers. Pricing softness stems from intense competition among EPC firms for large-scale greenfield projects. Ammonia plants in capital-constrained markets exhibit high price sensitivity, while European chemical producers prioritize performance over initial cost.
Supply Chain Analysis
Strategic-stockpile preferences for critical long-lead components characterize the urea strippers supply chain. China, India, and Germany concentrate manufacturing capabilities for heavy engineering equipment and specialized alloys. High-grade stainless steels, titanium, and specialized corrosion-resistant alloys are critical inputs for these components. Commodity price volatility for these advanced materials represents a structural risk. Distribution runs through a direct-to-customer model, primarily via EPC firms and technology licensors managing turnkey projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urea strippers market requires a robust substitution defense against alternative ammonia recovery technologies. Incumbents must navigate the threat posed by novel membrane separation techniques in petrochemical processing.
For Market Incumbents:
Shield market share by deepening vertical integration into advanced material fabrication. Invest in continuous R&D for next-generation corrosion-resistant alloys and expand manufacturing capacity in strategic regions like India. This counters the margin pressure from rising raw material costs and new entrants offering lower-cost alternatives. Control over critical component supply provides a competitive advantage against technology licensors.
For New Entrants and Emerging Players:
Certification fast-track programs for specialized components offer a pathway for new entrants. Target the modernization of aging plants in Eastern Europe and Southeast Asia by offering cost-effective, energy-efficient structured packing solutions. Partner with local engineering firms to provide integrated revamp packages. The ammonia recovery segment in industrial waste treatment represents a penetrable niche for focused offerings.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large heavy engineering conglomerates with specialized fabrication units. The market offers long-term viability over a 5-10 year window, driven by sustained global fertilizer demand and environmental regulations. Seek out mid-sized technology licensors possessing proprietary high-pressure stripping designs. The signal to watch is the increasing adoption rate of advanced material lifecycle services, indicating a shift towards long-term asset management.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply of critical components for high-pressure strippers. |
| Technology Licensing Agreements | Accelerates market penetration for advanced energy-saving technologies. |
| Green Manufacturing Transition | Aligns with global environmental mandates and enhances brand reputation. |
| Advanced Material R&D | Extends equipment lifespan and reduces maintenance costs for plant operators. |
| Integrated Project Delivery Model | Streamlines project execution and reduces risk for plant owners. |
Research Approach
Operator-level perspectives from plant managers, procurement leads, and process engineers anchored the qualitative base of this study. Primary interviews with industry stakeholders combined with secondary validation from trade publications and regulatory reports. Directors of R&D, EPC project managers, and material science experts provided critical insights. Customs data, industrial association reports, and company annual filings supplemented primary findings. A bottom-up and top-down triangulation approach ensured data accuracy.
Sensitivity analysis informed the quantitative modeling for the urea strippers market. The analytical framework projected market dynamics across the analysis window, considering segmentation by product type, technology, application, and material grade. Compound annual growth rates were derived from historical trends and anticipated technological advancements. Key forecast inputs included global fertilizer consumption trends and industrial emissions regulatory changes.
Underlying assumptions cover stable geopolitical conditions and consistent agricultural policies, with deviation risk concentrated in raw material price shocks. Unexpected shifts in global energy prices or rapid regulatory changes for industrial emissions could impact projections. Revision becomes warranted when major new plant construction projects are delayed or canceled.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Ionophores Market