
 Cryogenic Column Market | 2026-2036
Cryogenic Column Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Column Market Analytics
Project logistics for oversized cryogenic equipment is rewriting how buyers secure column assemblies across continents. Linde plc leverages its captive fleet of specialized transport vessels to sustain delivery timelines for remote LNG sites. Air Liquide anchors European supply through integrated engineering-to-installation contracts. Chart Industries Inc. competes on modular fabrication, positioning prefabricated column skids that cut field construction hours.
A cryogenic column is a thermally insulated vertical vessel engineered to separate gas mixtures at temperatures below minus 150 degrees Celsius through controlled phase equilibrium, typically fabricated from austenitic stainless steel or aluminum alloys with multi-layer vacuum insulation. These systems enable industrial-scale extraction of pure oxygen, nitrogen, and argon from atmospheric air, or liquefaction and fractionation of natural gas into transportable LNG. Fractionation columns command the largest installed base due to their centrality in air separation units, while cryogenic heat exchangers represent the fastest-growing product category as LNG train capacities scale. Gas separation applications dominate current revenue, though medical applications are deepening margin pools through ultra-high-purity specifications for pharmaceutical manufacturing and biobanking.
The EPA enforces leak detection and repair standards for cryogenic systems handling fluorinated gases, compelling upgrades to sealed column architectures. OSHA mandates process safety management for facilities operating below cryogenic thresholds, shaping plant design and operator certification requirements. China's MEE implements dual carbon goals that restrict energy intensity in air separation operations, filtering market access toward efficient designs. Stakeholders must monitor how evolving containment standards in multiple jurisdictions reshape total cost of ownership calculations and supplier qualification criteria.
Market Dynamics
The EU F-Gas Regulation is tightening containment standards for industrial cooling applications, forcing a wholesale redesign of column sealing architectures and vapor recovery systems across European air separation facilities.
Growth Catalysts
- Dual carbon goals in China:The MEE mandates energy intensity reductions in air separation operations, filtering market access toward high-efficiency column designs with advanced insulation systems.
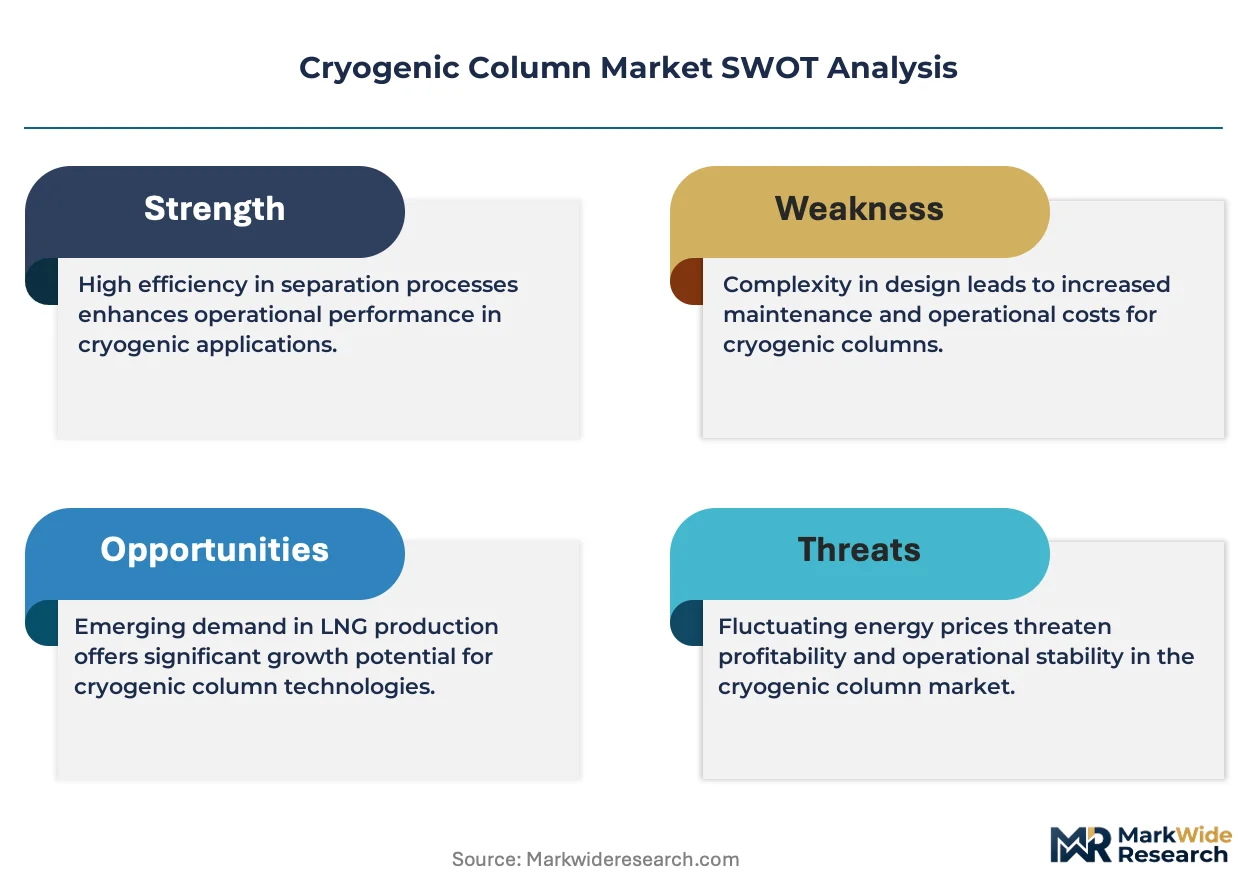
- LNG processing expansion:Gulf Coast facilities are scaling procurement of cryogenic fractionation systems to handle rising natural gas export volumes.
- Biobanking infrastructure:Ultra-high-purity specifications for pharmaceutical manufacturing and cell therapy storage are deepening margin pools in medical-grade gas separation.
Market Restraints
- Nickel alloy cost volatility:Austenitic stainless steel and aluminum alloy input prices swing with mining output, compressing fabrication margins unpredictably.
- Specialized transport bottleneck:Oversized column assemblies require captive fleets of cryogenic vessels, concentrating delivery capacity with integrated engineering groups.
- Fluorinated gas containment:EPA leak detection standards impose sealed architecture upgrades that extend project timelines and certification costs.
Strategic Opportunities
- Modular skid fabrication:Prefabricated column systems cut field construction hours and enable remote site deployment without established infrastructure.
- State-backed air separation:China's domestic manufacturing capacity expansion creates procurement openings for engineering-to-installation contractors.
- ISO 14644 cleanroom convergence:Pharmaceutical-grade nitrogen and argon specifications are merging semiconductor and medical purity standards, unifying certification pathways.
Industry Challenges
- Cryogenic welder scarcity:Qualified technicians for austenitic stainless assembly command premium wages and extended lead times, constraining fabrication throughput.
- Process safety management compliance:OSHA mandates for sub-cryogenic operations require operator certification programs that extend commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Column Market |
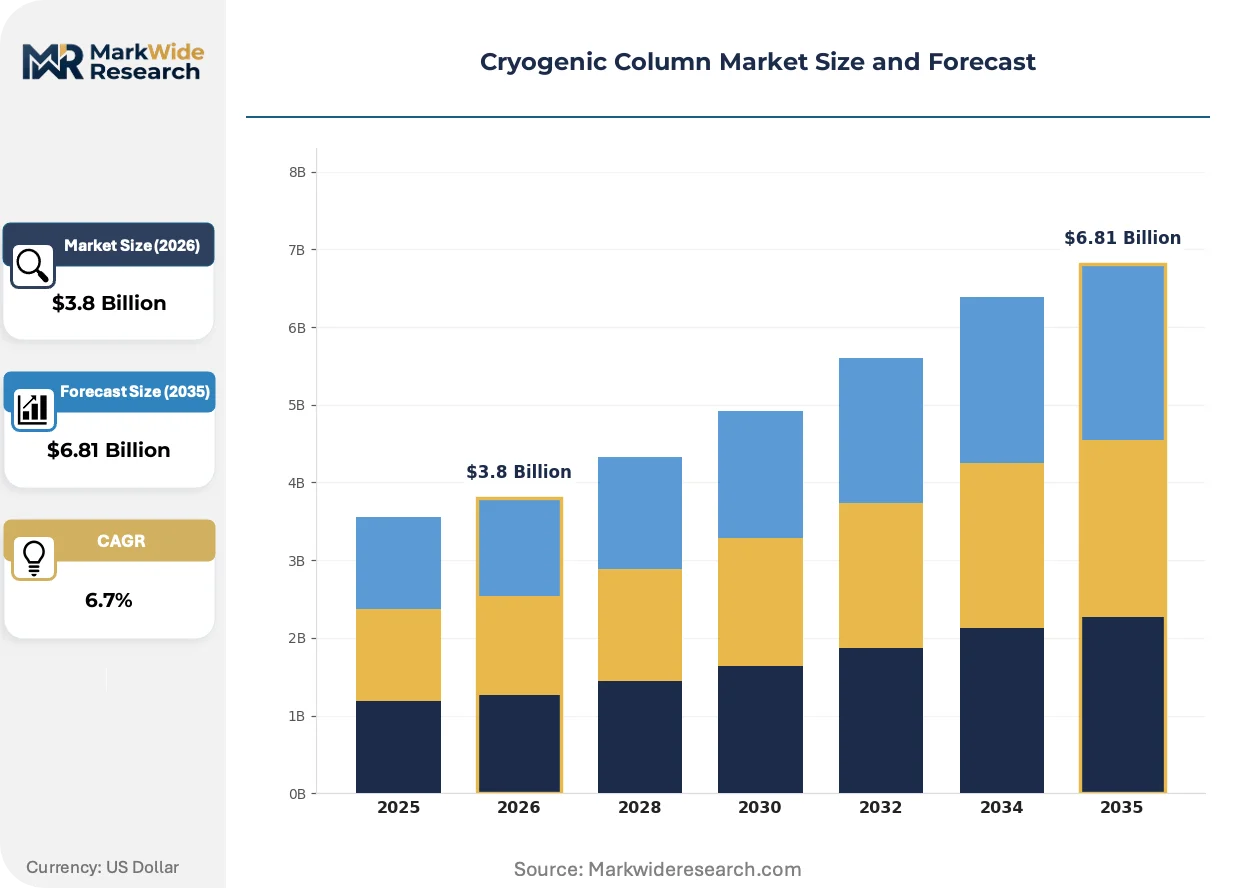
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fractionation Columns, Storage Columns, Cryogenic Heat Exchangers, Dewar Flasks Application: Gas Separation, LNG Processing, Industrial Cooling, Medical Applications End User: Energy Sector, Healthcare Providers, Research Institutions, Manufacturing Units Technology: Vacuum Insulation, Cryostat Systems, Thermal Control Mechanisms, Heat Transfer Technologies |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Chart Industries Inc., TAIYO NIPPON SANSO CORPORATION, Messer, INOX India Limited, Nikkiso Co. Ltd., KaiFeng Air Separation Group Co., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Column Market Evolving Landscape
Column architecture is compressing toward compact, modular formats while regulatory pressure on fluorinated gas containment accelerates sealed-system redesigns across major industrial clusters.
Additive manufacturing of nickel superalloy column internals is collapsing lead times for complex heat exchanger geometries. LNG train operators are adopting printed distillation trays to replace machined assemblies. This fabrication shift is collapsing the traditional 18-month delivery window for large fractionation columns into sub-12-month cycles.
The EU F-Gas Regulation mandates progressive fluorinated gas phase-downs through 2030. Industrial cooling applications must demonstrate near-zero leak rates or face operating restrictions. Air separation units across Germany, France, and the Netherlands are retrofitting magnetic-bearing turboexpanders and hermetically sealed cold boxes to maintain compliance.
Buyers are unbundling after-sales service from initial equipment contracts. Large industrial gas consumers in the United States are negotiating separate maintenance agreements with third-party specialists rather than captive service arms. This purchasing fragmentation is most visible among Gulf Coast LNG operators seeking to diversify operational risk across multiple service providers.
Cryogenic Column Market Segmentation
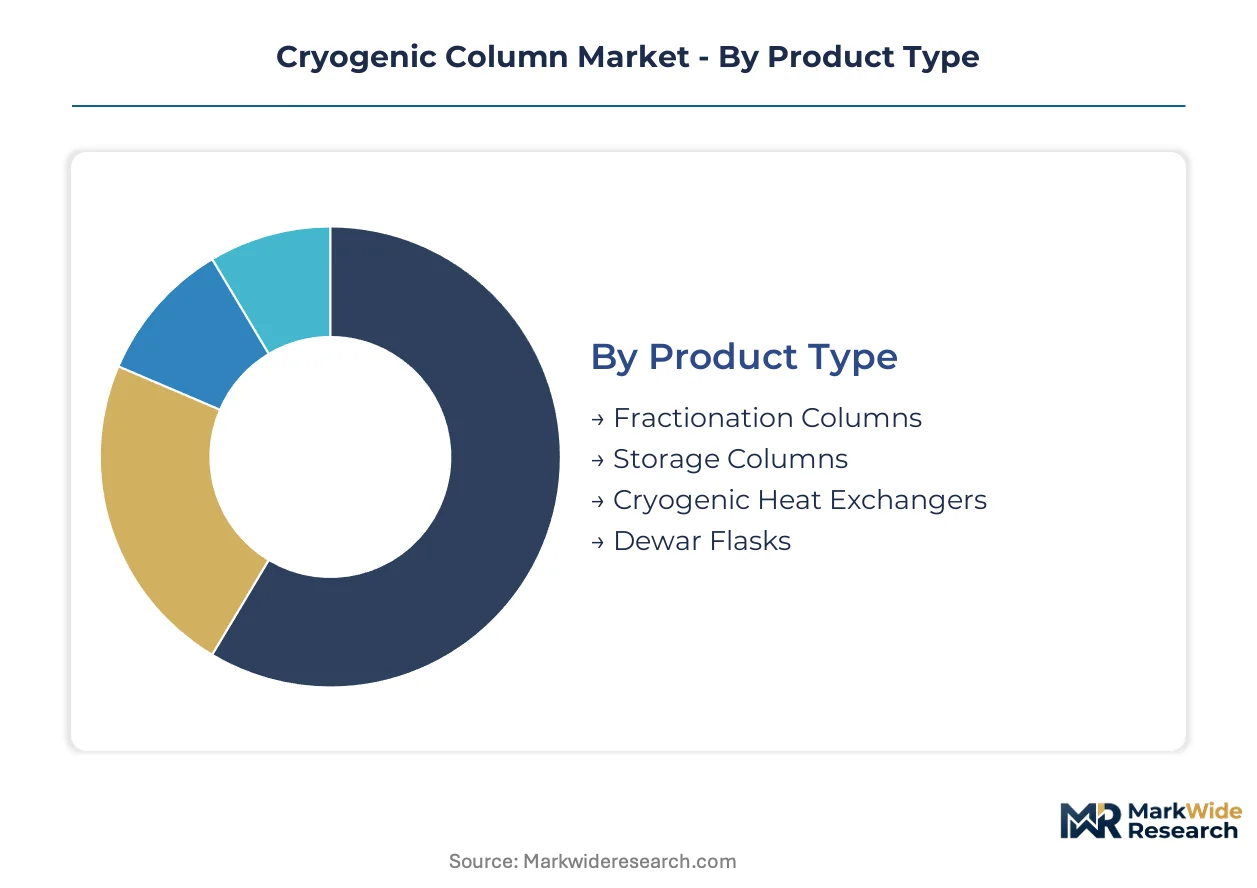
Cryogenic column procurement patterns diverge sharply across product architectures and end-use specifications. Buyers in LNG processing prioritize fractionation throughput, while medical gas consumers demand purity certification tiers that reshape supplier qualification criteria.
Product Type:
Use cases span from massive air separation trains to portable laboratory storage, with each architecture demanding distinct fabrication competencies and insulation systems.
- Fractionation Columns:These multi-stage distillation vessels separate atmospheric gases through controlled temperature gradients across packed or trayed internals. Demand concentrates in China where state-backed air separation projects scale domestic manufacturing capacity, with MEE energy intensity mandates filtering procurement toward high-efficiency designs.
- Cryogenic Heat Exchangers:Compact aluminum plate-fin or coil-wound geometries maximize thermal transfer in minimal footprint for LNG liquefaction cycles. Gulf Coast export facilities are scaling procurement to handle rising natural gas volumes, with printed distillation tray adoption collapsing traditional delivery windows.
- Storage Columns:Vertical vessels with multi-layer vacuum insulation maintain liquid nitrogen or oxygen at minus 150 degrees Celsius for industrial buffer storage.
- Dewar Flasks:Portable double-walled containers with superinsulation enable laboratory-scale cryogenic fluid handling and biological sample transport.
The dominant share belongs to fractionation columns, while cryogenic heat exchangers are closing the gap fastest.
Application:
Customer requirements fragment across purity thresholds, with pharmaceutical specifications diverging from industrial bulk gas standards.
- Gas Separation:Air separation units extract tonnage quantities of oxygen, nitrogen, and argon through cryogenic distillation of liquefied atmospheric air. Energy sector procurement dominates volume, though EPA leak detection standards compel sealed architecture upgrades that extend project timelines.
- LNG Processing:Fractionation trains liquefy and purify natural gas for marine transport, with pretreatment columns removing CO2, mercury, and heavy hydrocarbons. Gulf Coast facilities anchor North American demand as export terminal capacity expands.
- Industrial Cooling:Process refrigeration systems leverage cryogenic fluids for rapid temperature reduction in chemical synthesis and food processing operations.
- Medical Applications:Ultra-high-purity nitrogen and argon serve pharmaceutical manufacturing and biobanking infrastructure, with ISO 14644 cleanroom convergence unifying semiconductor and medical certification pathways.
Gas separation commands the largest installed base, while medical applications are expanding most quickly through purity premium capture.
End User:
Procurement authority concentrates differently across sectors, with integrated energy majors wielding volume leverage against fragmented research laboratory demand.
- Energy Sector:Oil and gas supermajors and independent LNG developers specify column trains with 25-plus year operational life and modular expansion capability. Chinese state-owned enterprises are scaling domestic manufacturing capacity through engineering-to-installation contracts.
- Healthcare Providers:Hospital systems and pharmaceutical manufacturers demand medical-grade gas separation with batch traceability and contamination documentation. Biobanking infrastructure investments are deepening margin pools through ultra-high-purity specifications.
- Research Institutions:National laboratories and university facilities require flexible-scale cryogenic systems for materials science and particle physics applications.
- Manufacturing Units:Steel, chemical, and electronics fabs consume industrial gases in continuous processes with uptime-critical supply contracts.
Energy sector buyers dominate contract value, while healthcare providers are gaining share fastest through specification escalation.
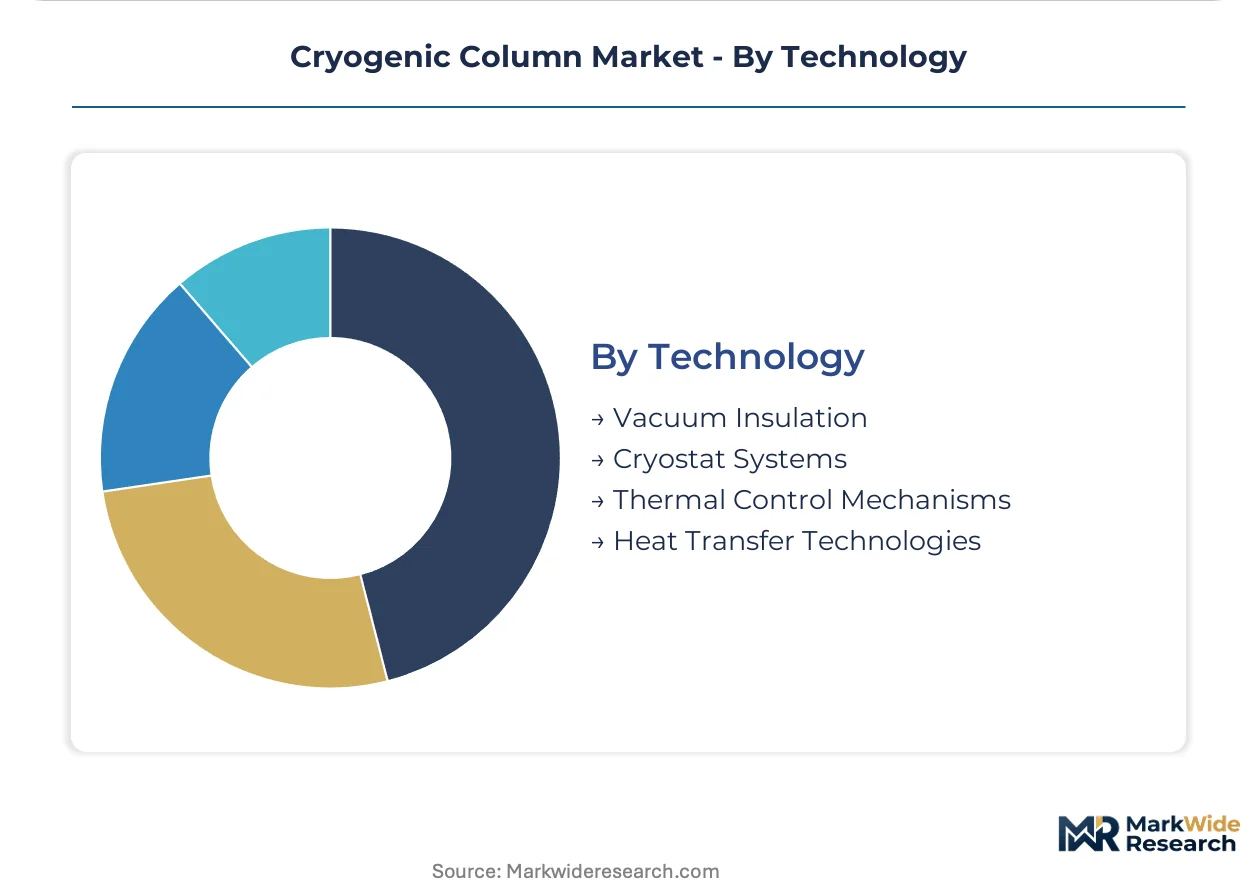
Technology:
Thermal performance differentiation hinges on insulation architecture selection and active cooling system integration.
- Vacuum Insulation:Multi-layer reflective shielding in evacuated annular spaces minimizes radiative and convective heat leak for long-duration storage. EU F-Gas Regulation containment standards are forcing redesign of sealing architectures across European installations.
- Cryostat Systems:Integrated vessel-cooler assemblies maintain sub-cryogenic temperatures through closed-cycle refrigeration or liquid cryogen boiloff. Research institutions in Germany and France are retrofitting magnetic-bearing turboexpanders to maintain compliance with progressive fluorinated gas phase-downs.
- Thermal Control Mechanisms:Active temperature regulation systems enable precise setpoint maintenance for sensitive biological or electronic payloads.
- Heat Transfer Technologies:Enhanced surface geometries and phase-change materials optimize thermal exchange efficiency in compact footprints.
Vacuum insulation retains the dominant installed base, while cryostat systems are climbing the fastest through hermetic sealing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast's liquefaction corridor anchors United States demand, with Corpus Christi-to-Lake Charles pipeline networks feeding export terminal expansions. China's Yangtze River Delta and Pearl River Delta industrial clusters concentrate air separation manufacturing scale. Germany's Ruhr industrial belt and Netherlands' Rotterdam-Antwerp port complex anchor European retrofit cycles for fluorinated gas compliance.
United States
Gulf Coast LNG export terminals at Sabine Pass and Freeport drive fractionation column procurement for natural gas liquefaction trains. EPA leak detection standards under the Clean Air Act compel sealed architecture upgrades at existing air separation facilities. The Houston Ship Channel industrial corridor concentrates engineering-to-installation contractors serving both energy and petrochemical gas consumers.
China
State-backed air separation projects in Jiangsu and Zhejiang provinces scale domestic manufacturing capacity for tonnage oxygen and nitrogen production. MEE dual carbon goals mandate energy intensity reductions that filter procurement toward high-efficiency column designs with advanced vacuum insulation. The Yangtze River Delta cluster anchors captive fabrication of cryogenic heat exchangers for LNG and industrial gas applications.
Germany
Industrial gas consumers in the Ruhr region and Bavarian chemical corridor retrofit air separation units for EU F-Gas Regulation compliance on fluorinated gas containment. ECHA enforcement of progressive phase-downs through 2030 forces magnetic-bearing turboexpander adoption and hermetically sealed cold box redesigns. The Cologne-Düsseldorf industrial belt concentrates engineering specialists executing sealed-system retrofits.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region demand ultra-high-purity nitrogen and argon for advanced lithography processes. METI industrial gas quality standards align with ISO 14644 cleanroom convergence, unifying certification pathways for pharmaceutical and electronics applications. The Osaka-Kobe industrial corridor anchors cryogenic equipment engineering for export to Southeast Asian LNG projects.
Netherlands
Rotterdam port industrial gas terminals and Antwerp chemical cluster operations drive vacuum-insulated storage column demand for buffer inventory management. EU F-Gas Regulation containment standards force vapor recovery system upgrades across European air separation facilities serving the Benelux chemical sector. The Port of Rotterdam's LNG import and bunkering infrastructure anchors cryogenic heat exchanger maintenance and replacement cycles.
Cryogenic Column Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on fabrication and insulation subsystems. Market structure concentrates around integrated industrial gas majors with captive engineering capabilities, while mid-scale fabricators compete on modular skid delivery timelines. Two strategic archetypes dominate: vertically integrated gas majors bundling equipment with long-term supply contracts, and independent fabricators selling engineered-to-order columns on specification. Competitive moves center on additive manufacturing adoption for heat exchanger internals and geographic expansion through engineering-to-installation partnerships.
Among European-integrated industrial gas groups, Linde plc and Air Liquide exemplify platform-tier positioning through captive project execution capabilities. Chart Industries Inc. represents the independent fabricator archetype, competing on modular column skid formats that compress field construction schedules. Japanese industrial gas specialists including TAIYO NIPPON SANSO CORPORATION occupy positions bridging system integration and regional equipment supply.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Chart Industries Inc. |
| TAIYO NIPPON SANSO CORPORATION |
| Messer |
| INOX India Limited |
| Nikkiso Co. Ltd. |
| KaiFeng Air Separation Group Co., LTD. |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor concentrates oversized cryogenic column transport costs, compressing fabrication margins for remote LNG sites while enabling Gulf Coast suppliers to extract volume premiums from inland buyers lacking captive logistics fleets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade nitrogen specifications from industrial bulk gas contracts. Price differentiation hinges on ISO 14644 cleanroom certification tier and after-sales service bundling duration. Cost compression in standard-grade fractionation columns is intensifying because nickel alloy input volatility feeds through austenitic stainless steel procurement. Healthcare providers demonstrate lowest price sensitivity due to biobanking purity mandates, while steel manufacturing units negotiate aggressively on tonnage oxygen supply contracts.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for cryogenic heat exchanger procurement. Manufacturing concentrates in China, Germany, and the United States for vacuum-insulated vessel fabrication. Raw material dependencies draw from Indonesian nickel mining, Australian bauxite refining, and domestic specialty steel rolling capacity. Single-source vulnerability concentrates in qualified cryogenic welder labor pools across the Ruhr industrial belt. Distribution runs through engineering-to-installation contractors bundling field construction with equipment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales maintenance agreements are expanding faster than hardware sales as Gulf Coast LNG operators unbundle service from initial equipment contracts, creating recurring revenue pools that outpace capital expenditure cycles.
For Market Incumbents: Pre-empt additive manufacturing disruption by securing exclusive heat exchanger geometry patents before printed distillation tray adoption accelerates. Lock in cryogenic welder apprenticeship pipelines across German and Chinese fabrication hubs to constrain competitor throughput expansion. Vertical integration into nickel alloy trading desks hedges input cost volatility threatening margin stability.
For New Entrants and Emerging Players: Pursue modular skid fabrication contracts for remote LNG sites lacking established infrastructure, where field construction hour reduction commands specification premiums. Target Chinese state-backed air separation projects in Jiangsu province seeking engineering-to-installation partnerships with domestic manufacturing capacity. Lead with additive manufacturing capability to collapse traditional 18-month delivery windows.
For Investors and Strategic Acquirers: Independent fabricators with captive cryogenic transport vessel fleets represent the most defensible acquisition archetype in a logistics-constrained market. Long-term viability centers on service-attach revenue durability as hardware commoditization accelerates across standard-grade industrial gas separation. Monitor EPA leak detection standard enforcement intensity as the inflection signal for sealed architecture upgrade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Adoption | Printed nickel superalloy heat exchanger geometries collapse traditional 18-month column delivery timelines. |
| Backward Integration into Nickel Trading | Australian and Indonesian mining exposure hedges austenitic stainless steel input cost volatility. |
| Hermetic Sealing System Retrofit | EU F-Gas Regulation compliance mandates magnetic-bearing turboexpander installation across German air separation units. |
| Modular Skid Fabrication Scale-Up | Prefabricated column systems enable remote site deployment without established Gulf Coast infrastructure. |
| After-Sales Service Unbundling | Separate maintenance agreements diversify operational risk for LNG operators seeking multi-provider coverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cryogenic equipment procurement managers at Gulf Coast LNG terminals, air separation plant engineers in the Yangtze River Delta, and aftermarket service directors at European industrial gas majors. Secondary validation drew from EPA Clean Air Act enforcement databases, EU ECHA fluorinated gas phase-down filings, and MEE dual carbon goal implementation notices. Bottom-up fabrication capacity surveys triangulated against top-down LNG train investment pipelines.
Calibration against historical capacity utilization rates and announced project development timelines anchored volume projections across the analysis window. Segmentation dimensions spanned product architecture, application purity tier, end-user procurement authority, and insulation technology selection. CAGRs were derived from regression against energy intensity mandates and export terminal commissioning schedules. Nickel alloy price volatility indices and cryogenic welder wage trajectories fed specialized forecast sensitivity layers.
Sensitivities concentrate around EPA enforcement intensity variations, EU F-Gas Regulation timeline accelerations, and Chinese MEE mandate implementation pacing. Forecasts reflect documented assumptions on additive manufacturing adoption curves and modular fabrication penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market