
 Acrylic Flooring Adhesives Market | 2026-2036
Acrylic Flooring Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Flooring Adhesives Market Outlook
ISO 14001 environmental management certification is unwinding competitive access across the acrylic flooring adhesives supply base, filtering out smaller compounders lacking documented lifecycle controls. Henkel leverages its adhesive chemistry heritage to sustain specification relationships with European flooring contractors. Sika anchors its position through integrated distribution of subfloor preparation and bonding systems. Dow competes on monomer backward integration, controlling captive supply of acrylic raw materials across multiple industrial adhesive lines.
Acrylic flooring adhesives are pressure-sensitive or structural bonding compounds formulated from acrylic polymer emulsions, typically exhibiting tack-free times under 30 minutes and shear strengths exceeding 2.0 N/mm² for resilient flooring applications. Their primary purpose is to bond vinyl, rubber, carpet, and wood flooring substrates to prepared concrete, plywood, or existing floor surfaces while accommodating residual moisture and thermal movement. Water-based formulations dominate volume due to lower volatile organic compound profiles and compatibility with green building certification schemes, while reactive systems capture premium margin pools in heavy-traffic commercial installations. Solvent-based adhesives retain niche industrial utility where rapid solvent flash-off enables accelerated production line throughput, though regulatory pressure continues narrowing this segment.
EPA VOC regulations, REACH substance restrictions, and California Air Resources Board standards collectively constrain permissible solvent content and mandate disclosure of hazardous air pollutants in flooring adhesive formulations. ECHA classification of specific acrylic monomers as skin sensitizers has triggered reformulation investments among suppliers serving EU member states. Stakeholders must monitor evolving state-level VOC thresholds in the US and pending MEE emission standards in China, as these frameworks will determine which formulation platforms remain viable across the largest volume markets.
Market Dynamics
Water-based acrylic emulsion technology is compressing solvent-borne capacity as contractors face tightening VOC thresholds across major specification markets. This formulation pivot is redrawing supplier economics and tightening certification requirements for compounders serving commercial flooring channels.
Growth Catalysts
- EPA VOC Phase-2 Limits:US federal emission ceilings for architectural coatings are accelerating contractor migration to compliant water-based systems in commercial new-build and renovation segments.
- Modular Construction:Prefabricated building methods in Germany and the United States are demanding rapid-cure adhesive platforms that enable same-day flooring installation within factory-controlled environments.
- Residual Moisture Tolerance:Advanced acrylic polymer chemistry now permits direct bonding to concrete slabs with elevated moisture content, eliminating costly surface preparation steps in high-humidity climates.
Market Restraints
- Acrylic Monomer Volatility:Propylene and acrylic acid feedstock costs swing with petrochemical refining margins, compressing formulation margins for non-integrated compounders.
- ECHA Skin Sensitizer Classification:Specific acrylate monomers now carry mandatory hazard labeling under EU CLP regulation, forcing reformulation investments and supply chain requalification.
- Polyurethane Substitution:Two-part PU systems retain specification lock-in for heavy-traffic healthcare and aviation installations where shear strength requirements exceed acrylic performance ceilings.
Strategic Opportunities
- India Green Building Council Certification:LEED-equivalent rating systems are mandating low-emission interior materials, opening specification pathways for water-based acrylic platforms in commercial real estate development.
- Digital Moisture Monitoring Integration:Smart subfloor sensors paired with adhesive selection algorithms are creating bundled service opportunities for technical distributors serving large-scale flooring contractors.
- Retrofit-First Urban Policies:Building renovation mandates in Germany and France are redirecting construction activity toward adhesive-intensive flooring replacement versus new substrate preparation.
Industry Challenges
- ISO 14001 Documentation Burden:Smaller compounders lack lifecycle assessment infrastructure to meet environmental management certification now required by major European flooring distributors.
- Multi-Standard Compliance Parallelism:Simultaneous adherence to EPA VOC rules, REACH substance restrictions, and California Air Resources Board thresholds fragments R&D resources and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Flooring Adhesives Market |
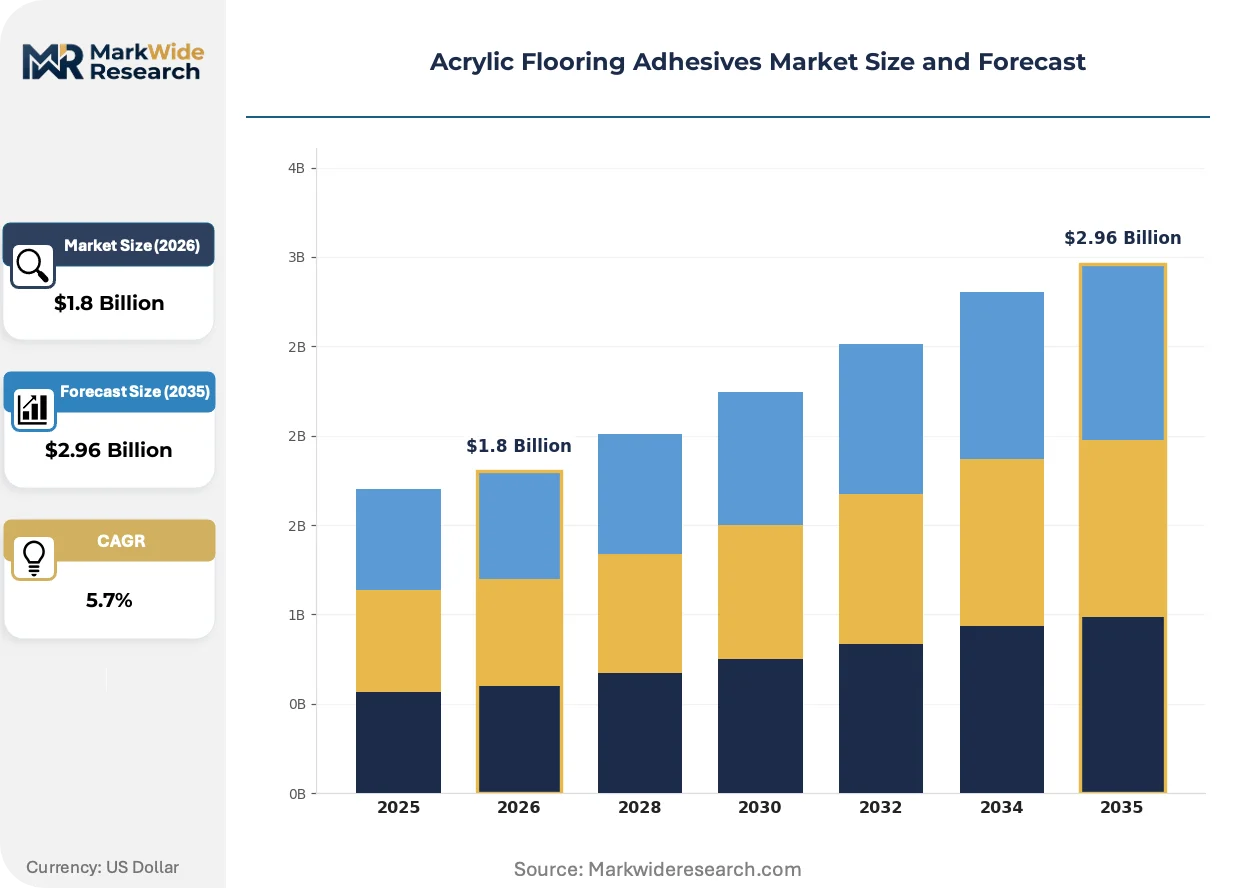
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Reactive, Hot Melt Application Area: Residential, Commercial, Automotive, Industrial Formulation Type: Single-Component, Multi-Component, Pre-Mixed, Additive-Enhanced End User: Contractors, Builders, DIY Enthusiasts, Flooring Retailers |
| Companies Covered | Henkel, H.B. Fuller, Sika, MAPEI, Arkema, 3M, Dow, Wacker Chemie, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Flooring Adhesives Market Strategic Shifts
Formulation chemistry and installation methodology are converging to compress project timelines while satisfying multi-jurisdictional emission standards. These shifts are redrawing competitive advantage around technical service capabilities rather than commodity supply.
Low-VOC water-based acrylic emulsions are displacing solvent-borne neoprene and SBR systems in resilient flooring specification. Commercial contractors in Germany and the United States are specifying these platforms for rapid-return-to-service installations in retail and hospitality verticals. This displacement is compressing demand for high-flash solvent systems and forcing legacy compounders to retool production lines or exit specification channels entirely.
REACH substance restrictions and ECHA hazard reclassifications are triggering monomer substitution programs across EU-serving supply chains. Suppliers are reformulating around exempted acrylate chemistries and investing in hazard communication infrastructure to maintain market access. Water-based platforms with documented safety data sheets are capturing specification preference over reactive systems requiring complex handling protocols.
Certification-driven procurement is consolidating buyer preference around adhesive suppliers with third-party environmental product declarations. Large commercial flooring contractors in China are pre-qualifying vendors based on MEE emission disclosure and ISO 14001 documentation ahead of project bidding. This behavioral shift is marginalizing uncertified compounders and rewarding integrated suppliers with established compliance infrastructure.
Acrylic Flooring Adhesives Market Segmentation
Acrylic flooring adhesives segment across formulation chemistry, installation setting, and buyer sophistication. Each dimension carries distinct regulatory exposure and margin profiles that reshape supplier priorities.
Product Type:
Water-based platforms face substitution pressure from reactive systems in high-performance commercial specifications, while solvent-borne capacity contracts under tightening VOC ceilings.
- Water-Based:Acrylic polymer emulsions with sub-30-minute tack-free times dominate specification-grade volume. Demand concentrates in Germany and the United States where EPA VOC Phase-2 limits and REACH emission thresholds accelerate contractor migration from solvent systems.
- Solvent-Based:Rapid-flash neoprene and SBR formulations retain niche utility in industrial production lines requiring accelerated throughput. China maintains limited solvent capacity for export-oriented manufacturing clusters, though MEE emission disclosure requirements are compressing this segment.
- Reactive:Two-part systems capture premium installations demanding shear strength above acrylic performance ceilings.
- Hot Melt:Thermoplastic acrylic formulations serve automated flooring lamination in prefabricated building modules.
Water-based retains volume leadership; reactive holds the steepest expansion curve.
Application Area:
Cost tier separation runs deepest between commercial specification work and residential renovation, with automotive and industrial occupying distinct procurement channels.
- Commercial:Rapid-cure acrylic systems bond resilient flooring in retail and hospitality verticals demanding same-day return-to-service. Germany and France drive specification volume through retrofit-first urban policies redirecting construction activity toward adhesive-intensive flooring replacement.
- Residential:DIY-friendly water-based emulsions capture renovation demand in moisture-tolerant formulations. The United States concentrates volume through big-box retail distribution serving homeowner installation.
- Automotive:Interior trim bonding applications require low-emission formulations meeting OEM material disclosure standards.
- Industrial:Heavy-traffic manufacturing floors specify reactive systems where acrylic shear strength proves insufficient.
Commercial commands the margin premium; residential delivers the widest volume base.
Formulation Type:
Customer sophistication separates single-component convenience from multi-component performance, with pre-mixed and additive-enhanced variants targeting specific installation constraints.
- Single-Component:Ready-to-use acrylic emulsions eliminate field mixing errors and accelerate contractor productivity. Demand concentrates among flooring retailers serving time-pressured renovation crews in the United States.
- Multi-Component:Two-part reactive systems deliver adjustable cure rates for large-format commercial installations. Germany anchors specification preference through integrated subfloor preparation and bonding system procurement.
- Pre-Mixed:Factory-blended formulations with documented shelf stability reduce field variability.
- Additive-Enhanced:Moisture-blocking and antimicrobial modifiers extend acrylic performance into challenging substrate conditions.
Single-component dominates unit volume; multi-component captures the specification premium.
End User:
Supply concentration varies sharply between professional contractor channels and fragmented DIY retail, with builders and flooring retailers occupying intermediate positions.
- Contractors:Commercial flooring specialists specify water-based systems with ISO 14001 documentation and third-party environmental product declarations. China pre-qualifies vendors based on MEE emission disclosure ahead of project bidding.
- Builders:Production homebuilders procure adhesive systems through national distribution agreements tied to flooring package suppliers.
- DIY Enthusiasts:Consumer-packaged acrylic emulsions with simplified application instructions capture renovation spend through retail hardware channels.
- Flooring Retailers:Technical distributors bundle adhesive selection with digital moisture monitoring services for large-scale contractor accounts.
Contractors drive specification-grade value; flooring retailers control the technical service interface.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial flooring contractors in Germany, the United States, and China concentrate specification-grade procurement, driving volume allocation toward suppliers with documented environmental certifications and rapid-cure formulation capabilities.
Germany
Retrofit-first urban policies in Berlin and Hamburg redirect construction activity toward adhesive-intensive flooring replacement rather than new substrate preparation. REACH substance restrictions and ECHA skin sensitizer classifications force reformulation investments among compounders serving EU member states. The Rhine-Ruhr industrial corridor anchors specification relationships between flooring distributors and certified adhesive suppliers.
United States
EPA VOC Phase-2 limits accelerate contractor migration to compliant water-based systems in commercial new-build and renovation segments. California Air Resources Board thresholds constrain permissible solvent content in flooring adhesive formulations. The Southeast manufacturing belt, spanning Georgia and the Carolinas, concentrates prefabricated building production demanding rapid-cure adhesive platforms.
China
MEE emission disclosure requirements compress solvent-borne capacity while opening specification pathways for water-based acrylic platforms. The Yangtze River Delta manufacturing cluster, centered on Shanghai and Jiangsu province, drives volume for export-oriented flooring production. Pre-qualification of vendors based on environmental documentation now precedes project bidding among large commercial contractors.
India
India Green Building Council certification mandates low-emission interior materials, creating specification opportunities for water-based acrylic systems in commercial real estate development. BIS standards and DGFT import regulations shape adhesive formulation requirements for domestic flooring manufacturers. The Mumbai-Pune industrial corridor concentrates demand from retail and hospitality verticals seeking rapid-return-to-service installations.
France
Building renovation mandates in Paris and Lyon redirect construction spend toward flooring replacement applications with intensive adhesive consumption. CE marking requirements and EU Green Deal implementation push specification toward lower-emission water-based platforms. The Île-de-France region anchors technical distributor networks bundling adhesive selection with digital moisture monitoring services.
Acrylic Flooring Adhesives Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive monomer supply and specialized adhesive compounders with specification-grade certification infrastructure. Market structure concentrates around three tiers: backward-integrated petrochemical majors controlling raw material economics, mid-scale European compounders with ISO 14001 documentation and distributor relationships, and regional formulators competing on price in residential renovation channels. Dominant competitive moves include portfolio diversification into water-based platforms and strategic partnerships with flooring manufacturers for co-developed installation systems.
Among integrated chemical suppliers, Dow and BASF exemplify the backward-integrated archetype with captive acrylic acid and emulsion polymerization capabilities spanning multiple industrial adhesive lines. Henkel and Sika occupy positions within the specification-focused tier, leveraging adhesive chemistry heritage and integrated subfloor preparation systems respectively to sustain contractor relationships. These four companies anchor competitive dynamics around formulation certification, environmental documentation, and rapid-cure performance claims.
| Leading Market Players |
|---|
| Henkel |
| H.B. Fuller |
| Sika |
| MAPEI |
| Arkema |
| 3M |
| Dow |
| Wacker Chemie |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Chinese acrylic acid plants shapes margin structures across water-based adhesive tiers, concentrating pricing power among backward-integrated suppliers while forcing compounders without captive monomer supply toward specification-grade differentiation to defend price floors.
Pricing Analysis
Cost-plus contracts indexed to propylene and acrylic acid spot markets dominate raw material procurement for non-integrated compounders. Three-tier pricing structure across specification-grade, commercial-grade, and economy-grade certification levels separates ISO 14001-documented systems from commodity emulsions. Cost compression in economy-grade residential channels is intensifying because of big-box retail consolidation and private-label expansion. DIY enthusiasts exhibit the highest price sensitivity, while commercial flooring contractors prioritize rapid-cure performance and environmental documentation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European flooring distributors serving rapid-cure commercial installations, while strategic stockpiling of acrylic acid and specialty monomers characterizes supplier behavior ahead of REACH substance restriction deadlines. Manufacturing concentration centers on Germany, the United States, and China, with the Rhine-Ruhr corridor, Southeast US manufacturing belt, and Yangtze River Delta anchoring emulsion polymerization capacity. Formulation rests on acrylic acid, specialty acrylate monomers, and emulsion stabilizers as critical inputs. Single-source vulnerability around ECHA-classified skin sensitizer monomers forces reformulation investments. Distribution runs through technical distributor networks bundling adhesive selection with subfloor preparation systems for contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic flooring adhesives sit in early-cycle expansion as water-based platforms displace solvent systems under tightening VOC regimes across major specification markets, with modular construction adoption accelerating rapid-cure demand.
For Market Incumbents: Compound specification relationships by deepening captive acrylic acid supply and accelerating ISO 14001 certification coverage across distributor networks. Polyurethane substitution in heavy-traffic healthcare installations threatens acrylic share in premium segments; defend through integrated subfloor-bonding system bundles and rapid-cure performance claims validated by third-party environmental product declarations. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships opens specification pathways in EU commercial channels without incumbent distributor lock-in. India Green Building Council certification requirements create white-space opportunity in Mumbai-Pune commercial real estate development. Target residential renovation through DIY-friendly single-component emulsions distributed via hardware retail partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with documented environmental management systems and established rapid-cure formulation libraries over commodity emulsion suppliers. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Acquisition target archetype: mid-scale European compounders with ISO 14001 documentation and stranded solvent-borne capacity suitable for water-based retooling. Watch MEE emission disclosure implementation in China as inflection indicator for specification-grade demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates margin structures from propylene volatility and ECHA reclassification risks. |
| Water-Based Platform Transition | REACH and EPA VOC Phase-2 compliance unlocks specification channels in Germany and US commercial markets. |
| ISO 14001 Certification Investment | Third-party environmental documentation meets pre-qualification requirements for China commercial contractor bidding. |
| Digital Moisture Monitoring Integration | Smart sensor bundling creates sticky technical distributor relationships and recurring service revenue streams. |
| Joint Venture with Flooring Manufacturers | Co-developed installation systems lock in specification preference through tested subfloor-bonding combinations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial flooring contractors, technical distributors, adhesive compounder R&D directors, and plant managers at acrylic acid production facilities. Secondary validation drew from EPA VOC regulation filings, ECHA substance restriction updates, REACH compliance databases, and trade association documentation from adhesive and flooring industry bodies. Bottom-up volume modeling triangulated against top-down value estimates derived from regional construction activity indices.
Across the projection horizon, the analytical framework segmented volume and value outputs by formulation chemistry, installation setting, buyer sophistication, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification-grade adoption rates and solvent-borne displacement curves, cross-referenced with modular construction penetration forecasts and green building certification mandates. Industry-specific inputs included residual moisture tolerance testing data and rapid-cure performance benchmarks from commercial flooring installations.
Decision-makers should treat outputs as directional under assumptions of continued VOC regulatory tightening and stable acrylic acid feedstock availability; material deviation in petrochemical refining margins or accelerated ECHA hazard reclassifications would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market