
 Slovenia Property and Casualty Insurance Market | 2026-2036
Slovenia Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Slovenia Property and Casualty Insurance Market Insights
Small business owners is collapsing as the fastest-growing buyer archetype in Slovenia's property and casualty insurance landscape, displacing traditional individual household purchasers as the primary policy origination engine. Zavarovalnica Triglav, d. d. leverages its captive agency network to dominate commercial lines across the Ljubljana basin. GRAWE Zavarovalnica, d. d. specializes in niche manufacturing and construction coverage for mid-sized enterprises in the Celje-Koper industrial belt. Allianz Slovenia competes through digital-first distribution that reduces acquisition costs for younger commercial policyholders.
Property and casualty insurance constitutes risk transfer contracts indemnifying policyholders against physical asset damage, legal liability, and business interruption losses, with premiums calibrated through actuarial modeling of frequency and severity distributions. The primary purpose spans financial protection for tangible property, motor vehicles, and third-party obligations across personal and commercial contexts. Auto insurance commands the largest premium pool among product types, reflecting Slovenia's dense vehicle ownership and mandatory third-party liability requirements. Commercial insurance is accelerating fastest as SMEs expand coverage beyond statutory minimums into business interruption and cyber liability riders. Broker distribution channels capture disproportionate margin in complex commercial placements, while direct online sales concentrate in standardized auto and home policies.
The Insurance Supervision Agency of Slovenia enforces Solvency II-aligned capital requirements that elevate barriers for smaller carriers and favor well-capitalized incumbents. EU Green Deal transition mandates are reshaping property underwriting standards, with stricter climate risk disclosure requirements affecting coverage terms for flood-exposed assets. Stakeholders must monitor how Slovenia's national recovery plan infrastructure spending redirects commercial construction insurance demand toward public-private partnership structures.
Market Dynamics
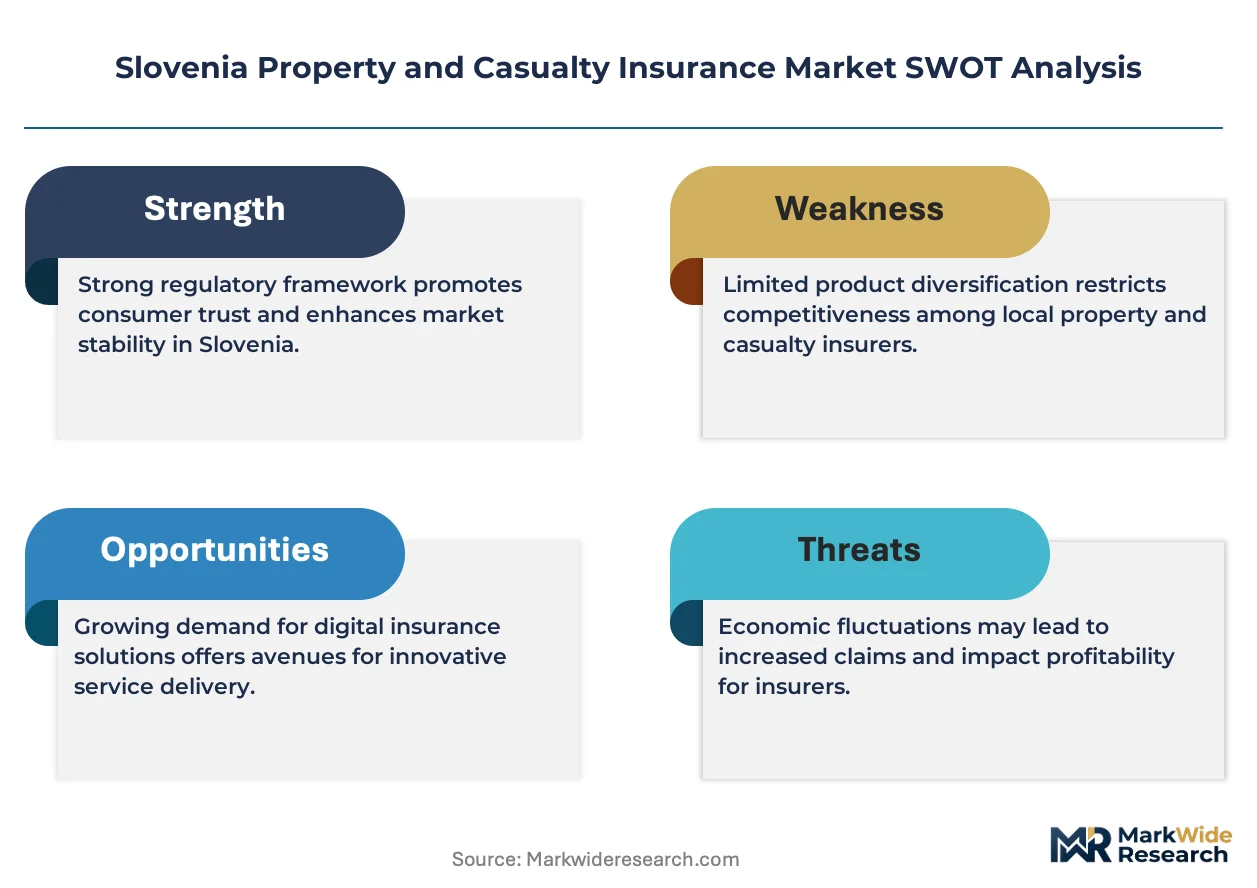
Solvenčna Insurance Supervision Agency's phased Solvency II implementation is compressing capital buffers for domestic carriers while redirecting premium flows toward reinsurance-backed underwriters with stronger balance sheets.
Growth Catalysts
- Ljubljana-Maribor logistics corridor expansion:Warehousing and distribution facility construction is generating commercial property coverage demand from 3PL operators seeking business interruption riders.
- EU Green Deal building retrofit mandates:Energy efficiency upgrade requirements for industrial assets are triggering reinstatement valuations and expanded coverage limits.
- Telematics-enabled usage-based auto:Fleet operators in the Celje basin are adopting sensor-driven premium calculations that align coverage costs with actual vehicle utilization patterns.
Market Restraints
- Reinsurance capacity concentration:Munich and Zurich-based reinsurers control treaty capacity for Slovenian catastrophe layers, creating pricing power asymmetry for flood-exposed property portfolios.
- Actuarial data scarcity:Limited historical claims severity datasets for cyber liability lines are forcing conservative reserving assumptions that inflate quoted premiums.
- Legacy IT integration costs:Domestic carriers face seven-figure system replacement expenditures to achieve Solvency II reporting granularity.
Strategic Opportunities
- Koper port industrial zone underpenetration:Maritime logistics clusters lack specialized cargo and contingent business interruption products tailored to container throughput volatility.
- Parametric flood coverage:River-gauge-triggered settlement mechanisms eliminate loss adjustment expenses for agricultural and commercial property exposures in the Drava basin.
- Embedded distribution via banking channels:Mortgage origination workflows at Nova Ljubljanska Banka offer policy attachment points for home and contents coverage.
Industry Challenges
- Actuarial modeling talent scarcity:Solvency II internal model validation requires specialized quantitative risk expertise that domestic labor markets cannot supply.
- Climate risk disclosure timelines:EU Green Deal reporting deadlines compress the window for developing forward-looking exposure assessments for commercial property portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovenia Property and Casualty Insurance Market |
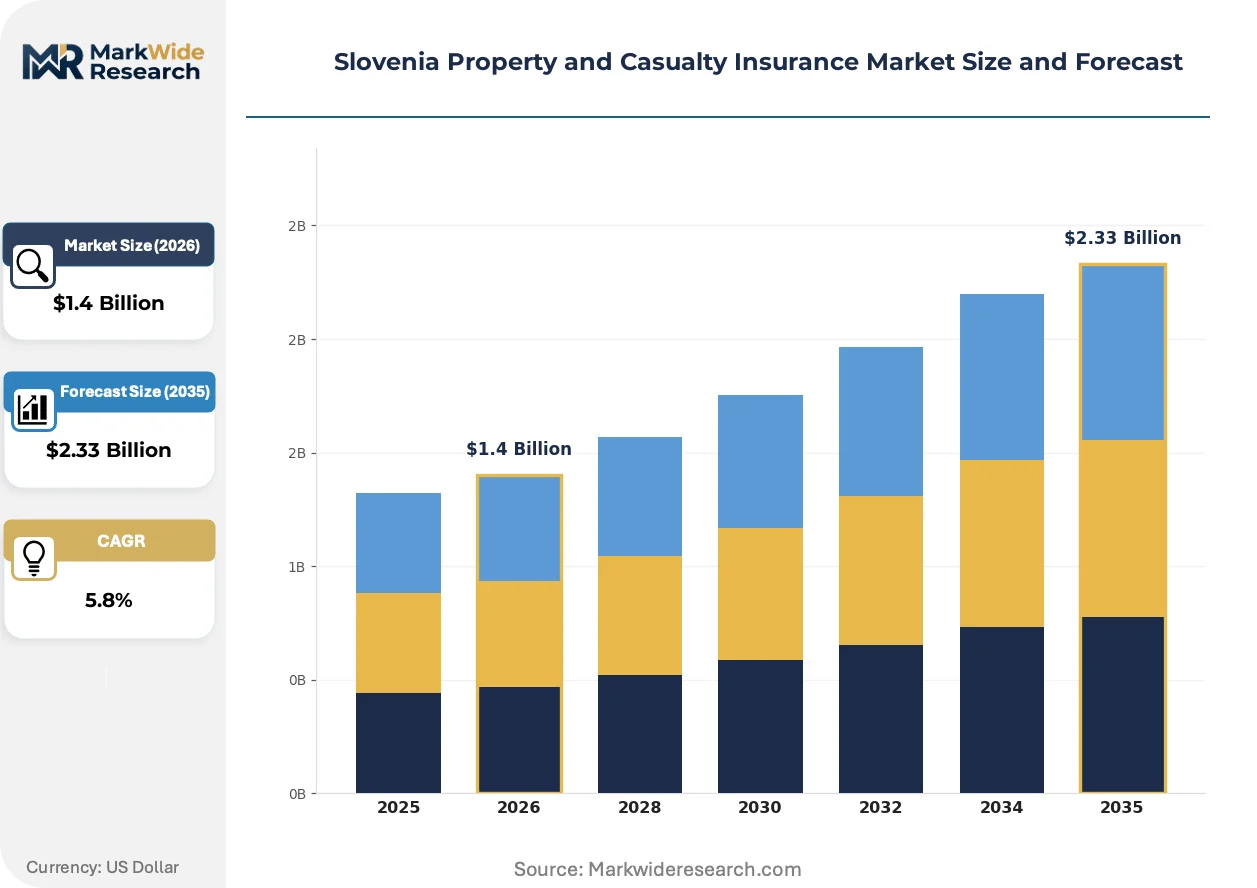
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Insurance, Auto Insurance, Liability Insurance, Commercial Insurance Customer Type: Individuals, Small Businesses, Large Corporations, Non-Profits Distribution Channel: Online, Agents, Brokers, Direct Sales Coverage Type: Comprehensive, Third-Party, Fire and Theft, Natural Disaster |
| Companies Covered | Zavarovalnica Triglav, d. d., GENNERALI zavarovalnica, d. d., Zavarovalnica Sava, d. d., Allianz Slovenia, GRAWE Zavarovalnica, d. d., Wiener Städtische zavarovalnica, d. d., Triglav Group, Sava Insurance Group, Generali Slovenija, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovenia Property and Casualty Insurance Market Trends and Innovations
Digital underwriting infrastructure is compressing policy issuance cycles from weeks to hours while fragmenting distribution power away from traditional agency networks toward embedded and direct channels.
Telematics hardware is miniaturizing to smartphone-integrable form factors that eliminate installation friction for commercial auto fleets. SME logistics operators in the Ljubljana basin are adopting these solutions fastest, lured by per-kilometer premium structures. The technology is miniaturizing capital deployment requirements for insurers, enabling direct-to-fleet digital distribution without intermediary infrastructure.
Solvency II harmonization through the Insurance Supervision Agency is mandating forward-looking capital adequacy assessments that incorporate climate stress scenarios. Domestic carriers must now model flood and drought impacts across multi-decade horizons. Commercial property underwriters are responding by tightening coverage terms for assets in the Savinja river catchment.
Small business owners are consolidating purchasing authority previously dispersed across individual household decision-makers. Broker networks in the Maribor-Celje corridor report that manufacturing SMEs now originate multi-line packages bundling property, liability, and cyber coverage. This concentration is most visible among 50-200 employee metalworking enterprises seeking economies of scale in premium negotiations.
Slovenia Property and Casualty Insurance Market Segmentation
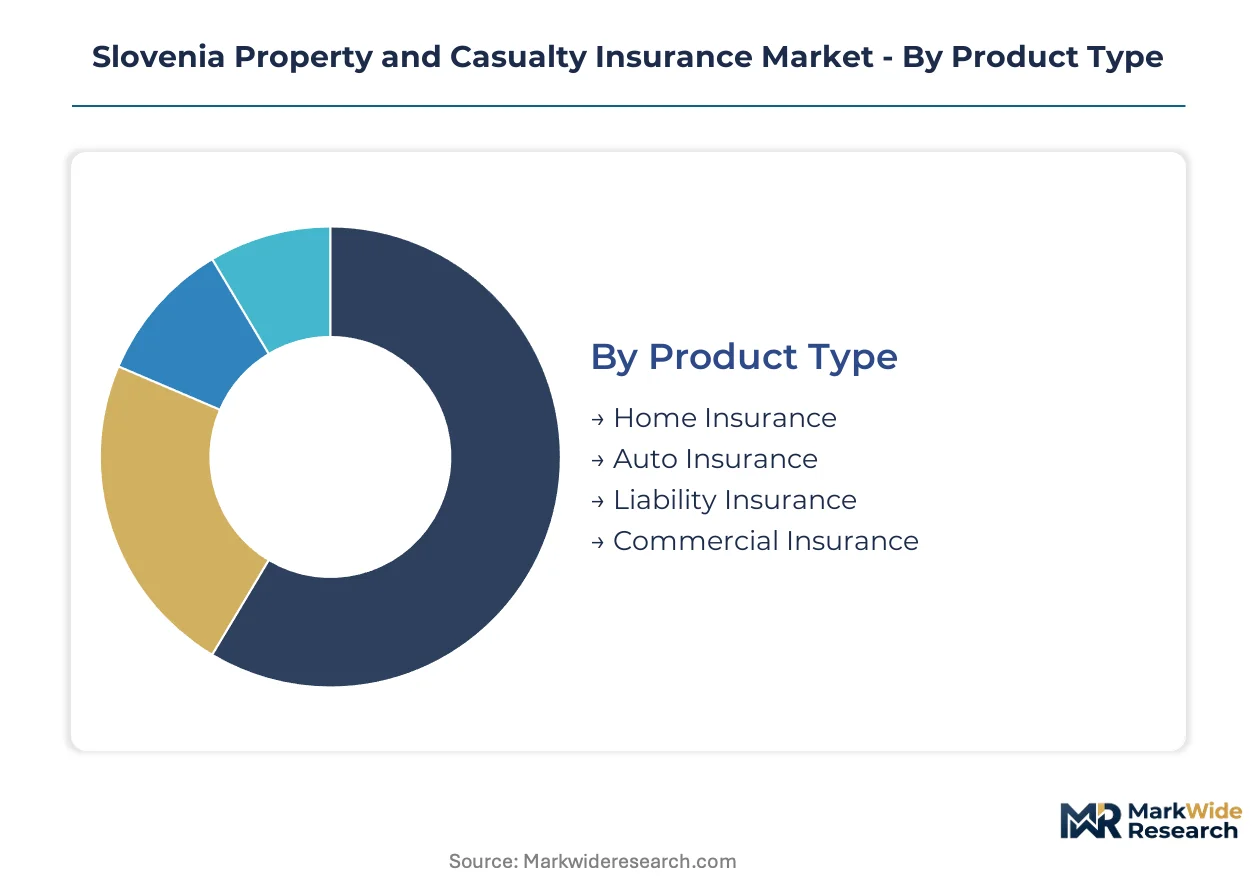
Slovenia's property and casualty insurance market fragments across four structural dimensions that shape underwriting economics and distribution strategy. The Insurance Supervision Agency's Solvency II calibration creates divergent capital requirements across product lines, while Ljubljana-Maribor corridor logistics activity concentrates demand geographically. Understanding these segment boundaries reveals where premium pools deepen and where margin compression threatens carrier profitability.
Product Type:
Regulatory mandates from the Insurance Supervision Agency impose differential capital charges based on underlying risk volatility and claims severity distributions.
- Auto Insurance:Mandatory third-party liability coverage anchors Slovenia's largest premium pool, with telematics-enabled usage-based products gaining traction among Celje basin fleet operators. Ljubljana-Maribor corridor logistics companies are the fastest adopters of sensor-driven premium structures that align costs with actual vehicle utilization.
- Commercial Insurance:Multi-line packages bundling property, liability, and cyber coverage dominate SME purchasing in the Maribor-Celje manufacturing belt. Metalworking enterprises with 50-200 employees are consolidating previously fragmented coverage into negotiated economies of scale.
- Home Insurance:Standardized dwelling and contents policies concentrate in direct-to-consumer digital channels, with Nova Ljubljanska Banka mortgage workflows offering embedded attachment points.
- Liability Insurance:Professional and product liability lines serve specialized manufacturing and construction exposures in the Celje-Koper industrial belt, with conservative reserving assumptions inflating quoted premiums due to limited historical severity data.
Auto Insurance handles the majority of throughput; Commercial Insurance is climbing the fastest on share.
Customer Type:
Purchasing authority consolidation is displacing fragmented individual decision-making with concentrated SME procurement power.
- Small Businesses:Manufacturing and logistics SMEs in the Ljubljana basin and Maribor-Celje corridor now originate multi-line coverage packages, displacing traditional individual household purchasers as the primary policy origination engine. Broker networks report these enterprises negotiate premium economies of scale previously unavailable to smaller buyers.
- Individuals:Personal auto and home coverage demand concentrates in standardized products distributed through direct digital channels and captive agency networks, with younger policyholders gravitating toward reduced-friction online purchasing.
- Large Corporations:Complex risk placements require broker-mediated access to reinsurance-backed underwriters with Solvency II-compliant balance sheets, particularly for catastrophe-exposed property portfolios.
- Non-Profits:Specialized coverage needs for social service and cultural organizations occupy niche placement channels with limited standardization.
Small Businesses command expanding share of premium origination; Individuals retain volume leadership but face margin pressure from channel shift.
Distribution Channel:
Digital infrastructure compression is fragmenting traditional agency network dominance toward embedded and direct acquisition models.
- Agents:Zavarovalnica Triglav's captive agency network maintains commercial lines dominance across the Ljubljana basin through relationship-based underwriting authority. These intermediaries capture disproportionate margin in complex placements requiring localized risk assessment.
- Online:Allianz Slovenia's digital-first distribution reduces acquisition costs for younger commercial policyholders and standardized personal lines, compressing policy issuance cycles from weeks to hours.
- Brokers:Independent intermediaries concentrate in the Maribor-Celje corridor, serving manufacturing SMEs with multi-line package negotiations and accessing reinsurance capacity for catastrophe layers.
- Direct Sales:Carrier-controlled channels focus on simplified auto and home products with minimal underwriting friction, competing on price transparency rather than advisory value.
Agents retain commercial complexity advantage; Online channels are expanding most quickly among younger demographic cohorts.
Coverage Type:
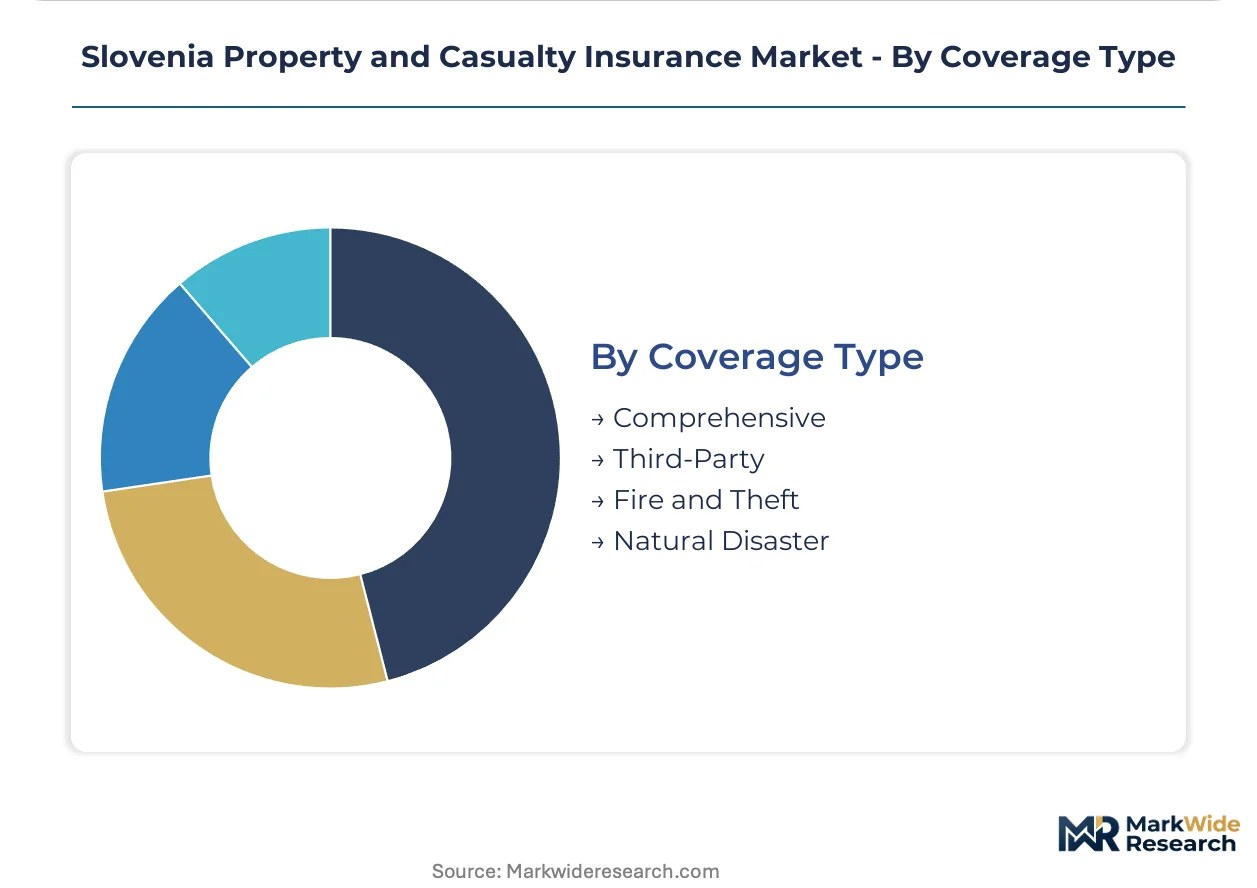
EU Green Deal transition mandates and Solvency II climate stress scenarios are reshaping coverage term availability and pricing granularity.
- Comprehensive:All-risk property protection incorporating business interruption and contingent coverage dominates SME purchasing in Ljubljana's expanding industrial zones, with 3PL operators seeking protection against supply chain disruption.
- Natural Disaster:Flood and earthquake coverage faces tightening terms for assets in the Savinja river catchment and Drava basin as carriers model multi-decade climate impacts under Solvency II requirements. Parametric river-gauge-triggered settlement mechanisms are emerging for agricultural and commercial exposures.
- Third-Party:Mandatory auto liability and professional obligation coverage constitute regulated minimums with limited pricing differentiation.
- Fire and Theft:Traditional named-peril coverage persists in cost-sensitive personal lines segments but faces displacement by comprehensive alternatives.
Comprehensive coverage absorbs the largest premium allocation; Natural Disaster products are gaining share fastest as climate risk disclosure tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ljubljana-Koper logistics corridor channels Slovenian insurance demand toward Adriatic maritime trade flows, with premium origination clustering around port infrastructure and inland distribution nodes. Domestic carriers underwrite risks tied to container throughput volatility and cross-border freight movements into Italy and Austria.
Ljubljana Basin
Third-party logistics operators and e-commerce fulfillment centers are expanding commercial property coverage requirements in Ljubljana's industrial zones. The Insurance Supervision Agency's Solvency II capital requirements favor well-capitalized carriers serving this segment. Zavarovalnica Triglav's captive agency network dominates complex commercial placements across the capital region.
Maribor-Celje Corridor
Metalworking and automotive component manufacturers with 50-200 employees are consolidating multi-line insurance packages spanning property, liability, and cyber coverage. EU Green Deal building retrofit mandates trigger reinstatement valuations for industrial assets in this manufacturing belt. Broker networks report premium economies of scale previously unavailable to mid-sized enterprises.
Koper Port Zone
Maritime logistics clusters lack specialized cargo and contingent business interruption products calibrated to container throughput volatility. The port's expansion as a gateway for Central European freight is generating demand for marine cargo and stock throughput coverage. Underpenetration persists in parametric solutions for weather-related supply chain disruptions.
Drava Basin
Agricultural and commercial property exposures face tightening flood coverage terms as carriers model multi-decade climate impacts under Solvency II requirements. Parametric river-gauge-triggered settlement mechanisms are emerging as alternatives to traditional indemnity structures. Conservative reserving assumptions inflate quoted premiums for catastrophe-exposed portfolios.
Slovenia Property and Casualty Insurance Market Competitive Landscape
Player mix skews toward domestic incumbents with captive distribution networks and European multinational carriers with digital-first capabilities. Market structure concentrates around three to four well-capitalized groups holding the majority of commercial lines premium volume. Strategic archetypes include agency-network dominators, direct digital specialists, and reinsurance-backed regional underwriters. Competitive moves center on embedded banking partnerships and telematics-enabled product differentiation.
Among domestic carriers, Zavarovalnica Triglav, d. d. and Zavarovalnica Sava, d. d. occupy positions within the agency-network tier, exemplifying relationship-driven commercial underwriting authority. Allianz Slovenia represents the multinational digital archetype, anchoring direct distribution capabilities for standardized personal and commercial lines. These three entities collectively illustrate the bifurcation between captive agency dominance and technology-enabled acquisition efficiency.
| Leading Market Players |
|---|
| Zavarovalnica Triglav, d. d. |
| GENNERALI zavarovalnica, d. d. |
| Zavarovalnica Sava, d. d. |
| Allianz Slovenia |
| GRAWE Zavarovalnica, d. d. |
| Wiener Städtische zavarovalnica, d. d. |
| Triglav Group |
| Sava Insurance Group |
| Generali Slovenija |
| Others |
Pricing and Supply Chain Analysis
Long-term treaty arrangements with Munich and Zurich-based reinsurers lock in catastrophe layer capacity for Slovenian carriers while capping price volatility for flood-exposed commercial property portfolios. These structures bind primary insurers to multi-year capacity commitments that constrain their ability to reprice risks when Solvency II climate stress scenarios tighten capital requirements.
Pricing Analysis
Legacy IT system pricing gaps separate carriers with modern digital infrastructure from those burdened by seven-figure replacement expenditures. Pricing stratifies across comprehensive multi-line packages, standardized auto liability, and parametric flood products with river-gauge-triggered settlements. Cost compression in cyber liability lines intensifies because limited historical severity data forces conservative reserving assumptions. Small manufacturing SMEs with 50-200 employees demonstrate highest price sensitivity, while large logistics operators absorbing business interruption riders show lowest.
Supply Chain Analysis
Container availability constraints through the Koper port corridor elevate inbound logistics costs for telematics hardware sourced from Germany, Netherlands, and Czech Republic. Actuarial modeling software and climate risk data feeds draw from UK, Switzerland, and US vendors. Single-source vulnerability concentrates in reinsurance treaty capacity controlled by Munich and Zurich groups. Distribution runs through captive agency networks for complex commercial placements and direct digital channels for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovenia's property and casualty insurance market faces high-growth disruption as Solvency II climate stress scenarios force multi-decade exposure modeling that incumbent IT infrastructure cannot support. The Insurance Supervision Agency's harmonization timeline compresses the window for carriers to deploy forward-looking capital adequacy assessments.
For Market Incumbents: Secure captive agency network loyalty through exclusive underwriting authority for Ljubljana basin commercial placements before Allianz Slovenia's digital-first distribution erodes relationship-based pricing power. Invest in telematics partnership infrastructure to defend auto premium pools against sensor-driven entrants. Prioritize Solvency II-compliant system replacement over marginal product expansion.
For New Entrants and Emerging Players: Solvency II internal model validation fast-track offers regulatory pathway for quantitative risk specialists lacking legacy balance sheet baggage. Target Koper port maritime logistics clusters lacking specialized cargo and contingent business interruption products. Embed distribution through Nova Ljubljanska Banka mortgage workflows to capture home and contents coverage attachment points.
For Investors and Strategic Acquirers: Capital is best deployed toward reinsurance-backed regional underwriters with demonstrated Solvency II compliance and established broker network access in the Maribor-Celje corridor. Monitor Insurance Supervision Agency enforcement actions against capital-constrained domestic carriers as acquisition trigger signal. Favor targets with parametric product development capabilities for Drava basin agricultural exposures.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Sensor-driven premium structures align Celje basin fleet costs with actual vehicle utilization patterns. |
| Parametric Flood Product Launch | River-gauge-triggered settlements eliminate loss adjustment expenses for Drava basin agricultural exposures. |
| Embedded Banking Partnership | Nova Ljubljanska Banka mortgage workflows attach home and contents coverage at origination. |
| Solvency II System Replacement | Modern reporting granularity satisfies Insurance Supervision Agency capital adequacy requirements. |
| Cyber Liability Portfolio Buildout | Manufacturing SME multi-line packages bundle property, liability, and cyber coverage in Maribor-Celje corridor. |
Research Methodology
The analysis maps auto insurance, commercial multi-line packages, home coverage, and liability products, each validated through chief underwriting officers, actuarial directors, broker network heads, and Insurance Supervision Agency regulatory staff. Primary interview findings triangulate against Insurance Supervision Agency solvency filings, EU Green Deal transition mandate documentation, port authority throughput statistics, and reinsurance treaty capacity disclosures. Bottom-up policy origination data and top-down premium pool estimates converge through iterative consistency checks.
Consistency checks validate volume and value outputs against external benchmarks including European Insurance and Occupational Pensions Authority sector reports and national statistical office financial services data. The analytical framework segments by product type, customer archetype, distribution channel, and coverage structure across the projection horizon. CAGRs derive from actuarial frequency-severity modeling applied to Ljubljana-Maribor corridor logistics expansion and EU Green Deal building retrofit mandates. Climate stress scenario inputs and telematics adoption curves inform forward-looking premium trajectories.
Decision-makers should treat outputs as directional under stable Solvency II implementation and EU Green Deal enforcement assumptions; material deviation in regulatory timeline or climate event frequency would warrant model refresh. Specific risks include reinsurance capacity withdrawal, cyber liability severity shock, and legacy IT replacement cost overrun. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Digital Innovation in Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Bancassurance Market
Insurance
Business Insurance Market
Insurance
Germany Reinsurance Market
Insurance
South Korea Liability Insurance Market
Insurance
France Car Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
France Liability Insurance Market
Insurance
Digital Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Insurance Protection Products Market
Insurance
Commercial Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market