
 Digital Account Opening Market | 2026-2036
Digital Account Opening Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Account Opening Market Analysis
Cloud-native identity orchestration is fragmenting the traditional core-banking monopoly over account origination, pushing verification, compliance, and funding workflows into specialized API layers. Wise leverages multi-jurisdiction licensing to sustain cross-border onboarding at scale. Stripe anchors its position through embedded financial services that absorb KYC burdens for platform clients. Mercury competes aggressively for startup treasury accounts with instant virtual card issuance and automated bookkeeping hooks.
Digital account opening encompasses the end-to-end automation of customer identity verification, risk scoring, regulatory compliance checks, and account activation without physical branch interaction, typically executing within minutes through mobile or web interfaces with biometric liveness detection and document OCR as core technical components. The technology dimension shows mobile platforms leading in consumer adoption while API integrations capture the fastest growth by embedding origination into vertical SaaS and marketplace workflows. Biometric authentication sits at the premium margin pool due to higher implementation complexity and fraud-prevention value, whereas web applications face commoditization from template-based banking-as-a-service providers.
The US OCC, CFPB, and FinCEN collectively enforce Bank Secrecy Act compliance, Customer Identification Program mandates, and fair lending standards that shape permissible automation levels in digital onboarding. The EU AI Act adds algorithmic accountability requirements for automated decisioning in credit and identity verification, forcing vendors to maintain audit trails and human-in-the-loop protocols. Stakeholders must monitor how real-time payment system expansions and open banking data-sharing frameworks redefine the competitive boundary between traditional institutions and API-native challengers.
Market Dynamics
Cloud-native identity orchestration is fragmenting the traditional core-banking monopoly over account origination, pushing verification, compliance, and funding workflows into specialized API layers that execute within minutes rather than days.
Growth Catalysts
- EU AI Act compliance mandates:The EU AI Act forces institutions to rebuild identity verification stacks with algorithmic accountability requirements, creating sustained demand for audit-trail-enabled onboarding platforms across European retail banking.
- Biometric liveness detection:Mobile-first consumers expect frictionless authentication, driving deployment of facial recognition and document OCR technologies that reduce abandonment rates in digital origination funnels.
- Real-time payment infrastructure:The United States' FedNow network and similar instant settlement systems in other countries enable immediate account activation, removing the funding delay that previously drove customers to branches.
Market Restraints
- GDPR data-localization costs:European data residency requirements force vendors to maintain region-specific infrastructure, raising operational complexity for cross-border onboarding providers.
- Document fraud sophistication:Synthetic identity attacks and deepfake document submissions require continuous model retraining, compressing margins for verification vendors serving high-risk segments.
- Core banking integration friction:Legacy mainframe architectures at incumbent institutions resist API-native origination workflows, slowing deployment timelines for modernization projects.
Strategic Opportunities
- Embedded finance penetration:Vertical SaaS platforms and marketplaces represent underpenetrated distribution channels where KYC-as-a-Service can absorb compliance burdens for non-financial originators.
- Open banking data convergence:The combination of account aggregation APIs with real-time identity verification enables instant risk scoring without traditional credit bureau latency.
- Startup treasury automation:Automated bookkeeping hooks and instant virtual card issuance address the cash-management needs of high-growth companies underserved by relationship-heavy incumbent banks.
Industry Challenges
- Machine learning engineering scarcity:Vendors struggle to hire talent capable of building fraud models that satisfy both performance benchmarks and EU AI Act explainability requirements.
- Multi-jurisdiction licensing complexity:Cross-border providers must navigate divergent national interpretations of AML directives, stretching legal and compliance resources across fragmented regulatory environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Account Opening Market |
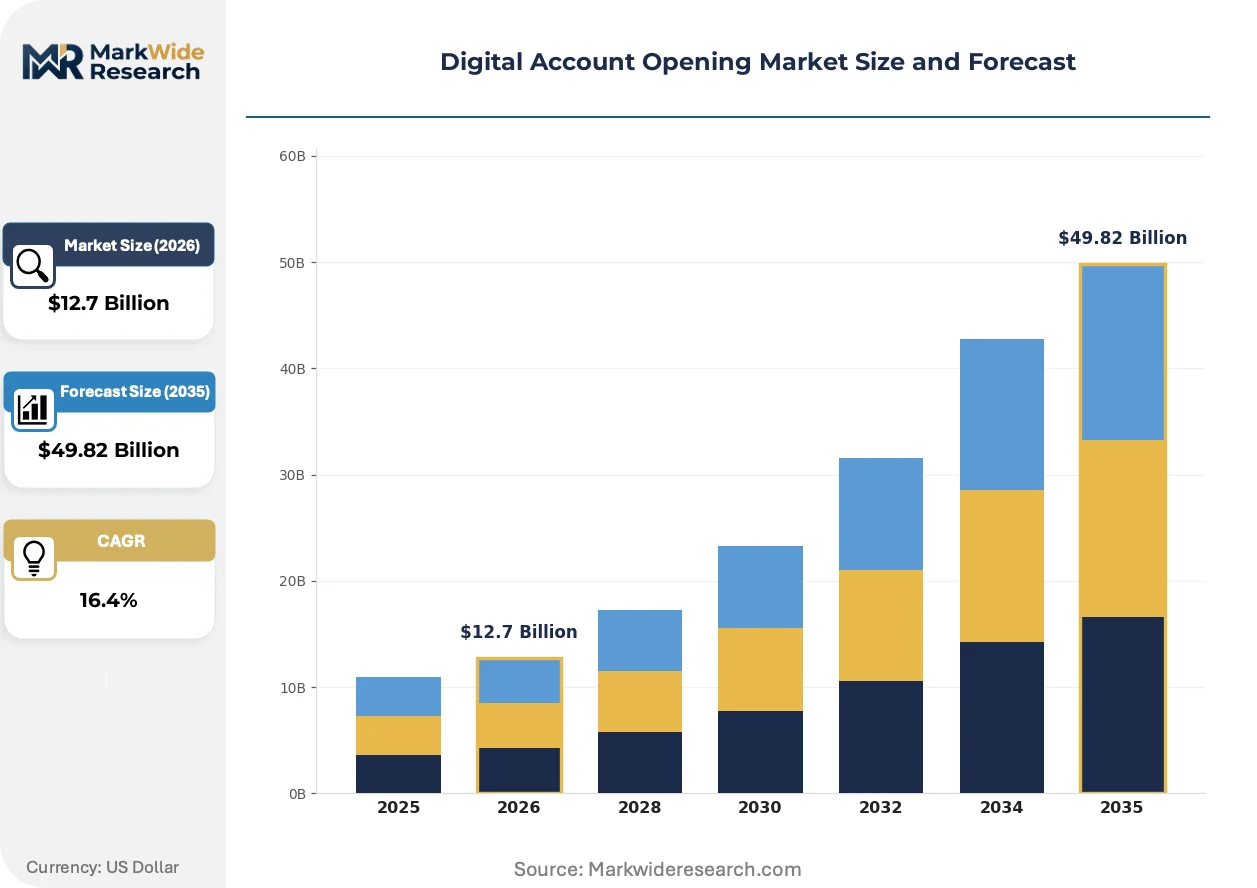
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Accounts, Business Accounts, Joint Accounts, Investment Accounts Technology: Mobile Platforms, Web Applications, API Integrations, Biometric Authentication End User: Retail Customers, Small Businesses, Corporations, Financial Institutions Application: Online Banking, Wealth Management, Customer Onboarding, Digital Payments |
| Companies Covered | Wise, Novo, Stripe, Baselane, Rho, PayPal, Mercury, Candescent, Block, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Account Opening Market Emerging Trajectories
Active experimentation with decentralized identity standards and behavioral biometrics is compressing the trust-establishment phase of digital onboarding from hours to seconds.
Passive behavioral biometrics is digitizing the identity verification layer by analyzing touchscreen pressure, typing cadence, and device handling patterns without explicit user action. Neobanks and fintech lenders are deploying these signals as primary authentication factors, reducing reliance on knowledge-based questions that fraudsters compromise through data breaches. The technology is digitizing risk scoring into a continuous background process rather than a discrete checkpoint.
The EU AI Act's algorithmic accountability requirements are mandating human-in-the-loop protocols for automated credit and identity decisions, forcing vendors to rebuild decisioning architectures with auditable intervention triggers. This creates compliance overhead but also differentiation for providers with pre-built explainability tooling. European retail banks are responding by consolidating vendor relationships around platforms with native audit-trail capabilities.
Platform-native onboarding is displacing standalone banking applications as the dominant origination channel, with customers expecting account opening embedded within commerce, payroll, and treasury workflows they already use. Marketplace sellers and gig workers initiate accounts through employer dashboards rather than bank websites. This shift is most visible in the United States, where vertical SaaS penetration and real-time payment infrastructure create the technical conditions for embedded origination at scale.
Digital Account Opening Market Segmentation
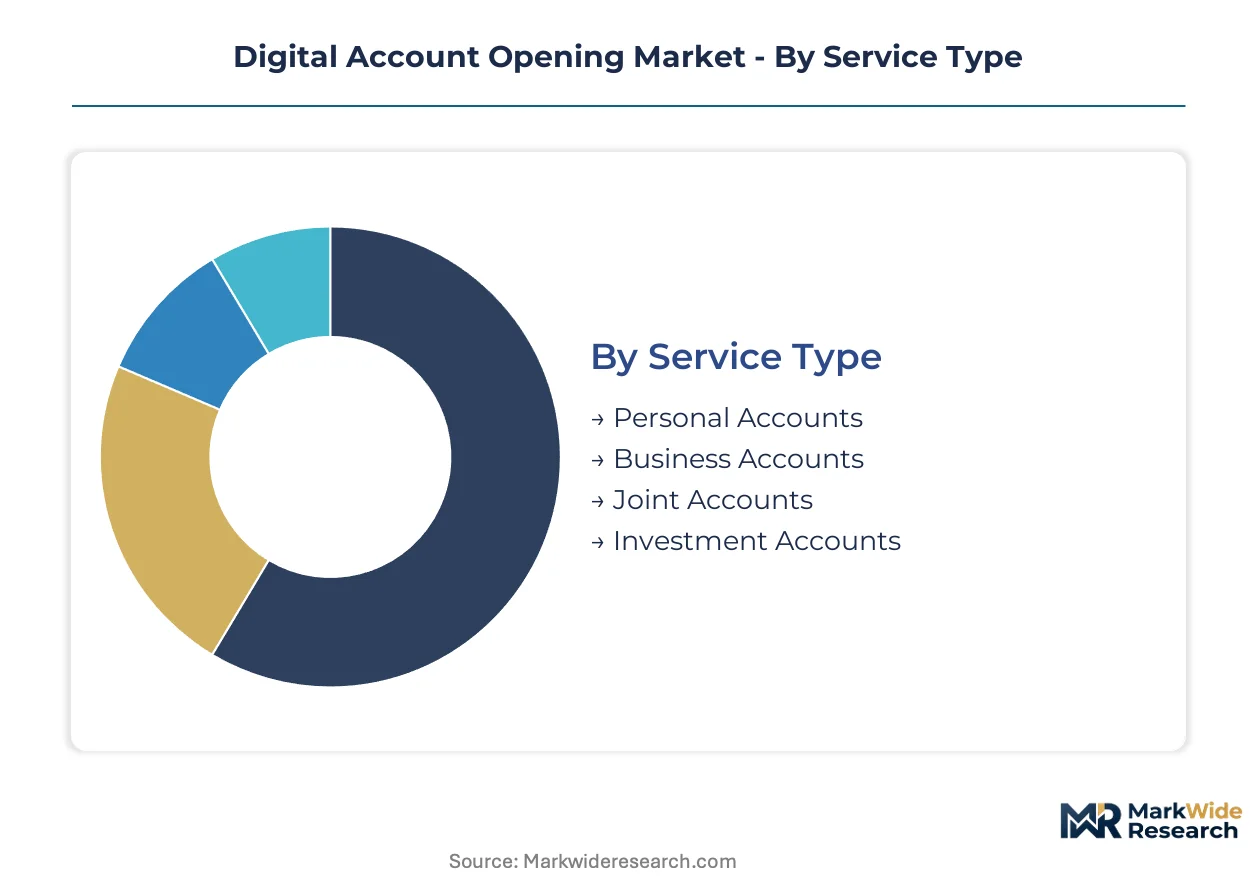
Segmentation in digital account opening reveals how infrastructure investments and regulatory requirements fragment vendor strategies across service tiers and technical architectures. Understanding these divides clarifies where compliance automation adds value versus where commoditization pressures dominate.
Service Type:
After-sales-service intensity varies dramatically across account categories, with business and investment accounts demanding ongoing compliance monitoring that personal accounts rarely require.
- Personal Accounts:Standardized KYC workflows with selfie-to-document matching and automated address verification handle the bulk of consumer onboarding volume. Demand concentrates in the United States where neobank competition and FedNow instant funding eliminate traditional branch advantages. Regulatory simplicity keeps per-account servicing costs lowest here.
- Business Accounts:Multi-layered beneficial ownership verification and ongoing transaction monitoring create sustained service obligations. Small and medium enterprises in Germany and France drive demand as EU AI Act audit-trail requirements force manual review protocols for automated decisions. Complexity sustains premium pricing.
- Joint Accounts:Dual identity verification with consent orchestration adds workflow steps without proportional revenue uplift.
- Investment Accounts:Suitability questionnaires and risk-profile attestation extend onboarding duration significantly.
By volume, Personal Accounts leads. By growth pace, Business Accounts is ahead.
Technology:
Cost tier separation in technology procurement reflects how embedded deployment models capture budget share from standalone application investments.
- API Integrations:Backend-as-a-service architectures let non-financial platforms embed origination without building compliance infrastructure. Vertical SaaS providers in the United States absorb KYC burdens for marketplace sellers and gig platforms. This segment gains share fastest as distribution shifts away from direct banking channels.
- Biometric Authentication:Liveness detection and passive behavioral signals command implementation premiums due to fraud-prevention value and engineering scarcity. European retail banks under EU AI Act mandates invest here for algorithmic accountability documentation. Higher margins reflect continuous model retraining requirements.
- Mobile Platforms:Consumer-facing applications face template-based commoditization from banking-as-a-service providers.
- Web Applications:Browser-based origination encounters abandonment pressure as mobile-first expectations harden.
By deployment scale, Mobile Platforms dominates current infrastructure. By margin expansion, Biometric Authentication outperforms.
End User:
Customer type determines whether origination serves as a loss-leader for deposit acquisition or a revenue-generating compliance service.
- Financial Institutions:White-label platform licensing and regulatory consulting create recurring revenue streams. Incumbent banks in India and Brazil modernize legacy stacks through vendor partnerships that include ongoing model governance. Procurement emphasizes audit-trail capabilities and multi-jurisdiction coverage.
- Small Businesses:Treasury automation with instant virtual card issuance and bookkeeping integration addresses cash-management pain points. Startup ecosystems in the United States and United Kingdom favor providers offering API-native workflows over relationship-heavy incumbents. Speed-to-activation drives vendor selection.
- Retail Customers:Mass-market onboarding competes primarily on friction reduction and mobile experience.
- Corporations:Entity verification at scale requires customized workflows with limited standardization potential.
By contract value, Financial Institutions anchors revenue. By expansion velocity, Small Businesses climbs fastest.
Application:
Maturity differentiation separates applications where digital origination is table stakes from those still converting physical workflows.
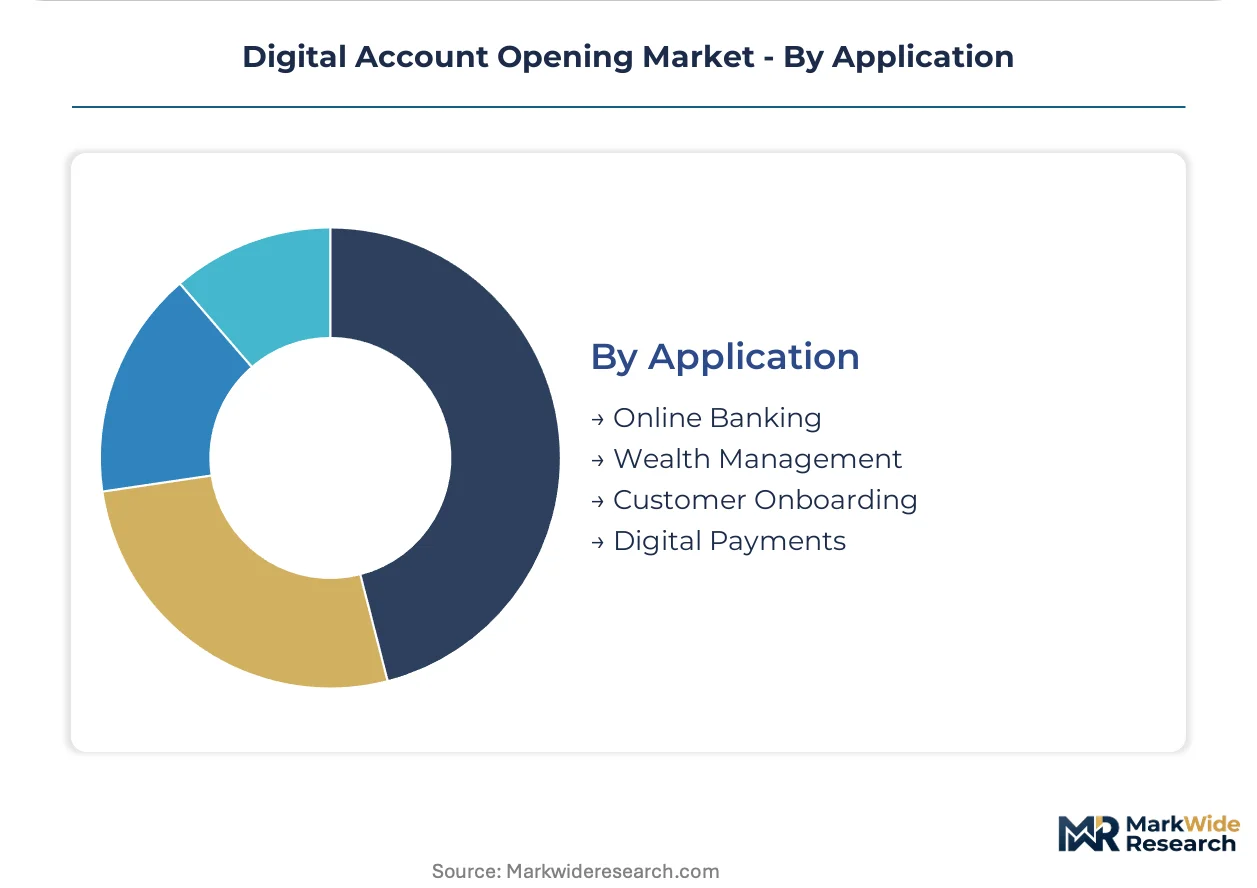
- Customer Onboarding:The core identity-verification use case spans all service types with the broadest vendor competition. Real-time payment infrastructure in the United States and open banking data availability in the United Kingdom enable instant risk scoring without credit bureau latency. Automation completeness varies most here.
- Digital Payments:Wallet provisioning and merchant account origination demand sub-minute activation speeds. Cross-border providers leverage multi-jurisdiction licensing to sustain onboarding scale across regulatory boundaries. Speed requirements push technical architecture decisions.
- Online Banking:Full-service account origination with deposit and lending products faces incumbent core-banking integration friction.
- Wealth Management:Suitability documentation and regulatory disclosure requirements slow automation adoption.
By implementation breadth, Customer Onboarding leads. By technical sophistication demands, Digital Payments is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border fintech flows from the United States into European and Asia-Pacific markets are accelerating API-native onboarding infrastructure deployment. Regulatory divergence between jurisdictions creates arbitrage opportunities for multi-licensed providers while fragmenting vendor procurement patterns.
United States
Neobank competition and FedNow instant settlement infrastructure drive demand for sub-minute account activation. The CFPB enforces fair lending standards that shape permissible automation levels in digital onboarding workflows. Fintech clusters in San Francisco and New York anchor development of embedded finance origination channels for marketplace sellers.
Germany
EU AI Act algorithmic accountability mandates force retail banks to rebuild identity verification stacks with auditable decision trails. BaFin supervision requires human-in-the-loop protocols for automated credit decisions. Berlin and Frankfurt host concentrated procurement activity for compliance-enabled onboarding platforms serving Mittelstand business banking.
United Kingdom
Open banking data availability enables instant risk scoring without traditional credit bureau latency. The Financial Conduct Authority regulates embedded finance partnerships between banks and non-financial platforms. London's fintech corridor dominates vendor development for API-native origination serving vertical SaaS distributors.
India
RBI digital KYC guidelines permit video-based customer identification that accelerates mobile-first onboarding at scale. The central bank's regulatory sandbox allows experimentation with biometric authentication for financial inclusion. Mumbai and Bangalore concentrate vendor partnerships between neobanks and identity verification technology providers.
Brazil
Pix instant payment infrastructure eliminates funding delays that previously drove customers to physical branches. Banco Central do Brasil enforces strict data localization requirements for financial technology providers. São Paulo anchors Latin America's most active market for cloud-native account origination platforms serving underbanked segments.
Digital Account Opening Market Vendor Landscape
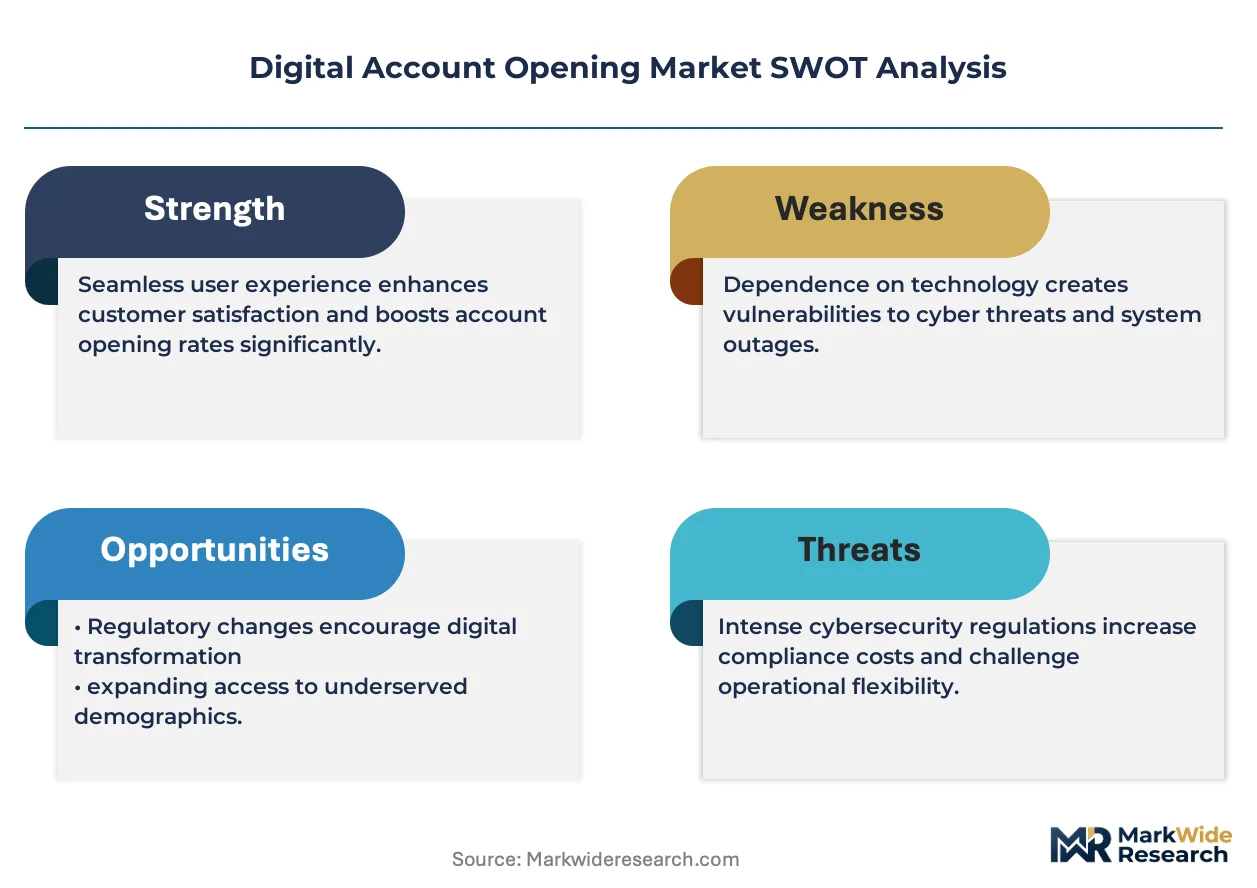
On the supply side, the industry is consolidating around API-native platforms that absorb compliance burdens for non-financial distributors. Tiered competition separates multi-jurisdiction challengers from regionally focused specialists. Three strategic archetypes dominate: embedded finance enablers, neobank infrastructure providers, and cross-border treasury specialists. M&A activity concentrates on identity verification technology acquisitions, while strategic partnerships with vertical SaaS platforms expand distribution reach.
Within the embedded finance tier, Stripe and Wise exemplify platform-native origination strategies that embed account opening into commerce and cross-border payment workflows. Mercury occupies a position among neobank-focused providers targeting startup treasury automation with instant virtual card issuance. These three companies represent divergent approaches to API-first customer acquisition—Stripe through platform distribution, Wise through multi-jurisdiction licensing, and Mercury through vertical specialization in high-growth company banking.
| Leading Market Players |
|---|
| Wise |
| Novo |
| Stripe |
| Baselane |
| Rho |
| PayPal |
| Mercury |
| Candescent |
| Block |
| Others |
Supply Flow & Price Mechanics
San Francisco's API-native identity verification cluster concentrates engineering talent for biometric liveness detection, compressing implementation premiums for cloud-native onboarding platforms while fragmenting pricing power among specialized compliance vendors. This geographic concentration of technical infrastructure creates tiered cost structures that propagate downstream through banking-as-a-service distribution channels.
Pricing Analysis
Current-generation biometric authentication with passive behavioral signals commands implementation premiums against prior-generation document OCR and next-generation decentralized identity standards still in pilot. Three-tier pricing structure across premium biometric suites, standard API-integrated verification, and economy template-based onboarding dominates procurement. Price differentiation rests on fraud-prevention certification tiers and continuous model retraining service levels. Cost compression in standard-tier verification is intensifying because banking-as-a-service providers replicate template workflows. Small business treasury automation buyers exhibit highest price sensitivity; financial institutions licensing white-label platforms show lowest.
Supply Chain Analysis
Extended payment terms from identity verification vendors to cloud infrastructure providers stretch working capital requirements across the onboarding technology stack. Engineering talent concentrates in the United States, India, and Germany. Raw material dependencies center on GPU compute capacity, biometric sensor hardware, and regulatory compliance documentation services. Single-source vulnerability in liveness detection model training data creates concentration risk. Distribution runs through API-first platform partnerships with vertical SaaS providers and direct enterprise licensing to financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. EU AI Act compliance requirements create switching costs that lock financial institutions into audit-trail-enabled vendor relationships.
For Market Incumbents: Entrench position through backward integration into biometric model training infrastructure and captive compliance documentation services. Core banking modernization threats from API-native challengers demand defensive consolidation around multi-jurisdiction licensing capabilities. Certification investment in EU AI Act explainability tooling reinforces vendor stickiness. For New Entrants and Emerging Players: Mid-market business banking in France and Germany represents the most penetrable entry point given EU AI Act forced rebuilds of incumbent verification stacks. Startup treasury automation in the United Kingdom offers secondary white-space with open banking data convergence enabling instant risk scoring. Go-to-market through embedded finance partnerships with vertical SaaS distributors absorbs compliance burdens for non-financial originators. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy core banking vendors divesting non-compliant identity verification modules. Long-term viability hinges on algorithmic accountability tooling becoming table stakes across European retail banking. Acquisition target archetypes include biometric authentication specialists with pre-built explainability frameworks. The signal to watch is FedNow real-time payment infrastructure expansion accelerating sub-minute activation demands.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Licensing Expansion | Enables cross-border onboarding scale across divergent AML directive interpretations in Germany, France, and the United Kingdom. |
| Biometric Model Training Infrastructure | Captures fraud-prevention value through continuous retraining against synthetic identity attacks and deepfake document submissions. |
| Embedded Finance Platform Partnership | Absorbs KYC burdens for vertical SaaS distributors serving marketplace sellers and gig worker segments. |
| EU AI Act Compliance Tooling | Differentiates vendors through native audit-trail capabilities and human-in-the-loop protocol automation. |
| Real-Time Payment Integration | Removes funding delay friction that previously drove customers to physical branches through FedNow and Pix connectivity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with digital banking product executives, identity verification engineering leads, regulatory compliance officers at financial institutions, and vertical SaaS platform architects. Secondary validation drew from SEC filings of publicly traded fintech infrastructure providers, RBI digital KYC guideline publications, BaFin supervision circulars, and open banking API adoption disclosures. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against banking-as-a-service revenue disclosures anchored market sizing.
Calibration against historical adoption curves for mobile-first onboarding and API-integrated origination informed trajectory assumptions across the analysis window. Segmentation dimensions modeled include service type, technology tier, end-user category, and application maturity, with additional granularity on regulatory framework clusters. CAGRs were derived through logistic diffusion modeling of biometric authentication penetration and embedded finance partnership velocity. Industry-specific inputs encompassed EU AI Act implementation timelines and real-time payment infrastructure deployment schedules.
Practitioners should monitor regulatory enforcement intensity and synthetic identity attack sophistication for early signals of vendor consolidation pressure. Forecasts reflect assumptions about compliance automation adoption rates and cloud-native infrastructure migration pace. Macroeconomic credit contraction, algorithmic accountability requirement expansion, or decentralized identity standard breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Investment Trading Software Market
Financial Services
South Korea Trade Finance Market
Financial Services
Financial Advisory Services Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Trade Finance Market
Financial Services
Multivendor ATM Software Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Smart Finance Services Market
Financial Services
E-Invoicing Market
Financial Services
US Online Trading Platform Market
Financial Services
Europe Factoring Services Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Europe E-Brokerages Market