
 Digital Transformation of Maritime Freight Market | 2026-2036
Digital Transformation of Maritime Freight Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation of Maritime Freight Market Intelligence
The proliferation of digital freight booking platforms is reshaping how shippers and freight forwarders procure capacity. These platforms are displacing traditional, manual communication channels like phone calls and emails with automated, API-driven transactions. SAP SE leverages its extensive enterprise software footprint to integrate logistics data across the supply chain. In parallel, KONGSBERG Gruppen ASA specializes in vessel-side operational technology, providing digital twins and automation systems for ship management.
Digital transformation of maritime freight involves applying advanced technologies to optimize the seaborne transport of goods. This includes using IoT solutions with sensors that provide real-time container telemetry on parameters like temperature and humidity. The primary purpose is to increase supply chain visibility, improve operational efficiency, and enhance cargo security. Within the technology segment, AI & Machine Learning for predictive maintenance and route optimization represents the fastest-growing area. Fleet Management and Cargo Tracking applications form the foundational, mature segments for shipping operators and port authorities.
Regulatory frameworks are a significant catalyst for digitalization. The International Maritime Organization's FAL Convention encourages standardized electronic data exchange, pushing ports and vessel operators toward digital documentation. Similarly, the European Union's Import Control System 2 (ICS2) mandates advance electronic cargo information for security screening. The central strategic decision for stakeholders now revolves around choosing between developing proprietary, closed-loop digital platforms or adopting open, interoperable systems that connect a wider ecosystem.
Market Dynamics
The central structural force shaping the market is the non-negotiable regulatory push for data transparency. Mandates for emissions tracking and advance cargo information are converging with commercial demands for efficiency, compelling a systemic shift from analog processes to integrated digital workflows across the maritime ecosystem.
Growth Catalysts
- Regulatory Mandates:The inclusion of shipping in the EU Emissions Trading System requires digital monitoring, reporting, and verification of carbon output, creating a direct demand for compliant software and sensor solutions.
- Technology Maturity:IoT sensors for real-time container telemetry have become cost-effective and reliable, driving adoption by shippers of perishable goods and high-value cargo who require visibility into temperature, humidity, and location.
- Smart Port Ecosystems:Initiatives in hubs like Singapore create concentrated zones of digital infrastructure, compelling carriers, freight forwarders, and drayage operators to adopt compatible digital tools to operate efficiently within these ports.
Market Restraints
- Interoperability Barriers:A lack of universal data standards among carriers, ports, and software vendors results in data silos and significant friction when attempting to integrate disparate systems into a single, cohesive supply chain view.
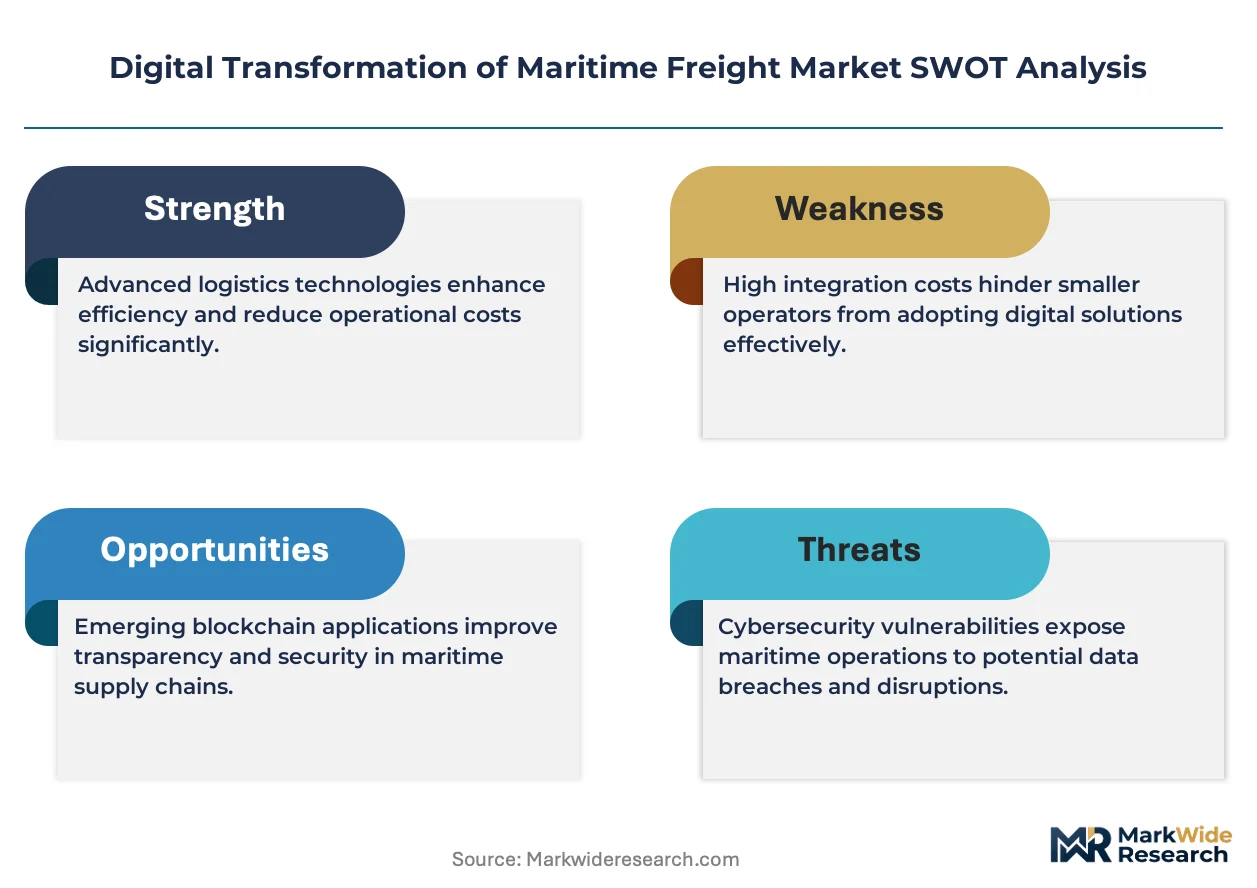
- High Capital Investment:The significant upfront cost to retrofit older vessels with modern sensors, connectivity hardware, and onboard systems presents a substantial financial barrier for smaller fleet owners and operators.
- Platform Dependency Risk:The digital marketplace is consolidating around a few large technology providers and carrier-backed platforms, raising concerns about long-term vendor lock-in and reduced negotiating power for shippers.
Strategic Opportunities
- Predictive Analytics Services:The application of digital twins for vessel performance modeling offers a significant opportunity to provide predictive maintenance and fuel optimization services, moving beyond basic tracking to active operational management.
- Greenfield Digitalization:Port modernization projects in emerging economies across Southeast Asia and Africa present an opportunity to deploy end-to-end digital systems without the burden of integrating with legacy infrastructure.
- Automated Compliance Solutions:The IMO's FAL Convention creates an opportunity for software providers to develop platforms that not only exchange data but also automate the generation and validation of all required digital trade documents.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity and cost of integrating new, cloud-based digital freight platforms with the decades-old, on-premise terminal operating systems and ERP systems used by many stakeholders.
- Maritime-Tech Talent Scarcity:The industry faces a shortage of professionals who possess a hybrid skillset combining maritime operational knowledge with expertise in data science, software development, and cybersecurity.
- Cybersecurity Vulnerability:Increased digital connectivity of vessels and port systems expands the attack surface for cyber threats, making the implementation and constant updating of robust security protocols a critical operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation of Maritime Freight Market |
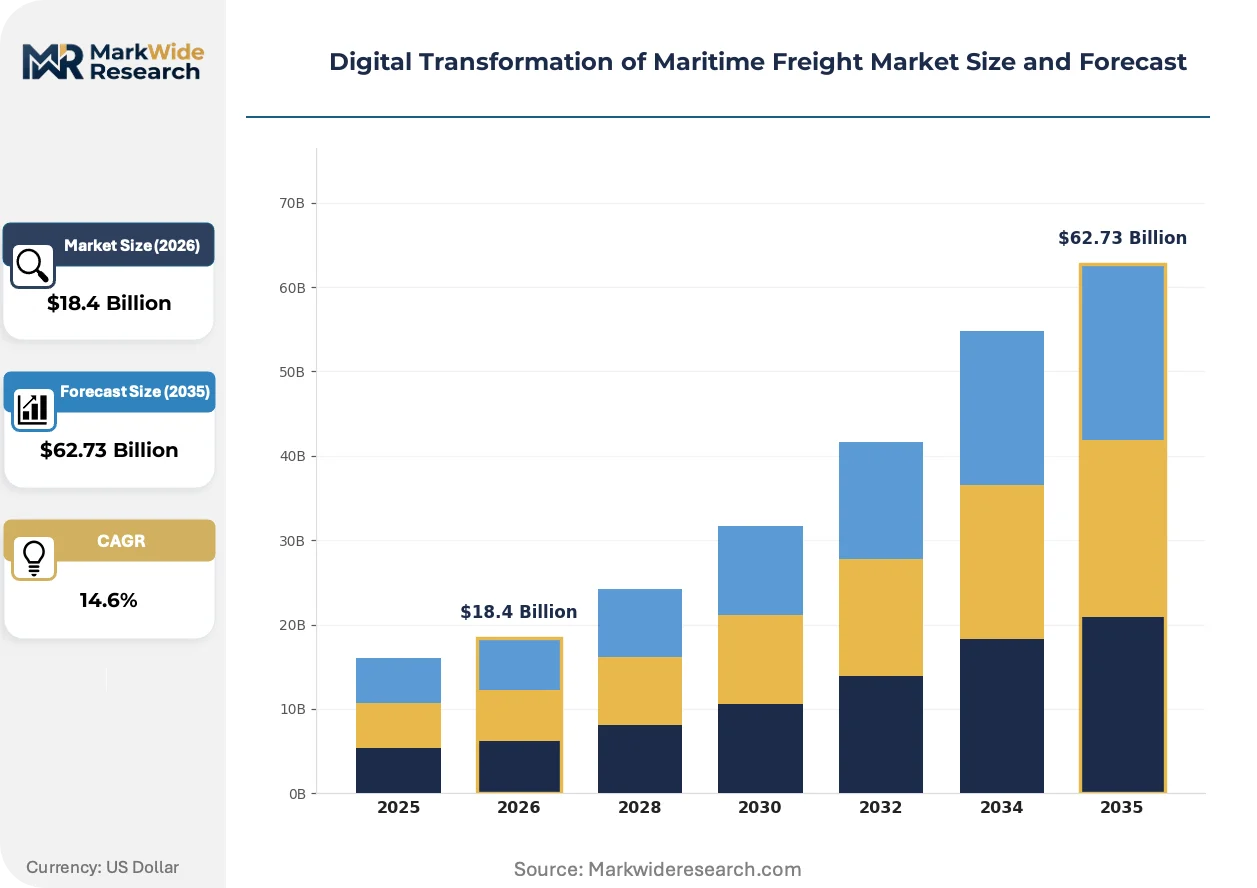
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Blockchain, AI & Machine Learning, Big Data Analytics, Cloud Computing, Digital Twins Application: Fleet Management, Cargo Tracking, Predictive Maintenance, Route Optimization, Port Operations, Supply Chain Visibility End User: Shipping Operators, Logistic Providers, Port Authorities, Freight Forwarders, Vessel Owners, Terminal Operators Deployment: On-Premises, Cloud-Based, Hybrid Models, Edge Computing |
| Companies Covered | Tech Mahindra Limited, KONGSBERG Gruppen ASA, ABB, Advantech, Wipro, SAP SE, Hexaware Technologies, Kintetsu World Express, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation of Maritime Freight Market Strategic Shifts & Innovations
The market is transitioning from isolated, function-specific digital tools toward integrated data ecosystems. This evolution connects previously siloed operational areas like vessel management, port logistics, and customs clearance into a more unified and intelligent network, enabling cross-functional optimization.
Artificial intelligence and machine learning algorithms provide predictive analytics for optimizing vessel routes and scheduling maintenance. Adoption is accelerating among major container lines and logistics providers aiming to reduce fuel consumption, minimize asset downtime, and improve schedule reliability. This technology is digitizing core operational decisions, transforming them from experience-based judgments into data-driven, automated recommendations for fleet management.
The International Maritime Organization’s cyber risk management guidelines mandate that vessel operators integrate cybersecurity into their certified safety management systems. This regulation compels shipowners to conduct formal risk assessments and deploy technical safeguards against digital threats to operational technology. The vessel management segment is most affected, now embedding cybersecurity evaluations into technology procurement and standard operating procedures.
A notable shift in buyer behavior involves shippers and beneficial cargo owners (BCOs) using digital freight booking platforms for direct procurement of ocean capacity. This disintermediates traditional communication channels with freight forwarders, who must now add more sophisticated value-added services to compete. This trend is most visible on high-volume, volatile trade lanes such as the trans-Pacific, where instant pricing and booking provide a competitive advantage.
Digital Transformation of Maritime Freight Market Segmentation
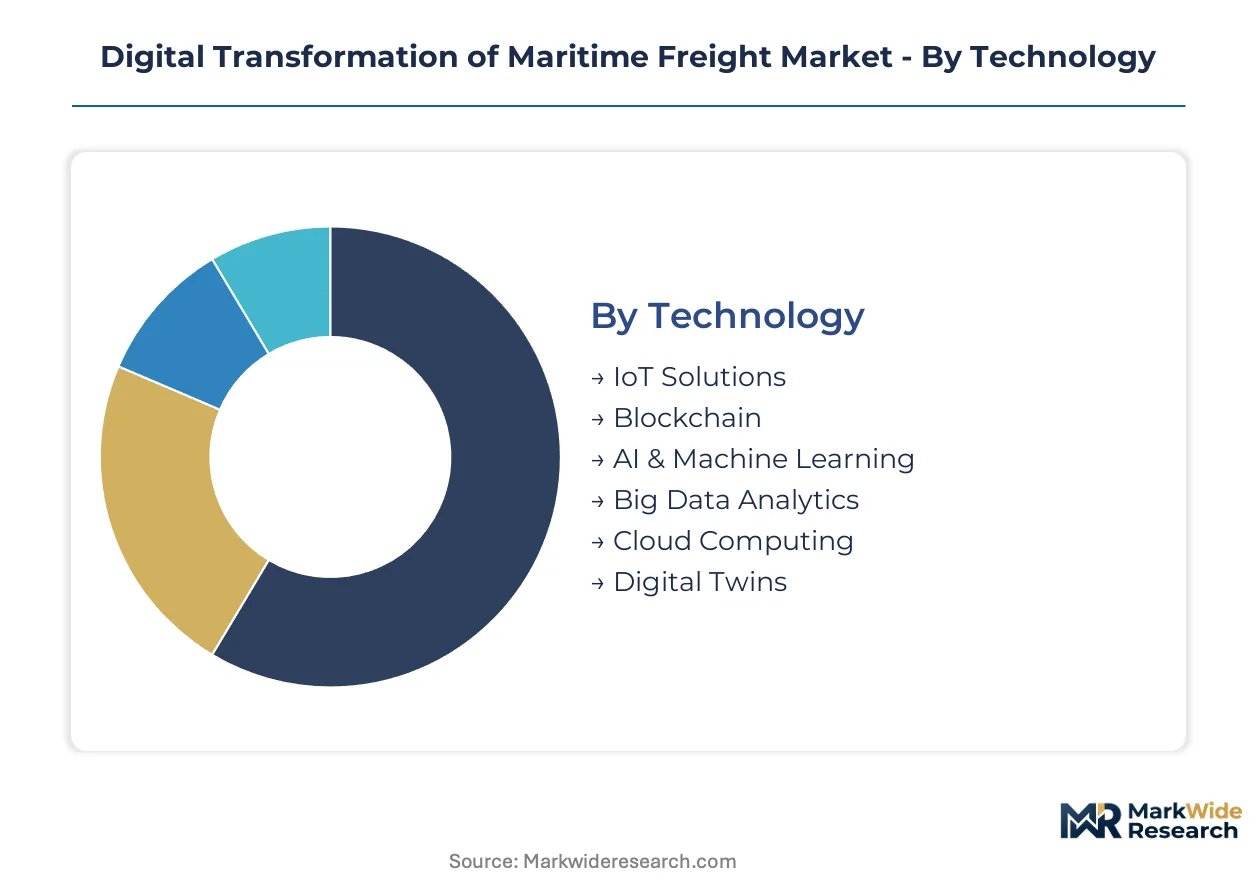
The Digital Transformation of Maritime Freight market is meticulously segmented to reflect the diverse technological adoption patterns and operational requirements across the shipping industry. Understanding these distinct segments allows stakeholders to tailor digital solutions effectively, addressing specific pain points and maximizing efficiency gains within their operational domains.
Technology:
The intensity of after-sales service and ongoing support often dictates the long-term value proposition for various digital technologies in maritime freight. Complex solutions like digital twins require continuous data integration and expert maintenance, contrasting with more standardized IoT deployments.
- IoT Solutions:These encompass sensor-based systems providing real-time data on cargo conditions, vessel performance, and location. Shippers of temperature-sensitive goods, like pharmaceuticals, drive demand for precise telemetry from these devices.
- Blockchain:Distributed ledger technology offers enhanced transparency and immutability for tracking cargo and documenting transactions across the supply chain. Adoption is concentrating in high-value cargo segments seeking improved security and audit trails.
- AI & Machine Learning:These technologies enable predictive analytics for route optimization, equipment maintenance, and demand forecasting. Major container lines are rapidly deploying AI to reduce fuel consumption and enhance schedule reliability.
- Big Data Analytics:Tools that process and interpret large volumes of operational data to uncover trends and inform strategic decisions.
- Cloud Computing:Provides scalable infrastructure for hosting digital platforms, data storage, and analytical processing, supporting remote access.
- Digital Twins:Virtual replicas of physical assets, like vessels or port terminals, used for simulation, performance monitoring, and predictive maintenance.
By volume, IoT Solutions lead. By growth pace, AI & Machine Learning is ahead.
Application:
Digital applications in maritime freight are differentiated by their primary operational focus, ranging from micro-level asset management to macro-level supply chain oversight. Each application targets distinct efficiency improvements and visibility enhancements for specific user groups.
- Fleet Management:Software systems designed to monitor and manage an entire fleet of vessels, covering scheduling, maintenance, and regulatory compliance. Shipping operators utilize these tools to optimize asset utilization and operational costs.
- Cargo Tracking:Solutions that provide real-time location and status updates for containers and goods throughout their journey. Freight forwarders and beneficial cargo owners rely on this for enhanced supply chain visibility.
- Predictive Maintenance:AI-driven systems that forecast equipment failures on vessels or in port infrastructure, enabling proactive repairs. This application helps vessel owners reduce unexpected downtime and costly emergency repairs.
- Route Optimization:Algorithms that calculate the most efficient vessel paths considering weather, fuel costs, and port congestion.
- Port Operations:Digital platforms streamlining activities within port terminals, including vessel traffic management and cargo handling.
- Supply Chain Visibility:Integrated platforms offering end-to-end transparency of goods movement from origin to final destination.
Fleet Management commands the largest share of deployments; Predictive Maintenance is expanding most quickly.
End User:
The digital transformation market for maritime freight serves a diverse array of end users, each with unique requirements for data, automation, and operational insights. Solutions are often tailored to address the specific challenges faced by these distinct maritime stakeholders.
- Shipping Operators:Companies managing and operating fleets of cargo vessels, requiring solutions for vessel performance, compliance, and route planning. These entities seek to optimize their core transport operations and asset management.
- Logistic Providers:Firms offering comprehensive freight management, warehousing, and distribution services. They leverage digital tools to enhance service delivery and customer communication.
- Port Authorities:Governmental or private bodies overseeing port infrastructure and operations, needing systems for traffic management and terminal efficiency. These organizations focus on optimizing port throughput and regulatory adherence.
- Freight Forwarders:Intermediaries arranging cargo transport on behalf of shippers, utilizing digital platforms for booking and tracking.
- Vessel Owners:Entities owning maritime vessels, often distinct from operators, focused on asset value, maintenance, and regulatory compliance.
- Terminal Operators:Companies managing cargo handling facilities within ports, requiring digital solutions for equipment and yard management.
Shipping Operators represent the foundational demand; Port Authorities are experiencing significant investment in digitalization.
Deployment:
Deployment models for digital maritime freight solutions vary based on infrastructure, security needs, and scalability preferences of end users. These models dictate how software and data are hosted, accessed, and managed within the maritime ecosystem.
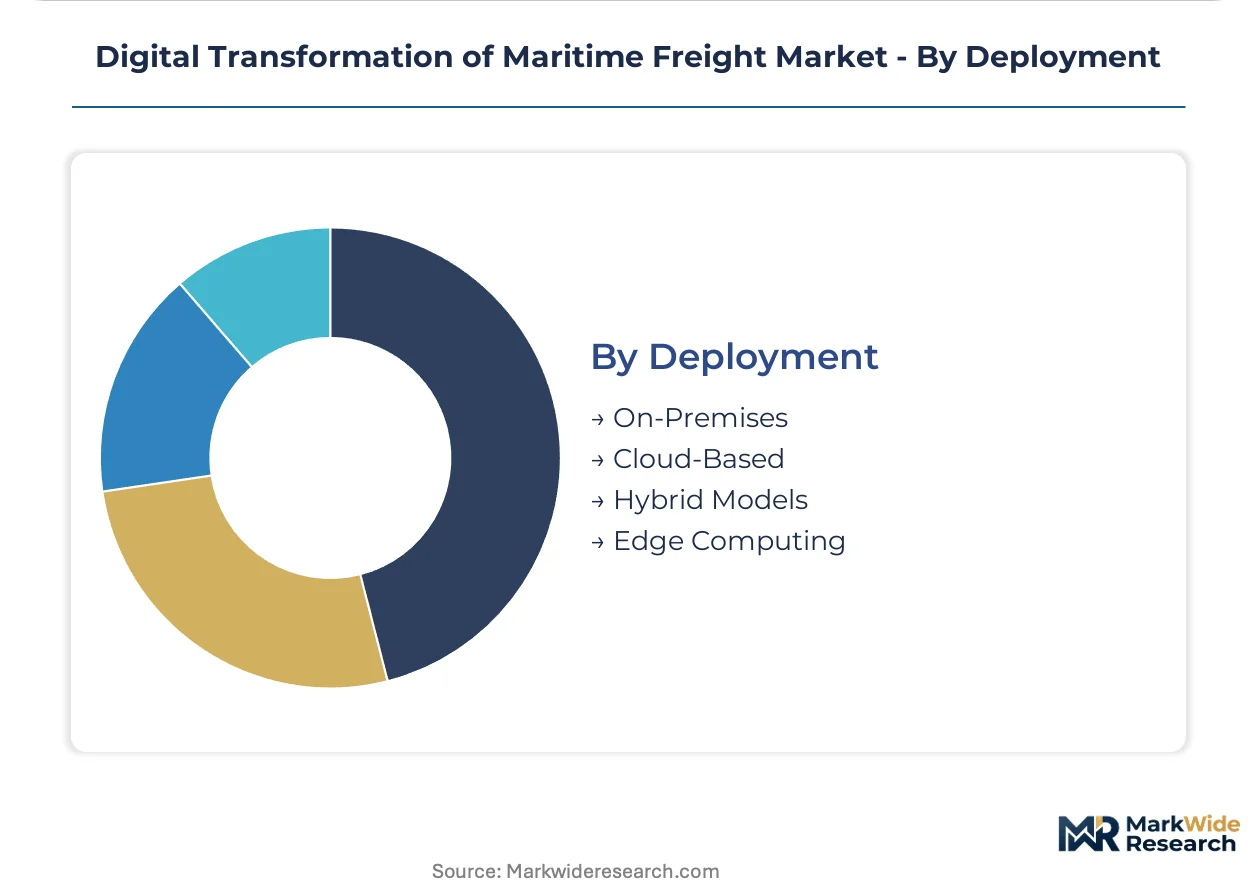
- On-Premises:Software and hardware installed and managed directly within the end user's own data centers or physical locations. This model is favored by organizations with stringent data sovereignty or legacy system integration needs.
- Cloud-Based:Solutions hosted by third-party providers and accessed over the internet, offering scalability and reduced infrastructure overhead. Many new digital freight platforms are exclusively cloud-based, attracting users seeking flexibility.
- Hybrid Models:A combination of on-premises and cloud-based deployments, allowing organizations to leverage benefits from both approaches.
- Edge Computing:Processing data closer to the source, like on a vessel or within a port, to reduce latency and bandwidth usage.
Cloud-Based deployments are widely adopted; Edge Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between major shipping hubs like Singapore and developing port networks in Southeast Asia influences digital transformation investment. Advanced port ecosystems command higher value for data-driven services and seamless integration. Emerging economies often prioritize foundational digital infrastructure to catch up with established trade routes.
Singapore
Demand for smart port solutions and real-time logistics data drives digitalization within the city-state. The Maritime and Port Authority of Singapore (MPA) actively promotes digital trade platforms and interoperable data exchange. Singapore's Tuas Port integrates advanced automation, IoT, and AI for enhanced operational efficiency and future capacity.
Netherlands
European regulatory mandates for emissions tracking and advanced cargo information accelerate digital monitoring adoption here. The EU Emissions Trading System (ETS) pushes carriers towards transparent reporting and verified carbon output. Rotterdam, Europe's largest port, implements extensive digital twin technology for real-time port management and predictive maintenance.
United States
Supply chain visibility and enhanced cargo security concerns fuel demand for advanced tracking solutions across American ports. The US Customs and Border Protection (CBP) mandates electronic cargo information for comprehensive security screening. Los Angeles and Long Beach ports are investing in AI-driven traffic management systems and automated gate processes.
China
The vast scale of manufacturing and export drives demand for efficient freight booking platforms and logistics optimization. China's Ministry of Transport encourages digital port development and smart logistics initiatives to improve national trade flows. Shanghai Port leverages 5G and AI for automated container handling operations and improved vessel turnaround times.
Germany
Efficiency gains in multimodal transport and predictive maintenance are key demand drivers for digital maritime solutions. The German government supports digital innovation within its logistics sector through various funding programs. Hamburg Port utilizes advanced analytics for optimizing vessel calls, cargo flow, and reducing environmental impact.
Digital Transformation of Maritime Freight Market Key Industry Players
Enterprise software providers and specialized operational technology vendors split the market for digital transformation in maritime freight, addressing distinct needs. The competitive landscape features a blend of established IT giants offering broad solutions and niche maritime-tech innovators focusing on specific vessel or port applications. Companies pursue strategic partnerships to integrate disparate systems and engage in portfolio diversification to expand their service offerings. This market structure reflects the complex integration required across the entire maritime value chain.
Within the specialized operational technology segment, KONGSBERG Gruppen ASA, a Norwegian-based company, exemplifies solutions for vessel-side automation, digital twins, and operational efficiency. Enterprise software integration is anchored by SAP SE, a German-based company providing extensive supply chain management platforms that connect logistics data across global networks. IBM Corporation, a global IT and consulting firm, represents the broader technology providers offering scalable cloud infrastructure, AI capabilities, and cybersecurity solutions for maritime applications. These companies collectively illustrate the diverse expertise required for comprehensive digital transformation initiatives across the industry.
| Leading Market Players |
|---|
| Tech Mahindra Limited |
| KONGSBERG Gruppen ASA |
| ABB |
| Advantech |
| Wipro |
| SAP SE |
| Hexaware Technologies |
| Kintetsu World Express |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Port congestion, exacerbated by global trade fluctuations, significantly influences pricing posture for digital maritime solutions. This operational pressure compels shipping operators and port authorities to invest in advanced analytics and automation, seeking to optimize throughput and reduce demurrage costs.
Pricing Analysis
Configured-to-order solutions for integrated digital twins and AI systems command a premium over standardized SaaS-tiered offerings. The dominant pricing structure combines subscription models for platform access with project-based fees for complex integrations and customization. Price differentiation stems from the level of bespoke development and the intensity of after-sales service. Pricing softness for basic IoT solutions reflects increasing technology maturity, while smaller fleet owners and operators exhibit higher price sensitivity than major container lines.
Supply Chain Analysis
The upstream supply for maritime digital solutions draws from global technology hubs, primarily in the United States, Germany, and China. Critical inputs include microchips for IoT devices, specialized AI/ML algorithms, and maritime-tech talent. The supply chain faces structural risk from cybersecurity vulnerability, given the interconnected nature of port and vessel systems. Distribution of digital solutions primarily occurs through direct sales from enterprise software providers and specialized operational technology vendors, often augmented by system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital transformation of maritime freight faces constraints from a shortage of hybrid talent combining maritime operational knowledge with data science expertise. This capability gap limits the pace of advanced technology adoption and integrated system deployment.
For Market Incumbents:Insulate core service offerings by actively participating in open, interoperable digital ecosystems to counter platform dependency risk. Diversify service portfolios beyond basic tracking into advanced predictive analytics and automated compliance solutions. Strategic partnerships with niche maritime-tech innovators can integrate specialized operational technology with existing enterprise platforms. Investing in maritime-specific AI/ML R&D provides proprietary advantages in fuel optimization and asset management.
For New Entrants and Emerging Players:Greenfield digitalization projects in emerging economies across Southeast Asia and Africa represent the most penetrable entry point for end-to-end digital systems. Automated compliance solutions for the IMO's FAL Convention and EU's ICS2 offer another specific white-space target. Focus on providing cost-effective, cloud-based platforms that streamline regulatory reporting and data exchange. Offering solutions with rapid deployment and clear, measurable efficiency gains attracts early adopters.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among SaaS providers offering specialized compliance or predictive analytics platforms. The market demonstrates long-term viability, underpinned by sustained regulatory mandates for data transparency and efficiency. Target niche maritime-tech innovators possessing proprietary AI/ML algorithms or robust IoT sensor networks. A key signal to watch is the widespread adoption of open, interoperable data standards, indicating ecosystem maturation and reduced integration friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating disparate systems enhances supply chain visibility for logistics providers. |
| Strategic Partnership | Partnerships between IT giants and OT specialists bridge operational and enterprise data gaps. |
| Acquisition of Specialist Firm | Acquiring niche AI/ML firms accelerates predictive maintenance and route optimization capabilities. |
| Product Launch: Automated Compliance Software | New software automates IMO FAL Convention data exchange for vessel operators. |
| Geographic Expansion into Emerging Ports | Expanding into Southeast Asia and Africa captures greenfield digitalization opportunities for new vendors. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. Interviews included shipping operators, port authority officials, freight forwarders, and technology CTOs. Secondary data sources encompassed regulatory filings, maritime industry reports, port authority publications, and enterprise software vendor disclosures. This approach ensured robust bottom-up and top-down triangulation of market insights.
Quantitative models were calibrated using historical market performance and projected technological adoption rates across the analysis window. The analytical framework integrated supply-demand dynamics, segmenting the market by technology, application, end-user, deployment model, and regional regulatory impact. Compound annual growth rates were derived from a weighted average of segment-specific growth trajectories. Key forecast inputs included global vessel traffic volumes and upcoming regulatory compliance deadlines.
Practitioners should monitor geopolitical events, major technological breakthroughs, or significant shifts in global trade policy for early signals of market revision. Forecasts reflect assumptions regarding cybersecurity resilience and continued regulatory enforcement. Cross-checking against independent maritime intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Aircraft Sensors Market
Others
Magnetic Stripe Readers Market
Others
Bulgur Market
Others
Cloud Advertising Market
Others
Wood Stoves Market
Others
Safety Instrumented System (SIS) Market
Others
Caster Wheels Market
Others
North America Printed Signage Market
Others
North America Micro Market
Others
Mainframe Computers Market
Others
5G Devices Market
Others
North America Enterprise Video Market
Others
Human Enhancement Technology Market
Others
Global Learning Analytics Market
Others
Hip Tendinitis Market
Others
Hotel Wardrobe Market