
 Caster Wheels Market | 2026-2036
Caster Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Caster Wheels Market Analysis
Chinese foundry and stamping capacity is restructuring the global supply base for caster yokes and wheel cores. TENTE International leverages its European distribution network to sustain premium positioning in medical and institutional channels. Hamilton Caster anchors North American heavy-duty demand through in-house forging and custom engineering capabilities. Colson Group competes across multiple price tiers through brand portfolio breadth spanning institutional and commercial applications.
Caster wheels are rolling mechanisms comprising a wheel mounted to a fork or housing, typically incorporating bearings rated for specific load thresholds and rotational speeds, designed to enable directional mobility of carts, equipment, and fixtures across floors and work surfaces. Their primary industrial purpose centers on reducing manual handling injury risk while improving workflow throughput in manufacturing, healthcare, and material handling environments. Swivel caster configurations lead unit volume due to omnidirectional utility in tight-space applications, while polyurethane material grades command margin premiums for floor protection and noise reduction in medical device and furniture settings. Heavy duty load capacity segments represent the fastest-growing structural category as automated guided vehicles and industrial automation equipment multiply weight requirements.
The US Occupational Safety and Health Administration and the European Committee for Standardization enforce load-rating and ergonomic standards that directly shape caster specification requirements in workplace equipment. China's National Institute of Standards and Technology participation through GB standard alignment affects export qualification protocols for Asian-manufactured caster assemblies entering regulated markets. Stakeholders must monitor evolving floor surface standards and sustainability mandates for wheel material recyclability as specification criteria harden across institutional procurement frameworks.
Market Dynamics
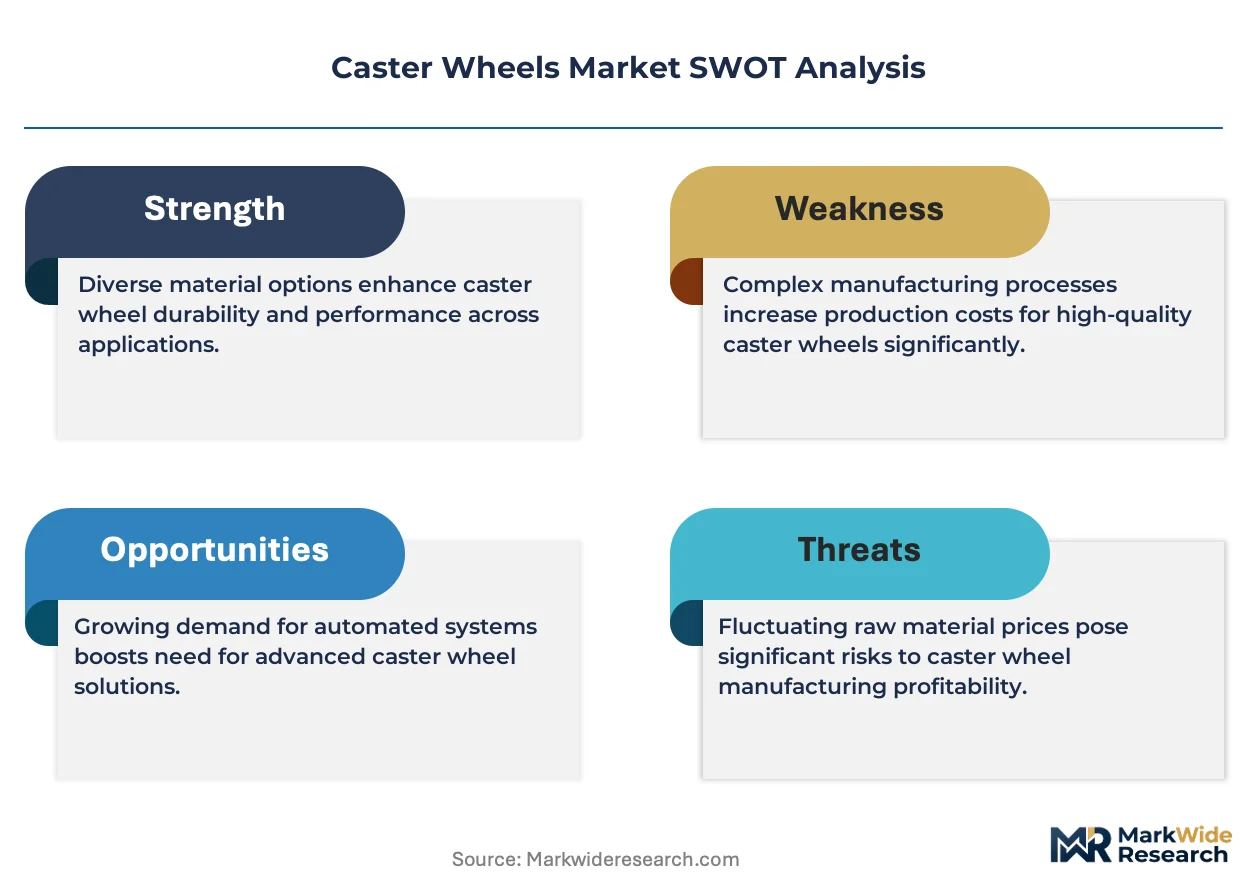
Polyurethane formulation chemistry is restructuring caster wheel manufacturing as REACH and F-Gas Regulation compliance costs force European suppliers to reformulate core materials, compressing margin structures while opening technical differentiation paths for compliant producers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for hydrofluorocarbons are accelerating polyurethane foam chemistry innovation, creating first-mover advantages for reformulation-capable suppliers serving institutional procurement frameworks.
- Automated guided vehicles:Manufacturing and logistics automation is multiplying load capacity requirements, pulling heavy-duty caster specifications into standard equipment configurations.
- Medical device logistics:Hospital retrofit programs for mobility infrastructure are expanding caster procurement volumes through specification upgrades in patient handling and diagnostic equipment.
Market Restraints
- Steel price volatility:Foundry-grade steel input costs fluctuate with scrap metal and energy markets, compressing margin predictability for yoke and core manufacturers without captive metallurgy capabilities.
- Chinese supply concentration:Stamping and casting capacity clustering in Zhejiang and Guangdong provinces creates geographic risk exposure for buyers dependent on Asian component sourcing.
- Floor surface standard fragmentation:Incompatible certification regimes across OSHA, CEN, and GB standards force redundant testing cycles, extending qualification timelines for multi-market product launches.
Strategic Opportunities
- India manufacturing:Production-linked incentive schemes and BIS standard alignment are attracting caster assembly investment to serve domestic automotive and material handling equipment growth.
- Wheel material recyclability:EU Green Deal circular economy mandates are creating specification premiums for thermoplastic polyurethane grades with validated closed-loop recovery pathways.
- Direct institutional procurement:Healthcare system consolidation is compressing distributor tiers, enabling qualified manufacturers to capture margin through GPO and IDN direct contracting.
Industry Challenges
- REACH registration expertise:Polyurethane chemistry compliance requires specialized regulatory affairs capacity that mid-tier compounders struggle to staff, creating bottleneck risk for European market access.
- Legacy ERP integration:Automated guided vehicle fleet management systems demand real-time caster-mounted sensor data transmission, forcing hardware redesign cycles for established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caster Wheels Market |
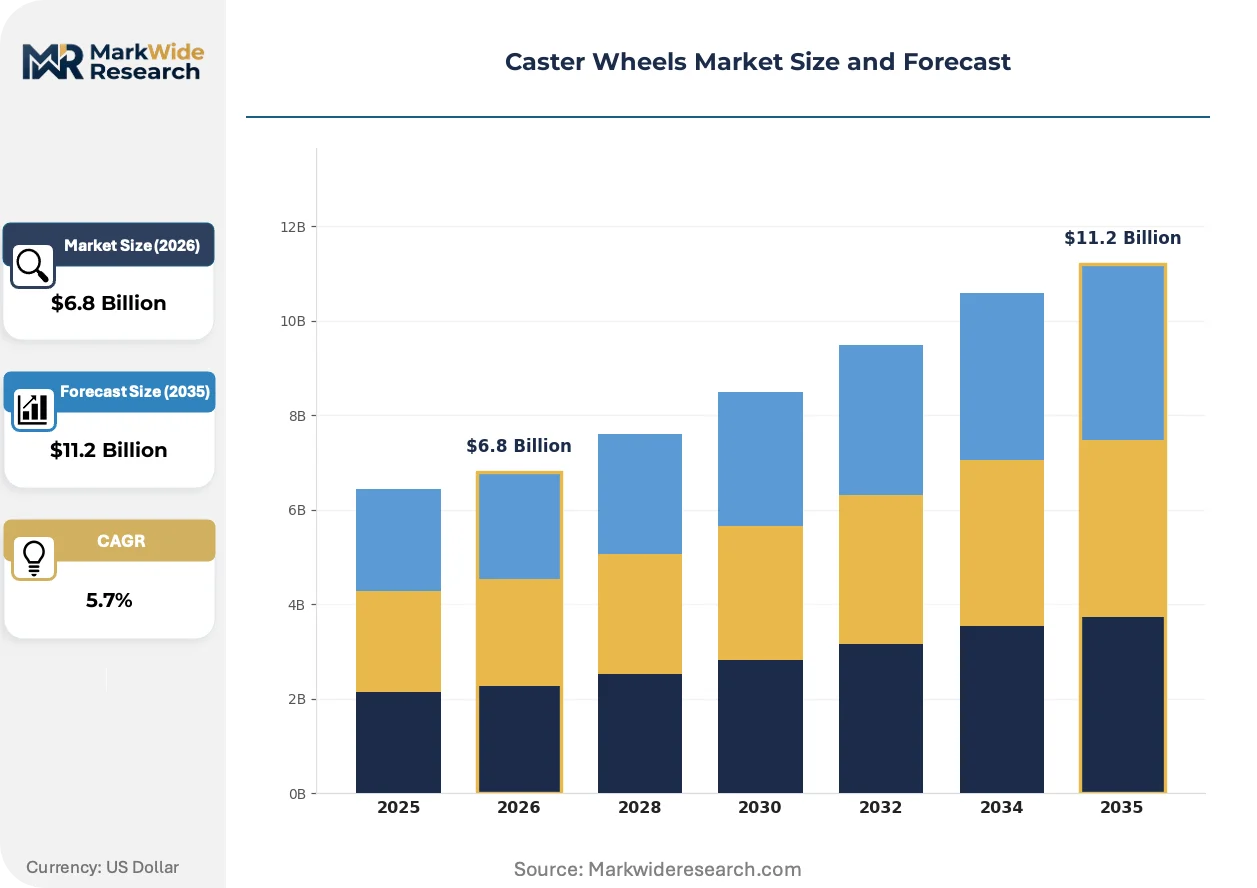
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Caster, Bolt Hole Caster, Swivel Caster, Rigid Caster Material: Plastic, Rubber, Metal, Polyurethane Application: Furniture, Industrial Equipment, Medical Devices, Automobiles Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty |
| Companies Covered | TENTE International, Albion Industries, Colson Group, Brauer, Faultless Caster, Hamilton Caster, Caster Concepts, STEINCO Paul vom Stein, Blickle Räder+Rollen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caster Wheels Market Emerging Trajectories
Material science advances and procurement digitization are compressing product lifecycles while elevating specification precision requirements across institutional buyer segments.
High-resilience thermoplastic polyurethane is overtaking conventional cast polyurethane in medical caster applications. Hospital equipment OEMs specify TPU grades for superior floor protection and acoustic performance in patient care environments. This material transition is compressing volume share for legacy rubber and standard polyurethane formulations in premium channel segments.
REACH authorization procedures are tightening substance restrictions for plasticizer and stabilizer chemistries used in wheel tread compounds. European compounders must reformulate legacy recipes or face market withdrawal, forcing qualification investments that smaller suppliers cannot absorb. Medical device and furniture channels are responding with accelerated supplier consolidation toward REACH-authorized compounders.
Digital specification platforms are replacing traditional distributor catalogs in institutional procurement workflows. Healthcare and industrial buyers now configure load rating, material grade, and brake options through parametric selectors, bypassing traditional sales engineering touchpoints. This channel compression is most visible in German and US hospital system purchasing, where procurement centralization mandates favor platform-enabled suppliers.
Caster Wheels Market Segmentation
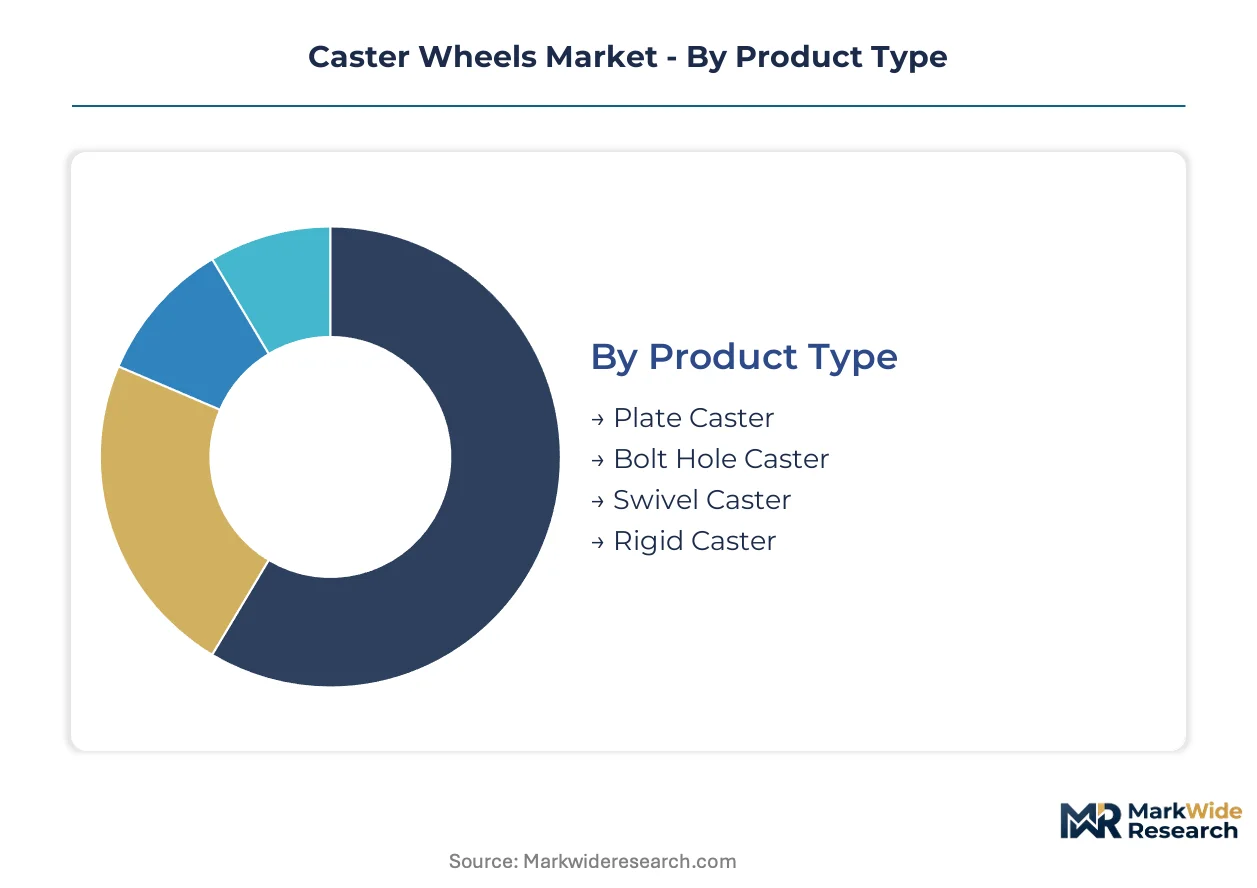
Caster wheel segmentation maps directly to procurement complexity tiers, with specification precision varying sharply across medical, industrial, and furniture channels. Certification burdens cluster unevenly across these boundaries, creating margin differentiation opportunities for qualified suppliers.
Product Type:
OSHA load-rating documentation applies universally, while CEN EN 12527-12535 series testing concentrates on swivel and rigid configurations for European institutional sales. Plate and bolt hole variants face lighter documentation thresholds in commercial furniture channels.
- Plate Caster:Flat mounting surface with four-bolt or welded attachment geometry dominates furniture and light industrial fixture applications. Demand concentrates in US residential and contract office furniture manufacturing, where bulk procurement contracts favor standardized four-inch plate dimensions and zinc-plated finishes.
- Bolt Hole Caster:Stem-insertion mounting with threaded or grip-ring retention enables rapid field replacement in rental equipment and temporary installations. German event infrastructure and Dutch warehouse logistics sectors specify this format for modularity.
- Swivel Caster:Raceway-bearing assembly permits 360-degree rotation under load, essential for tight-space maneuverability in hospital beds and retail displays.
- Rigid Caster:Fixed-direction travel provides directional stability in long-aisle transport applications and automated guided vehicle base configurations.
Swivel caster sits at the top of the volume ranking, with bolt hole caster climbing the fastest.
Material:
Cost tier stratification separates commodity inputs from specification-grade compounds, with thermoplastic polyurethane commanding three-to-five-fold premiums over standard rubber in medical channels.
- Plastic:Injection-molded polypropylene and nylon formulations serve price-sensitive furniture and retail fixture segments where load thresholds remain below 100 kilograms. Chinese molding capacity in Zhejiang province supplies global volume for this tier.
- Rubber:Natural and synthetic elastomer treads provide floor protection and shock absorption in institutional applications. REACH authorization constraints on plasticizer chemistries are compressing European compounder margins and consolidating supply toward ECHA-registered producers.
- Metal:Cast iron, forged steel, and ductile iron cores with hardened treads dominate extra-heavy-duty industrial and automotive assembly line applications. US foundry capacity in Ohio and Pennsylvania anchors North American supply for forging-grade specifications.
- Polyurethane:Cast and thermoplastic grades deliver load-bearing capacity with floor protection and acoustic dampening. Hospital equipment OEMs in Germany and the US specify high-resilience TPU for patient care environments, with EU Green Deal circular economy mandates creating specification premiums for closed-loop recyclable grades.
Polyurethane captures the highest margin tier, with thermoplastic grades expanding most quickly in medical procurement.
Application:
Customer type fragmentation separates specification-heavy institutional buyers from price-driven commercial procurement, with channel access requirements varying sharply across these boundaries.
- Furniture:Residential, office, and hospitality seating and storage mobility requirements span light to medium duty ratings. Volume concentrates in Chinese export manufacturing and Polish contract furniture production for European markets.
- Industrial Equipment:Manufacturing, warehousing, and logistics material handling equipment demands heavy-duty configurations with predictive maintenance sensor integration. Automated guided vehicle fleet expansion is pulling smart caster specifications with real-time load monitoring.
- Medical Devices:Patient beds, diagnostic equipment, and surgical carts require antimicrobial finishes, precision bearings, and floor protection certification. FDA device regulations and MDR compliance in Europe force dual-qualification investments for suppliers serving transatlantic OEMs.
- Automobiles:Assembly line dollies, engine cradles, and aftermarket shop equipment specify extra-heavy-duty metal-core configurations. German automotive manufacturing density sustains premium demand for forged steel yoke assemblies.
Industrial equipment leads absolute volume, with medical devices gaining share fastest through specification upgrades.
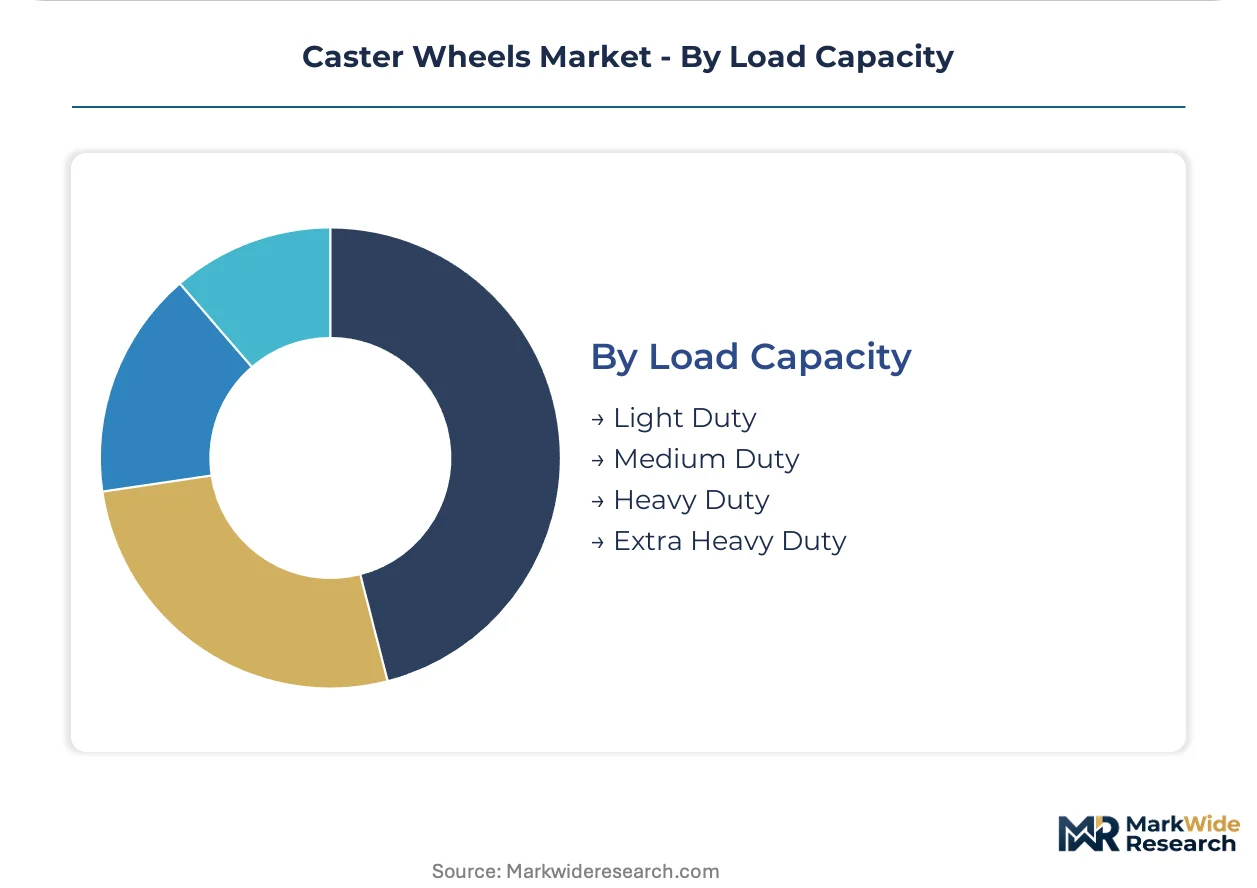
Load Capacity:
Supply concentration in forging and casting capacity shapes competitive positioning, with captive metallurgy capabilities separating integrated producers from assembly-only competitors.
- Light Duty:Sub-100 kilogram ratings serve furniture, retail displays, and office equipment. Stamping and injection molding supply chains in Guangdong province dominate global component sourcing.
- Medium Duty:100-500 kilogram thresholds cover institutional food service, warehouse carts, and light manufacturing. Indian PLI scheme incentives are attracting assembly investment to serve domestic material handling growth.
- Heavy Duty:500-2,000 kilogram specifications support manufacturing automation, automotive assembly, and logistics equipment. Hamilton Caster and TENTE International anchor premium positioning through in-house forging and European distribution networks respectively.
- Extra Heavy Duty:Above-2,000 kilogram ratings for aerospace tooling, shipyard equipment, and specialized industrial applications require custom engineering and finite element analysis certification. US and German producers maintain technical leadership through captive metallurgy and application engineering capacity.
Medium duty holds the largest installed base, with heavy duty showing the steepest expansion trajectory from automation equipment multiplication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting caster wheel production toward jurisdictions with lower compliance costs, even as specification-heavy end-users in regulated markets demand traceable supply chains. European REACH and F-Gas mandates compress margins for reformulation-heavy producers, while Asian stamping capacity offers cost advantages for commodity-grade yoke assemblies.
United States
Hospital retrofit programs and automated guided vehicle fleet expansion drive specification demand for heavy-duty and medical-grade casters. OSHA load-rating documentation requirements shape procurement workflows across manufacturing and healthcare sectors. Ohio and Pennsylvania foundry clusters anchor domestic forging capacity for extra-heavy-duty industrial applications.
Germany
Automotive assembly line automation and medical device OEM concentration sustain premium demand for precision-bearing and floor-protection-certified casters. EU F-Gas Regulation and REACH authorization procedures force polyurethane compounder consolidation toward ECHA-registered suppliers. Baden-Württemberg and Bavaria industrial belts concentrate forging and distribution infrastructure for European institutional channels.
China
Export manufacturing scale and domestic material handling equipment growth absorb expanding stamping and molding capacity. GB standard alignment with international protocols affects qualification timelines for caster assemblies entering regulated markets. Zhejiang and Guangdong province clusters dominate global component sourcing for light and medium duty wheel cores and yokes.
India
Production-linked incentive schemes and BIS standard harmonization attract assembly investment to serve domestic automotive and logistics equipment expansion. Central government manufacturing incentives reduce import dependence for medium-duty industrial casters. Maharashtra and Gujarat industrial corridors concentrate new capacity for material handling and automotive supplier tier integration.
Japan
Precision manufacturing equipment and semiconductor fab automation sustain demand for low-vibration, high-accuracy caster specifications. METI industrial standards and JIS certification requirements filter supplier qualification for domestic OEM procurement. Kansai and Chubu manufacturing belts maintain specialized forging and bearing integration capabilities for premium industrial segments.
Caster Wheels Market Vendor Landscape
German and US producers anchor premium-tier specification supply; Chinese fabricators hold volume-driven commodity positioning. The vendor base stratifies across three functional tiers: integrated forging houses with captive metallurgy, specialized medical-grade compounders with REACH authorization, and assembly-focused stampers serving price-sensitive channels. Competitive intensity centers on polyurethane chemistry compliance and automated guided vehicle sensor integration capabilities.
Among European-anchored specialists, TENTE International and STEINCO Paul vom Stein exemplify distribution-network-dependent positioning for institutional procurement frameworks. Hamilton Caster and Colson Group represent contrasting North American archetypes: the former through in-house forging and custom engineering capacity, the latter through brand portfolio breadth spanning multiple price tiers. Albion Industries and Blickle Räder+Rollen occupy mid-market technical positions, while Caster Concepts and Faultless Caster illustrate assembly-specialist models. Brauer rounds out the named set as a regional European fabricant.
| Leading Market Players |
|---|
| TENTE International |
| Albion Industries |
| Colson Group |
| Brauer |
| Faultless Caster |
| Hamilton Caster |
| Caster Concepts |
| STEINCO Paul vom Stein |
| Blickle Räder+Rollen |
| Others |
Supply Flow & Price Mechanics
REACH-authorized polyurethane chemistry certification separates premium medical-grade compounders from commodity rubber stampers, with this bifurcation expressing simultaneously in five-fold price premiums for TPU grades and in captive European distribution networks that bypass distributor markups for qualified institutional buyers.
Pricing Analysis
Distributor margin compression in healthcare procurement channels is accelerating direct-to-OEM contracting as hospital GPO consolidation eliminates intermediary tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and load rating precision, with FDA and MDR dual-qualified suppliers capturing least price-sensitive medical device OEM segments while furniture channels face acute cost compression from Chinese molding capacity. Pricing pressure stems from steel scrap volatility and REACH reformulation investments, with German automotive and US hospital buyers exhibiting lowest price elasticity due to specification lock-in.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg, Ohio, and Zhejiang province anchor hub-and-spoke fulfillment patterns for respective market tiers. Geographic supply concentration centers on China for stamped yoke assemblies, Germany for forged precision bearings, and the US for extra-heavy-duty metallurgy. Raw material dependencies draw from foundry-grade steel scrap, polyol and isocyanate feedstocks for polyurethane, and injection-molding resin grades. Single-source vulnerability concentrates in Guangdong stamping clusters for light-duty furniture casters. Distribution runs through medical equipment OEM direct contracts, industrial distributor networks, and contract furniture manufacturer bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in REACH-compliant polyurethane compounders and sensor-integrated heavy-duty configurations, with cost-down drivers from Indian PLI scheme manufacturing incentives and premium-tier shift toward closed-loop recyclable TPU grades in EU institutional procurement.
For Market Incumbents: Deepen captive forging capabilities in Ohio and Pennsylvania to defend against Chinese supply concentration risks while accelerating REACH-authorized compounder consolidation to capture medical device OEM specification premiums. Vertical integration into sensor hardware for automated guided vehicle fleet integration represents the critical R&D lever for heavy-duty segment defense. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for reformulation-capable polyurethane suppliers to displace legacy compounders facing market withdrawal. White-space targets include Indian domestic automotive assembly under PLI incentives and US hospital retrofit direct contracting channels. A specification-first go-to-market angle through digital procurement platform integration bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration expertise bottlenecks European market access for mid-tier compounders. Long-term viability favors integrated producers with captive metallurgy and authorized chemistry portfolios over assembly-only stampers. Watch for automated guided vehicle fleet sensor mandates as inflection indicator for smart caster specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Authorized Compound Investment | ECHA registration secures European medical device OEM access against reformulation-forced exits. |
| India PLI Scheme Manufacturing Entry | BIS-aligned assembly capacity captures domestic automotive and logistics equipment procurement growth. |
| Sensor-Integrated Heavy-Duty Development | Real-time load monitoring meets automated guided vehicle fleet management system data requirements. |
| Direct Healthcare GPO Contracting | Bypassing distributor tiers captures margin compression from hospital system consolidation mandates. |
| Closed-Loop TPU Grade Certification | EU Green Deal circular economy mandates create specification premiums for validated recovery pathways. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement managers, hospital GPO contracts specialists, and polyurethane compounder R&D directors grounded qualitative assessment, cross-referenced with customs trade data, ECHA substance registration databases, SEC equipment manufacturer filings, and hospital procurement contract disclosures. Bottom-up channel volume estimates triangulated against top-down industrial equipment production forecasts.
Segment-level projections across load capacity tiers, material chemistry grades, application channels, and regional manufacturing clusters informed analytical framework construction throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, automation penetration curves, and regulatory compliance cost trajectories. Key inputs included automated guided vehicle fleet deployment schedules and REACH authorization timeline assumptions.
Revisions become necessary when F-Gas Regulation phase-down accelerates, steel scrap volatility exceeds historical bands, or hospital procurement centralization reverses toward distributor re-intermediation. Forecasts reflect documented assumptions on polyurethane substitution elasticities and geographic supply shift velocities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Tablet Market
Others
Buchner Funnels Market
Others
AI in Home Automation Market
Others
Computer on Module Market
Others
Turkey Health and Medical Insurance Market
Others
APAC Machine Vision Systems Market
Others
India Smart Home Market
Others
Radiation Detection Monitoring and Safety Market
Others
Fluorite Market
Others
Cloud DVR Market
Others
South America Orange Market
Others
South Korea Smart Home Market
Others
Europe Indoor LBS Market
Others
LED Packaging Market
Others
Smart Home As a Service Market
Others
South Asia Geosynthetics Market