
 Wood Stoves Market | 2026-2036
Wood Stoves Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Stoves Market Insights
Specialty hearth retail networks is rewriting how premium wood stoves reach end consumers, bypassing traditional big-box intermediaries. Hearth & Home Technologies leverages its captive distribution to sustain margin control across North American showrooms. Blaze King differentiates through extended burn-time engineering that anchors its position in high-efficiency segments. Napoleon competes on manufacturing scale, operating vertically integrated foundries that supply cast iron components at cost advantage.
Wood stoves are self-contained heating appliances designed for controlled biomass combustion, typically fabricated from cast iron, steel plate, or soapstone composite with internal firebrick lining and adjustable air intake systems to regulate burn rate and thermal output. Their primary commercial purpose is to deliver radiant and convective heat to enclosed spaces using renewable solid fuel. Pellet stoves command the fastest-growing product category as automated feed systems and electronic ignition reduce operator skill requirements. Cast iron stoves retain the largest installed base among replacement buyers seeking durability and classic aesthetic integration. Residential heating absorbs the dominant share of volume, though emergency heating applications are gaining structural importance following grid reliability disruptions in temperate climates.
EPA certification requirements under the New Source Performance Standards dictate particulate emission thresholds, compelling manufacturers to redesign combustion chambers and catalytic after-treatment systems. The EU Ecodesign Directive and associated F-Gas Regulation create parallel compliance obligations for European market access, while CSA B415 testing protocols govern Canadian efficiency claims. Stakeholders must monitor evolving state-level wood-burning bans in air quality non-attainment zones, as these local prohibitions threaten to fragment addressable demand faster than federal standards harmonize product specifications.
Market Dynamics
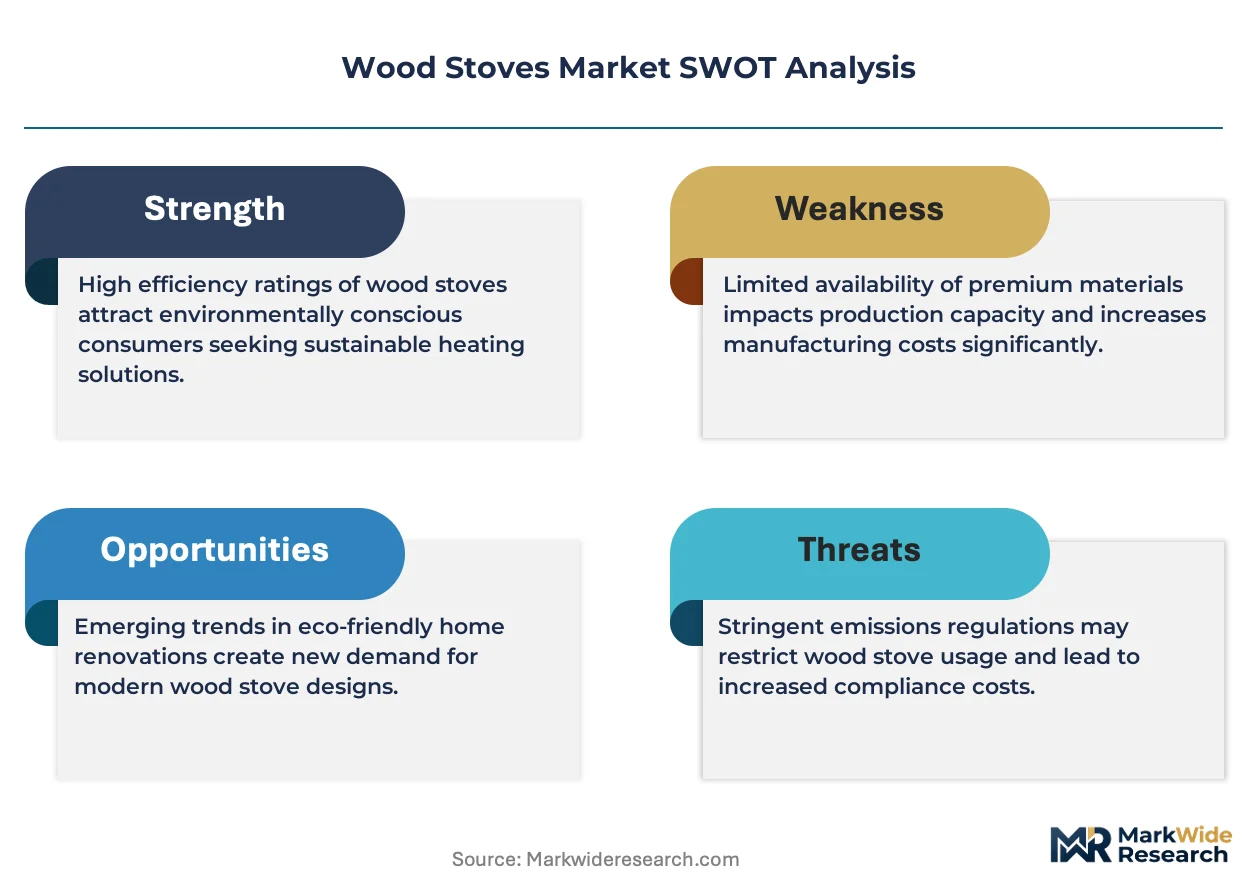
EPA Phase IV emission standards are compressing combustion chamber designs and forcing manufacturers to absorb catalytic converter costs while maintaining price accessibility for rural cabin owners.
Growth Catalysts
- Off-Grid Residency Expansion:Rural property owners in Montana, Maine, and Vermont are installing EPA-certified units as primary heat sources for seasonal and year-round dwellings disconnected from natural gas infrastructure.
- Biomass Fuel Economics:Cordwood pricing stability relative to heating oil and propane is reinforcing wood stove operating cost advantages in forested regions of the United States and Canada.
- CSA B415 Certification:Canadian efficiency testing protocols are creating cross-border product standardization that reduces manufacturer compliance duplication across North American markets.
Market Restraints
- Cast Iron Input Volatility:Foundry-grade pig iron pricing fluctuations are compressing margin structures for stove fabricators dependent on bulk metallurgical supply contracts.
- Air Quality Non-Attainment Bans:California's San Joaquin Valley and Colorado's Front Range counties are implementing seasonal wood-burning prohibitions that eliminate addressable demand in high-income exurban zones.
- Heat Pump Substitution:Cold-climate electric heat pumps with coefficient of performance ratings above 2.5 are capturing replacement demand from grid-connected rural households.
Strategic Opportunities
- Alaska Rural Energy:Villages beyond the Railbelt grid lack natural gas distribution and present concentrated demand for high-efficiency biomass heating with extended burn-time engineering.
- Emergency Preparedness Positioning:Grid reliability disruptions in Texas and the Pacific Northwest are creating first-time buyer segments seeking backup heat independent of electrical infrastructure.
- Hearth Retail Network Expansion:Specialty showroom formats in secondary metro markets are bypassing big-box intermediaries and capturing margin through consultative sales of certified premium units.
Industry Challenges
- Catalytic Combustor Sourcing:Ceramic honeycomb substrate supply concentration among three North American suppliers is creating procurement bottlenecks for EPA Phase IV-compliant stove production ramps.
- Installation Technician Certification:NFI Woodburning Specialist credential scarcity is constraining sales velocity in markets where code enforcement requires licensed hearth installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Stoves Market |
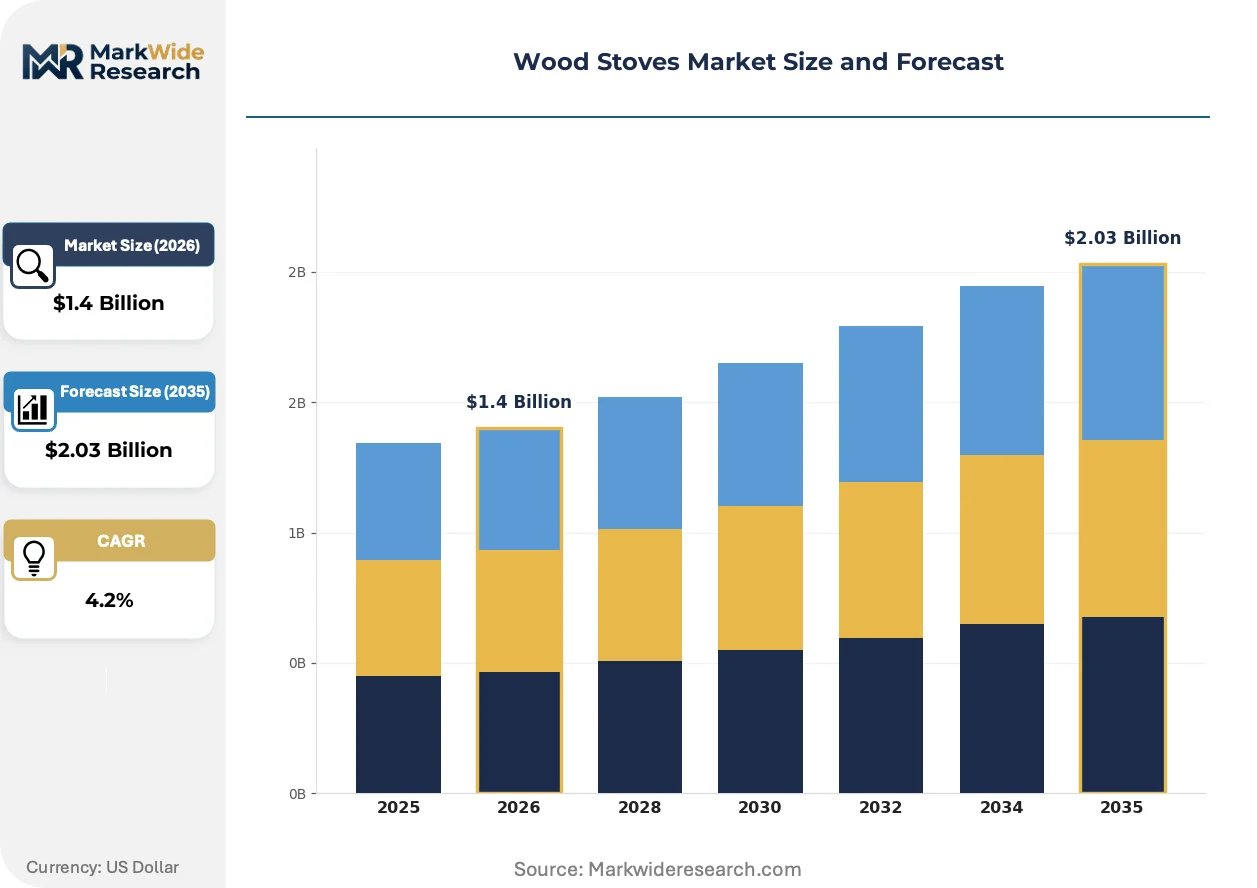
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellet Stoves, Conventional Stoves, Soapstone Stoves, Cast Iron Stoves Application: Residential Heating, Commercial Heating, Outdoor Heating, Emergency Heating Fuel Type: Wood Pellets, Logs, Compressed Wood Bricks, Biomass Distribution Channel: Online Retail, Home Improvement Stores, Specialty Stores, Wholesale Distributors |
| Companies Covered | Regency, Buck Stove, Hearth & Home Technologies, Englander, Osburn, Drolet, Blaze King, Ventis, Napoleon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Stoves Market Trends and Innovations
Combustion engineering and distribution architecture are undergoing parallel transformation as emission thresholds tighten and direct-to-consumer channels mature.
Catalytic after-treatment systems are hybridizing with secondary combustion chambers to achieve sub-2.0 g/hr particulate emission rates. Off-grid cabin builders in the northern Rocky Mountains are specifying these hybrid configurations for permit approval in counties with strict burn-day ordinances. The technology is hybridizing product positioning between traditional radiant heat delivery and regulatory compliance premiums.
The EPA New Source Performance Standards Phase IV mandate is eliminating non-catalytic stove designs from certified product lines. Manufacturers are retooling foundry patterns and firebox geometries to accommodate catalyst insertion ports and temperature probe integration. Residential replacement buyers in New England and the Great Lakes states are absorbing price premiums of fifteen to twenty-five percent for compliant units.
Direct-to-consumer digital channels are displacing traditional hearth retail intermediaries for accessory and maintenance part sales. Millennial cabin owners in the Pacific Northwest are purchasing replacement gaskets, firebricks, and catalytic combustors through manufacturer portals rather than local dealers. This pattern is most visible in Washington and Oregon where urban-based second-home owners lack established relationships with rural hearth retailers.
Wood Stoves Market Segmentation
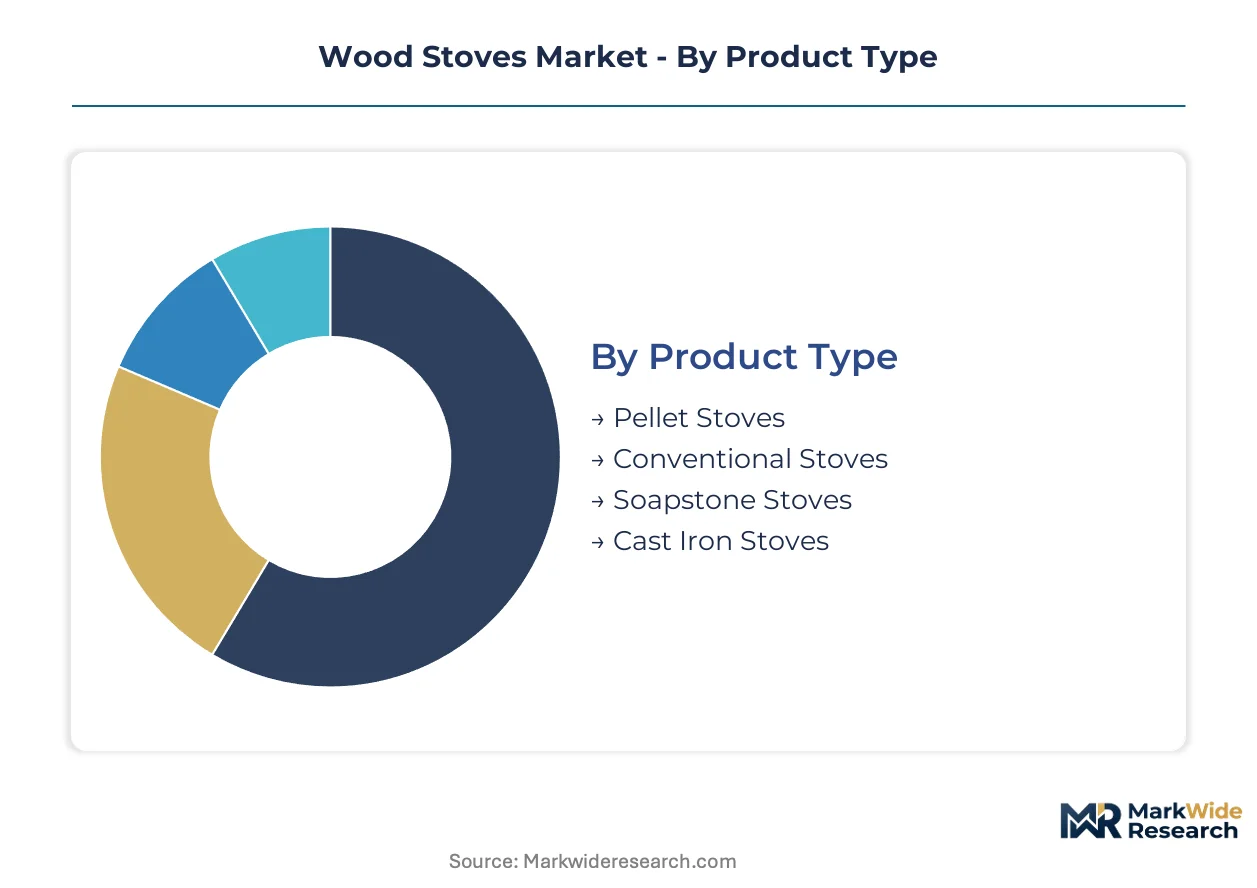
Wood stove purchasing decisions split across combustion technology, installation context, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that manufacturers must navigate.
Product Type:
Cost tier differentiation separates automated feed systems from manual combustion appliances.
- Pellet Stoves:Automated auger-fed systems with electronic ignition and programmable thermostats reduce operator skill demands. Demand concentrates among aging rural homeowners in Maine and Vermont seeking hands-off heating. EPA Phase IV compliance arrives more easily through precise fuel-to-air ratio control.
- Cast Iron Stoves:Fabricated from foundry-grade pig iron with internal firebrick lining, these units deliver thermal mass retention and classic aesthetic integration. Replacement buyers across the Great Lakes states prioritize durability and heritage design over efficiency ratings.
- Conventional Stoves:Steel plate construction with basic air intake adjustment dominates entry-level price points.
- Soapstone Stoves:Composite thermal mass construction extends radiant heat release cycles for overnight burns.
Cast Iron Stoves commands the established base. The steepest expansion runs through Pellet Stoves.
Application:
Installation context determines regulatory scrutiny intensity and seasonal demand patterns.
- Residential Heating:Primary and secondary heat sources for single-family dwellings, cabins, and seasonal residences. Off-grid property owners in Montana and Idaho install EPA-certified units as sole heat sources where natural gas infrastructure terminates miles from property lines. Cordwood economics versus propane heating oil reinforces adoption in forested regions.
- Emergency Heating:Backup systems activated during grid reliability failures. Texas homeowners purchased record volumes following winter storm Uri disruptions. Pacific Northwest buyers seek independence from hydroelectric grid vulnerability during ice storm seasons.
- Commercial Heating:Small-scale hospitality and retail installations in historic districts.
- Outdoor Heating:Patio and recreational fire features with minimal emission controls.
Residential Heating absorbs dominant volume. Emergency Heating is climbing fastest as climate volatility intensifies.
Fuel Type:
Supply chain maturity and storage logistics differentiate solid fuel categories.
- Wood Pellets:Densified biomass with standardized moisture content and automated handling compatibility. Manufacturing concentrates in the US Southeast and British Columbia where sawmill residue supply is captive. Pellet stoves require this fuel format for auger feed mechanism reliability.
- Logs:Cordwood in hardwood and softwood species split and seasoned on-site or purchased locally. Rural Alaska villages beyond the Railbelt grid rely exclusively on locally harvested timber. Seasoned cordwood pricing stability versus heating oil reinforces operating cost advantages.
- Compressed Wood Bricks:Densified logs for simplified stacking and transport.
- Biomass:Agricultural residue and energy crop feedstocks in experimental deployment.
Logs retains the largest installed base. Compressed Wood Bricks is expanding most quickly among urban second-home owners lacking chainsaw skills.
Distribution Channel:
Customer relationship depth and margin capture vary sharply across procurement pathways.
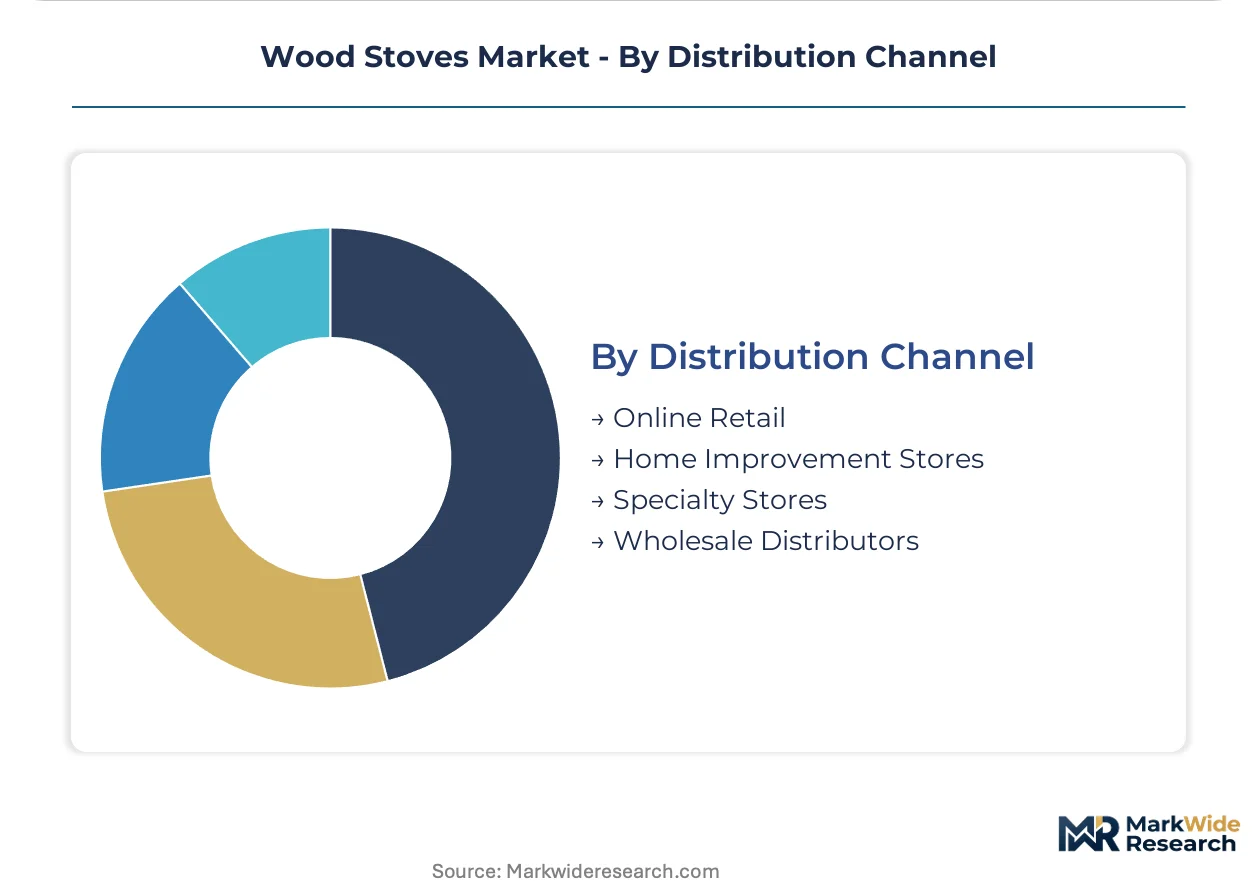
- Specialty Stores:Hearth retail showrooms with NFI-certified staff providing consultative sales and installation coordination. Hearth & Home Technologies operates captive networks across secondary metro markets. These outlets bypass big-box intermediaries and capture margin through premium unit placement.
- Online Retail:Manufacturer-direct portals and marketplace platforms for accessories, replacement parts, and standardized units. Millennial cabin owners in Washington and Oregon purchase catalytic combustors and gaskets without rural dealer relationships.
- Home Improvement Stores:Big-box retail with limited technical support and self-directed selection.
- Wholesale Distributors:Regional supply houses serving contractor and builder channels.
Specialty Stores commands the premium transaction base. Online Retail is gaining share fastest among replacement part purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Alaska Pipeline System terminates at Valdez, anchoring rural energy distribution patterns that extend wood stove demand into villages beyond the Railbelt grid. This infrastructure geography shapes biomass heating economics across northern latitudes where natural gas distribution fails to reach.
United States
Montana, Maine, and Vermont cabin owners install EPA-certified units as primary heat sources where natural gas infrastructure terminates miles from property lines. EPA Phase IV emission standards are eliminating non-catalytic stove designs from certified product lines. The northern Rocky Mountains cluster around Missoula and Bozeman is specifying hybrid catalytic configurations for permit approval in counties with strict burn-day ordinances.
Canada
CSA B415 efficiency testing protocols are creating cross-border product standardization that reduces manufacturer compliance duplication. Cordwood pricing stability versus heating oil reinforces operating cost advantages in forested regions of British Columbia and Quebec. The Vancouver Island and Gulf Islands corridor is absorbing price premiums for compliant units as local air quality management districts tighten seasonal burning restrictions.
Norway
EU Ecodesign Directive compliance obligations govern market access for imported appliances while domestic producers leverage heritage cast iron fabrication expertise. The country's national environmental regulator enforces particulate thresholds that exceed federal minimums in Oslo and Bergen airsheds. The Østlandet region surrounding Oslo maintains the densest concentration of soapstone stove installations for overnight thermal mass retention.
Sweden
Nordic building codes mandate renewable heat shares that preserve wood stove relevance in new construction despite heat pump penetration. The Swedish Environmental Protection Agency administers testing protocols aligned with EU Ecodesign but with additional domestic efficiency labeling requirements. The Värmland and Dalarna counties cluster represents the strongest replacement demand as aging installations from the 1980s construction boom reach end-of-service intervals.
Finland
Sauna-adjacent heating traditions sustain dual-purpose stove specifications that combine residential space heating with water jacket integration. The country's national safety and chemical agency regulates combustion appliance emissions under harmonized EU frameworks with supplementary national durability testing. The Lakeland region surrounding Kuopio and Joensuu concentrates rural off-grid residency where cordwood harvesting rights attach to property ownership.
Wood Stoves Market Competitive Landscape
On the supply side, the industry is consolidating around captive distribution networks and foundry-integrated fabricators with cost advantages in metallurgical inputs. Strategic archetypes separate specialty hearth retailers controlling margin through consultative sales, vertically integrated manufacturers with in-house cast iron production, and automated feed system specialists capturing aging rural demographics. Competitive moves concentrate on showroom network expansion and catalytic after-treatment technology licensing to achieve EPA Phase IV compliance without sacrificing price accessibility.
Among North American fabricators, Hearth & Home Technologies, Blaze King, and Napoleon occupy distinct positioning vectors. Hearth & Home Technologies exemplifies the captive distribution archetype through controlled showroom networks. Blaze King represents extended burn-time engineering specialization. Napoleon anchors scale-driven manufacturing with foundry integration. Each occupies a defensible position against margin compression from emission compliance costs and input material volatility.
| Leading Market Players |
|---|
| Regency |
| Buck Stove |
| Hearth & Home Technologies |
| Englander |
| Osburn |
| Drolet |
| Blaze King |
| Ventis |
| Napoleon |
| Others |
Pricing and Supply Chain Analysis
The Trans-Alaska Pipeline System freight corridor anchors logistics cost dynamics for foundry-grade pig iron shipments from Pacific Northwest ports, concentrating supply-side leverage among three North American catalytic substrate suppliers while forcing downstream price stratification between EPA-certified premium units and basic steel-plate alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates catalytic-equipped cast iron models from basic steel units and non-certified legacy inventory. Certification grade under EPA Phase IV and foundry integration depth drive price differentiation, with captive foundry operators capturing margin advantage. Cost compression in the standard tier is intensifying because ceramic honeycomb substrate procurement bottlenecks force absorption of after-treatment component costs. Rural off-grid cabin owners in Montana and Idaho exhibit highest price sensitivity, while emergency-preparedness buyers in Texas and the Pacific Northwest absorb premium positioning for grid-independent reliability.
Supply Chain Analysis
Extended payment terms from foundry suppliers in the United States and Canada are stabilizing working capital for stove fabricators facing ceramic honeycomb substrate supply concentration. Raw material flows draw from domestic pig iron foundries, British Columbia sawmill residue for pellet feedstock, and Norwegian soapstone quarries for thermal mass composites. Single-source vulnerability in catalytic combustor substrates creates procurement risk. Distribution runs through captive specialty hearth retail networks and manufacturer-direct portals for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood stoves market sits in early-cycle expansion as grid reliability disruptions and off-grid residency growth extend addressable demand beyond traditional rural heating replacement cycles.
For Market Incumbents: Insulate margin structures through backward integration into foundry operations and captive catalytic substrate supply agreements. EPA Phase IV compliance cost absorption threatens price accessibility for core rural buyers; defend positioning through showroom network control and extended burn-time engineering licensing to sustain premium tier capture. For New Entrants and Emerging Players: Pursue Alaska Railbelt-adjacent villages and emergency-preparedness segments in Texas and the Pacific Northwest where first-time buyer formation outpaces established dealer relationships. The most penetrable white space sits in automated pellet feed systems for aging rural demographics. Go-to-market execution should leverage direct-to-consumer digital channels for accessory and maintenance part sales. For Investors and Strategic Acquirers: Specialty hearth retail networks with NFI-certified installation coordination capabilities offer acquisition exposure to margin capture bypassing big-box intermediaries. Long-term viability hinges on regulatory durability of biomass heating in air quality non-attainment zones. The inflection signal to watch is state-level wood-burning ban proliferation versus federal standard harmonization progress.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic After-Treatment Licensing | Technology transfer agreements enable EPA Phase IV compliance without proprietary R&D infrastructure. |
| Captive Foundry Integration | In-house pig iron casting insulates margin from metallurgical input volatility. |
| Specialty Showroom Network Expansion | Consultative sales formats in secondary metros bypass big-box intermediaries and capture premium placement. |
| Pellet Feed System Automation | Electronic ignition and programmable thermostats reduce operator skill barriers for aging rural demographics. |
| Direct-to-Consumer Portal Development | Manufacturer-direct channels displace rural dealers for replacement combustor and gasket sales. |
Research Methodology
Initial hypotheses were tested against primary input from hearth retail operators, EPA compliance engineers, foundry procurement managers, and off-grid cabin builders and refined through secondary validation against EPA certification databases, CSA B415 test records, EIA residential energy consumption surveys, and customs trade data for foundry-grade pig iron imports. Bottom-up unit shipment estimates triangulated with top-down heating appliance expenditure analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include combustion technology tier, installation context, fuel type compatibility, and distribution channel structure. CAGRs derived from regression analysis of historical replacement cycles and penetration elasticity to cordwood pricing spreads. Industry-specific forecast inputs incorporated burn-day ordinance proliferation rates and NFI technician certification pipeline constraints.
Sensitivities concentrate around state-level wood-burning ban implementation timelines and ceramic honeycomb substrate supply expansion. Forecasts reflect documented assumptions regarding EPA enforcement consistency and rural grid extension deferrals. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sandbags Market
Others
Italy Smart Home Market
Others
Education and Learning Analytics Market
Others
Durian Fruit Market
Others
Ambient Assisted Living and Smart Home Market
Others
Industrial Personal Computer Market
Others
Document Camera Market
Others
Global ESD Protection Devices Market
Others
North America Commercial Vehicles Lubricants Market
Others
North America Compressor Oil Market
Others
Residential Electrical Conduit Market
Others
Latin America Domestic CEP Market
Others
Calcined Petroleum Coke Market
Others
Transportation Lighting Market
Others
Global Smart Home Installation Service Market
Others
Small Office Home Office (SOHO) Servers Market