
 Global Learning Analytics Market | 2026-2036
Global Learning Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Learning Analytics Market Foresight
North America is reconfiguring its learning analytics infrastructure through substantial cloud capacity investments and university system digitization. IBM Corporation leverages its Watson analytics backbone to anchor enterprise education deployments across multiple continents. Microsoft Corporation competes through deep integration with its productivity ecosystem, while SAP SE specializes in linking workforce analytics directly to human capital management workflows. Oracle Corporation sustains its position through database-level performance optimization for large-scale institutional deployments.
Learning analytics encompasses the measurement, collection, analysis, and reporting of data about learners and their contexts for purposes of understanding and optimizing learning and the environments in which it occurs, typically processing structured and unstructured data streams through machine learning pipelines with latency requirements under 500 milliseconds for real-time intervention triggers. The discipline serves institutional and corporate stakeholders seeking to improve educational outcomes, reduce dropout incidence, and align training investments with measurable skill acquisition. Cloud-based deployment leads in revenue contribution due to scalability advantages for mid-tier institutions, while predictive analytics solutions represent the fastest-expanding solution offering category as organizations shift from retrospective reporting to forward-looking risk identification. Prescriptive analytics commands premium pricing where institutions require automated recommendation engines for curriculum adjustment.
The EU AI Act, GDPR, and FERPA in the United States collectively reshape product architecture requirements, mandating algorithmic transparency and learner data portability that increase engineering costs but create compliance-based switching costs for established vendors. ISO standards for learning technology interoperability further constrain market access for platforms lacking certified integration protocols. Stakeholders must monitor evolving cross-border data governance frameworks and assess whether their analytics stacks can adapt to jurisdiction-specific consent management without fragmenting operational dashboards.
Market Dynamics
Real-time inference architectures are compressing decision latencies below 500 milliseconds, forcing vendors to rebuild analytics stacks around edge computing nodes and federated learning protocols that preserve data locality while enabling instantaneous learner interventions.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating procurement of explainable machine learning pipelines across European higher education institutions.
- Corporate L&D budget expansion:Workforce competency measurement platforms are capturing larger shares of enterprise training expenditures as skill-based hiring practices diffuse through technology and financial services sectors.
- Cloud infrastructure maturation:Scalable container orchestration is lowering deployment barriers for mid-tier universities previously excluded from advanced analytics capabilities.
Market Restraints
- GDPR-FERPA jurisdictional friction:Cross-border learner data transfers face divergent consent architectures that fragment operational dashboards and inflate legal engineering overhead.
- Specialized data science talent scarcity:Shortages of professionals combining pedagogical domain expertise with production machine learning engineering are constraining implementation velocity.
- Legacy LMS integration complexity:Proprietary data formats in entrenched campus management systems resist standardized API extraction without costly middleware development.
Strategic Opportunities
- Prescriptive analytics white space:Automated curriculum recommendation engines command premium pricing where institutions seek to reduce manual advising bottlenecks.
- India's digitizing higher education sector:National Education Policy implementation is creating procurement windows for competency-tracking platforms across state university systems.
- Federated learning convergence:Privacy-preserving model training across institutional boundaries without raw data centralization addresses regulatory constraints while expanding addressable data volumes.
Industry Challenges
- ISO interoperability certification timelines:Lagging standardization for learning technology protocols creates vendor lock-in risks and complicates multi-platform institutional deployments.
- Algorithmic bias audit capabilities:Insufficient tooling for systematic fairness evaluation in predictive dropout models exposes institutions to reputational and legal liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Learning Analytics Market |
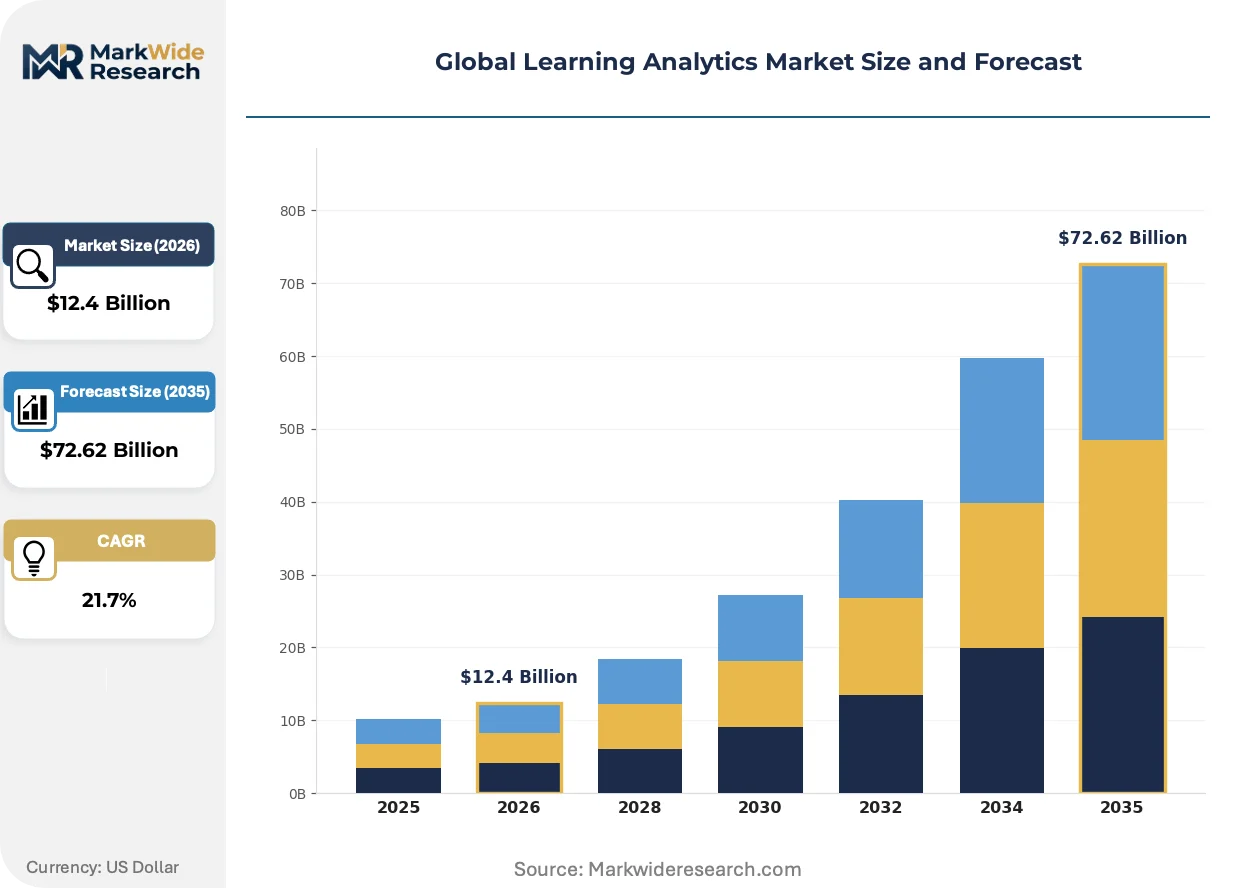
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $72.62 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge, SaaS Solution Offering: Predictive Analytics, Descriptive Analytics, Prescriptive Analytics, Diagnostic Analytics, Adaptive Learning Solutions Use Case: Student Performance Monitoring, Course Optimization, Skill Gap Analysis, Retention Improvement, Engagement Tracking End User Industry Vertical: Higher Education Institutions, Corporate Training Departments, K-12 Schools, Vocational Training Providers, Online Education Platforms |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Oracle Corporation, Blackboard Inc., D2L Corporation, Instructure Inc., SAS Institute Inc., Tableau Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Learning Analytics Market Shifts & Advancements
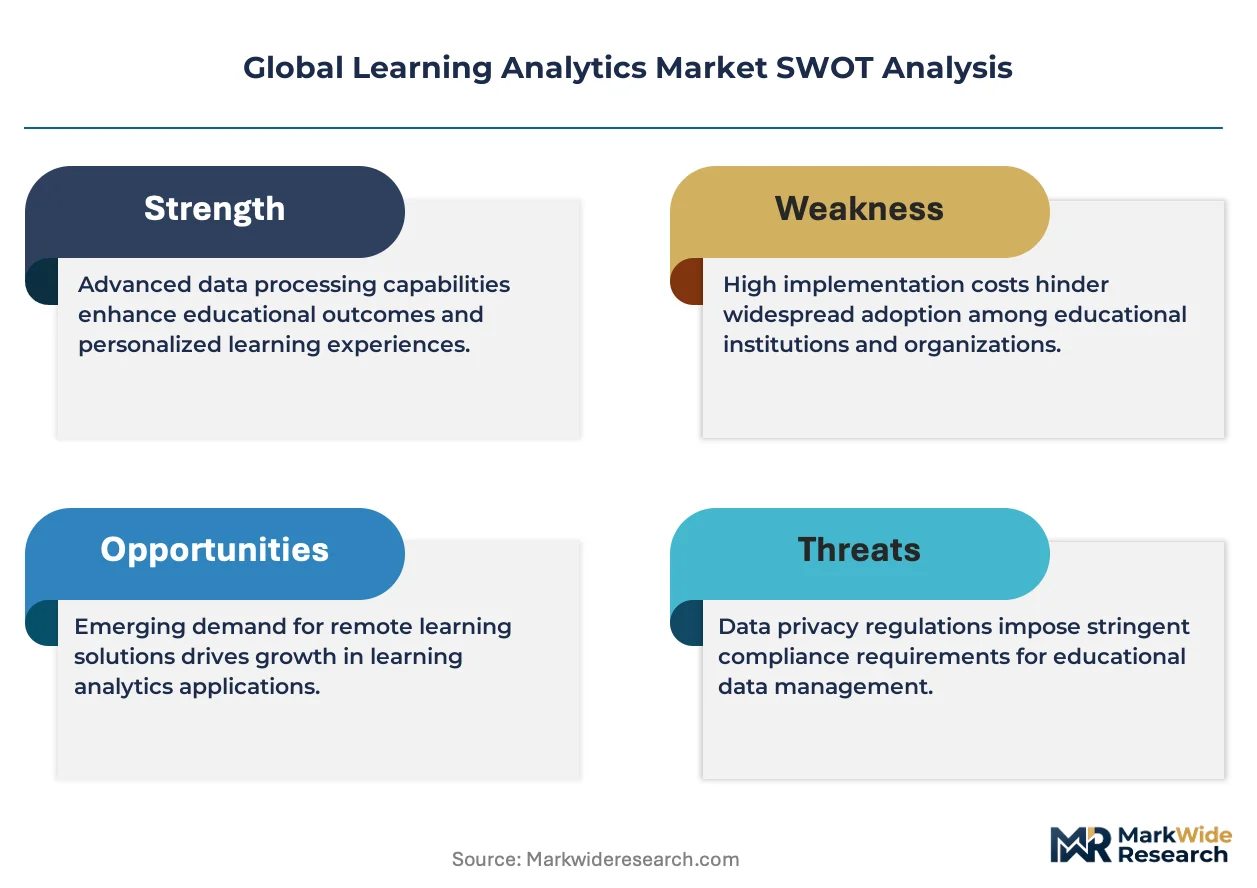
Analytics architectures are bifurcating between centralized cloud warehouses and distributed edge nodes, with architectural choices increasingly determined by jurisdictional data sovereignty requirements rather than purely technical performance metrics.
Natural language processing engines are hybridizing structured assessment data with unstructured learner communications to generate holistic engagement scoring. University systems in Australia and Canada are piloting these multimodal pipelines for early warning systems. The technology is hybridizing previously siloed quantitative and qualitative data streams into unified intervention triggers that compress response cycles from weeks to minutes.
The EU AI Act's risk classification framework is forcing vendors to reengineer high-stakes predictive models with mandatory human oversight interfaces. This regulatory architecture is elevating engineering costs for automated advising systems while creating compliance-based switching costs that favor established platforms with dedicated legal resources. European vocational training providers are most affected, with many delaying procurement until third-party conformity assessments clarify liability boundaries.
Enterprise buyers are unbundling analytics subscriptions from bundled LMS contracts, creating direct procurement relationships with specialized vendors. This disintermediation is compressing vendor sales cycles and shifting negotiation leverage toward institutional procurement offices with dedicated edtech evaluation functions. The pattern is most visible in United States community college systems, where separate RFP processes for learning analytics now precede core platform selections.
Global Learning Analytics Market Segmentation
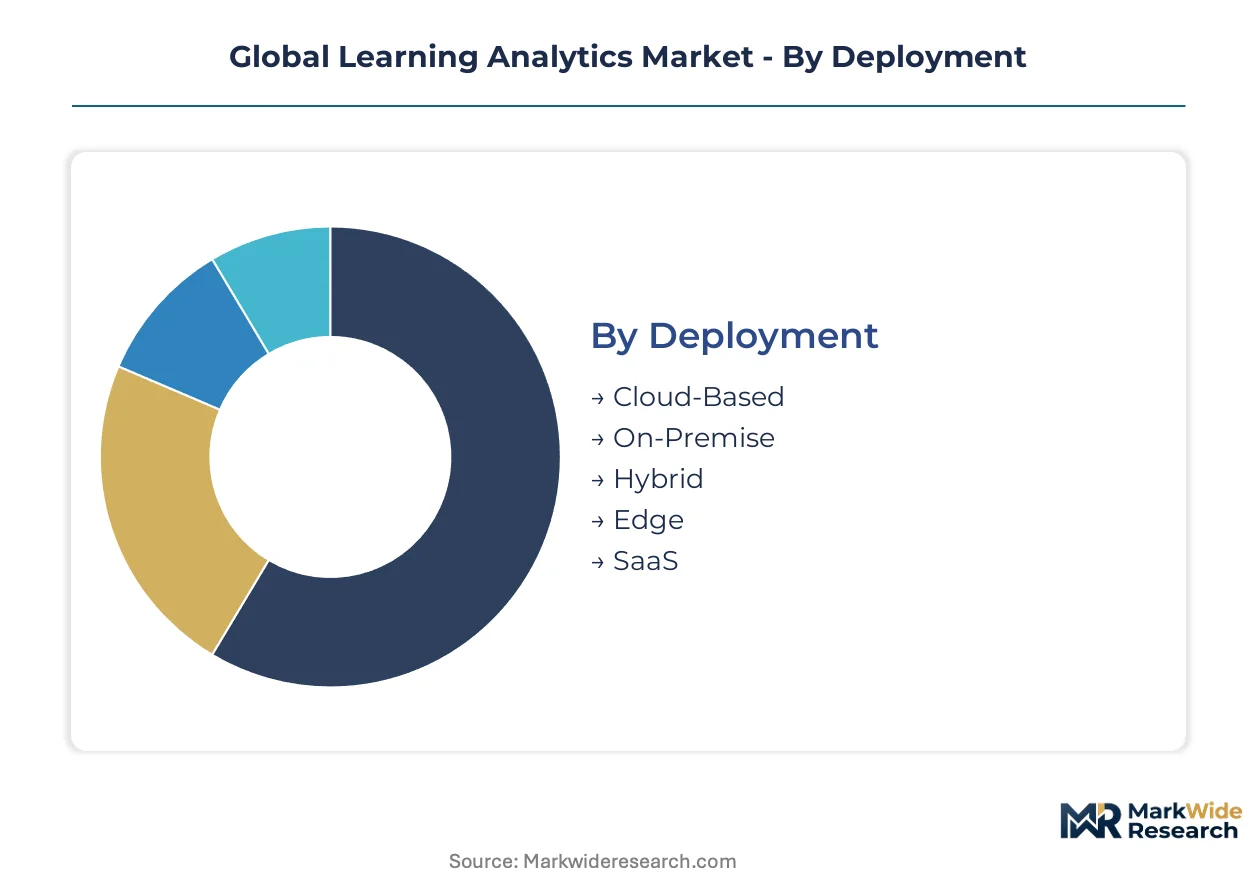
Learning analytics vendors configure product architectures around distinct deployment topologies, analytical sophistication levels, and institutional workflows. Segmentation reveals where engineering investments concentrate and which customer profiles command premium pricing tiers.
Deployment:
Cost tier determines accessibility for different institutional budget profiles, with cloud economics reshaping procurement patterns across education sectors.
- Cloud-Based:Multi-tenant architectures with elastic compute scaling serve mid-tier universities lacking capital expenditure capacity. United States community college systems drive procurement volume here, prioritizing operational expenditure models over infrastructure ownership.
- SaaS:Pre-configured analytics modules with standardized dashboards accelerate time-to-value for corporate L&D departments. Financial services firms in London and Singapore deploy these for rapid workforce competency mapping without internal data engineering teams.
- On-Premise:Dedicated hardware installations meeting stringent data sovereignty requirements.
- Hybrid:Split architectures processing sensitive identifiers locally while leveraging cloud analytics engines.
- Edge:Distributed nodes enabling sub-500 millisecond inference for real-time classroom interventions.
Cloud-Based deployments command the established base. The steepest expansion runs through Edge configurations addressing latency-sensitive use cases.
Solution Offering:
Application sophistication separates retrospective reporting from forward-looking intervention capabilities, with pricing stratifying across analytical maturity levels.
- Prescriptive Analytics:Automated recommendation engines dynamically adjusting curriculum pathways based on real-time learner telemetry. German vocational training providers under EU AI Act compliance mandates procure these systems to document human oversight interfaces for high-stakes advising decisions.
- Predictive Analytics:Machine learning pipelines identifying at-risk learners before dropout events crystallize. Australian universities pilot these for early warning systems integrating structured grades with unstructured communications sentiment.
- Descriptive Analytics:Historical dashboards summarizing completed learning activities and assessment outcomes.
- Diagnostic Analytics:Root-cause decomposition of learning outcome variance across demographic and instructional variables.
- Adaptive Learning Solutions:Closed-loop systems automatically personalizing content difficulty and presentation format.
Descriptive Analytics retains the largest installed footprint. Adaptive Learning Solutions are gaining share fastest as institutions automate personalization at scale.
Use Case:
Customer workflow integration determines where analytics platforms embed deeply versus remaining peripheral reporting tools.
- Retention Improvement:Predictive models flagging disengagement patterns trigger proactive advisor outreach. Canadian university systems deploy these pipelines to compress intervention response cycles from weeks to minutes.
- Skill Gap Analysis:Competency mapping against evolving occupational standards guides training investment prioritization. India's National Education Policy implementation creates procurement windows here across state university systems.
- Student Performance Monitoring:Continuous grade and assessment tracking with threshold-based alerting.
- Course Optimization:Learning design analytics identifying ineffective content sequences and assessment structures.
- Engagement Tracking:Behavioral telemetry measuring platform interaction depth and temporal patterns.
Student Performance Monitoring anchors current deployments. Skill Gap Analysis shows the most rapid uptake as workforce-aligned education expands.
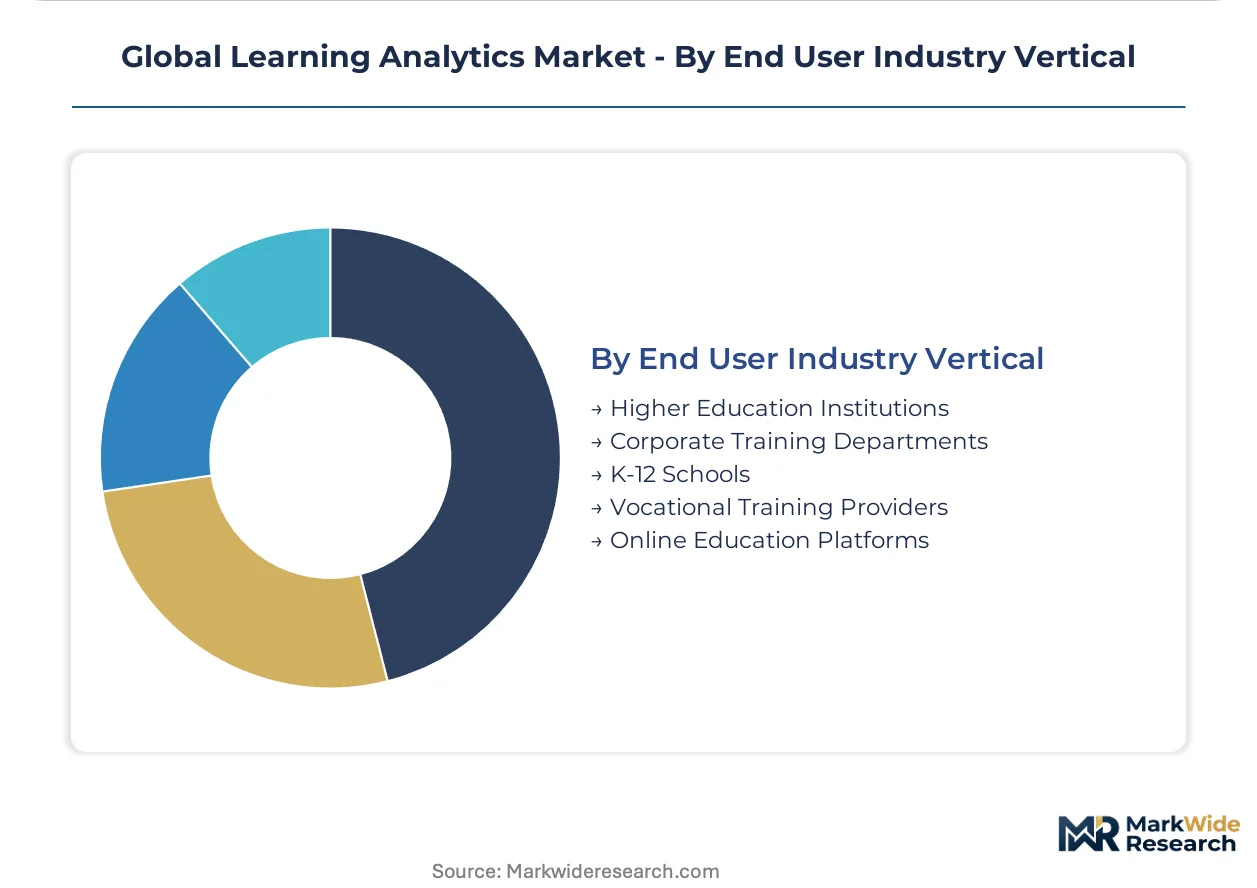
End User Industry Vertical:
Volume concentration and margin structure vary sharply across institutional types, with procurement authority and evaluation sophistication driving sales cycle length.
- Corporate Training Departments:Direct budget authority and outcome accountability accelerate purchasing decisions. Technology sector employers in California and Washington state unbundle analytics from bundled LMS contracts, creating standalone procurement relationships with specialized vendors.
- Higher Education Institutions:Complex shared governance and accreditation requirements extend evaluation timelines. Research-intensive universities in Massachusetts and Texas demand federated learning architectures preserving data locality across departmental boundaries.
- K-12 Schools:District-level purchasing with parental consent management complexity.
- Vocational Training Providers:EU AI Act risk classification delays procurement pending third-party conformity assessments.
- Online Education Platforms:Native digital infrastructure enables seamless analytics integration at massive scale.
Higher Education Institutions represent the deepest installed base. Corporate Training Departments are climbing the fastest as skill-based hiring practices diffuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERPA compliance requirements in the United States anchor the dominant geography, where federal education technology investments and enterprise L&D budgets are converging to reshape procurement patterns.
United States
Community college systems and research-intensive universities drive demand through separate RFP processes for learning analytics. FERPA mandates govern learner data portability and consent management. California and Washington technology sector employers unbundle analytics from bundled LMS contracts, creating standalone procurement relationships.
Germany
Vocational training providers under EU AI Act compliance mandates procure prescriptive analytics with documented human oversight interfaces. The EU AI Act's risk classification framework delays some procurement pending third-party conformity assessments. Bavaria and North Rhine-Westphalia anchor enterprise deployments linking workforce analytics to human capital management workflows.
United Kingdom
Financial services firms in London deploy SaaS analytics modules for rapid workforce competency mapping without internal data engineering teams. GDPR requirements shape algorithmic transparency and data localization decisions. The Southeast and Midlands concentrate procurement volume for cloud-based deployment models.
India
National Education Policy implementation creates procurement windows for competency-tracking platforms across state university systems. State-level digitization initiatives accelerate cloud infrastructure adoption. Maharashtra and Karnataka lead skill gap analysis deployments as workforce-aligned education expands.
Australia
University systems pilot multimodal pipelines integrating structured assessment data with unstructured learner communications for early warning systems. The country's national data protection framework influences architectural choices. New South Wales and Victoria concentrate real-time intervention system deployments compressing response cycles from weeks to minutes.
Global Learning Analytics Market Competitive Landscape
Cloud-native specialists and legacy enterprise software providers split the market into distinct competitive spheres with divergent engineering priorities. The vendor landscape exhibits tiered concentration, with established platforms commanding compliance-based switching costs while mid-tier challengers compete on deployment velocity. Two strategic archetypes dominate: productivity ecosystem integrators leveraging existing workplace software relationships, and database-centric architects optimizing for large-scale institutional performance. Competitive moves center on federated learning protocol development and edge computing node expansion to address sub-500 millisecond latency requirements.
Within the productivity ecosystem tier, Microsoft Corporation exemplifies deep integration strategies, while IBM Corporation and Oracle Corporation occupy positions anchored by enterprise infrastructure relationships. These three entities represent contrasting approaches to architectural choices increasingly determined by jurisdictional data sovereignty requirements rather than purely technical performance metrics.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Blackboard Inc. |
| D2L Corporation |
| Instructure Inc. |
| SAS Institute Inc. |
| Tableau Software |
| Others |
Supply & Pricing Matrix
Elastic cloud capacity underutilization across United States hyperscaler regions is compressing infrastructure-as-a-service rates, enabling SaaS vendors to absorb GDPR compliance engineering costs without passing full premiums to mid-tier university buyers while maintaining margin buffers.
Pricing Analysis
Geographic price spreads between German vocational training providers and United States community college systems exceed three-to-one for equivalent prescriptive analytics modules, reflecting EU AI Act conformity assessment burdens and localized human oversight interface requirements. Subscription tiers stratify across premium prescriptive engines, standard predictive dashboards, and economy descriptive reporting levels. Pricing pressure intensifies downward as cloud-native challengers disintermediate legacy LMS bundling arrangements. Corporate training departments in financial services show lowest price sensitivity, while India's state university systems negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Extended payment terms from ninety to one hundred twenty days now dominate procurement contracts, straining mid-tier analytics vendors without balance-sheet depth to finance working capital gaps. Engineering talent concentrates in the United States, Germany, and India, with machine learning pipeline development drawing from specialized labor pools in Bangalore, Munich, and Boston. Raw material dependencies center on GPU compute allocations, open-source framework maintenance, and ISO certification auditing capacity. Single-source vulnerability runs through NVIDIA's datacenter chip supply. Distribution runs through direct enterprise sales teams, systems integrators, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Production-grade machine learning engineers with pedagogical domain expertise represent the critical bottleneck constraining implementation velocity, creating asymmetric returns for organizations that solve this talent synthesis challenge.
For Market Incumbents: Insulate installed base relationships through ISO interoperability certification investments that raise switching costs for European higher education institutions facing EU AI Act compliance deadlines. Acquire specialized edge computing node providers to compress inference latencies below 500 milliseconds for real-time classroom intervention use cases. For New Entrants and Emerging Players: Establish a beachhead in India's National Education Policy implementation window, where state university systems seek competency-tracking platforms without legacy vendor entrenchment. Target prescriptive analytics white space in German vocational training, where third-party conformity assessment delays have frozen incumbent procurement cycles. Lead with federated learning architectures that address cross-border data governance fragmentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with embedded workflow integration rather than standalone analytics tools, indicating superior long-term viability across the five-to-ten year holding window. Monitor EU AI Act third-party conformity assessment completion rates as the inflection signal for European procurement reacceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Protocol Development | Enables privacy-preserving model training across institutional boundaries without raw data centralization. |
| Edge Computing Node Expansion | Addresses sub-500 millisecond latency requirements for real-time learner intervention triggers. |
| ISO Interoperability Certification | Creates compliance-based switching costs that lock in European higher education procurement relationships. |
| Human Oversight Interface Engineering | Satisfies EU AI Act risk classification mandates for high-stakes predictive advising systems. |
| Corporate L&D Direct Procurement Channel | Captures unbundled analytics demand from technology sector employers in California and Washington. |
Research Methodology
Operator-level perspectives from chief learning officers, IT procurement directors, platform engineering leads, and regulatory compliance officers anchored the qualitative base. Primary interview findings combined with secondary validation drawn from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and university system RFP documentation. Bottom-up deployment topology modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing around regulatory implementation timelines and cloud infrastructure cost curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, solution offering sophistication, use case workflow integration, and end-user industry vertical. CAGRs derived from elasticity-adjusted adoption curves and budget allocation shift patterns. Forecast inputs incorporated EU AI Act compliance cost pass-through assumptions and corporate L&D budget expansion trajectories.
Sensitivities concentrate around GDPR-FERPA jurisdictional friction resolution, EU AI Act third-party conformity assessment standardization, and specialized data science talent scarcity alleviation. Forecasts reflect documented assumptions about regulatory implementation velocity and cloud infrastructure cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hip Tendinitis Market
Others
Solid White Films Market
Others
Storm Surge Barriers Market
Others
Tobacco Packaging Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Managed Testing Services Market
Others
Smart Badge Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Tanned Fish Skin Leather Market
Others
Digital Tattoos Market
Others
Bamboo Straws Market
Others
Gym Wipes Market
Others
Wearable Brain Devices Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Reduced-Risk Products (Rrps) Market