
 North America Enterprise Video Market | 2026-2036
North America Enterprise Video Market Size, Share, and Industry Trends Forecast 2026-2036
North America Enterprise Video Market Intelligence
The proliferation of cloud-native platforms delivered through value-added resellers is rewriting traditional direct sales models. Microsoft Corporation leverages its extensive partner network to bundle video solutions within its broader software ecosystem. Cisco Systems Inc. sustains its market position through its established hardware and Webex software integration. Zoom Video Communications Inc. competes aggressively on user experience and a direct-to-consumer upgrade path, challenging legacy channel strategies.
Enterprise video encompasses the use of video technologies for business communication, training, and marketing. These platforms utilize codecs like H.264 and protocols such as WebRTC to ensure high-quality streaming across corporate networks. Cloud deployment models dominate new installations due to scalability, though hybrid solutions persist in regulated industries. Within solution types, video conferencing and remote collaboration tools represent the largest segments, while video content management shows significant growth.
Data privacy regulations, including Canada's PIPEDA and various US state-level laws, impose strict requirements on data handling for video platforms. In the healthcare sector, compliance with the Health Insurance Portability and Accountability Act (HIPAA) is a non-negotiable requirement for any solution handling patient information. Vendors must now decide whether to build compliance features as a core competency or rely on integrations to meet diverse jurisdictional rules.
Market Dynamics
The central dynamic in the North America enterprise video market is the tension between the need for scalable, user-friendly collaboration tools for hybrid workforces and the stringent security and compliance requirements imposed by regulated industries and data privacy laws.
Growth Catalysts
- Financial Services Adoption:The financial services sector in the United States and Canada increasingly utilizes enterprise video for secure client consultations, wealth management updates, and internal compliance training, driving demand for platforms with robust security features.
- Hybrid Work Models:The corporate shift to permanent hybrid and remote work structures necessitates investment in video conferencing and collaboration platforms to maintain productivity, employee engagement, and business continuity across distributed teams.
- Technology Hub Concentration:Demand is highly concentrated in major technology and financial centers across the US and Canada, where a high density of large enterprises and a culture of early technology adoption accelerate market penetration.
Market Restraints
- Network Infrastructure Limitations:Inconsistent last-mile internet bandwidth, particularly in rural and less-developed areas of North America, can degrade video quality and limit the effectiveness of high-definition video conferencing, creating a barrier to adoption.
- Data Sovereignty and Compliance Costs:Adhering to regulations like Canada's PIPEDA and the US's HIPAA requires significant investment in compliant infrastructure and processes, increasing costs and complexity for vendors and end-users.
- Threat from Consumer-Grade Tools:The prevalence of free or low-cost consumer video applications creates a "good enough" alternative that can lead to shadow IT adoption within departments, fragmenting enterprise control and posing security risks.
Strategic Opportunities
- Expansion into New Verticals:There is significant opportunity in adapting enterprise video solutions for specific workflows in underpenetrated sectors like the legal field for remote depositions or manufacturing for remote diagnostics and expert assistance.
- AI and Analytics Integration:Integrating artificial intelligence to provide automated meeting summaries, transcriptions, and sentiment analysis offers a path to create higher-value services beyond basic communication, creating new revenue streams.
- SMB-Focused Channel Programs:Developing simplified, low-touch sales and distribution channels can unlock the large and underserved small and medium-sized business (SMB) market, which has been historically priced out of enterprise-grade solutions.
Industry Challenges
- Legacy System Integration:Enterprises face significant operational hurdles when trying to integrate modern cloud-based video platforms with existing on-premise IT infrastructure, such as legacy video conferencing hardware and unified communications systems.
- Managing Data Proliferation:The explosion of video content, including recordings and transcripts, creates substantial challenges for data governance, storage management, and security, increasing the risk of data breaches or compliance violations.
- Specialized Skills Gap:A shortage of IT professionals with combined expertise in network engineering, cloud platform administration, and cybersecurity complicates the deployment and management of sophisticated enterprise video ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Enterprise Video Market |
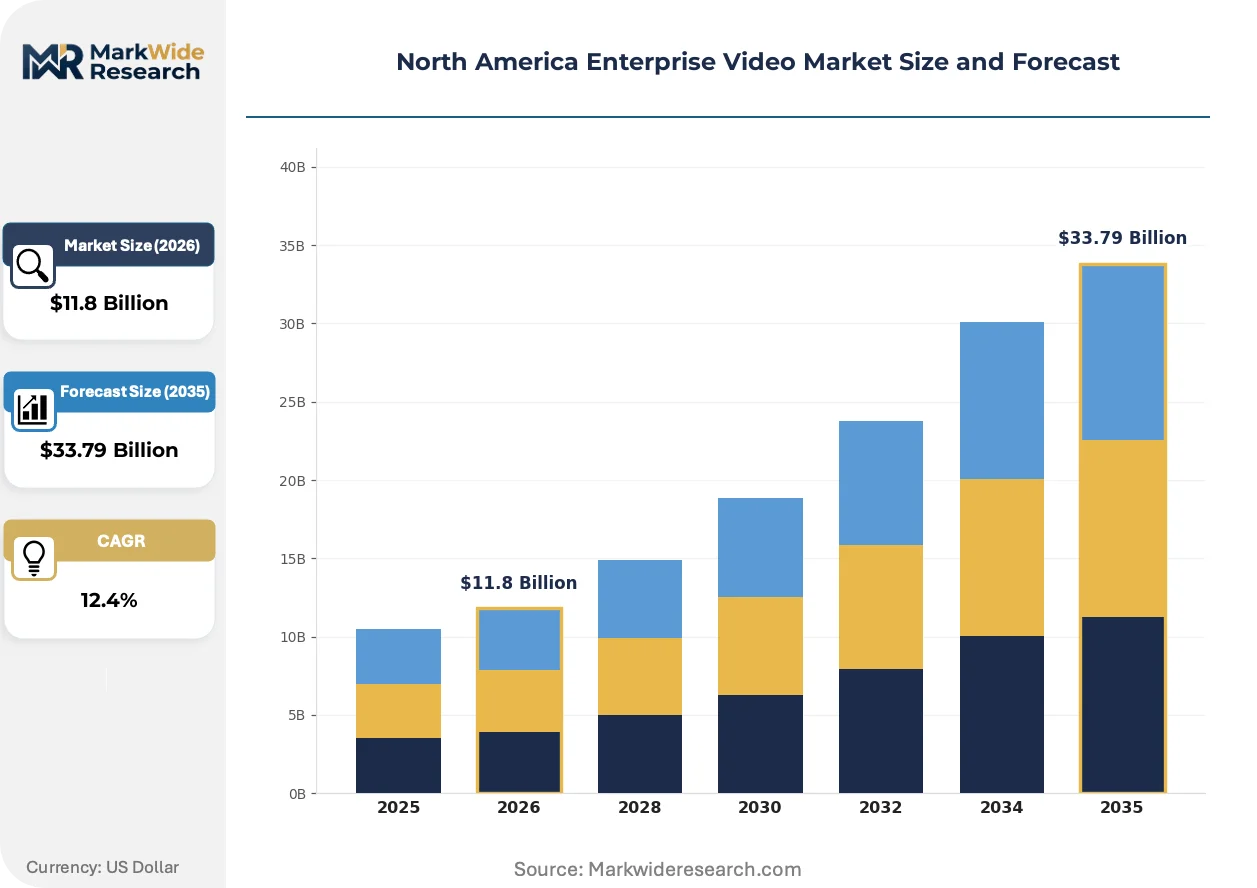
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $33.79 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge Computing Solution Type: Video Conferencing, Video Streaming, Webinars, Video Surveillance, Video Content Management Application: Corporate Training, Sales Enablement, Internal Communications, Remote Collaboration, Event Broadcasting End User Industry: Information Technology, Financial Services, Government Agencies, Educational Institutions, Media & Entertainment |
| Companies Covered | Microsoft Corporation, Cisco Systems Inc, Zoom Video Communications Inc, Adobe Inc, IBM Corporation, Avaya, Brightcove Inc, Kaltura Inc, Vidyo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Enterprise Video Market Strategic Shifts & Innovations
The market is shifting from providing simple connectivity to delivering intelligent, integrated workflows. This evolution prioritizes extracting business value from video interactions, embedding them directly into core processes rather than treating them as standalone communication events.
Artificial intelligence-powered analytics is a key innovation transforming video content. These tools automatically transcribe speech, generate summaries, and identify action items from meetings. Large enterprises, particularly in the technology and consulting sectors, are rapidly adopting this capability to enhance productivity and create a searchable knowledge base from video archives. The market is migrating from basic video streaming towards intelligent content platforms that automate post-meeting tasks and knowledge management.
The Health Insurance Portability and Accountability Act (HIPAA) in the United States imposes strict data handling requirements. This regulation forces vendors serving the healthcare industry to implement end-to-end encryption, secure access controls, and sign Business Associate Agreements. Consequently, the healthcare sector is most affected, with providers exclusively selecting HIPAA-compliant platforms for telehealth and patient communication, thus creating a distinct, compliance-gated sub-market.
A prominent behavioral shift involves departmental teams adopting video tools directly, often through freemium models that bypass central IT. This bottom-up adoption pattern, which prioritizes user experience, directly challenges the traditional sales model reliant on value-added resellers and lengthy procurement cycles. This trend is most visible within fast-moving technology companies in the United States, where agility is valued over centralized IT control.
North America Enterprise Video Market Segmentation
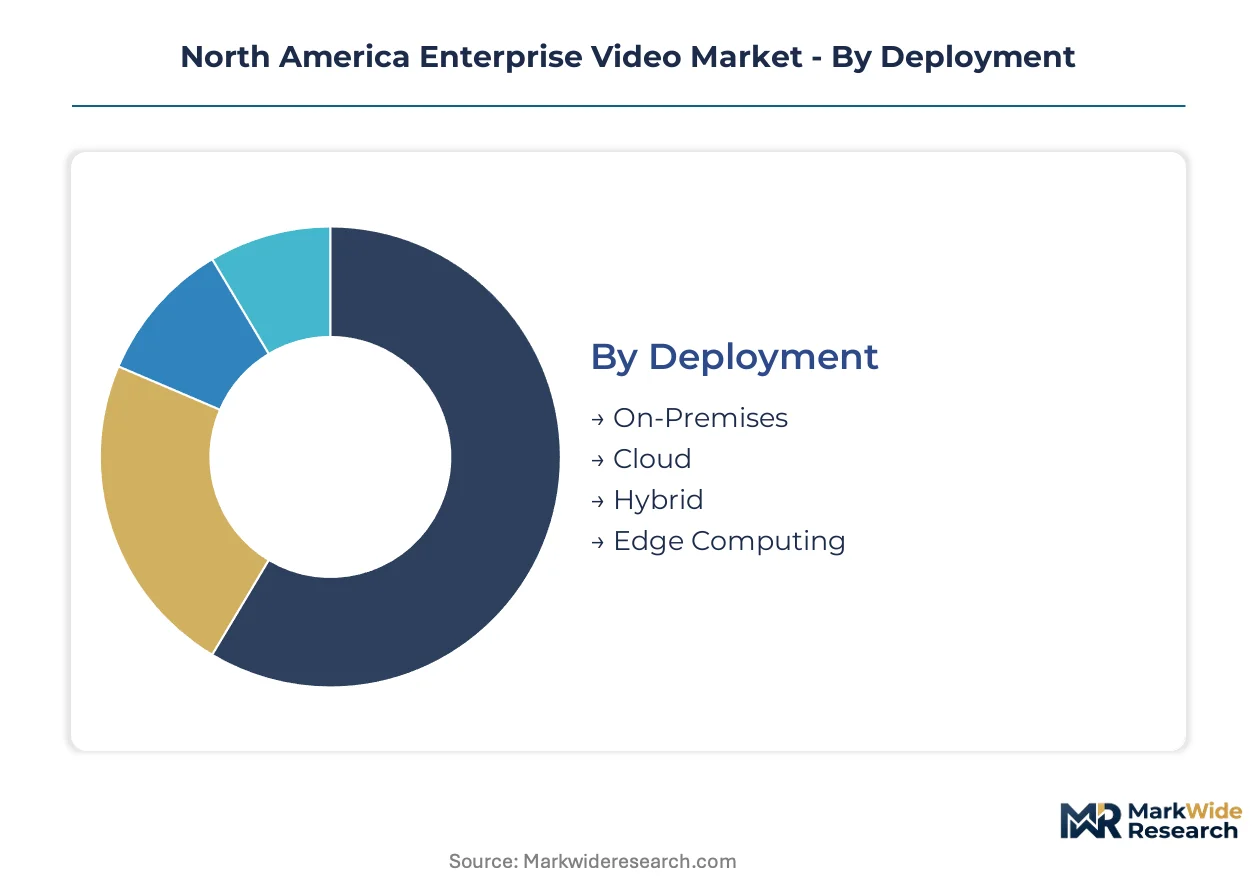
The North America enterprise video market categorizes solutions based on deployment models, functional types, core applications, and target industries. Understanding these distinct segments reveals where investment capitalizes on current demand and where future growth will emerge. Each segment responds differently to technological shifts and regulatory pressures across the United States and Canada.
Deployment:
Deployment models exhibit varying refresh cycles, with cloud-native installations seeing rapid adoption while on-premises solutions maintain longer operational lifespans. Hybrid approaches blend these cycle times, offering flexibility for North American enterprises.
- Cloud:These platforms deliver video services over the internet, managed by third-party providers, offering immense scalability and reduced infrastructure overhead. Demand concentrates within technology hubs in the United States, driven by the need for agile, globally accessible collaboration tools.
- Hybrid:This model combines on-premises infrastructure with cloud services, allowing organizations to retain control over sensitive data while leveraging cloud flexibility. Financial services firms in Canada utilize hybrid deployments to meet data residency requirements while enabling remote work.
- On-Premises:Enterprise video systems hosted entirely within a company's own data centers provide maximum control over data security and customization. Regulated industries in the US, such as government agencies, often prefer on-premises solutions for strict compliance.
- Edge Computing:Processing video data closer to the source, such as on local servers or devices, reduces latency and bandwidth consumption. This model supports real-time applications like remote diagnostics in manufacturing facilities across North America.
Cloud deployment anchors the volume base while Edge Computing gains share at the steepest rate.
Solution Type:
The diverse solution types address distinct communication needs, ranging from ubiquitous real-time interactions to specialized content management requirements. Each solution type supports specific business processes across North American organizations.
- Video Conferencing:These tools facilitate live, interactive meetings between multiple participants, often featuring screen sharing and chat functionalities. Widespread adoption in US corporate environments for daily team meetings and client interactions drives significant market volume.
- Video Content Management:Platforms for storing, organizing, and distributing recorded video assets, including training materials and meeting archives. Large enterprises in Canada leverage VCM to create searchable knowledge bases and ensure compliance with retention policies.
- Video Streaming:One-to-many live or on-demand broadcasts deliver corporate announcements, town halls, and marketing content to broad audiences. Media and entertainment companies in North America frequently use video streaming for internal and external communications.
- Webinars:Structured online seminars or presentations allow hosts to interact with a large audience, often used for training, product launches, or lead generation. Educational institutions and marketing departments across the US rely heavily on webinars.
- Video Surveillance:Security systems utilizing video cameras to monitor premises, assets, or operations, providing real-time oversight and recorded evidence. Government agencies and critical infrastructure operators in North America deploy video surveillance for security protocols.
Video Conferencing remains strategically central for daily operations, while Video Content Management is increasingly vital for knowledge retention and governance.
Application:
Enterprise video applications range from foundational internal communication tools to advanced external engagement strategies. The maturity of these applications varies, reflecting their integration depth into organizational workflows across the US and Canada.
- Remote Collaboration:Tools enabling geographically dispersed teams to work together effectively through shared virtual spaces, document co-editing, and real-time communication. Technology firms in the United States prioritize remote collaboration solutions to support distributed agile teams.
- Corporate Training:Video platforms deliver instructional content for employee onboarding, skill development, and compliance education, often asynchronous and on-demand. Financial services in Canada use video for mandatory annual compliance training and professional development.
- Internal Communications:Broadcasting company-wide updates, executive messages, and departmental news through live streams or recorded video fosters employee engagement. Large corporations across North America utilize internal video for transparent and consistent messaging.
- Sales Enablement:Utilizing video for sales pitches, product demonstrations, and personalized client communications to accelerate the sales cycle and improve conversion rates. Business development teams in the US leverage video to enhance customer interactions.
- Event Broadcasting:Live streaming or recording large-scale corporate events, conferences, and product launches to reach a wider audience beyond physical attendees. Marketing departments in North America increasingly use video for virtual and hybrid events.
Remote Collaboration applications are fundamental for hybrid work, with Corporate Training increasingly integrated into continuous learning workflows.
End User Industry:
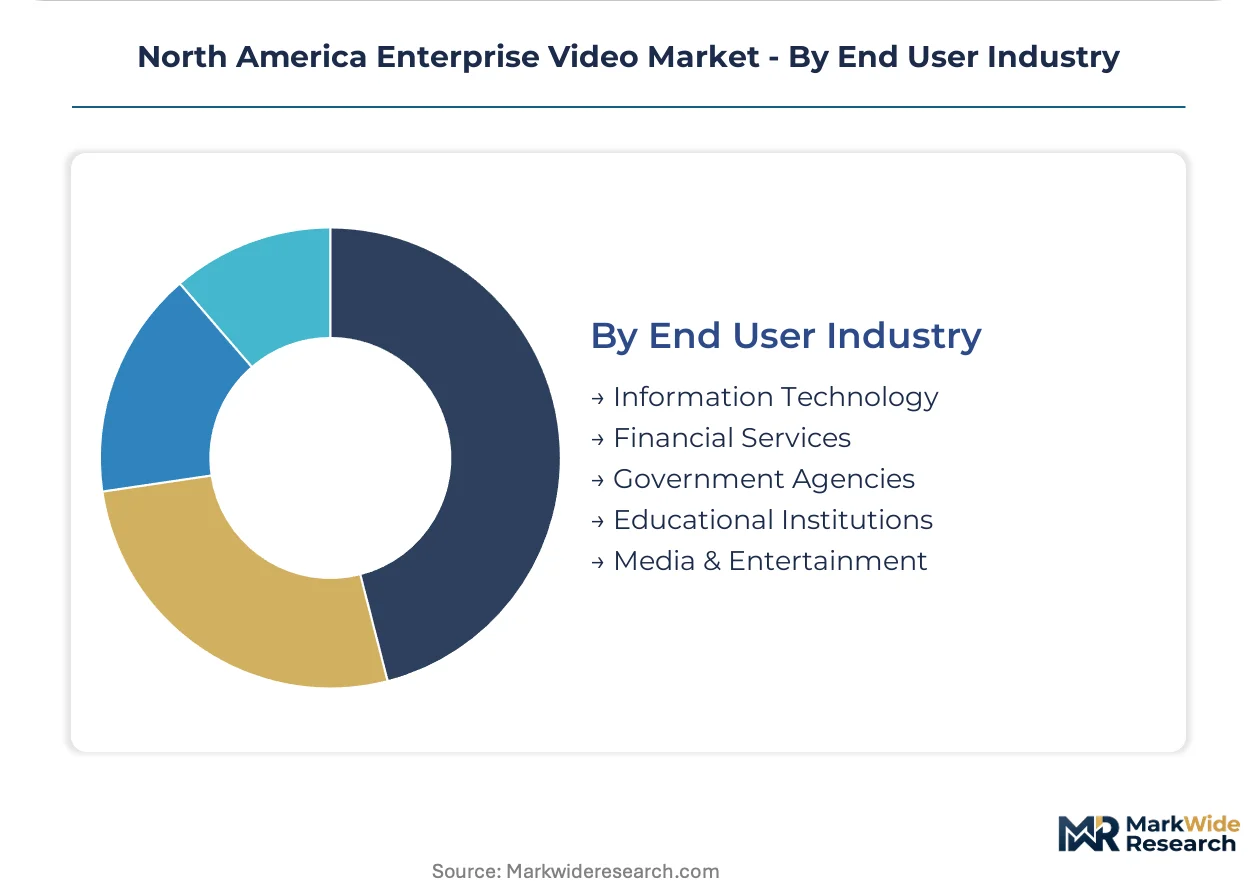
End-user industries adopt enterprise video based on their specific operational needs, regulatory environments, and customer engagement models. The impact of data privacy regulations significantly influences platform selection within these sectors across North America.
- Financial Services:Banks, investment firms, and insurance companies use video for secure client consultations, wealth management, and internal compliance training. Strict adherence to regulations like HIPAA (for health-related financial data) and state-level privacy laws in the US is paramount.
- Information Technology:Technology companies widely adopt enterprise video for internal team collaboration, software development, and client support, often leading innovation in platform features. These firms in North America drive demand for advanced AI-powered analytics and integration capabilities.
- Educational Institutions:Universities, colleges, and K-12 schools use video for remote learning, lecture capture, and administrative meetings. The shift to hybrid learning models across the US and Canada has accelerated demand for robust, accessible platforms.
- Government Agencies:Public sector entities utilize video for secure internal communications, public outreach, and emergency response coordination. Compliance with federal and state security mandates is a critical requirement for US government deployments.
- Media & Entertainment:Production houses, broadcasters, and content creators use video for remote production workflows, content review, and distribution. These companies in North America require high-bandwidth, low-latency video solutions.
Financial Services demand robust compliance features, while Information Technology drives innovation in video platform capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the North America enterprise video market shows asymmetry, with the United States often setting benchmarks for premium, compliant solutions. Canada follows closely, balancing regulatory demands with market adoption trends. Demand patterns across the region reflect diverse economic structures and regulatory environments.
United States
The United States experiences strong demand for enterprise video platforms, driven by widespread hybrid work models and financial services' need for secure client interactions. Compliance with HIPAA and various state-level data privacy laws mandates robust security features for platforms operating here. Technology hubs in California, such as Silicon Valley, actively integrate advanced AI-powered video analytics into corporate workflows.
Canada
Canada's market for enterprise video solutions is propelled by the necessity for remote collaboration across its vast geography and strong corporate training requirements. Adherence to Canada's PIPEDA regulations and provincial data residency rules is a critical factor for solution providers. Financial centers in Toronto increasingly adopt hybrid cloud video solutions to balance data sovereignty with operational flexibility.
California
California, a major technology hub, drives demand for cutting-edge enterprise video solutions due to its innovative tech companies and extensive content creation industries. The California Consumer Privacy Act (CCPA) imposes stringent data handling requirements, pushing vendors towards enhanced privacy features. Media companies in Los Angeles utilize advanced video streaming platforms for remote production and global content distribution.
New York Metro
New York Metro exhibits significant demand from its dominant financial services, media, and legal sectors, requiring highly secure and reliable video communication. The New York SHIELD Act and specific financial regulations enforce strict data security protocols for enterprise video deployments. Wall Street firms in Manhattan increasingly leverage video for secure client consultations and internal compliance training.
North America Enterprise Video Market Key Industry Players
Integrated Platform Providers and Specialized Collaboration Innovators split the North America enterprise video market, each pursuing distinct growth strategies. The competitive landscape is characterized by a tiered structure, ranging from broad ecosystem players to agile, user-centric solution providers. Consolidation occurs through strategic partnerships that expand market reach and technology licensing agreements enhance core offerings. Companies actively engage in portfolio diversification to address varied enterprise communication needs.
Within the Integrated Platform Provider tier, Microsoft Corporation, a Redmond-based software giant, anchors a broad ecosystem approach, bundling video solutions within its extensive software suite. Cisco Systems Inc., a San Jose-headquartered networking hardware and software company, maintains its market position through established hardware and Webex software integration. Zoom Video Communications Inc., a San Jose-based communication technology firm, represents the Specialized Collaboration Innovator archetype, competing aggressively on user experience and a direct-to-consumer upgrade path.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems Inc |
| Zoom Video Communications Inc |
| Adobe Inc |
| IBM Corporation |
| Avaya |
| Brightcove Inc |
| Kaltura Inc |
| Vidyo |
| Others |
Cost & Logistics Intelligence
Silicon Valley's concentration of software development talent and infrastructure influences the pricing power for advanced enterprise video platforms. This concentration allows vendors to command premiums for innovative, feature-rich solutions.
Pricing Analysis
Configured-to-order enterprise video solutions command a premium over standard, off-the-shelf offerings. The dominant pricing structure is subscription-based, often SaaS-tiered, reflecting feature sets and user counts. Customization level for specific workflows and robust after-sales support drive price differentiation. Pricing softness stems from the proliferation of free consumer-grade tools, impacting SMBs who are most price-sensitive. Large enterprises and regulated industries, however, prioritize compliance and security, exhibiting lower price sensitivity.
Supply Chain Analysis
Upstream feedstock for enterprise video platforms primarily involves semiconductor components, optical sensors, and specialized codecs. Supply concentration for these critical hardware elements largely resides in East Asia, with software development concentrated in the United States and Canada. A structural risk is single-source vulnerability for specific chipsets or advanced codec licenses. Downstream distribution primarily leverages value-added resellers for enterprise clients, complemented by direct-to-consumer upgrade paths for many software-centric solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America enterprise video market offers a defensive moat, primarily through regulatory entrenchment for compliant solutions. Strict data privacy laws and industry-specific mandates create high barriers to entry for new players.
For Market Incumbents: Entrench market position by deepening integration with existing enterprise IT ecosystems. Incumbents should acquire specialized AI analytics firms, countering the threat from consumer-grade tools. Investing in advanced security certifications and expanding channel control reinforces market leadership. This leverages established client relationships.
For New Entrants and Emerging Players: Pursue niche vertical markets currently underserved by broad platform providers, such as remote diagnostics or legal e-discovery. The SMB market remains highly penetrable due to its price sensitivity. A freemium-to-premium upgrade path, focusing on superior user experience, offers an effective go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized collaboration innovators with strong AI capabilities and vertical expertise. Long-term viability is strong, driven by permanent hybrid work models. Acquisition targets include agile firms offering compliance-as-a-service or advanced video content management. Watch for increasing corporate budget allocation for intelligent workflow automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI Analytics Firm | Enhances platform capabilities with automated summaries and sentiment analysis for corporate users. |
| Invest in HIPAA Compliance | Secures access to the healthcare sector's compliance-gated sub-market for patient communication. |
| Expand Value-Added Reseller Network | Broadens market reach and provides localized support for enterprise clients in North America. |
| Develop SMB-Focused Freemium Model | Captures large, underserved small and medium-sized business market with simplified offerings. |
| Integrate Edge Computing Capabilities | Reduces latency and improves real-time performance for remote diagnostics in manufacturing. |
Research Approach
Operator-level perspectives from CTOs, IT procurement officers, channel partners, and compliance officers anchored the qualitative base for this study. Primary interviews were triangulated with extensive secondary research, including SEC filings of public companies, industry association reports, and government privacy law databases like PIPEDA. This dual approach ensured both bottom-up market insights and top-down validation of market trends.
Scenario-bracketing informed the quantitative model, projecting market evolution across the analysis window. The framework modeled segmentation dimensions including deployment model, solution type, end-user industry, organization size, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical data and projected forward based on identified growth catalysts. Hybrid work adoption rates and regulatory compliance costs served as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized collaboration innovators or new entrants would shift outcomes. Rapid technological disruption or unforeseen regulatory changes represent risk factors. Cross-checking against major industry analyst reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Legal Services Market
Others
United States Indoor LBS Market
Others
Europe Street Lighting Market
Others
North America IT Device Market
Others
Global Sportswear Market
Others
Video Conferencing Hardware Market
Others
Depth Gauge Market
Others
Paper Shredder Market
Others
Balsa Wood Market
Others
Fluid Bed Systems Market
Others
Global Tobacco Market
Others
Global Car Wax Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
North America Compressor Oil Market
Others
Profiling Floats Market
Others
Managed Testing Services Market