
 Digital Transformation in Healthcare Market | 2026-2036
Digital Transformation in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation in Healthcare Market Intelligence
The proliferation of Software as a Service (SaaS) subscription models is rewriting the competitive landscape for healthcare IT providers. This asset-light approach allows smaller clinics and hospitals to access advanced technologies without massive upfront capital investment. Epic Systems Corporation leverages its deep integration within large hospital networks to maintain its market position. Meanwhile, Oracle Health, following its acquisition of Cerner, competes on the strength of its comprehensive enterprise-level data management capabilities.
Digital transformation in healthcare involves integrating technologies to digitize processes, enhance patient care, and improve operational efficiency. A core technical aspect is achieving data interoperability through standardized protocols like HL7 and FHIR to enable seamless information exchange. Cloud Computing and Artificial Intelligence represent the fastest-growing technology segments, enabling scalable data storage and predictive analytics. Within applications, Electronic Health Records (EHR) form the foundational layer, while Telemedicine platforms are seeing rapid adoption for remote patient consultations.
Regulatory frameworks establish the guardrails for digital health adoption, with data privacy being a primary concern. The Health Insurance Portability and Accountability Act (HIPAA) in the United States and the General Data Protection Regulation (GDPR) in Europe impose strict rules on patient data handling. Navigating these complex and sometimes conflicting international standards is a critical challenge for technology vendors. The ability to demonstrate robust cybersecurity and clear data governance will determine market access and provider trust.
Market Dynamics
The central force defining the healthcare digital transformation market is the industry-wide mandate for data interoperability. This imperative creates a structural tension between the proprietary, closed ecosystems of established electronic health record vendors and the pressing need for seamless data exchange among providers, payers, and patients using standards like FHIR.
Growth Catalysts
- Regulatory Mandates:Legislation like the 21st Century Cures Act in the United States actively compels healthcare providers and IT developers to adopt open data sharing APIs, directly stimulating investment in interoperable platforms.
- Cloud Computing Adoption:The shift to cloud infrastructure enables smaller healthcare facilities to access powerful data analytics and EHR systems on a subscription basis, lowering the barrier to entry and expanding the addressable market. *Patient-Centric Care Models: A growing emphasis on patient engagement and remote monitoring fuels demand for digital tools, including telemedicine platforms and mobile health applications that connect patients with their care teams.
Market Restraints
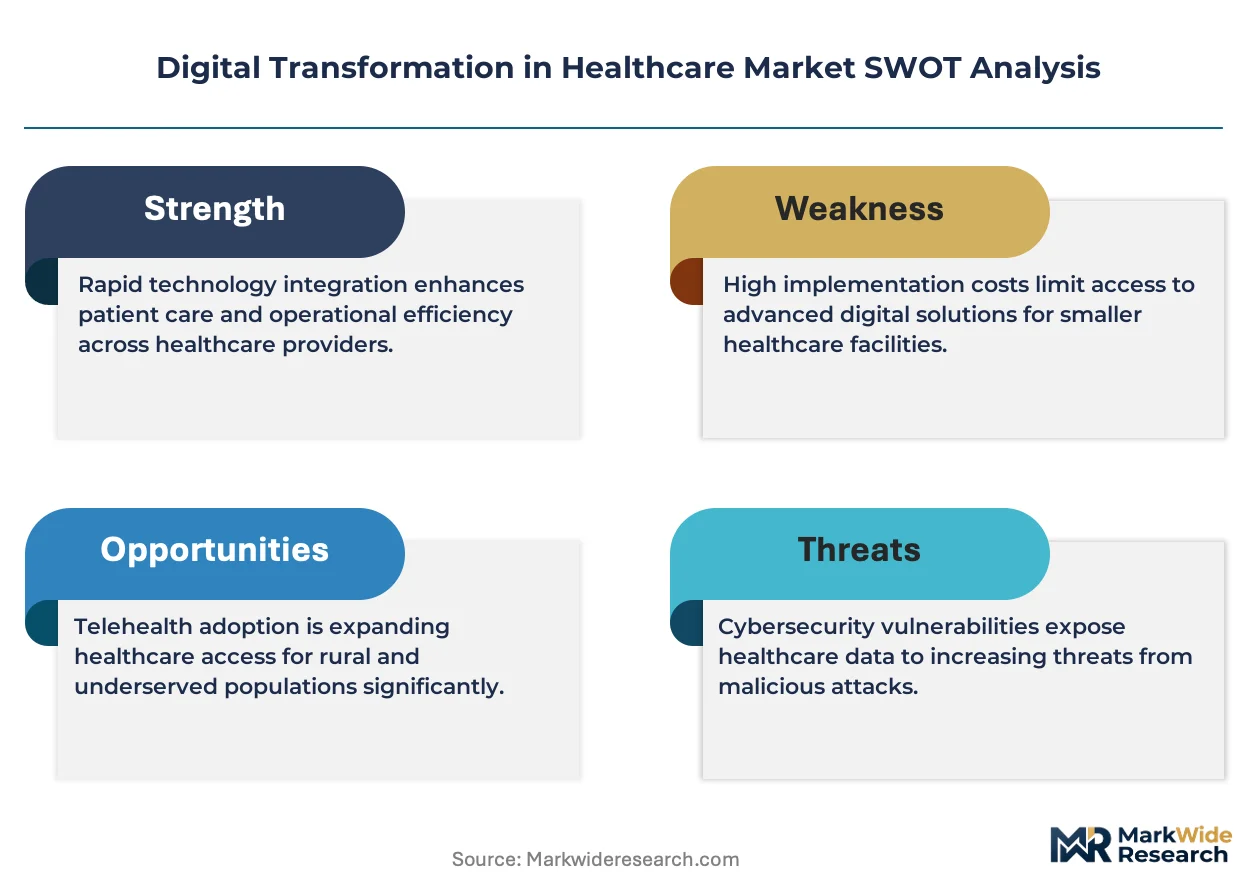
- High Implementation Costs:The substantial upfront capital expenditure and resource allocation required to deploy or upgrade comprehensive EHR systems remain a significant barrier for many small to mid-sized hospitals and clinics.
- Cybersecurity Vulnerabilities:The increasing frequency and sophistication of cyberattacks targeting healthcare organizations create a climate of caution, slowing the adoption of new connected technologies due to fears of data breaches and operational disruption.
- Data Interoperability Challenges:Despite regulatory pushes, the persistent lack of universal data standardization across disparate legacy systems creates significant technical and financial hurdles to achieving seamless information flow.
Strategic Opportunities
- Predictive Analytics with AI:Leveraging artificial intelligence and machine learning on aggregated health data presents a major opportunity to develop predictive models for disease progression, patient risk stratification, and operational resource planning.
- Expansion of Telehealth Services:There is significant white space in expanding telehealth beyond general consultations into specialized areas such as tele-psychiatry, remote chronic disease management, and virtual post-operative follow-ups.
- Underpenetrated Emerging Markets:While China is advancing rapidly, many regions in Southeast Asia, Latin America, and Africa have nascent digital health ecosystems, offering greenfield opportunities for vendors with scalable, cost-effective solutions.
Industry Challenges
- Specialized Talent Scarcity:A pronounced shortage of professionals with dual expertise in both clinical workflows and advanced data science, cybersecurity, or cloud architecture hampers implementation and innovation efforts within healthcare organizations.
- Legacy System Integration:The operational difficulty of integrating modern digital solutions with entrenched, often outdated, legacy IT infrastructure is a primary and costly challenge for established hospitals and health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation in Healthcare Market |
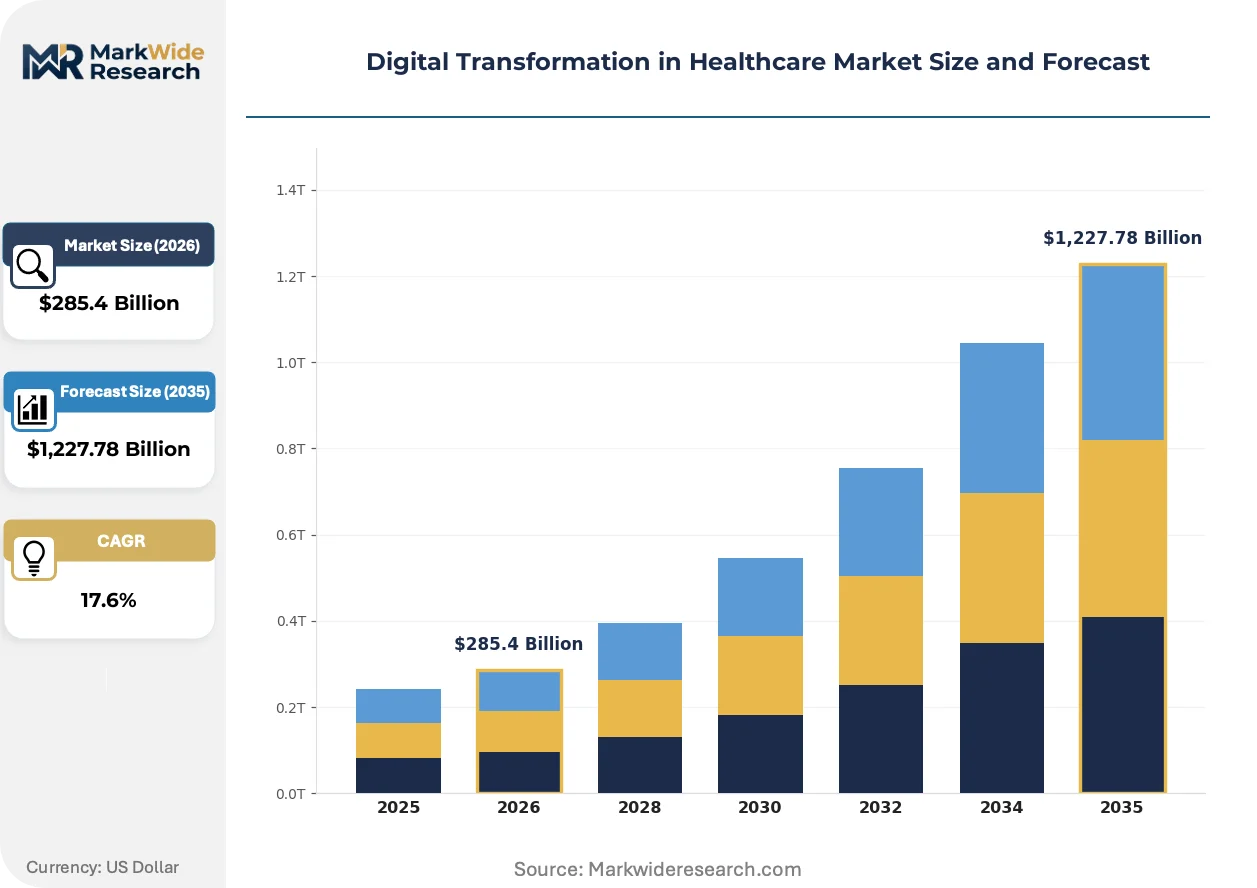
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $1,227.78 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Big Data Analytics, Cloud Computing, Telemedicine, Blockchain Application: Patient Engagement, Clinical Decision Support, Remote Monitoring, Electronic Health Records, Revenue Cycle Management End User: Hospitals, Ambulatory Centers, Diagnostic Laboratories, Pharmacies, Rehabilitation Centers Implementation Model: On-Premises, Cloud-Based, Hybrid, Managed Services, Software as a Service |
| Companies Covered | Epic Systems Corporation, Oracle Health, GE HealthCare Technologies Inc, Siemens Healthineers AG, Koninklijke Philips NV, Medtronic Plc, Cerner Corporation, IBM Watson Health, Teladoc Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation in Healthcare Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from basic record digitization to the deployment of intelligent, predictive, and interconnected health systems. This shift is powered by advancements in AI, new regulatory paradigms for data and algorithms, and changing patient expectations for care delivery.
Artificial intelligence in medical imaging serves to augment clinical decision-making. These platforms are being adopted by large hospital networks and specialized diagnostic centers to improve the speed and accuracy of interpretations. This technology is digitizing the radiologist's workflow, transforming it from a manual review process into an AI-assisted analysis that can prioritize critical cases and identify subtle anomalies.
The European Union's AI Act establishes a risk-based regulatory framework for artificial intelligence systems that has global implications. It places strict obligations on high-risk applications, including many clinical decision support and diagnostic tools used in healthcare. Consequently, software vendors in this segment must now invest significantly in transparent documentation, robust risk management, and conformity assessments to retain market access in Europe.
A notable behavioral change is the increasing patient expectation for on-demand access to their own health data and care services. This trend disrupts the traditional, episodic model of patient interaction, favoring continuous engagement through patient portals, mobile health apps, and wearable device integration. This consumer-driven shift is most apparent in North America and Western Europe, compelling providers to invest in technologies that support greater transparency and patient autonomy.
Digital Transformation in Healthcare Market Segmentation
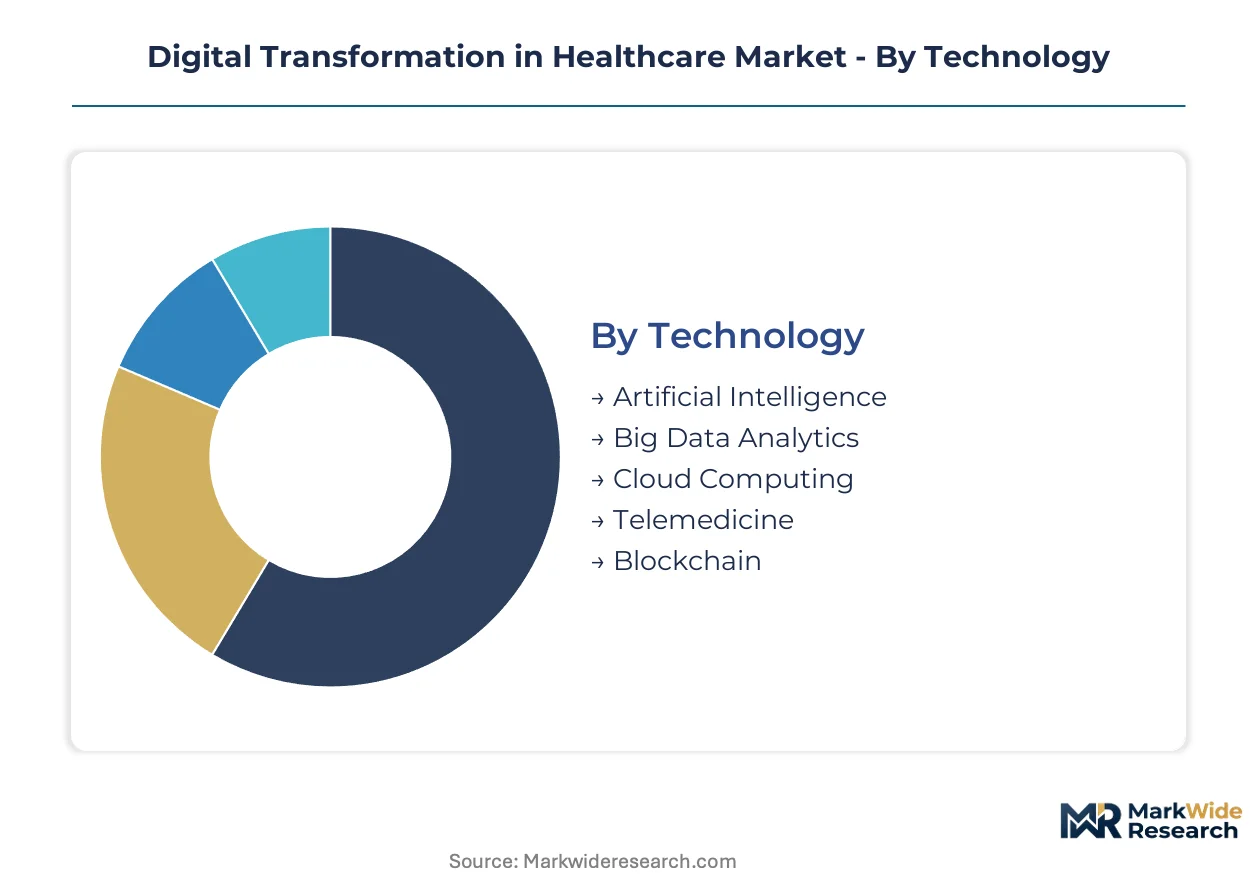
Segmentation analysis within the digital transformation in healthcare market clarifies the diverse technological adoption patterns and strategic investment priorities across various stakeholders. Understanding these distinct segments helps healthcare providers and technology vendors tailor solutions that address specific operational needs and patient care requirements.
Technology:
The intensity of after-sales service and ongoing support significantly differentiates technology segments in digital healthcare.
- Artificial Intelligence:Involves machine learning algorithms and advanced analytics to process vast datasets, identify patterns, and support clinical decision-making. Demand is significant in diagnostic centers and large research hospitals for medical imaging analysis and predictive modeling.
- Cloud Computing:Provides on-demand access to computing resources, storage, and applications over the internet, eliminating the need for direct active management. Demand concentrates in small to mid-sized clinics and large hospital systems seeking scalable infrastructure for EHRs and data analytics.
- Big Data Analytics:Processes large volumes of complex healthcare data to uncover hidden patterns, correlations, and insights for improved outcomes.
- Telemedicine:Facilitates remote clinical services and virtual consultations, enabling patient access to care from various locations.
- Blockchain:Offers a decentralized, secure ledger technology for managing patient records and ensuring data integrity across multiple stakeholders.
Cloud Computing holds the largest share; momentum sits with Artificial Intelligence.
Application:
Digital transformation applications directly impact various stages of the patient journey and administrative workflows.
- Electronic Health Records:Serve as the foundational digital repository for patient medical information, streamlining documentation and information access for providers. Demand is concentrated across all healthcare facilities, driven by regulatory mandates for data interoperability in developed economies.
- Remote Monitoring:Utilizes connected devices and platforms to track patient health data outside traditional clinical settings, supporting chronic disease management and preventive care. Demand is expanding rapidly in North America and Western Europe due to patient-centric care models and telehealth expansion.
- Patient Engagement:Tools and platforms designed to empower patients with access to health information, appointment scheduling, and communication with care teams.
- Clinical Decision Support:Provides evidence-based recommendations and alerts to clinicians at the point of care, enhancing diagnostic accuracy and treatment planning.
- Revenue Cycle Management:Optimizes financial processes from patient registration to final payment, improving billing accuracy and reducing administrative overhead for providers.
Electronic Health Records remain central, while Remote Monitoring shows the steepest expansion trajectory.
End User:
The diverse needs and operational scales of various healthcare end-users shape the adoption patterns of digital solutions.
- Hospitals:Large, integrated healthcare facilities requiring comprehensive digital solutions for patient management, clinical workflows, and administrative functions. Demand is driven by the need to improve patient outcomes and operational efficiency within complex environments, particularly in large hospital networks.
- Ambulatory Centers:Outpatient facilities providing specialized medical services, focusing on streamlined patient flow and efficient resource utilization. Demand for digital tools here emphasizes patient scheduling, electronic medical records, and telemedicine platforms to enhance accessibility.
- Diagnostic Laboratories:Utilize digital tools for managing test orders, processing results, and integrating data with patient records to support clinical diagnoses.
- Pharmacies:Implement digital systems for prescription management, inventory control, and patient medication adherence programs, improving dispensing accuracy and efficiency.
- Rehabilitation Centers:Adopt digital platforms for therapy management, progress tracking, and patient engagement, facilitating personalized recovery plans and remote monitoring.
Hospitals represent the primary consumer base, with Ambulatory Centers gaining share fastest due to increasing outpatient care.
Implementation Model:
The choice of implementation model significantly influences upfront investment, operational flexibility, and ongoing maintenance for healthcare organizations.
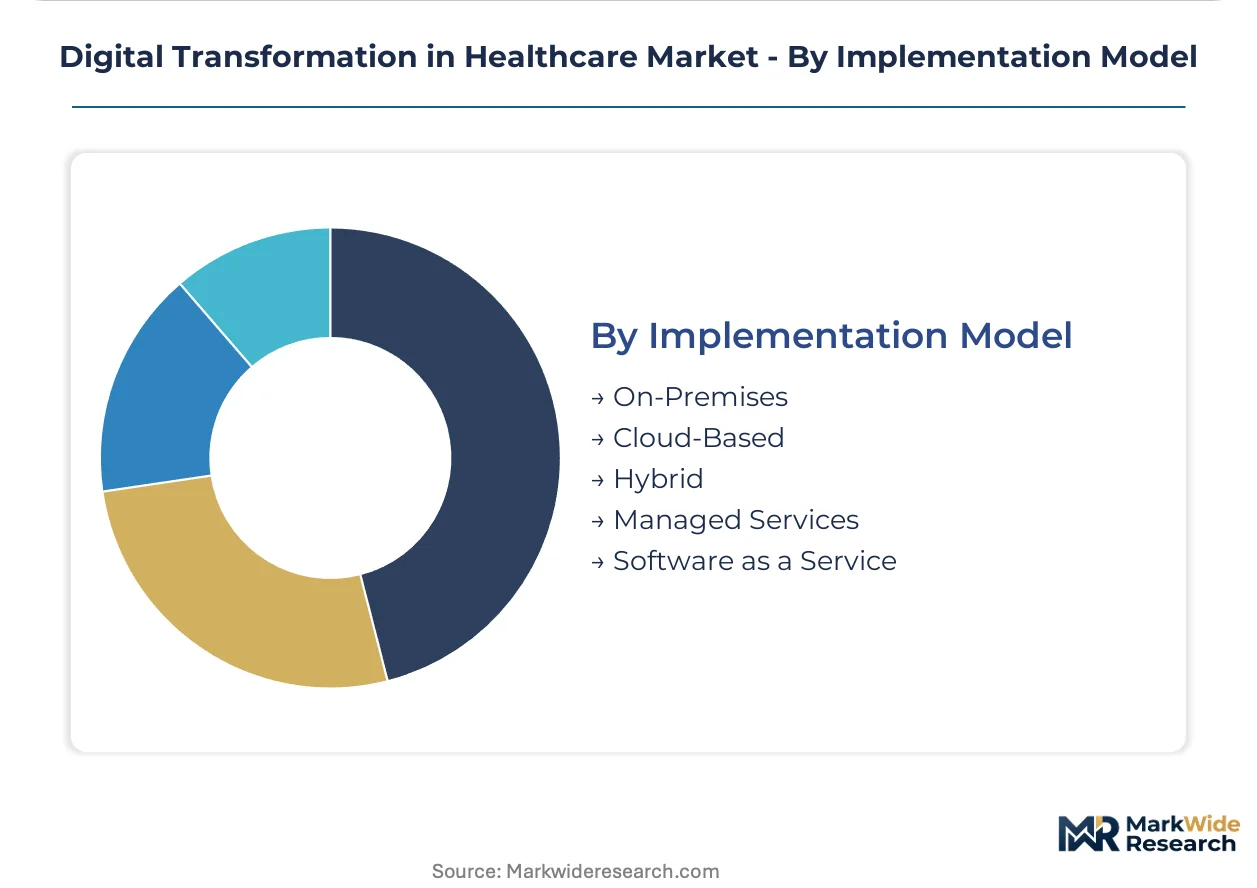
- Cloud-Based:Involves deploying digital health solutions on remote servers accessed via the internet, offering scalability and reduced infrastructure costs. Demand is concentrating among smaller clinics and hospitals seeking to avoid massive upfront capital investments and leverage subscription models.
- Software as a Service:Delivers software applications over the internet on a subscription basis, managed by a third-party vendor, providing a ready-to-use solution. This model is expanding quickly in healthcare due to its asset-light approach, enabling access to advanced technologies without extensive IT overhead.
- On-Premises:Involves installing and running software on local servers within the healthcare facility, offering full control over data and customization options.
- Hybrid:Combines elements of both on-premises and cloud-based deployments, allowing organizations to maintain sensitive data locally while leveraging cloud resources for scalability.
- Managed Services:Entails outsourcing IT operations and management to a third-party provider, allowing healthcare facilities to focus on core patient care activities.
Cloud-Based models are rapidly displacing traditional On-Premises solutions, with Software as a Service driving much of this shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies and incentives are significantly driving the digital transformation in healthcare across various nations. These regulatory pushes accelerate the adoption of advanced health technologies, improving patient outcomes and operational efficiencies. Nations prioritize data interoperability and secure information exchange to modernize their healthcare infrastructures.
United States
The United States sees strong demand for digital tools driven by patient engagement and remote monitoring services. The 21st Century Cures Act actively mandates open data sharing APIs, stimulating investment in interoperable platforms. Innovation clusters in Silicon Valley and Boston's biotech corridor are accelerating the development of new digital health solutions.
Germany
Germany's demand for digital health solutions stems from its robust hospital infrastructure and focus on advanced diagnostics. The General Data Protection Regulation (GDPR) establishes stringent requirements for secure patient data management across the nation. Medical technology hubs in Munich and Berlin are actively developing AI-powered diagnostic tools and cloud-based platforms.
China
China exhibits rapid expansion in demand for advanced electronic health record systems and telemedicine platforms. The National Health Commission actively promotes digital health initiatives to improve healthcare accessibility and efficiency. Major tech hubs in Shanghai and Beijing are concentrating on AI integration within healthcare and scalable cloud solutions.
India
India presents significant greenfield opportunities for digital health vendors with scalable and cost-effective solutions. The Ayushman Bharat Digital Mission is actively building a national digital health infrastructure, driving demand for interoperable platforms. Bengaluru and Hyderabad are major hubs for health IT development, attracting investment in cloud and AI technologies.
Japan
Japan's aging demographic fuels demand for remote monitoring technologies and patient engagement platforms. The Ministry of Health, Labour and Welfare actively supports digital health transformation through various policy initiatives. Research centers in Tokyo and Kyoto are specializing in AI applications for medical imaging and predictive analytics.
Digital Transformation in Healthcare Market Key Industry Players
On the supply side, the industry is tiered and evolving, balancing established enterprise solutions with agile cloud-based offerings for diverse healthcare providers. Three strategic archetypes include large-scale EHR providers, specialized AI and analytics platforms, and SaaS-centric telemedicine solution vendors. Companies engage in strategic acquisitions to expand their comprehensive data management capabilities and broaden their service portfolios. Portfolio diversification into cloud computing and advanced analytics also defines competitive moves among these players, alongside strategic partnerships.
On the enterprise solution vector, Epic Systems Corporation represents a deep integration within large hospital networks, maintaining a strong market position through its established EHR systems. Oracle Health, following its acquisition of Cerner, exemplifies a comprehensive enterprise-level data management capability, competing on the strength of its broad portfolio. Siemens Healthineers AG occupies a position leveraging its medical imaging expertise to integrate digital solutions for enhanced diagnostics and clinical workflows. These entities anchor the market for extensive, integrated digital health platforms, serving complex healthcare ecosystems with specialized offerings.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| GE HealthCare Technologies Inc |
| Siemens Healthineers AG |
| Koninklijke Philips NV |
| Medtronic Plc |
| Cerner Corporation |
| IBM Watson Health |
| Teladoc Health |
| Others |
Cost & Logistics Intelligence
Global data transmission networks shape the cost dynamics for digital healthcare solutions, influencing both the concentration of specialized software development and the differentiation of downstream service pricing.
Pricing Analysis
Regulatory compliance certifications (HIPAA, GDPR) create the primary spread in digital health solution pricing. Subscription-based SaaS models dominate, offering access to advanced technologies without substantial upfront capital. Price differentiation stems from the level of customization required and the depth of integrated after-sales support. Pricing pressure intensifies for basic EHR functionalities due to increasing competition from cloud-native providers. Small to mid-sized clinics exhibit the highest price sensitivity, often opting for standardized, cost-effective solutions.
Supply Chain Analysis
Cybersecurity threat landscapes represent a significant structural risk in the digital health supply chain. Software development and data center infrastructure concentrate in the United States, India, and China. Key dependencies include specialized AI processors and robust cloud computing services. Data sovereignty concerns between major economic blocs influence infrastructure deployment decisions. Distribution primarily runs through direct sales teams and strategic channel partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the increasing patient expectation for on-demand access to health data and care services, creating numerous niche demands.
For Market Incumbents:
Insulate core EHR market share by accelerating interoperability initiatives through FHIR-compliant APIs, addressing the threat from agile cloud-native platforms. Deepen integration with AI and machine learning capabilities to offer predictive analytics and clinical decision support, leveraging existing large datasets. Strategic partnerships with specialized telehealth providers can expand service portfolios and maintain relevance against emerging entrants.
For New Entrants and Emerging Players:
Underpenetration in specialized telehealth services within Southeast Asia and Latin America offers significant white space. Target specific clinical areas like tele-psychiatry or remote chronic disease management with focused, scalable SaaS solutions. A go-to-market angle emphasizing rapid deployment and demonstrable ROI for smaller healthcare facilities can facilitate market entry.
For Investors and Strategic Acquirers:
Carve-out targets emerge from conglomerate technology firms shedding non-core healthcare IT assets, and from legacy EHR providers seeking to divest outdated product lines. Digital health represents a multi-decade transformation, supporting long-term investment viability in foundational technologies. The signal to watch is regulatory harmonization across major economies, which could unlock broader market access for innovative solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless data flow between disparate systems enhances patient care coordination and operational efficiency. |
| Strategic Partnership | Collaboration with specialized AI firms accelerates the development of advanced diagnostic tools. |
| Geographic Expansion | Entering nascent digital health ecosystems in emerging markets captures greenfield opportunities. |
| Acquisition of Specialist Firm | Targeting cybersecurity solution providers strengthens data protection capabilities against evolving threats. |
| Product Launch | Introducing new patient engagement platforms meets the growing demand for continuous patient interaction. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved dialogues with hospital CIOs, clinical workflow specialists, health tech developers, and regulatory compliance officers. This was complemented by secondary data from regulatory body reports (HIPAA, GDPR, EU AI Act), industry association publications, academic research papers, and company financial disclosures, enabling both bottom-up and top-down triangulation.
The forecast inputs considered included evolving healthcare spending trends, technological advancements, and regional digital literacy rates across the analysis window. The analytical framework modeled segmentation dimensions such as technology, application, end user, implementation model, and regional regulatory environment. Compound Annual Growth Rates were derived through a comprehensive assessment of historical growth patterns and projected future market dynamics.
Practitioners should monitor unforeseen regulatory changes, major cyberattacks, and economic downturns impacting healthcare budgets for early signals of market shifts. These forecasts reflect underlying assumptions about technology adoption and policy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market