
 South East Asia Digital Transformation Market | 2026-2036
South East Asia Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Digital Transformation Market Insights
Market Context
ISO/IEC 27001 certification is rotating as the primary gating standard for enterprise digital transformation contracts across South East Asia. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor public sector engagements in Singapore and Thailand. IBM Corporation sustains mainframe modernization pipelines for legacy banking infrastructure across Indonesia and Malaysia. Accenture PLC dominates strategy consulting mandates tied to Industry 4.0 upgrades in Vietnamese manufacturing zones.
Technical Definition and Segment Structure
South East Asia digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, Internet of Things, and big data analytics into enterprise operational architectures to automate workflows, optimize decision velocity, and restructure customer engagement models. Cloud computing infrastructure commands the largest committed spend pool as hyperscalers expand availability zones in Jakarta, Singapore, and Bangkok to reduce latency for latency-sensitive manufacturing and financial services workloads. Hybrid cloud deployment models capture the fastest expansion trajectory as Indonesian and Philippine enterprises straddle legacy on-premises systems with elastic public cloud burst capacity during peak trading cycles. Managed services margin pools concentrate around 24/7 security operations center outsourcing and patch management, particularly for mid-market firms lacking captive cybersecurity expertise.
Regulatory Framework
Singapore's Personal Data Protection Commission, Indonesia's Ministry of Communication and Informatics, and Thailand's National Cyber Security Agency collectively enforce data localization and breach notification standards that dictate cloud architecture choices and vendor eligibility across the region. BIS-equivalent standards in Vietnam and Philippines further fragment compliance requirements, forcing service providers to maintain jurisdiction-specific infrastructure footprints. Stakeholders must monitor evolving cross-border data transfer reciprocity agreements between ASEAN member states to anticipate whether unified regional cloud frameworks will emerge or national silos will deepen procurement complexity.
Market Dynamics
ISO/IEC 27001 certification requirements are compressing vendor qualification timelines across South East Asia, forcing enterprises to pre-certify cloud and cybersecurity partners before procurement cycles begin.
Growth Catalysts
- Indonesian manufacturing corridor expansion:Export processing zones in Batam and Bekasi are mandating IoT-enabled predictive maintenance systems to meet buyer traceability requirements from European and North American importers.
- Singapore's PDPC cross-border framework:The Personal Data Protection Commission's 2023 trust certification scheme for data intermediaries is accelerating lawful data transfer volumes between Singapore-based headquarters and ASEAN operating subsidiaries.
- Thai banking cloud migration:The Bank of Thailand's operational risk management guidelines are pushing retail banks toward hybrid architectures that burst transaction processing into domestic cloud availability zones during quarterly reporting peaks.
Market Restraints
- Data localization hardware costs:Indonesian and Vietnamese regulations requiring in-country server deployment are inflating capital expenditure baselines by 40-60 percent versus regional cloud arbitrage models.
- ASEAN regulatory fragmentation:Non-harmonized breach notification timelines across Singapore, Thailand, Indonesia, and Vietnam force service providers to maintain parallel compliance operations, eroding margin pools.
- Legacy mainframe dependency:Malaysian and Indonesian universal banks retain COBOL-based core banking systems that resist API-native integration, constraining real-time analytics deployment.
Strategic Opportunities
- Philippine mid-market SOC outsourcing:Cebu and Clark IT-BPO corridors harbor 12,000+ mid-sized enterprises lacking captive 24/7 security operations capabilities, creating managed detection and response service whitespace.
- AI-IoT convergence in Vietnamese smart factories:Northern industrial provinces are piloting computer vision quality control systems integrated with predictive maintenance platforms for electronics contract manufacturers.
- Thailand's digital wallet infrastructure:The government's retail central bank digital currency distribution is forcing payment processors to rebuild backend architectures, opening systems integration contracts for cloud-native vendors.
Industry Challenges
- Cloud-native talent scarcity:Kubernetes and Terraform certification holders in Jakarta and Bangkok command 2.5x salary premiums versus traditional infrastructure administrators, constraining project velocity.
- ISO 27001 audit backlog:Certification body capacity constraints in Singapore and Kuala Lumpur are extending enterprise vendor onboarding timelines to 14-18 weeks.
- Hybrid integration complexity:Indonesian conglomerates operating SAP ECC on-premises alongside Salesforce cloud instances face master data synchronization failures that stall customer 360 initiatives.
Report Scope
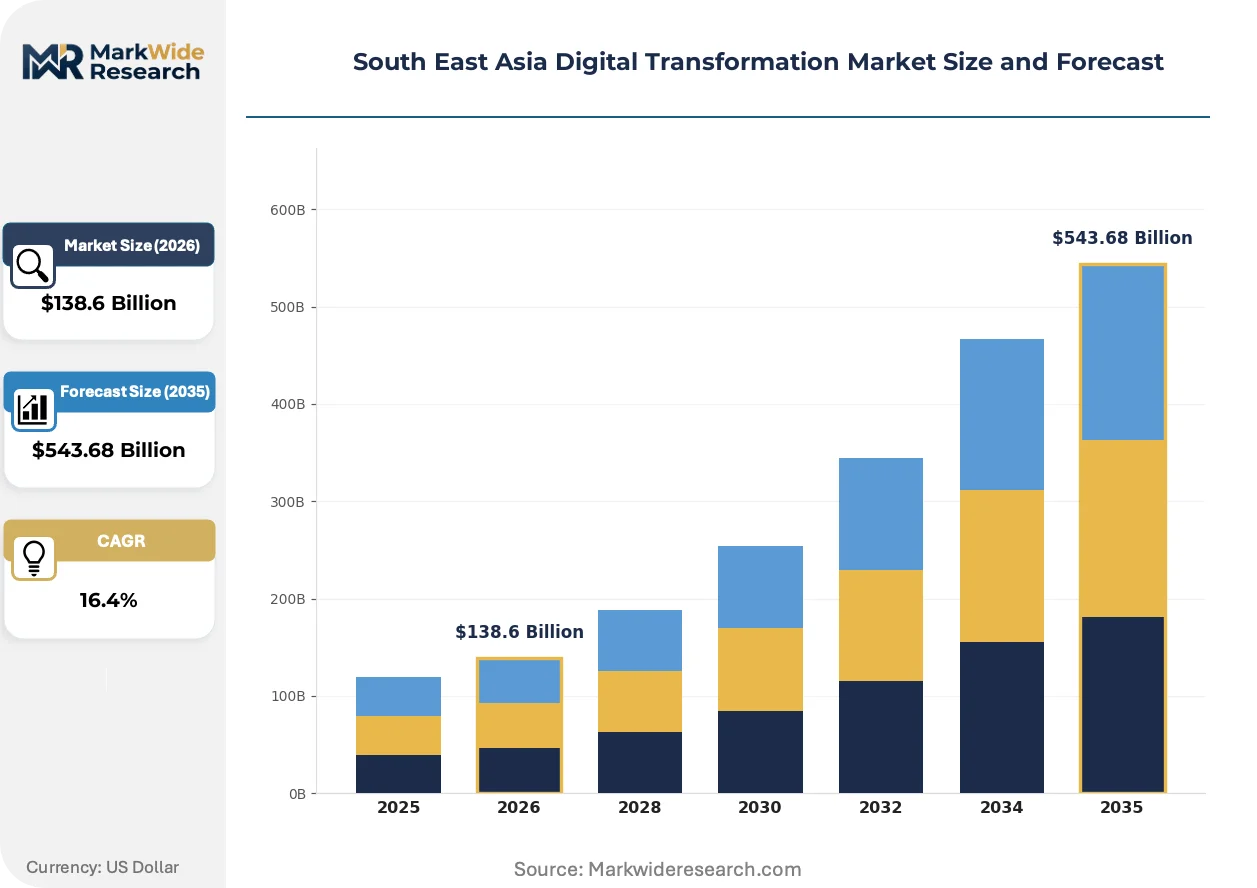
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Digital Transformation Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $543.68 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, AI, IoT, Big Data End User: Retail, Healthcare, Manufacturing, Education Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Managed Services, Integration Services, Support Services |
| Companies Covered | Accenture PLC, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Cisco Systems, Infosys, Tata Consultancy Services, NTT Data, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Digital Transformation Market Trends and Innovations
Generative AI copilots are penetrating South East Asian enterprise workflows faster than prior automation waves, compressing the traditional three-year technology adoption cycle into 12-18 month procurement windows.
Edge computing nodes deployed within Indonesian manufacturing plants are displacing centralized cloud analytics for latency-sensitive quality control applications. Electronics assemblers in Batam and Semarang are installing GPU-equipped edge servers to process machine vision inference locally rather than round-tripping to Singapore availability zones. This architectural shift is compressing defect detection response times from 800 milliseconds to sub-50 milliseconds while reducing cross-border data transfer volumes.
Thailand's National Cyber Security Agency has enacted mandatory critical infrastructure notification requirements that classify financial services, energy, and healthcare data flows as protected categories. The regulation forces domestic enterprises to pre-register cloud service provider contracts for security review, adding 6-10 weeks to procurement timelines. Thai conglomerates are responding by embedding compliance documentation into RFP templates and pre-qualifying vendors with existing NCSA security clearance.
Subscription-based managed security service contracts are displacing perpetual license plus maintenance models across Philippine and Vietnamese mid-market enterprises. Channel partners in Manila and Ho Chi Minh City are unbundling hardware provisioning from ongoing threat monitoring, shifting revenue recognition to monthly recurring streams. This pattern concentrates most visibly among 500-2,000 employee manufacturing exporters seeking to convert fixed security infrastructure costs to variable operating expenditures aligned with shipment volumes.
South East Asia Digital Transformation Market Segmentation
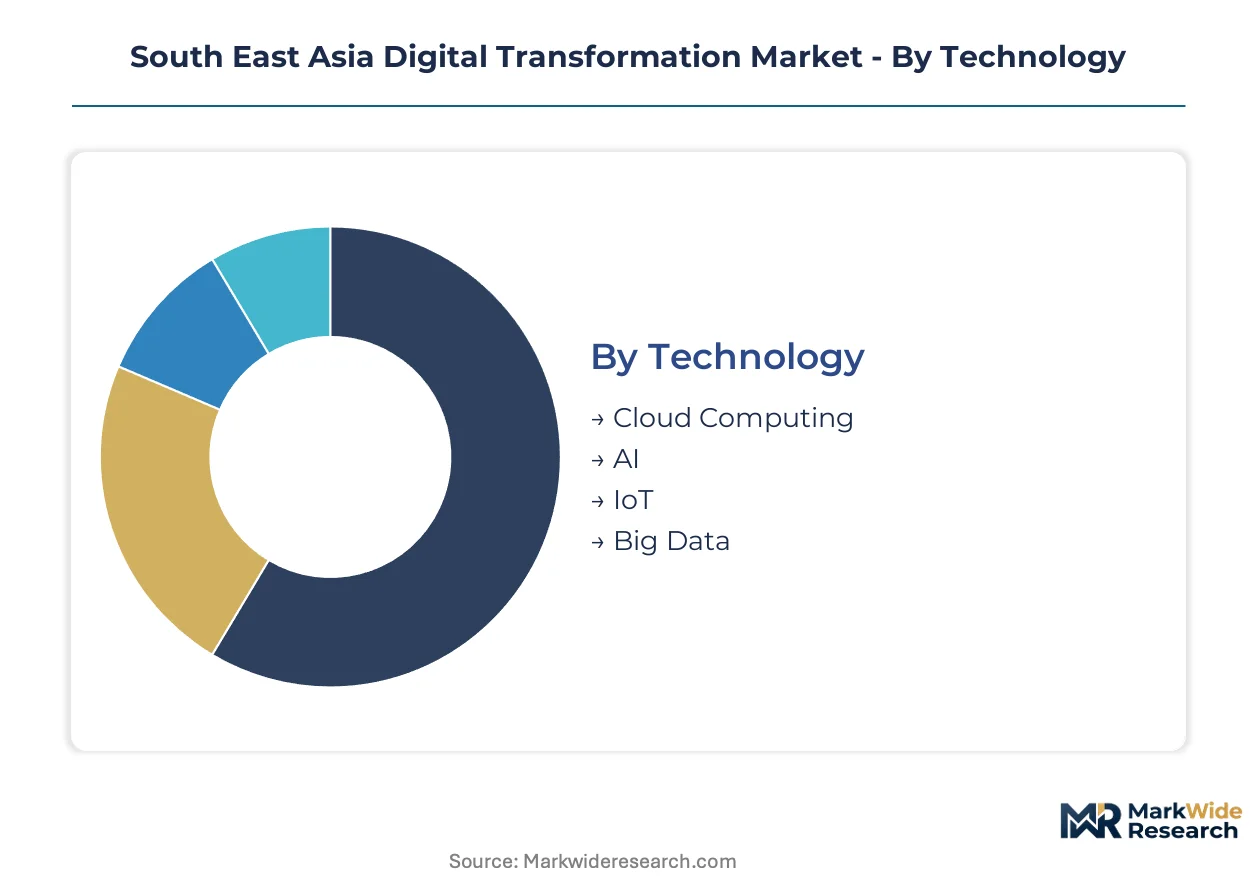
Technology choices across South East Asia increasingly hinge on data sovereignty requirements rather than pure performance metrics. Regulatory fragmentation between Singapore, Indonesia, Thailand, and Vietnam forces enterprises to architect segment-specific solutions that satisfy jurisdiction-specific compliance thresholds.
Technology:
Singapore's PDPC, Indonesia's Ministry of Communication and Informatics, and Thailand's National Cyber Security Agency each impose distinct technical mandates that reshape technology procurement priorities across the region.
- Cloud Computing:Hyperscalers operate dedicated availability zones in Jakarta, Singapore, and Bangkok to satisfy latency requirements for financial services transaction processing. Indonesian and Thai data localization statutes compel in-country infrastructure deployment, eliminating regional arbitrage strategies that previously routed workloads through Singapore hubs.
- AI:Generative copilots are compressing enterprise adoption cycles from thirty-six months to twelve-to-eighteen month procurement windows. Vietnamese electronics manufacturers and Thai banks deploy computer vision and natural language processing for quality control and customer service automation, though talent scarcity in Jakarta and Bangkok constrains project velocity.
- IoT:Predictive maintenance platforms anchor manufacturing corridor mandates in Batam and Bekasi export zones. European and North American importers require traceability systems that Indonesian suppliers satisfy through sensor-enabled production line monitoring.
- Big Data:Malaysian and Indonesian universal banks struggle with COBOL-based core systems that resist API-native integration, stalling real-time analytics deployment despite infrastructure investments.
Established volume favors Cloud Computing; emerging adoption favors AI.
End User:
Customer sophistication and regulatory exposure determine solution complexity and margin structure across vertical markets.
- Manufacturing:Electronics assemblers in Batam and Semarang install GPU-equipped edge servers for sub-fifty-millisecond defect detection, displacing centralized cloud analytics. Export processing zone mandates from European buyers drive IoT-enabled predictive maintenance investments.
- Retail:Thailand's retail central bank digital currency distribution forces payment processors to rebuild backend architectures, opening systems integration contracts for cloud-native vendors.
- Healthcare:Thailand's National Cyber Security Agency classifies healthcare data flows as protected categories, forcing pre-registration of cloud contracts and extending procurement timelines by six-to-ten weeks.
- Education:Philippine and Vietnamese institutions pursue hybrid learning platforms with limited captive IT expertise, creating managed service whitespace for channel partners.
Margin concentration sits with Manufacturing; regulatory tailwinds favor Healthcare.
Deployment Model:
Capital intensity and compliance risk stratify deployment preferences across enterprise maturity tiers.
- Hybrid Cloud:Indonesian and Philippine enterprises straddle legacy on-premises systems with elastic public cloud burst capacity during peak trading cycles. The Bank of Thailand's operational risk guidelines explicitly push retail banks toward this architecture for quarterly reporting peaks.
- Private Cloud:Singaporean headquarters operations and Thai conglomerates with NCSA security clearance maintain dedicated infrastructure for sensitive workloads. Pre-qualification requirements compress vendor pools to established players with existing regulatory relationships.
- Public Cloud:Mid-market firms in Cebu and Clark IT-BPO corridors leverage regional availability zones for cost efficiency, though data localization hardware costs inflate baselines forty-to-sixty percent versus arbitrage models.
- On-Premises:Malaysian and Indonesian universal banks retain COBOL-based core banking systems that resist migration, constraining real-time capabilities.
Fastest expansion trajectory belongs to Hybrid Cloud; legacy lock-in preserves On-Premises.
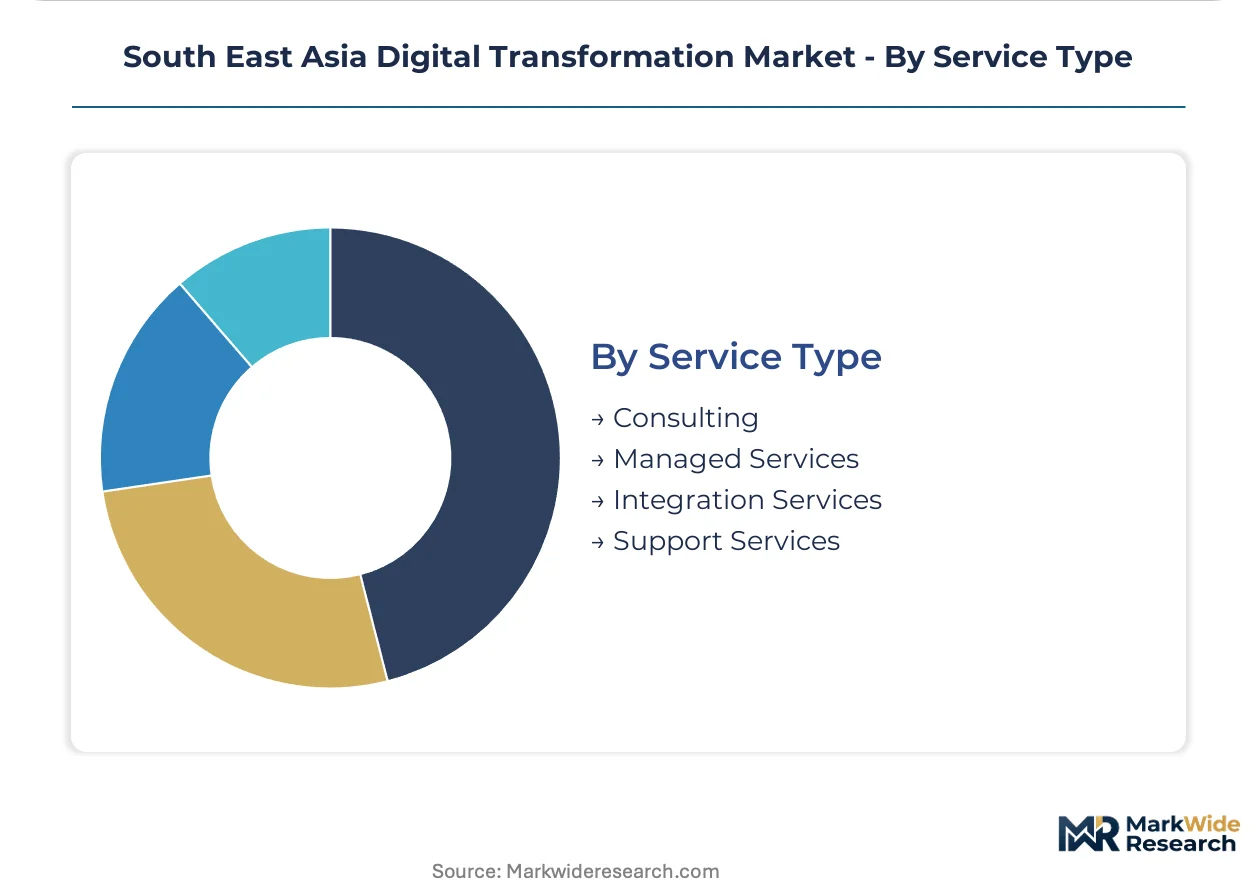
Service Type:
Revenue recognition models shift from perpetual licenses toward recurring streams as mid-market buyers seek variable cost structures.
- Managed Services:Twenty-four-hour security operations center outsourcing concentrates margin pools around mid-market firms lacking captive cybersecurity expertise. Channel partners in Manila and Ho Chi Minh City unbundle hardware from ongoing threat monitoring, converting fixed infrastructure costs to monthly recurring expenditures aligned with shipment volumes.
- Consulting:Strategy mandates tied to Industry 4.0 upgrades in Vietnamese manufacturing zones demand vertical expertise in computer vision quality control and predictive maintenance integration.
- Integration Services:Indonesian conglomerates operating SAP ECC on-premises alongside Salesforce cloud instances face master data synchronization failures that stall customer 360 initiatives, creating demand for hybrid integration specialists.
- Support Services:ISO 27001 certification body capacity constraints in Singapore and Kuala Lumpur extend vendor onboarding timelines to fourteen-to-eighteen weeks, forcing enterprises to embed compliance documentation into RFP templates.
Recurring revenue momentum favors Managed Services; project-based demand anchors Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Personal Data Protection Commission has enacted stricter cross-border data flow certification schemes that are reshaping vendor selection criteria across ASEAN headquarters operations. Indonesia's Ministry of Communication and Informatics mandates in-country server deployment that inflates capital expenditure baselines. Thailand's National Cyber Security Agency forces pre-registration of cloud contracts for security review.
Singapore
Financial services institutions and multinational headquarters anchor cloud migration demand as the Personal Data Protection Commission enforces trust certification schemes for data intermediaries. The 2023 cross-border framework accelerates lawful data transfer volumes between Singapore-based headquarters and ASEAN operating subsidiaries. Marina Bay and One-North technology corridors concentrate hyperscaler availability zones serving latency-sensitive regional workloads.
Indonesia
Manufacturing corridors in Batam and Bekasi mandate IoT-enabled predictive maintenance systems to meet European and North American importer traceability requirements. The Ministry of Communication and Informatics requires in-country server deployment, eliminating regional cloud arbitrage strategies previously routed through Singapore hubs. Export processing zones in Semarang install GPU-equipped edge servers for sub-fifty-millisecond defect detection.
Thailand
Retail banks pursue hybrid cloud architectures that burst transaction processing into domestic availability zones during quarterly reporting peaks under Bank of Thailand operational risk guidelines. The National Cyber Security Agency classifies financial services data flows as protected categories, forcing pre-registration of cloud service provider contracts. Bangkok and Eastern Economic Corridor industrial zones concentrate systems integration demand tied to digital wallet infrastructure rebuilds.
Vietnam
Electronics contract manufacturers in northern industrial provinces pilot computer vision quality control systems integrated with predictive maintenance platforms. BIS-equivalent standards fragment compliance requirements, forcing service providers to maintain jurisdiction-specific infrastructure footprints. Hai Phong and Bac Ninh manufacturing zones drive Industry 4.0 consulting mandates for vertical expertise in automation integration.
Philippines
Cebu and Clark IT-BPO corridors harbor mid-sized enterprises lacking captive 24/7 security operations capabilities, creating managed detection and response service whitespace. Data localization hardware costs inflate baselines versus regional arbitrage models, compressing mid-market procurement budgets. Metro Manila channel partners unbundle hardware provisioning from ongoing threat monitoring, shifting revenue recognition to monthly recurring streams.
South East Asia Digital Transformation Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with established regulatory relationships and specialized consulting boutiques with vertical expertise. Market structure concentrates around three tiers: hyperscaler cloud platforms with sovereign architecture offerings, global systems integrators with ASEAN delivery networks, and regional managed service providers with pre-qualified security clearances. Dominant competitive moves include strategic partnerships with national regulators for compliance pre-certification and geographic expansion through local channel partner acquisitions.
Within the hyperscaler tier, Microsoft Corporation anchors public sector engagements through Azure sovereign cloud architecture tailored to Singapore and Thailand regulatory requirements. IBM Corporation sustains mainframe modernization pipelines for legacy banking infrastructure across Indonesia and Malaysia, representing the incumbent technology archetype resisting displacement. Accenture PLC dominates strategy consulting mandates tied to Industry 4.0 upgrades in Vietnamese manufacturing zones, exemplifying the vertical specialization approach capturing premium-margin transformation projects.
| Leading Market Players |
|---|
| Accenture PLC |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Cisco Systems |
| Infosys |
| Tata Consultancy Services |
| NTT Data |
| Others |
Pricing and Supply Chain Analysis
GPU-equipped edge servers displacing centralized cloud analytics in Indonesian manufacturing plants simultaneously compresses cross-border bandwidth costs and redistributes hardware procurement toward Batam and Semarang industrial zones. This substitution dynamic collapses the traditional Singapore-hub pricing model while elevating in-country server deployment premiums.
Pricing Analysis
Certification level creates the primary spread across South East Asia digital transformation contracts, with ISO/IEC 27001-accredited vendors commanding project premiums over uncertified competitors. Subscription-based SaaS tiers dominate revenue recognition, though data localization hardware requirements in Indonesia and Vietnam inflate capital expenditure baselines versus regional arbitrage alternatives. Price differentiation hinges on compliance grade and vertical expertise depth, with manufacturing buyers exhibiting highest sensitivity to upfront infrastructure costs while financial services prioritize security assurance over unit economics.
Supply Chain Analysis
Just-in-time provisioning preferences dominate hyperscaler cloud infrastructure deployment, though Indonesian data localization mandates force strategic stockpiling of in-country server capacity. Hardware supply concentrates in Singapore, Taiwan, and South Korea for GPU and networking equipment, while software licensing flows from US and European headquarters operations. Single-source vulnerability sits with specialized edge computing components sourced from Taiwan semiconductor fabricators. Distribution runs through channel partners in Manila and Ho Chi Minh City for mid-market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across ASEAN member states fragments procurement standards, creating specialist niches for compliance-certified service providers and jurisdiction-specific infrastructure operators.
For Market Incumbents: Compound regulatory relationships through pre-certification investments with Singapore's PDPC and Thailand's NCSA, converting compliance documentation into RFP template advantages. Deepen vertical expertise in Vietnamese manufacturing automation to defend margin position against emerging systems integrators. Prioritize ISO 27001 audit capacity expansion in Kuala Lumpur to compress vendor onboarding timelines that currently extend fourteen-to-eighteen weeks. For New Entrants and Emerging Players: Differentiate on sovereign cloud architecture specialization for Indonesian and Thai data localization requirements, targeting mid-market manufacturing exporters in Cebu and Clark corridors lacking captive 24/7 security operations. Penetrate Philippine education and healthcare managed services whitespace through unbundled hardware provisioning with monthly recurring threat monitoring. Lead with compliance-first positioning that embeds regulatory documentation into initial client conversations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional managed service providers with pre-qualified security clearances and established channel networks. Long-term viability rests on regulatory reciprocity evolution across ASEAN member states. Target acquisition archetypes include Indonesian SOC operators with NCSA relationships and Vietnamese Industry 4.0 consulting boutiques. Monitor cross-border data transfer agreement negotiations as the critical inflection signal for unified regional cloud framework emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Partnership | PDPC and NCSA security clearances compress procurement timelines by six-to-ten weeks for Thai and Singaporean contracts. |
| Edge Computing Infrastructure Deployment | GPU-equipped servers in Batam and Semarang reduce defect detection latency from centralized cloud round-trips. |
| Vertical Specialization Acquisition | Vietnamese manufacturing automation expertise captures premium-margin Industry 4.0 consulting mandates. |
| Channel Partner Network Expansion | Manila and Ho Chi Minh City partners enable mid-market recurring revenue conversion in Philippine IT-BPO corridors. |
| Sovereign Cloud Architecture Investment | In-country availability zones satisfy Indonesian and Thai data localization statutes eliminating regional arbitrage. |
Research Methodology
The analysis maps cloud computing infrastructure, artificial intelligence deployment, IoT-enabled manufacturing systems, and managed security services, each validated through chief technology officers, IT procurement officers, platform engineers, and channel partners across Singapore, Indonesia, Thailand, Vietnam, and the Philippines. Primary interview insights triangulate against secondary sources including hyperscaler capex disclosures, ASEAN regulatory filings, customs and trade data for hardware imports, and SEC 10-K filings for listed technology conglomerates. Bottom-up segment sizing reconciles with top-down market value estimates.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves applied to technology adoption cycle compression patterns and infrastructure investment trajectories. Forecast inputs incorporate cloud availability zone expansion timelines and ISO 27001 certification body capacity constraints.
Material uncertainties — regulatory reciprocity negotiations, cross-border data transfer rule harmonization, and hyperscaler capacity allocation decisions — sit outside the modeled envelope. Forecasts reflect assumptions about continued data localization enforcement and sustained manufacturing corridor automation mandates. Practitioners should keep alternative scenarios live as ASEAN regulatory coordination efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
North America Digital Transformation Market