
 MENA Digital Transformation Market | 2026-2036
MENA Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Digital Transformation Market Outlook
The gap between sovereign-grade cloud deployments and generic SaaS offerings is restructuring procurement patterns across MENA enterprise buyers. Oracle sustains dominance in on-premises database migrations for Gulf banking regulators. Amazon Web Services anchors hyperscale capacity through dedicated UAE and Saudi zones. Microsoft competes by bundling productivity suites with Azure sovereign cloud commitments tailored to local data residency mandates.
MENA digital transformation encompasses the integration of cloud computing, artificial intelligence, Internet of Things sensors, and blockchain protocols into enterprise and government operations, typically delivered through API-connected platforms with sub-100 millisecond latency requirements for real-time analytics. Its primary purpose is replacing legacy paper-based and siloed IT systems with interoperable digital infrastructure that reduces transaction costs and enables predictive decision-making. Cloud Computing leads technology spending as Gulf states prioritize hyperscale data center localization. Process Automation captures disproportionate margin pools in manufacturing and logistics verticals where labor arbitrage still dominates cost structures. Hybrid Cloud deployment models are growing fastest among BFSI end users navigating between regulatory data sovereignty requirements and elastic compute needs.
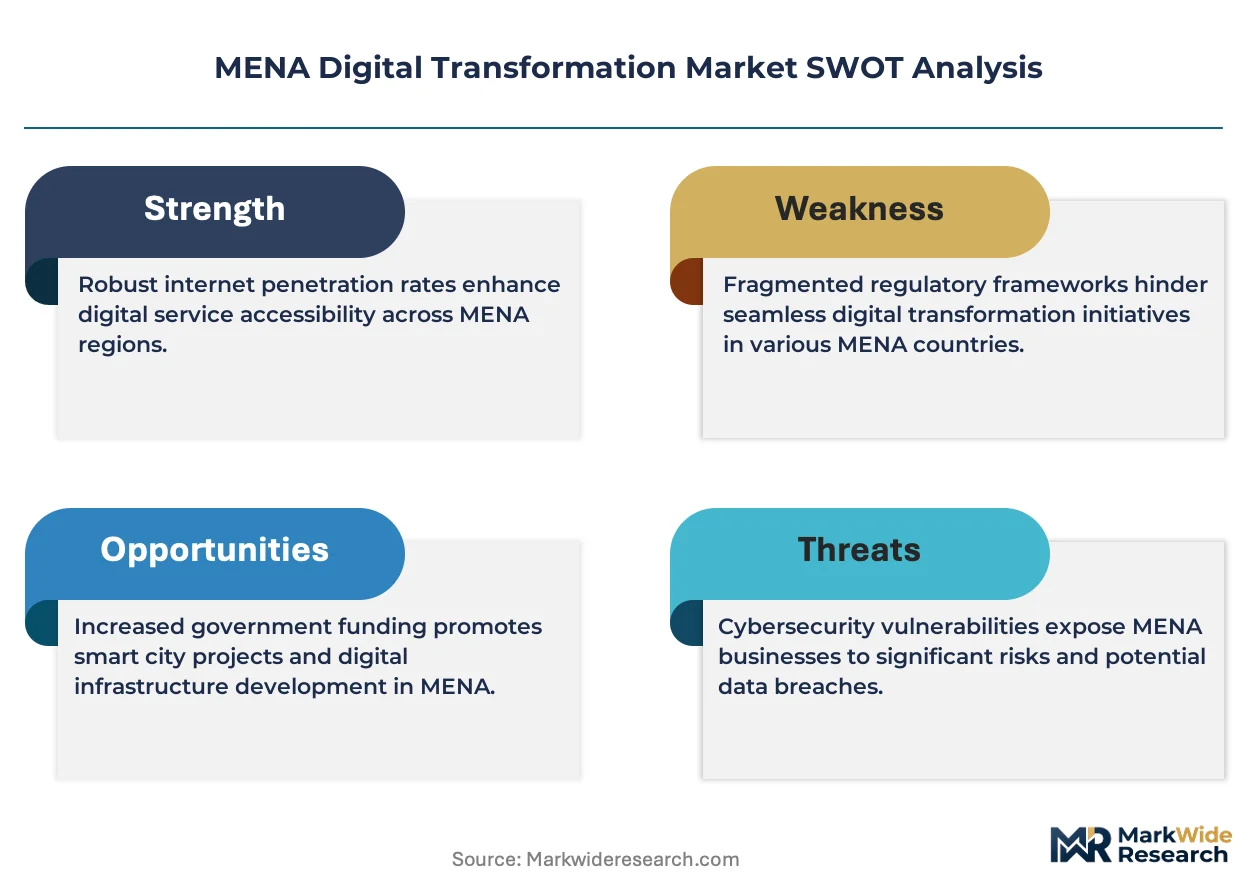
UAE's Telecommunications and Digital Government Regulatory Authority enforces data localization standards that shape cloud provider market entry requirements. Saudi Arabia's National Data Management Office and Egypt's National Telecom Regulatory Authority impose complementary compliance frameworks around cross-border data flows and cybersecurity certification. Stakeholders must monitor evolving sovereign AI governance codes as Gulf regulators draft algorithmic accountability rules that will determine which platform architectures qualify for government contract eligibility.
Market Dynamics
Sovereign data residency mandates are fragmenting cloud procurement across MENA enterprise buyers, forcing hyperscale providers to localize infrastructure while compliance costs reshape vendor selection criteria for banking and government contracts.
Growth Catalysts
- Saudi Vision 2030 digitization targets:Government mandates for paperless administration and e-services are accelerating enterprise software procurement across the Kingdom's public sector and state-linked enterprises.
- Edge computing deployments:Oil and gas operators in the UAE and Kuwait are installing sub-50 millisecond latency infrastructure to enable real-time predictive maintenance on offshore platforms.
- Central Bank digital currency frameworks:Monetary authorities in the UAE and Saudi Arabia are piloting programmable payment rails that require modernized core banking infrastructure upgrades.
Market Restraints
- Cross-border data transfer restrictions:UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's National Data Management Office impose conflicting localization standards that complicate multi-country enterprise architectures.
- Specialized cloud engineering talent scarcity:Gulf labor markets lack sufficient certified professionals for sovereign cloud deployment and zero-trust security implementation, inflating project timelines and contractor costs.
- Legacy mainframe dependency:Established banks in Egypt and Lebanon maintain COBOL-based core systems with decades of embedded business logic, creating technical debt that resists API-first modernization.
Strategic Opportunities
- Underpenetrated Egyptian enterprise market:Cairo-based mid-market manufacturers and logistics operators remain below 15% cloud adoption, presenting first-mover advantages for localized managed service providers.
- AI governance code anticipation:Draft algorithmic accountability rules under review by Gulf regulators will create certification requirements that qualified platform vendors can monetize through compliance-as-a-service offerings.
- Blockchain-IoT convergence:Dubai's trade and logistics corridors are piloting integrated sensor and distributed ledger infrastructure for end-to-end supply chain traceability, opening integrated platform contracts.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across Saudi, UAE, and Egyptian jurisdictions must manage disparate API standards, identity frameworks, and billing structures without unified management tooling.
- Cybersecurity certification bottlenecks:National security clearance requirements for cloud personnel in sensitive sectors extend hiring cycles and constrain project staffing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Digital Transformation Market |
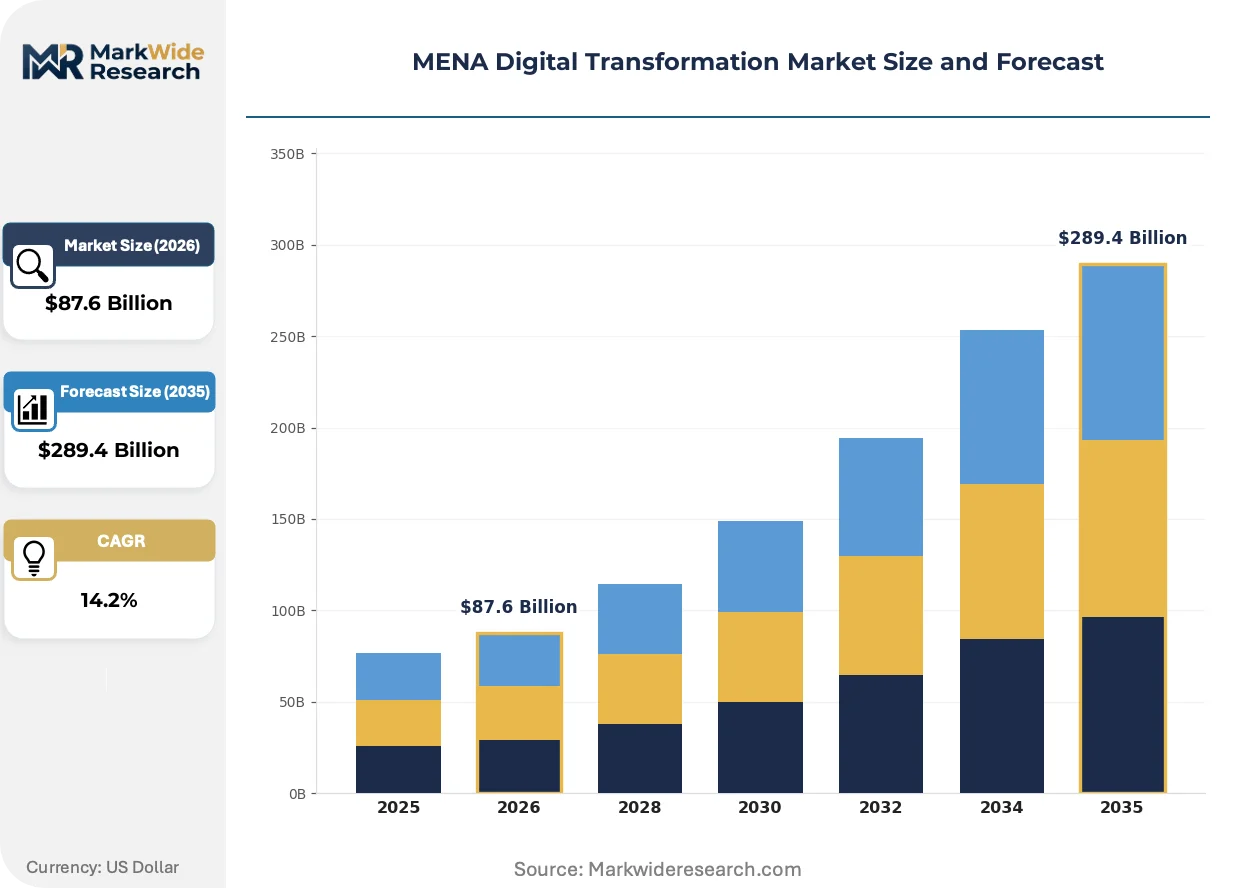
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, IoT, AI, Blockchain Deployment: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: Healthcare, Retail, BFSI, Manufacturing Application: Process Automation, Customer Experience, Data Analytics, Cybersecurity |
| Companies Covered | Oracle, Salesforce, Microsoft, Accenture, SAP, Amazon Web Services, IBM, Deloitte, Google Cloud, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Digital Transformation Market Strategic Shifts
Hyperscale infrastructure localization is compressing the architectural gap between on-premises sovereignty and elastic public cloud consumption across MENA financial services and government sectors.
Multi-tenant sovereign cloud architecture is consolidating procurement decisions for Gulf banking regulators who previously maintained separate negotiations for compute, storage, and productivity software layers. Saudi Arabian Monetary Authority licensed institutions are migrating core workloads to dedicated in-country availability zones at accelerated pace. This consolidation is collapsing the traditional three-year RFP cycle into unified platform commitments that bundle infrastructure, compliance certification, and managed security operations.
UAE's Telecommunications and Digital Government Regulatory Authority data classification framework is mandating tiered localization requirements based on data sensitivity levels, with Category 1 data requiring full in-country processing. Financial institutions must rearchitect customer-facing applications to satisfy these residency tiers or risk operating license suspension. Tier-1 banks are responding by establishing captive cloud subsidiaries that maintain operational independence from global hyperscale parent entities.
Enterprise buyers are unbundling transformation contracts from single-vendor systems integrators, instead awarding separate infrastructure, platform, and application layer contracts to specialized providers. Saudi government entities now run competitive tenders for cloud capacity, middleware, and citizen-facing application development as distinct workstreams. This fragmentation is most visible in Riyadh and Jeddah municipal digitization programs where procurement teams maintain separate vendor scorecards for each technology layer.
MENA Digital Transformation Market Segmentation
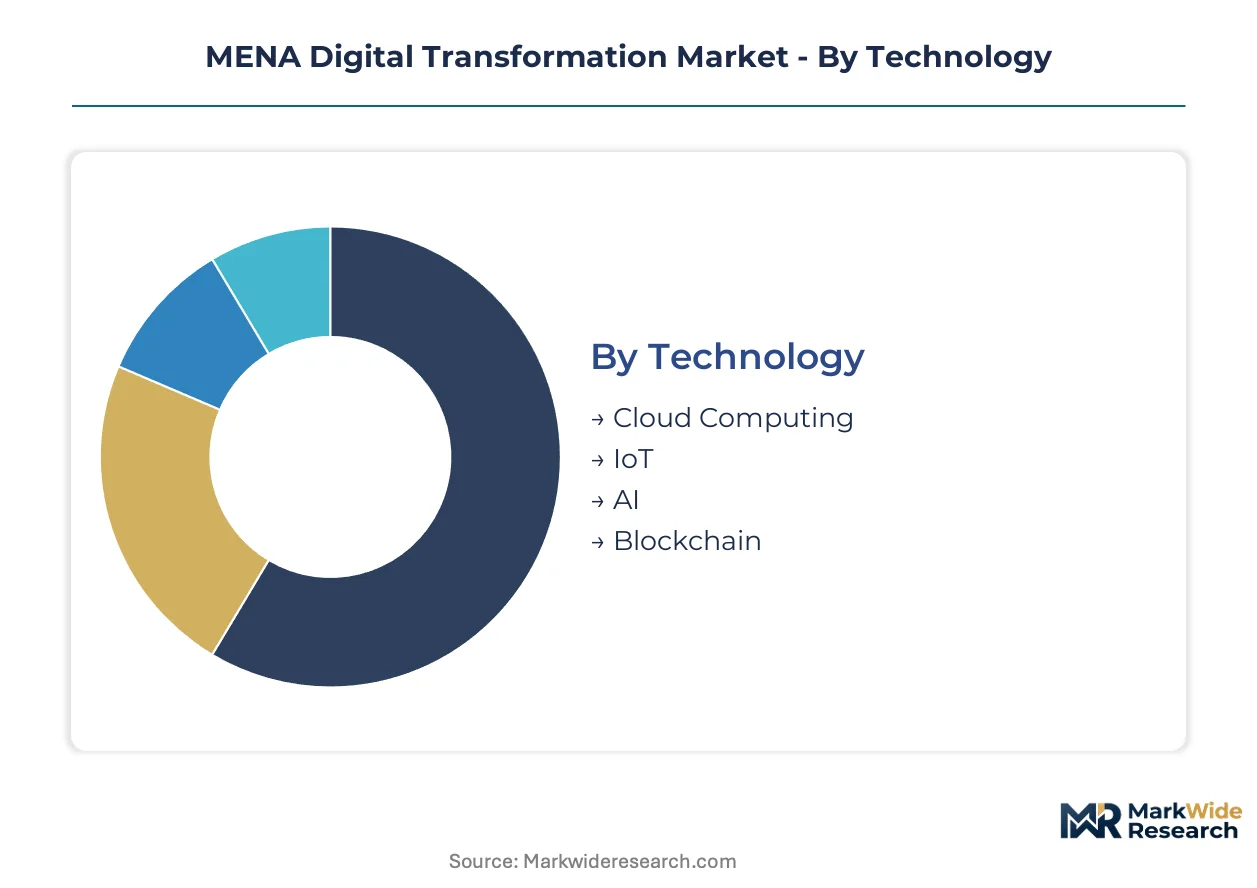
Technology layering in MENA digital transformation demands precise segmentation matching sovereign compliance requirements to workload characteristics. Deployment choices, end-user verticals, and application priorities fragment procurement patterns across Gulf banking regulators and Egyptian manufacturing clusters.
Technology:
Cloud infrastructure specifications anchor procurement decisions for Gulf financial institutions navigating data residency mandates.
- Cloud Computing:Hyperscale infrastructure with sub-100 millisecond latency requirements dominates sovereign data center investments in Saudi Arabia and UAE. Gulf banking regulators mandate in-country availability zones for core banking workloads, compressing vendor selection timelines.
- AI:Machine learning platforms with Arabic natural language processing capabilities concentrate government contract eligibility in Riyadh and Dubai. Algorithmic accountability drafts under regulator review shape platform architecture certification requirements.
- IoT:Industrial sensor networks with edge computing integration enable real-time predictive maintenance for UAE and Kuwait oil operators.
- Blockchain:Distributed ledger protocols pilot trade finance digitization across Dubai logistics corridors with customs integration requirements.
Mature deployment sits with Cloud Computing. Newer deployment is concentrated in AI.
Deployment:
Cost tier differentiation separates enterprise buyers with legacy technical debt from cloud-native entrants.
- Hybrid Cloud:Interoperable architectures bridging on-premises sovereignty with elastic public capacity capture BFSI procurement in Saudi Arabia. Tier-1 banks establish captive cloud subsidiaries maintaining operational independence from hyperscale parents.
- Private Cloud:Dedicated single-tenant infrastructure satisfies Category 1 data classification under UAE Telecommunications and Digital Government Regulatory Authority mandates. Full in-country processing requirements drive dedicated zone investments.
- Public Cloud:Shared multi-tenant services address non-sensitive workloads for mid-market Egyptian manufacturers below 15% cloud adoption.
- On-Premises:Legacy COBOL-based core systems in Egyptian and Lebanese banks resist API-first modernization despite escalating maintenance costs.
Volume concentration favors Hybrid Cloud. Margin expansion is accelerating fastest in Private Cloud.
End User:
Application maturity varies sharply across verticals with divergent regulatory exposure and labor cost structures.
- BFSI:Banking, financial services, and insurance verticals consolidate three-year RFP cycles into unified platform commitments bundling infrastructure, compliance certification, and managed security operations.
- Manufacturing:Process automation captures disproportionate margin pools where labor arbitrage still dominates Egyptian and Saudi cost structures.
- Healthcare:Patient data localization requirements under national health authority mandates constrain cloud architecture choices.
- Retail:Customer-facing digital service deployment concentrates in UAE and Saudi urban corridors with high smartphone penetration.
Procurement sophistication sits with BFSI. First-mover advantages are concentrating in Manufacturing.
Application:
Customer type segmentation separates government digitization mandates from competitive pressure responses in private sector buyers.
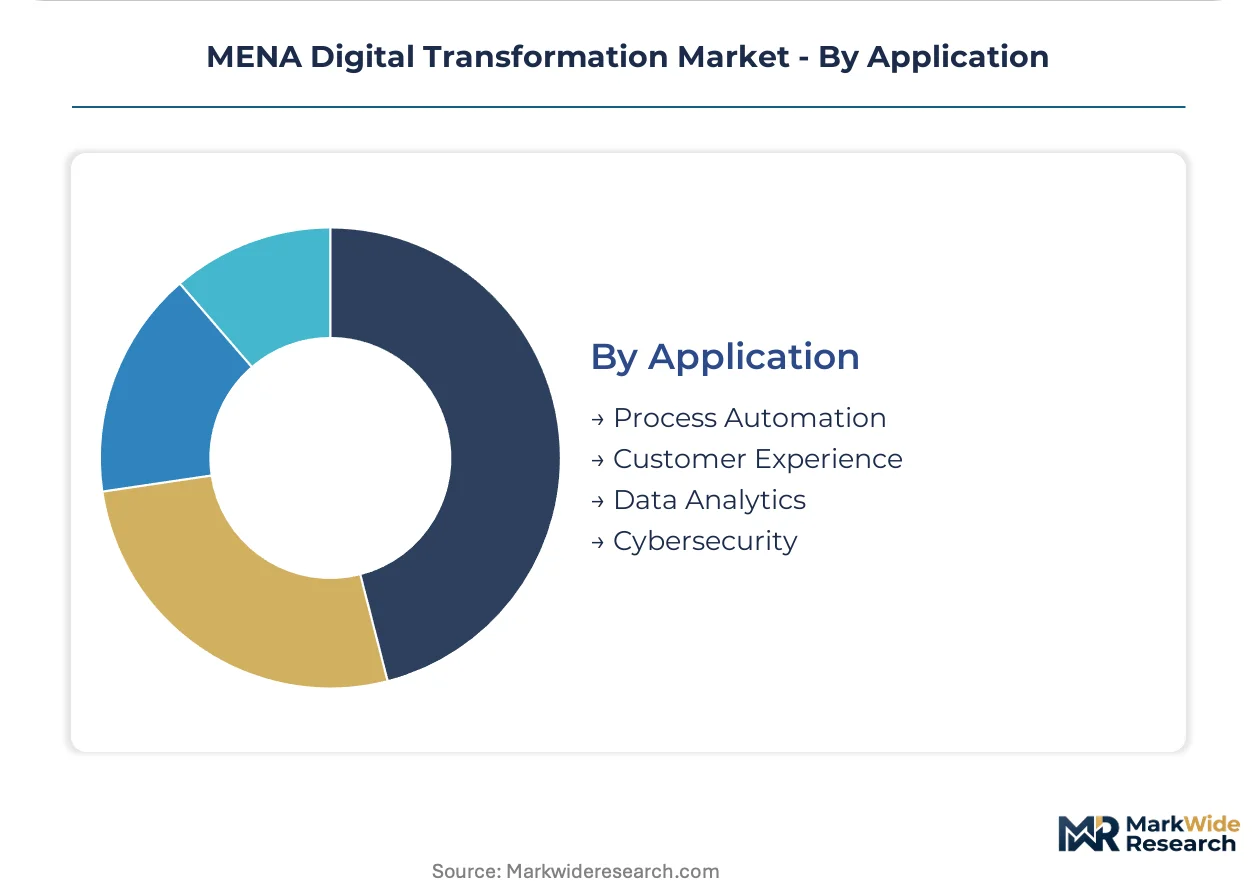
- Process Automation:Robotic process automation and workflow orchestration platforms displace paper-based administration in Saudi Vision 2030 paperless targets. Government mandates accelerate enterprise software procurement across public sector and state-linked enterprises.
- Data Analytics:Real-time predictive decision-making platforms integrate IoT sensor streams with sovereign cloud storage for oil and gas operators.
- Customer Experience:Citizen-facing digital service portals consolidate municipal procurement in Riyadh and Jeddah with separate vendor scorecards for each technology layer.
- Cybersecurity:Zero-trust security implementation faces talent scarcity inflating project timelines and contractor costs across Gulf labor markets.
Regulatory urgency sits with Process Automation. Capability building is expanding most quickly in Cybersecurity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors sovereign cloud deployment across the Gulf Cooperation Council, with hyperscale data center zones concentrated in King Abdullah Financial District and KAFD Tech Hub. The Saudi capital hosts the region's densest concentration of certified in-country availability zones for banking regulators.
Saudi Arabia
Public Investment Fund capital allocation and Saudi Vision 2030 digitization mandates drive enterprise software procurement. The National Data Management Office enforces cross-border data flow restrictions that shape cloud provider market entry. Jeddah municipal digitization programs run competitive tenders for citizen-facing application development as distinct workstreams from infrastructure procurement.
United Arab Emirates
Dubai's Smart Dubai initiative and Abu Dhabi sovereign wealth deployment concentrate demand for citizen-facing digital services. The Telecommunications and Digital Government Regulatory Authority mandates tiered data localization based on sensitivity classifications. Dubai Internet City clusters fintech operators piloting blockchain-IoT convergence for trade corridor traceability.
Egypt
Cairo-based mid-market manufacturers below 15% cloud adoption present first-mover opportunities for localized managed service providers. The National Telecom Regulatory Authority imposes cybersecurity certification frameworks around sovereign data requirements. New Administrative Capital construction incorporates smart city sensor networks with edge computing integration for municipal operations.
Kuwait
Oil and gas operators deploy sub-50 millisecond latency infrastructure for real-time predictive maintenance on offshore platforms. The Central Bank of Kuwait participates in regional digital currency pilot programs requiring modernized core banking infrastructure. Al-Zour refinery complex anchors industrial IoT sensor network deployments with sovereign cloud backhaul requirements.
Qatar
Liquefied natural gas expansion projects drive process automation procurement for operational technology integration. The Qatar National Bank regulatory environment shapes fintech cloud architecture certification requirements. Lusail smart city development concentrates API-first municipal service platforms with Arabic natural language processing capabilities.
MENA Digital Transformation Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light platform vendors for enterprise wallet share across MENA sovereign cloud procurement. The vendor base separates into three distinct tiers: hyperscale cloud providers with dedicated in-country zones, legacy enterprise software vendors migrating on-premises installations, and systems integrators bundling compliance certification with managed services. Dominant competitive moves include infrastructure localization investments to satisfy data residency mandates and vertical-specific partnership networks to capture banking and government contract eligibility.
Within the hyperscale infrastructure tier, Amazon Web Services, Microsoft, and Oracle occupy positions shaped by sovereign zone deployment timing and banking regulator relationships. AWS anchors UAE and Saudi dedicated zones through early market entry. Microsoft bundles productivity suites with Azure sovereign commitments tailored to local data residency mandates. Oracle sustains dominance in on-premises database migrations for Gulf banking regulators with decades of embedded core system relationships. These three vendors exemplify divergent pathways to contract eligibility across the region's fragmented compliance landscape.
| Leading Market Players |
|---|
| Oracle |
| Salesforce |
| Microsoft |
| Accenture |
| SAP |
| Amazon Web Services |
| IBM |
| Deloitte |
| Google Cloud |
| Others |
Value Chain & Pricing Dynamics
Captive cloud subsidiary formation by Saudi and UAE Tier-1 banks anchors both supply positioning and pricing power in MENA digital transformation markets. This vertical integration choice eliminates hyperscale markup layers while embedding compliance certification costs directly into internal cost structures.
Pricing Analysis
Outcome-based pricing tied to uptime guarantees and sovereign compliance certification dominates enterprise cloud procurement in the Gulf. Three-tier pricing structure across premium sovereign-grade, standard localized, and economy multi-tenant levels separates banking regulators from mid-market manufacturers. Cost compression in standard-tier services is intensifying because Egyptian and Saudi cloud providers compete on localization speed. Government buyers exhibit lowest price sensitivity due to mandate-driven procurement timelines.
Supply Chain Analysis
Regional distribution centers in Dubai Internet City and Riyadh's KAFD Tech Hub concentrate hyperscale hardware deployment for Gulf markets. Supply draws from semiconductor fabrication in Taiwan, server assembly in China, and cooling systems from Germany. Single-source vulnerability in AI accelerator chips threatens sovereign cloud buildout timelines. Distribution runs through systems integrator partnerships that bundle compliance certification with managed service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MENA digital transformation sits in a mainframe-to-cloud transition phase, with COBOL-based core banking systems yielding to API-first sovereign cloud architectures across Egyptian and Lebanese financial institutions.
For Market Incumbents: Anchor defensive positioning through captive cloud subsidiary expansion in Saudi Arabia and UAE to preempt hyperscale margin capture. Deepen compliance-as-a-service capabilities before Gulf regulators finalize algorithmic accountability codes. Prioritize zero-trust security certification investments to offset talent scarcity inflating project costs.
For New Entrants and Emerging Players: Launch via localized managed service partnerships targeting Cairo-based mid-market manufacturers below 15% cloud adoption. Concentrate first-mover advantages in Egyptian process automation where labor arbitrage still dominates cost structures. Differentiate through Arabic natural language processing capabilities for government contract eligibility.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale acquisition of regional compliance specialists with sovereign certification relationships. Long-term viability favors platform vendors with embedded banking regulator trust. Monitor Saudi Vision 2030 paperless mandate acceleration as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Zone Expansion | AWS, Microsoft, and Oracle compete for Saudi and UAE banking regulator licenses through dedicated in-country availability zones. |
| Compliance-as-a-Service Development | Platform vendors monetize Gulf algorithmic accountability drafts through pre-certified AI governance offerings. |
| Vertical Partnership Networks | Systems integrators bundle UAE Telecommunications and Digital Government Regulatory Authority certification with managed security operations. |
| Edge Computing Infrastructure | Oil operators in Kuwait and UAE deploy sub-50 millisecond latency systems for offshore predictive maintenance. |
| Blockchain-IoT Convergence | Dubai logistics corridors pilot integrated sensor and distributed ledger infrastructure for supply chain traceability. |
Study Parameters
Multi-period observation of hyperscale capex disclosures, sovereign cloud licensing timelines, and government digitization procurement anchored the trend analysis, supplemented by interviews with cloud infrastructure architects, banking regulator technology officers, systems integrator practice leads, and enterprise IT procurement directors. Secondary validation drew from SEC filings of listed hyperscalers, UAE Telecommunications and Digital Government Regulatory Authority public consultations, Saudi National Data Management Office policy releases, and Egyptian National Telecom Regulatory Authority certification databases. Bottom-up project pipeline tracking and top-down macroeconomic scenario weighting enabled triangulation across estimates.
Segment-weighting approaches applied differential growth assumptions across deployment models, end-user verticals, and technology layers throughout the forecast period. The analytical framework modeled hybrid cloud, private cloud, public cloud, and on-premises segments alongside BFSI, manufacturing, healthcare, and retail end users. CAGRs derived from regression against digitization spending intensity and regulatory mandate implementation schedules. Inputs included Saudi Vision 2030 target progression and UAE data classification framework adoption curves.
Regulatory mandate delays, sovereign AI governance code revisions, and cross-border data flow restriction changes are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around compliance timeline adherence and hyperscale localization investment commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Telco Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Contact Center Transformation Market