
 Retail Digital Transformation Market | 2026-2036
Retail Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Digital Transformation Market Outlook
Cloud infrastructure spending by North American retail technology vendors is consolidating as enterprise demand for unified commerce platforms intensifies. Amazon.com, Inc. leverages its AWS and logistics technology stack to dominate cloud-based retail infrastructure globally. SAP SE anchors European retail digitalization through its S/4HANA commerce modules and supply chain orchestration tools. Microsoft Corporation competes aggressively in the segment via Azure-powered retail analytics and Copilot integrations for workforce optimization.
Retail digital transformation encompasses the integration of cloud computing, artificial intelligence, Internet of Things sensors, and advanced data analytics into merchandising, supply chain, and customer engagement workflows, typically deployed through API-connected microservices architectures that enable real-time inventory visibility and personalized pricing. Its primary commercial purpose is to replace fragmented legacy retail IT stacks with interoperable systems that reduce stockouts, shrinkage, and labor costs while improving conversion rates across physical and digital touchpoints. Cloud Computing represents the foundational technology layer where margin pools are deepest due to recurring subscription economics and infrastructure lock-in effects. AI applications within personalization and demand forecasting are expanding fastest as retailers deploy generative models for dynamic pricing and automated customer service. Brick-and-Mortar end users are undergoing the most urgent retrofit cycle as they deploy IoT-enabled shelves and computer-vision checkout to defend foot traffic against pure-play e-commerce competitors.
The EU AI Act and GDPR impose strict algorithmic transparency and data minimization requirements on European retailers deploying automated decision-making for pricing and customer segmentation. In the United States, the FTC scrutinizes retail AI applications for discriminatory outcomes while state-level privacy laws in California and Virginia fragment compliance obligations. China's SAMR and GB standards govern cross-border data flows for multinational retailers operating localized e-commerce platforms. Stakeholders must monitor regulatory divergence between jurisdictions as data localization mandates and AI governance frameworks proliferate, since compliance architecture choices made today will constrain technology vendor selection and deployment flexibility for the next decade.
Market Dynamics
Fortune 500 retailers are dismantling legacy point-of-sale infrastructure and replacing it with API-connected microservices architectures that enable real-time inventory visibility across physical and digital touchpoints. This forced modernization is compressing vendor selection cycles and locking in cloud infrastructure commitments for the next decade.
Growth Catalysts
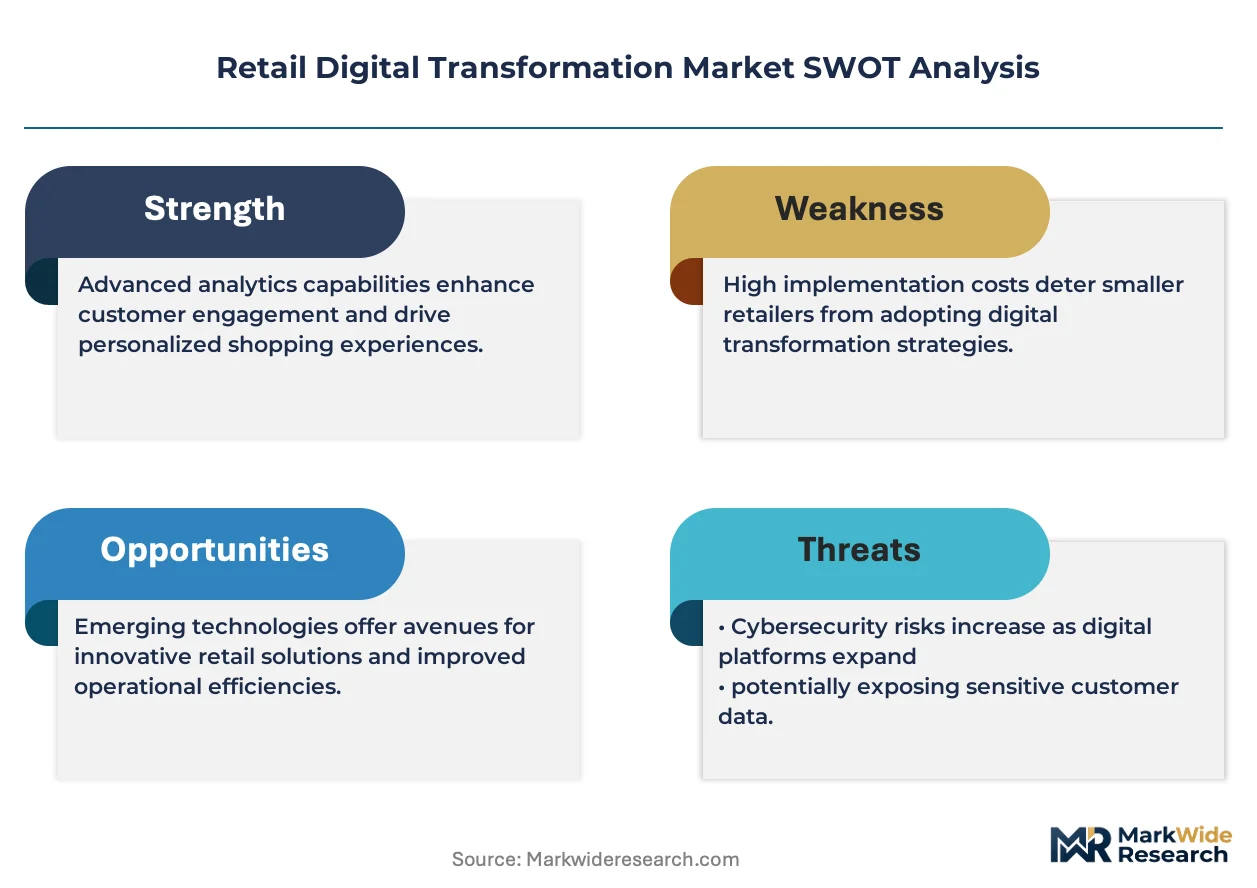
- EU AI Act compliance mandates:European retailers must restructure customer data architectures to meet algorithmic transparency requirements, creating immediate demand for governance tooling and audit-ready platforms.
- Computer-vision checkout deployment:Grocery chains and hypermarket operators are accelerating self-checkout investments to defend foot traffic against pure-play e-commerce competitors.
- Unified commerce platform consolidation:Enterprise demand for interoperable systems that reduce stockouts and shrinkage is pulling cloud infrastructure spending from fragmented legacy stacks.
Market Restraints
- GDPR data minimization requirements:Strict European data localization rules constrain cross-border data flows for multinational retailers operating localized e-commerce platforms.
- Technical debt in legacy POS systems:Decades-old on-premise infrastructure lacks API connectivity, forcing expensive rip-and-replace cycles before microservices architectures can deploy.
- Skill scarcity in AI/ML engineering:Retailers face acute shortages of talent capable of deploying generative models for dynamic pricing and automated customer service.
Strategic Opportunities
- IoT-enabled shelf deployment in the United States:Brick-and-mortar retrofit cycles present white space for sensor vendors serving Fortune 500 retailers modernizing legacy infrastructure.
- Convergence of edge computing and computer vision:Real-time inference at store level enables automated inventory tracking without cloud latency, opening new architecture categories.
- California Consumer Privacy Act expansion:State-level privacy law fragmentation creates demand for compliance platforms that span multiple US jurisdictions.
Industry Challenges
- Integration complexity with mainframe-era inventory systems:Retailers struggle to connect real-time microservices to batch-processed legacy databases without disrupting operations.
- Capex intensity of full-stack modernization:Simultaneous replacement of POS, supply chain orchestration, and customer data platforms strains capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Digital Transformation Market |
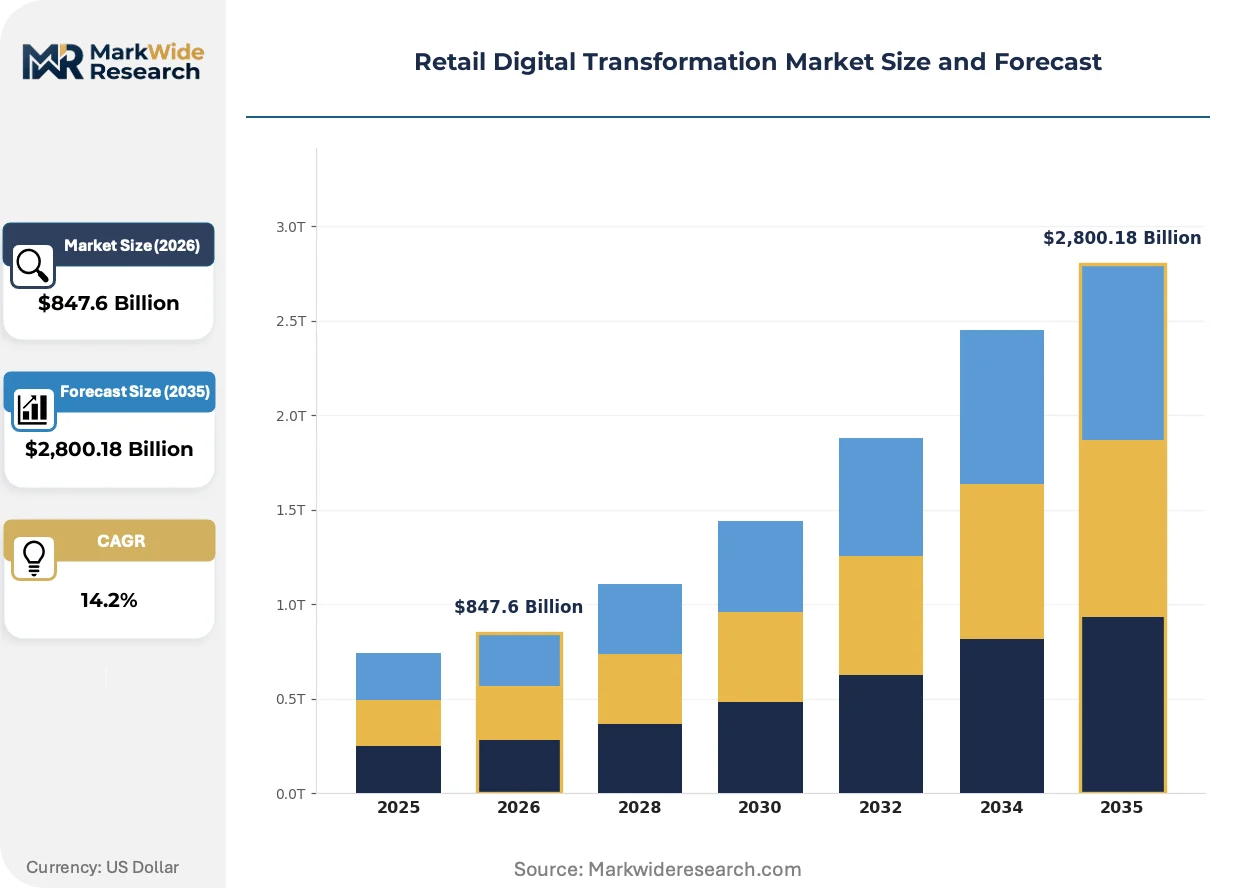
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Managed Services, Training Technology: Cloud Computing, AI, IoT, Big Data End User: E-Commerce, Brick-and-Mortar, Omni-Channel, Wholesalers Deployment: On-Premises, Cloud-Based, Hybrid, Others |
| Companies Covered | Amazon.com, Inc., SAP SE, Oracle Corporation, IBM Corporation, Microsoft Corporation, Salesforce Inc., Accenture plc, Walmart Inc., Alibaba Group Holding Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Digital Transformation Market Strategic Shifts
Generative AI applications are rewriting how retailers forecast demand and personalize pricing, while regulatory pressure on algorithmic decision-making forces simultaneous investment in explainability tooling. These parallel developments are compressing technology roadmaps and vendor consolidation timelines.
Generative AI for dynamic pricing operates by processing real-time competitor data, inventory levels, and customer segmentation signals to adjust prices automatically across channels. Mid-market apparel and electronics retailers are adopting these tools fastest, driven by margin pressure from pure-play competitors. This capability is expanding into automated customer service and demand forecasting, compressing the traditional software vendor landscape into unified platforms.
The EU AI Act imposes mandatory algorithmic impact assessments on automated pricing and customer segmentation systems deployed by European retailers. Retailers must now document training data provenance and decision logic for regulators, adding compliance overhead to AI deployments. Fashion and grocery segments in Germany and France are responding by embedding governance tooling directly into their cloud procurement specifications.
Buyer concentration among Fortune 500 retailers is forcing technology vendors to abandon point solutions in favor of full-stack platforms. Procurement teams now require unified commerce capabilities spanning POS, inventory, and customer data as table stakes, displacing best-of-breed vendors. This pattern is most visible in the United States, where legacy modernization budgets are consolidating around Amazon Web Services, Microsoft Azure, and SAP cloud offerings.
Retail Digital Transformation Market Segmentation
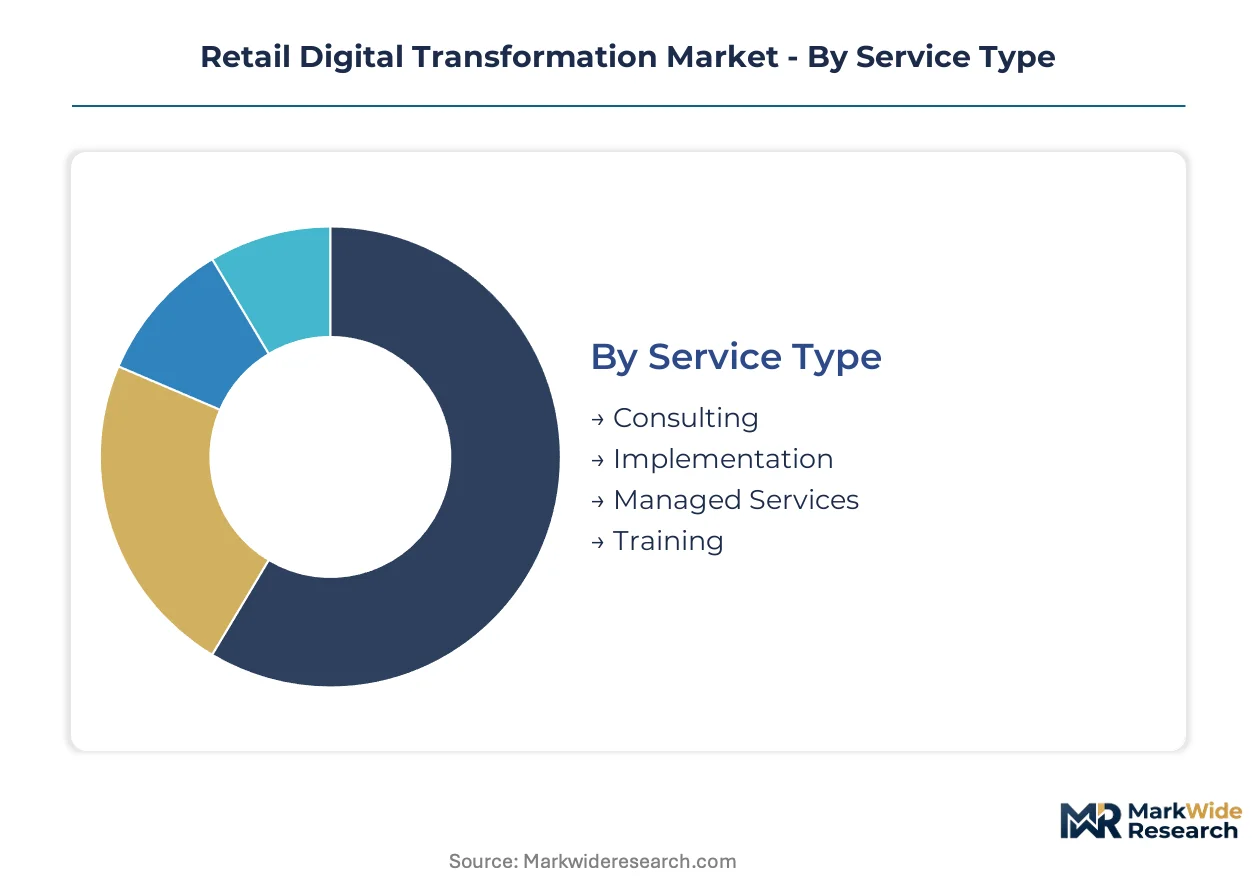
Retail digital transformation projects require precise alignment between service capabilities, technology infrastructure, and operational maturity. Segmentation reveals where capital concentrates and which deployment patterns lock in multi-year vendor relationships.
Service Type:
Technology specification and integration complexity determine which service tiers capture the largest contract values.
- Consulting:Strategic assessment of legacy POS architectures and cloud migration roadmaps dominates Fortune 500 procurement cycles. Retailers in the United States pay premium rates for regulatory compliance planning around FTC algorithmic scrutiny and state privacy fragmentation.
- Implementation:System integration services connect API microservices to mainframe-era inventory databases without operational disruption. Demand clusters among grocery chains and hypermarket operators accelerating self-checkout deployment to defend foot traffic.
- Managed Services:Ongoing infrastructure monitoring and security patching for hybrid cloud environments.
- Training:Workforce upskilling programs addressing acute AI/ML engineering scarcity in retail technology teams.
Mature deployment sits with Consulting. Newer deployment is concentrated in Implementation.
Technology:
Cost tier and margin pool depth separate foundational infrastructure from application-layer investments.
- Cloud Computing:Foundational infrastructure layer delivering recurring subscription economics and vendor lock-in effects. Amazon Web Services, Microsoft Azure, and SAP cloud offerings capture the bulk of Fortune 500 modernization budgets in the United States.
- AI:Generative models for dynamic pricing and automated customer service are expanding most quickly as retailers deploy algorithmic decision-making systems. EU AI Act compliance mandates force simultaneous investment in explainability tooling and governance platforms.
- IoT:Sensor networks enabling real-time inventory visibility and computer-vision checkout systems.
- Big Data:Analytics platforms processing customer segmentation signals and demand forecasting workloads.
Revenue concentration favors Cloud Computing. Steepest expansion trajectory belongs to AI.
End User:
Application urgency and competitive pressure intensity vary sharply across retail operational models.
- Brick-and-Mortar:Physical retailers undergoing the most urgent retrofit cycle as they deploy IoT-enabled shelves and computer-vision checkout. Grocery chains and hypermarket operators in the United States drive self-checkout automation investments to defend foot traffic against pure-play e-commerce competitors.
- Omni-Channel:Unified commerce platforms integrating POS, inventory, and customer data across physical and digital touchpoints. Procurement teams now require interoperable capabilities as table stakes, displacing fragmented legacy stacks.
- E-Commerce:Pure-play digital retailers optimizing cloud-native architectures and personalization engines.
- Wholesalers:B2B distributors modernizing supply chain orchestration and demand forecasting systems.
Capital deployment intensity peaks with Brick-and-Mortar. Technology sophistication leadership sits with Omni-Channel.
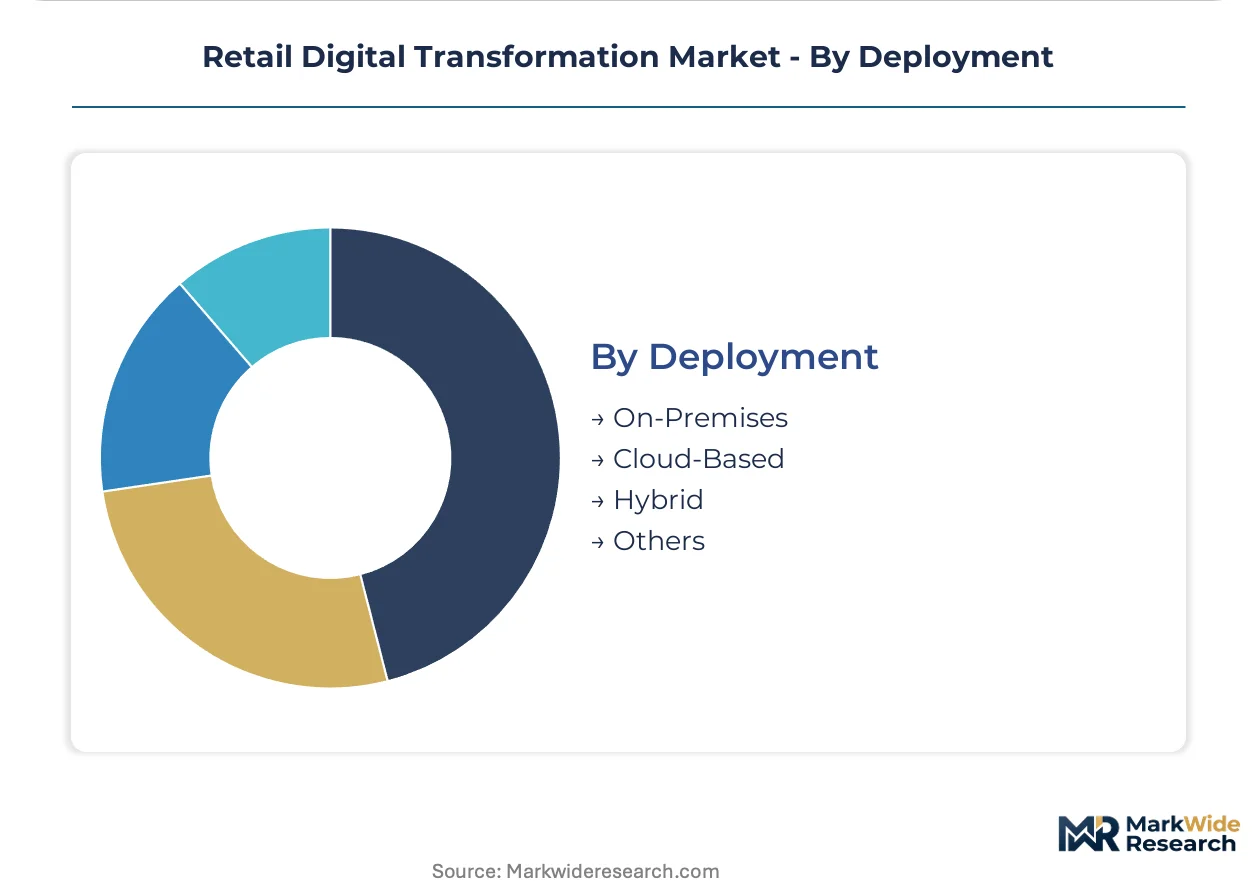
Deployment:
Customer type and data sovereignty requirements shape architecture choices across regulatory jurisdictions.
- Cloud-Based:Fully managed infrastructure eliminating on-premise maintenance burdens and enabling elastic scaling. GDPR data minimization requirements and EU AI Act algorithmic transparency mandates force European retailers to select audit-ready cloud platforms with embedded governance tooling.
- Hybrid:Split architectures preserving sensitive customer data on-premise while leveraging cloud compute for analytics workloads. China's SAMR and GB standards governing cross-border data flows push multinational retailers toward localized deployment models.
- On-Premises:Legacy data center retention for retailers with strict data localization requirements or technical debt constraints.
- Others:Edge computing deployments enabling real-time inference at store level without cloud latency.
Vendor consolidation momentum favors Cloud-Based. Regulatory complexity is driving Hybrid adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments in retail technology concentrate where Fortune 500 headquarters and legacy POS modernization budgets cluster. The United States, Germany, China, United Kingdom, and Japan anchor deployment velocity through distinct regulatory and competitive pressures.
United States
Fortune 500 retailers headquartered in Chicago, Minneapolis, and Bentonville drive self-checkout automation and IoT-enabled shelf deployments. FTC algorithmic scrutiny and California Consumer Privacy Act fragmentation force compliance architecture investments. The Pacific Northwest technology corridor supplies cloud infrastructure and workforce optimization platforms to national retail chains.
Germany
EU AI Act mandates reshape customer data architectures for grocery chains and fashion retailers operating across Düsseldorf and Hamburg. Algorithmic transparency requirements for automated pricing create immediate demand for governance tooling embedded in cloud procurement. Bavaria's industrial automation cluster feeds computer-vision checkout system deployments.
China
SAMR cross-border data flow regulations and GB standards push multinational retailers toward localized e-commerce platforms in Shanghai and Shenzhen. Domestic retail conglomerates accelerate unified commerce investments to defend against pure-play competitors. The Yangtze River Delta concentration of logistics technology vendors enables edge computing convergence with computer vision.
United Kingdom
GDPR data minimization requirements constrain customer segmentation AI deployments for London-based omnichannel retailers. Post-Brexit regulatory divergence from EU frameworks complicates compliance for chains operating across both jurisdictions. The Southeast England technology corridor supplies managed services for hybrid cloud environments.
Japan
METI digital transformation subsidies support convenience store chains and department stores modernizing legacy POS infrastructure in Tokyo and Osaka. Aging workforce demographics accelerate demand forecasting automation and workforce optimization platforms. The Kanto region concentration of systems integrators enables API microservices deployment without operational disruption.
Retail Digital Transformation Market Competitive Environment
Global majors compete with regional champions across cloud infrastructure and specialized retail applications, producing a tiered structure where hyperscalers capture foundational workloads while vertical specialists defend niche segments. The vendor base organizes around three archetypes: hyperscale cloud providers with retail-specific modules, enterprise software incumbents with commerce platforms, and systems integrators managing legacy modernization. M&A activity concentrates on AI governance tooling acquisitions, while strategic partnerships between cloud providers and retail technology vendors accelerate unified platform consolidation.
Within the hyperscale tier, Amazon.com, Inc. and Microsoft Corporation occupy positions as anchors for cloud-based retail infrastructure deployment, with SAP SE representing the European enterprise software archetype through its S/4HANA commerce modules. These three exemplify the platform consolidation pattern where procurement teams now require interoperable POS, inventory, and customer data capabilities as table stakes, displacing fragmented best-of-breed vendors.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Salesforce Inc. |
| Accenture plc |
| Walmart Inc. |
| Alibaba Group Holding Limited |
| Others |
Value Chain & Pricing Dynamics
Platform-completeness divergence between hyperscale cloud vendors and point-solution specialists manifests in both subscription pricing structures and supply chain configurations. Premium-tier unified commerce platforms bundle implementation services and ongoing governance tooling, while commodity SaaS offerings unbundle professional services and push integration costs onto retailers.
Pricing Analysis
Warranty and service-bundling arrangements separate enterprise-grade cloud infrastructure contracts from self-managed deployments. Subscription SaaS-tiered pricing dominates, with differentiation driven by API call volume tiers and embedded AI governance certification levels. Pricing pressure stems from Fortune 500 procurement teams consolidating vendor relationships and demanding volume discounts for multi-year commitments. Mid-market retailers exhibit highest price sensitivity, while hyperscale grocery chains prioritize platform completeness over unit cost.
Supply Chain Analysis
Freight and logistics costs for edge-computing hardware shipments from Taiwan, South Korea, and China feed into total cost of ownership calculations for IoT-enabled shelf deployments. Semiconductor components for computer-vision systems and cloud data center equipment draw from concentrated East Asian manufacturing hubs. Single-source vulnerability in advanced GPU supply for AI training workloads constrains deployment timelines. Distribution runs through systems integrator partnerships rather than direct vendor-to-retailer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure capacity for retail workloads concentrates among three hyperscalers, creating supply-constrained pricing power that favors incumbent platform vendors with reserved instance commitments.
For Market Incumbents: Cement platform lock-in through multi-year enterprise agreements that bundle edge hardware, cloud compute, and compliance tooling into unified procurement contracts. Defend against emerging vertical AI specialists by embedding EU AI Act governance modules directly into S/4HANA and Azure retail offerings. Prioritize capacity expansion in Germany and Japan to capture regional data localization demand.
For New Entrants and Emerging Players: Regional systems integrators in Southeast Asia represent the most penetrable channel partner type for specialized computer-vision checkout vendors. Target white space in hybrid cloud managed services for UK retailers navigating post-Brexit regulatory divergence. Pursue co-sell arrangements with Microsoft Azure marketplace to bypass direct enterprise sales cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with AI governance tooling specialists given EU AI Act enforcement timelines accelerating enterprise procurement. Long-term viability hinges on embedding explainability capabilities into cloud-native architectures rather than standalone compliance products. Acquisition target archetype: vertical-specific demand forecasting platforms with Fortune 500 proof points. Monitor FTC algorithmic scrutiny intensity as inflection signal for US compliance spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies POS, inventory, and customer data layers into single vendor relationship. |
| Acquisition of Specialist Firm | Captures AI governance capabilities required for EU AI Act compliance mandates. |
| Strategic Partnership | Links hyperscaler cloud infrastructure with regional systems integrator implementation capacity. |
| Geographic Expansion | Establishes localized data centers in China to satisfy SAMR cross-border restrictions. |
| Product Launch | Introduces edge-computing inference hardware reducing cloud latency for real-time inventory tracking. |
Study Parameters
Multi-period observation of cloud infrastructure capex disclosures, retail technology procurement announcements, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with CTOs at Fortune 500 retailers, cloud platform engineers, systems integrator practice leads, and compliance officers navigating EU AI Act implementation. Secondary validation drew from SEC 10-K filings of publicly traded retail technology vendors, hyperscaler earnings call transcripts, EMA and FDA regulatory databases for AI-enabled medical retail applications, and customs trade data for edge hardware imports. Bottom-up project pipeline tracking triangulated against top-down market sizing from cloud provider revenue segment disclosures.
Input-output matrices modeled deployment velocity across service type, technology layer, end-user operational model, and deployment architecture dimensions over the projection horizon. CAGRs derived from regression analysis of historical cloud spending patterns against retail revenue growth correlations, incorporating AI adoption curve assumptions and regulatory compliance cost burden estimates. Forecast inputs included workforce automation substitution rates and data localization mandate expansion scenarios.
Several conditions sit outside the modeled scope, including sovereign debt crises triggering enterprise IT budget freezes, breakthrough quantum computing disruptions rendering current encryption architectures obsolete, and geopolitical conflict severing Taiwan semiconductor supply lines. Forecasts reflect documented assumptions about regulatory enforcement intensity and vendor consolidation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Digital Transformation Market