
 DECT System Market | 2026-2036
DECT System Market Size, Share, and Industry Trends Forecast 2026-2036
DECT System Market Analysis
Enterprise distribution channels for cordless voice hardware are reshaping as direct-to-healthcare procurement models gain ground. Panasonic leverages its manufacturing scale to sustain dominance in base station supply chains across Asian markets. Yealink competes through VoIP adaptor specialization, while Spectralink Corporation anchors its position in multi-cell systems for hospital environments.
A DECT system comprises digitally enhanced cordless telecommunications equipment operating in the 1.88–1.90 GHz frequency band, employing time division multiple access and Gaussian frequency shift keying modulation to deliver secure, low-latency voice transmission for commercial and residential applications. Cordless phones retain the largest installed base among product types, though business phones command stronger margin pools in enterprise renewals. Multi-cell technology leads growth trajectories as facilities replace single-cell coverage with seamless handover capabilities across sprawling campuses. Healthcare facilities represent the fastest-expanding end user category, driven by nurse call integration and clinical mobility requirements.
The European Telecommunications Standards Institute governs DECT protocol evolution, while the FCC regulates spectrum access and device certification in the United States, and Japan's Ministry of Internal Affairs and Communications oversees 1.9 GHz licensing frameworks. ETSI's DECT-2020 NR standard introduces 5G IoT compatibility, compelling manufacturers to redesign chipset architectures for dual-mode operation. Stakeholders must weigh spectrum reallocation risks against the upgrade revenue potential of software-defined base stations.
Market Dynamics
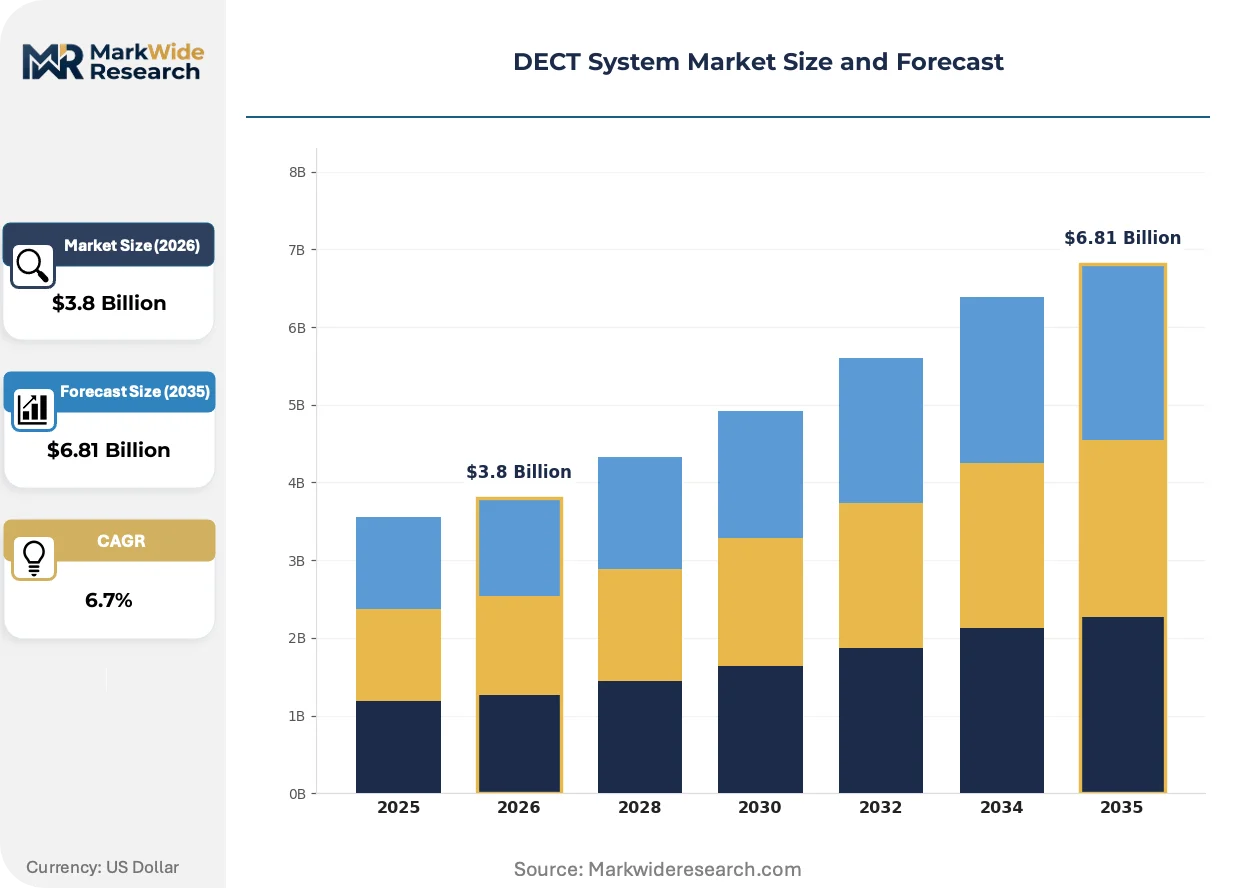
The DECT System Market is restructuring around the ETSI DECT-2020 NR standard, which forces chipset redesigns and creates divergence between legacy single-cell installations and 5G-IoT-ready multi-cell architectures across healthcare and industrial campuses.
Growth Catalysts
- ETSI DECT-2020 NR Mandate:The European standard compels manufacturers toward dual-mode base stations, opening upgrade cycles in German hospital networks and Nordic industrial facilities.
- Nurse Call Integration Demand:Clinical mobility requirements in United States acute care hospitals are replacing aging PBX infrastructure with cordless voice systems that synchronize with patient monitoring alerts.
- Japan 1.9 GHz Spectrum Refarming:The Ministry of Internal Affairs and Communications is reallocating bands to prioritize mission-critical voice, accelerating licensed DECT deployments over unlicensed alternatives in Tokyo medical centers.
Market Restraints
- GaAs and Silicon Germanium Input Volatility:RF front-end component costs fluctuate with compound semiconductor foundry capacity concentrated in Taiwan and South Korea.
- Single-Cell Base Station Obsolescence:Legacy hardware stockpiles in Eastern European secondary markets create pricing pressure on new multi-cell system sales.
- Wi-Fi 6E Voice Substitution:Hospital IT departments in United States health systems are piloting converged data-voice networks that bypass dedicated cordless infrastructure.
Strategic Opportunities
- Indian Healthcare Infrastructure:The country's national medical device regulator is streamlining 1.9 GHz equipment approvals, creating first-mover advantage for enterprise-grade multi-cell deployments in private hospital chains.
- Industrial IoT Convergence:DECT-2020 NR's 5G compatibility enables sensor backhaul integration, positioning base stations as dual-purpose voice and telemetry hubs in German automotive manufacturing plants.
- Direct-to-Facility Procurement Channels:Group purchasing organizations in United States hospital networks are consolidating vendor lists, rewarding manufacturers with integrated nurse call interoperability.
Industry Challenges
- DECT-2020 NR Certification Timelines:ETSI compliance testing for dual-mode chipsets extends product development cycles by 8-14 months, compressing margin windows for mid-tier manufacturers.
- RF Engineer Talent Scarcity:Gaussian frequency shift keying optimization and time-division multiple access protocol expertise concentrates among legacy telecom specialists nearing retirement in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DECT System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
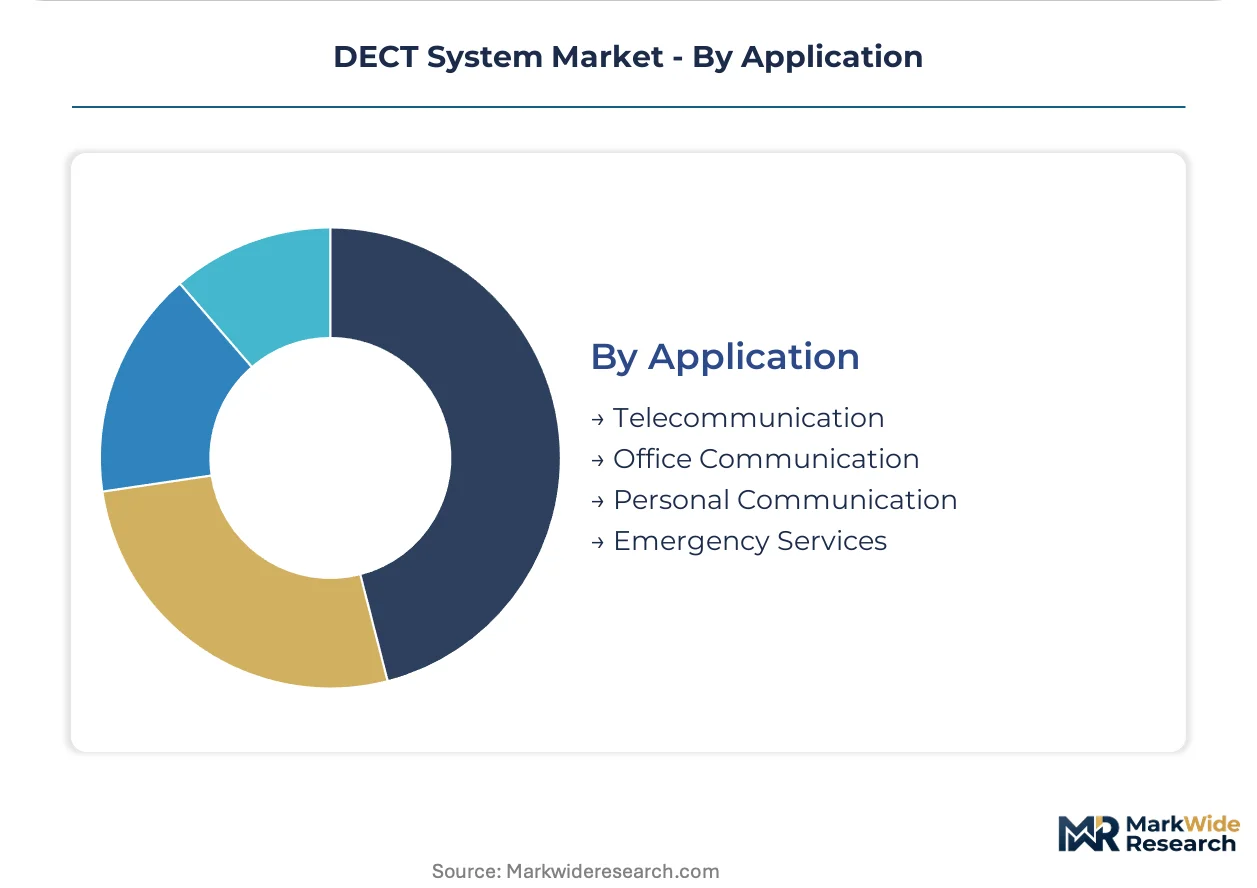
| Segmentation | Product Type: Business Phones, Cordless Phones, VoIP Adaptors, Base Stations End User: Residential, Small Office/Home Office, Enterprises, Healthcare Facilities Technology: Single Cell, Multi-Cell, Handset, Access Point Application: Telecommunication, Office Communication, Personal Communication, Emergency Services |
| Companies Covered | Uniden, Motorola, Panasonic, Yealink, Spectralink Corporation, Gigaset, Philips, Grandstream Networks, VTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DECT System Market Emerging Trajectories
Base station architectures are bifurcating as software-defined radios displace fixed-function hardware, while spectrum policy divergence between regulatory jurisdictions fragments product roadmaps.
Multi-cell seamless handover technology is migrating from proprietary implementations toward standardized DECT-2020 NR protocols. German industrial campuses and United States hospital networks are adopting these systems at replacement-cycle pace. The technology is migrating from single-cell coverage islands toward campus-wide mobility fabrics that eliminate dead zones in sprawling facilities.
Japan's Ministry of Internal Affairs and Communications is tightening 1.9 GHz licensing frameworks to prioritize licensed over unlicensed operation. This industrial consequence elevates hardware certification burdens while excluding low-cost consumer-grade imports. Medical device manufacturers in Tokyo and Osaka are responding by pre-integrating DECT modules into nurse call systems prior to domestic market entry.
Healthcare procurement departments are consolidating vendor relationships around integrated voice-alert platforms. United States group purchasing organizations are displacing standalone cordless phone contracts with multi-system agreements bundling base stations, handsets, and nurse call middleware. This concentration is most visible in Southeastern and Midwestern hospital networks where facility consolidation has reduced independent purchasing authority.
DECT System Market Segmentation

DECT system procurement patterns diverge sharply across deployment scales, from single-handset residential installations to campus-wide healthcare networks requiring seamless handover. Segment boundaries reflect fundamental trade-offs between hardware cost, spectrum licensing, and integration complexity.
Product Type:
Deployment scenarios span home offices requiring basic cordless handsets to German automotive plants demanding ruggedized multi-cell infrastructure.
- Business Phones:Enterprise-grade handsets integrate nurse call middleware and support encrypted voice protocols for United States hospital networks. Margin concentration in healthcare renewals drives manufacturer R&D toward clinical interoperability certification.
- Cordless Phones:Consumer and SOHO devices dominate unit volumes across residential markets in Japan and Germany. ETSI DECT-2020 NR compliance timelines are compressing refresh cycles as legacy single-cell stock depreciates.
- VoIP Adaptors:Bridge hardware enables PBX migration without full infrastructure replacement.
- Base Stations:Multi-cell controllers anchor campus deployments with seamless handover capabilities.
The dominant share belongs to Cordless Phones, while Business Phones is closing the gap fastest.
End User:
Customer archetypes range from price-sensitive residential buyers to procurement committees managing million-dollar healthcare infrastructure tenders.
- Residential:Single-cell cordless systems serve home voice needs with minimal configuration. Japanese regulators are tightening 1.9 GHz licensing to exclude unlicensed consumer imports from Tokyo and Osaka markets.
- Small Office/Home Office:Hybrid VoIP-cordless setups bridge legacy PSTN and IP networks. Cost pressure from Wi-Fi 6E voice alternatives is narrowing hardware margins in United States micro-business segments.
- Enterprises:Campus-wide multi-cell deployments dominate Nordic industrial facilities and North American corporate headquarters. Procurement through group purchasing organizations is consolidating vendor relationships around integrated platforms.
- Healthcare Facilities:Nurse call synchronization and clinical mobility requirements are displacing aging PBX infrastructure in German hospital networks and United States acute care systems. FCC Part 15 compliance and HIPAA voice security mandates elevate certification burdens.
Healthcare Facilities command the steepest expansion trajectory, though Residential retains the largest installed base.
Technology:
Architecture choices determine coverage topology, handover capability, and backward compatibility with legacy spectrum allocations.
- Single Cell:Standalone base stations serve isolated coverage zones with no inter-cell coordination. Eastern European secondary markets are liquidating obsolete hardware inventories, pressuring new equipment pricing.
- Multi-Cell:Seamless handover fabrics eliminate dead zones across sprawling campuses. German industrial facilities and United States hospital networks are adopting these systems at replacement-cycle pace, driven by ETSI DECT-2020 NR protocol standardization.
- Handset:Endpoints range from basic cordless units to clinical-grade devices with antimicrobial housings.
- Access Point:Distributed radio units extend coverage density in high-interference environments.
Multi-Cell is gaining share fastest, while Single Cell remains entrenched in legacy residential installations.
Application:
Functional requirements vary from basic voice connectivity to mission-critical emergency response with regulatory-grade reliability.
- Telecommunication:Carrier-grade infrastructure supports PSTN interconnection and VoIP trunking for service providers. Japan's Ministry of Internal Affairs and Communications is prioritizing licensed DECT for mission-critical voice over unlicensed alternatives.
- Office Communication:Enterprise PBX replacement drives cordless voice adoption in German and United States commercial real estate. Integration with unified communications platforms is becoming a procurement prerequisite.
- Personal Communication:Residential voice remains the default use case, though smartphone substitution is eroding growth in mature markets.
- Emergency Services:Ruggedized handsets with location tracking serve first responder and hospital code teams. FCC certification for public safety spectrum compatibility adds development cost and timeline risk.
Telecommunication holds the dominant position, while Emergency Services is expanding most quickly on regulatory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's digital logistics corridor underwrites Germany's central role in European DECT infrastructure deployment, connecting industrial automation clusters to North Sea shipping lanes.
United States
Acute care hospital networks in the Southeast and Midwest are consolidating cordless voice procurement through group purchasing organizations. FCC Part 15 certification requirements for 1.9 GHz equipment elevate compliance costs for new market entrants. The Dallas-Fort Worth medical corridor hosts multi-cell deployment pilots integrating nurse call middleware with clinical mobility platforms.
Germany
Automotive manufacturing plants in Bavaria and Baden-Württemberg demand ruggedized multi-cell systems for factory-floor voice coordination. ETSI DECT-2020 NR mandates compel base station manufacturers toward dual-mode chipset architectures. Stuttgart's industrial automation cluster drives replacement cycles as legacy single-cell infrastructure reaches end-of-life.
Japan
Tokyo and Osaka medical centers prioritize licensed DECT deployments following Ministry of Internal Affairs and Communications spectrum refarming initiatives. The 1.9 GHz band reallocation favors mission-critical voice applications over unlicensed consumer alternatives. Yokohama's medical device manufacturing corridor is pre-integrating DECT modules into nurse call systems for domestic market entry.
India
Private hospital chains in Maharashtra and Karnataka are expanding wireless voice infrastructure as national medical device regulators streamline 1.9 GHz equipment approvals. CDSCO certification pathways for cordless telecommunications hardware are reducing time-to-market for enterprise-grade suppliers. Mumbai's healthcare procurement hubs are consolidating vendor relationships around integrated clinical mobility platforms.
United Kingdom
NHS trust procurement frameworks are evaluating multi-cell DECT replacements for aging PBX systems in London and Birmingham hospital networks. Ofcom spectrum management consultations are shaping 1.9 GHz licensing terms for healthcare applications. The Cambridge-Oxford medical technology corridor is piloting DECT-2020 NR interoperability with existing telemetry infrastructure.
DECT System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF front-end modules and baseband processors. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with manufacturing scale, VoIP-specialized communication equipment firms, and clinical mobility pure-plays focused on healthcare certification. Competitive positioning hardens through vertical integration into semiconductor sourcing and strategic partnerships with nurse call middleware providers.
Among diversified electronics manufacturers, Panasonic and VTech exemplify scale-driven platform integrators with broad cordless phone portfolios. Yealink and Grandstream Networks represent the VoIP-specialized tier bridging legacy PBX migration toward IP-native architectures. Spectralink Corporation occupies a distinct position within clinical mobility, anchoring multi-cell system deployment for United States hospital environments. Motorola and Uniden sit within consumer and SOHO segments, while Gigaset and Philips maintain European market presence through ETSI-aligned product roadmaps.
| Leading Market Players |
|---|
| Uniden |
| Motorola |
| Panasonic |
| Yealink |
| Spectralink Corporation |
| Gigaset |
| Philips |
| Grandstream Networks |
| VTech |
| Others |
Supply Flow & Price Mechanics
Compound semiconductor foundry capacity concentrated in Taiwan and South Korea anchors RF front-end component costs, feeding margin compression downstream into base station manufacturing while enterprise-grade multi-cell deployments in German hospital networks capture the steepest pricing premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market, with ETSI DECT-2020 NR certification tier and enterprise volume scale serving as the primary price differentiation drivers. Cost compression in economy-tier cordless phones is intensifying because Wi-Fi 6E voice alternatives are narrowing hardware margins. Healthcare procurement committees exhibit the least price sensitivity due to nurse call integration mandates, while residential buyers in Japanese markets face tightening budget constraints.
Supply Chain Analysis
Foxconn, Jabil, and Pegatron hold dominant contract-manufacturing capacity for DECT base station assembly, with production concentrated in China, Vietnam, and Mexico. GaAs substrates, silicon germanium wafers, and ceramic filter components feed from specialized foundries in Taiwan and Japan. Single-source vulnerability in compound semiconductor supply creates structural risk for RF front-end module availability. Distribution runs through enterprise IT distributors and direct-to-facility procurement channels serving United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gaussian frequency shift keying optimization expertise concentrates among legacy telecom specialists nearing retirement in Germany and Japan, creating a capability gap that threatens multi-cell system development timelines for mid-tier manufacturers.
For Market Incumbents: Insulate market position by securing captive supply of RF front-end components through backward integration into compound semiconductor sourcing, and accelerate ETSI DECT-2020 NR certification investment to outpace Wi-Fi 6E voice substitution threats in United States health systems. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Indian private hospital chains in Maharashtra and Karnataka offering secondary white-space opportunity. A VoIP adaptor specialization strategy enables PBX migration service bundling without full infrastructure replacement investment. For Investors and Strategic Acquirers: Capital is best deployed toward clinical mobility pure-plays with established nurse call middleware partnerships and existing FCC Part 15 certification portfolios. Long-term viability hinges on software-defined radio architecture transition capability. Watch for ETSI compliance timeline compression as an inflection indicator signaling margin pressure on hardware-centric competitors.| Strategic Initiative | Industry Significance |
|---|---|
| DECT-2020 NR Certification Investment | ETSI compliance enables dual-mode base station sales into German automotive and Nordic industrial replacement cycles. |
| Nurse Call Middleware Partnership | United States GPO vendor consolidation rewards integrated voice-alert platform suppliers with preferred contracting status. |
| Compound Semiconductor Backward Integration | Captive GaAs and silicon germanium supply insulates margins against Taiwan and South Korea foundry capacity constraints. |
| Direct-to-Facility Procurement Channel | Bypassing traditional distributors captures margin from United States hospital network consolidation and vendor list rationalization. |
| Software-Defined Radio Architecture Transition | Displacement of fixed-function hardware enables firmware-upgrade revenue streams and reduces chipset redesign cycle burden. |
Methodological Framework
Operator-level perspectives from base station procurement managers, biomedical engineers, GPO contracts managers, and RF front-end component sourcing directors anchored the qualitative base. Primary fieldwork combined with secondary validation against ETSI technical specifications, FCC Part 15 device certifications, CDSCO medical device registration databases, and customs import records for 1.9 GHz equipment. Bottom-up deployment tracking across German automotive plants and United States hospital networks triangulated against top-down manufacturer revenue analysis.
Scenario-bracketing around ETSI DECT-2020 NR adoption pace, Wi-Fi 6E voice substitution intensity, and compound semiconductor supply disruption probability structured the analytical framework across the analysis window. Segmentation modeling incorporated product type, end user archetype, technology architecture, and regional regulatory cluster dimensions. CAGRs derived from replacement-cycle timing in Nordic industrial facilities and United States acute care systems, with nurse call integration penetration and spectrum refarming policy velocity as industry-specific forecast inputs.
Practitioners should monitor ETSI certification timeline extensions, Japan Ministry of Internal Affairs and Communications spectrum reallocation announcements, and Taiwan foundry capacity utilization for early signals of forecast revision necessity. Quarterly review of United States GPO vendor list changes and German hospital network procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Global IP Phone Market
Telecommunications
Global Esim Market
Telecommunications
Denmark ICT Market
Telecommunications
Italy Telecom Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Medical 5G Market
Telecommunications
IP PBX Market
Telecommunications
Global Broadband Services Market
Telecommunications
DWDM System Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
IP Telephony Market
Telecommunications
Asia-Pacific IPTV Market