
 Digital Transformation Consulting Market | 2026-2036
Digital Transformation Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation Consulting Market Analysis
Generative AI integration into enterprise software stacks is reshaping how organizations redesign customer-facing workflows and internal operations. Accenture leverages its pre-built industry cloud accelerators to compress deployment timelines for clients in regulated sectors. Deloitte Digital sustains competitive separation through deep vertical expertise in financial services compliance architecture. McKinsey & Company anchors its positioning in board-level strategy work that links technology roadmaps to capital allocation decisions.
Digital transformation consulting encompasses advisory and implementation services that align organizational processes, technology infrastructure, and workforce capabilities with digitally enabled business models, typically delivered through phased engagement structures spanning diagnostic assessment, solution design, and change management. The primary commercial purpose centers on reducing operational friction, unlocking data monetization pathways, and building adaptive enterprise architectures that withstand competitive disruption. Cloud Computing services within the technology segment dominate current revenue pools as enterprises migrate legacy workloads, while Artificial Intelligence consulting represents the fastest-expanding margin pool as clients seek production deployment beyond pilot programs. Process Optimization across the service type dimension remains structurally mature with compressed pricing, whereas IT Transformation engagements command premium fees due to scarce systems integration talent.
FDA scrutiny of AI-enabled diagnostic tools in healthcare is elevating demand for compliance-integrated implementation consulting among U.S. providers. The EU AI Act and GDPR jointly shape procurement specifications for European clients, requiring algorithmic transparency documentation and data governance architecture as deliverable components. ISO standards for information security management increasingly gate market access for boutique consultancies serving multinational accounts. Stakeholders must monitor whether regulatory fragmentation between jurisdictions forces duplication of compliance investment or creates arbitrage opportunities for firms with cross-border certification depth.
Market Dynamics
Generative AI integration is collapsing traditional project timelines across enterprise software implementations, forcing consultancies to restructure delivery models and talent deployment around compressed value realization cycles.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are compelling European enterprises to procure integrated governance and implementation services rather than point solutions.
- Cloud migration tailwinds:Healthcare providers are accelerating adoption of cloud-based patient management systems, creating sustained demand for security-architecture consulting.
- German industrial automation:Manufacturing investments in predictive maintenance and digital twins are reshaping procurement patterns toward multi-year transformation partnerships.
Market Restraints
- Scarce systems integration talent:Premium fees for IT Transformation engagements reflect acute shortages of architects capable of bridging legacy and cloud-native environments.
- Regulatory fragmentation:Divergent FDA and EMA pathways for AI-enabled diagnostic tools force duplication of compliance investment for multinational healthcare clients.
- Compressed Process Optimization pricing:Mature service categories face margin erosion as automation tools commoditize workflow analysis deliverables.
Strategic Opportunities
- Production deployment gap:Clients seek consulting partners capable of moving AI pilots into operational environments, representing expansion beyond advisory into managed outcomes.
- Data monetization architecture:Enterprises require guidance on compliant data product development, combining GDPR governance with revenue model design.
- ISO 27001 certification depth:Boutique consultancies with cross-border information security credentials can arbitrage multinational compliance requirements.
Industry Challenges
- Change management execution:Workforce capability building lags technology deployment, creating adoption failures that damage consulting firm reputations.
- Algorithmic audit capacity:Shortage of professionals trained in explainable AI and bias detection constrains delivery of EU AI Act-compliant documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation Consulting Market |
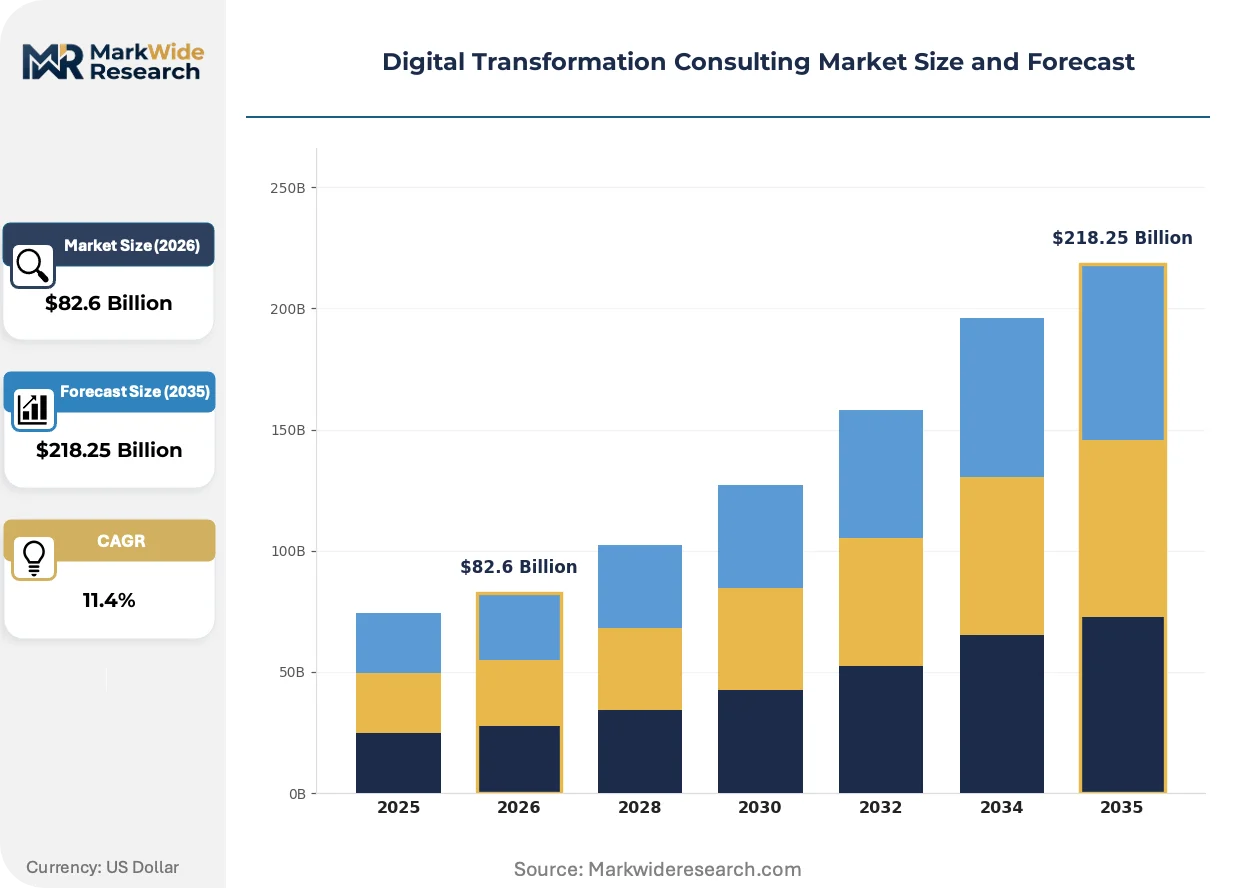
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $218.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, IT Transformation, Process Optimization, Change Management End User: Large Enterprises, SMEs, Government Agencies, Non-profits Technology: Cloud Computing, Artificial Intelligence, Data Analytics, IoT Industry Vertical: Financial Services, Healthcare, Retail, Telecommunications |
| Companies Covered | Accenture, Deloitte Digital, IBM Consulting, McKinsey & Company, Boston Consulting Group, Capgemini, PwC, Cognizant, Bain & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation Consulting Market Emerging Trajectories
Advisory delivery models are fragmenting as clients demand measurable outcomes rather than roadmap documents, compressing the traditional diagnostic-to-implementation cycle and elevating partners with pre-built accelerators.
Generative AI code generation is collapsing software development timelines for enterprise workflow redesign. Financial services institutions are deploying these tools for customer-facing process automation at accelerated pace. The structural consequence is elimination of lengthy build phases, forcing consultancies to shift revenue toward integration and governance services.
The EU AI Act risk classification framework is mandating conformity assessments for high-risk algorithmic systems. Healthcare and financial services procurement specifications now embed transparency documentation as non-negotiable deliverables. German and French enterprises are front-loading compliance architecture spend to preempt enforcement action.
Enterprise buyers are unbundling strategy and implementation, awarding diagnostic work to strategy boutiques while contracting systems integration to technology specialists. The traditional full-service model faces disintermediation. Healthcare providers in the United States demonstrate this most visibly, separating FDA pathway consulting from EHR deployment.
Digital Transformation Consulting Market Segmentation
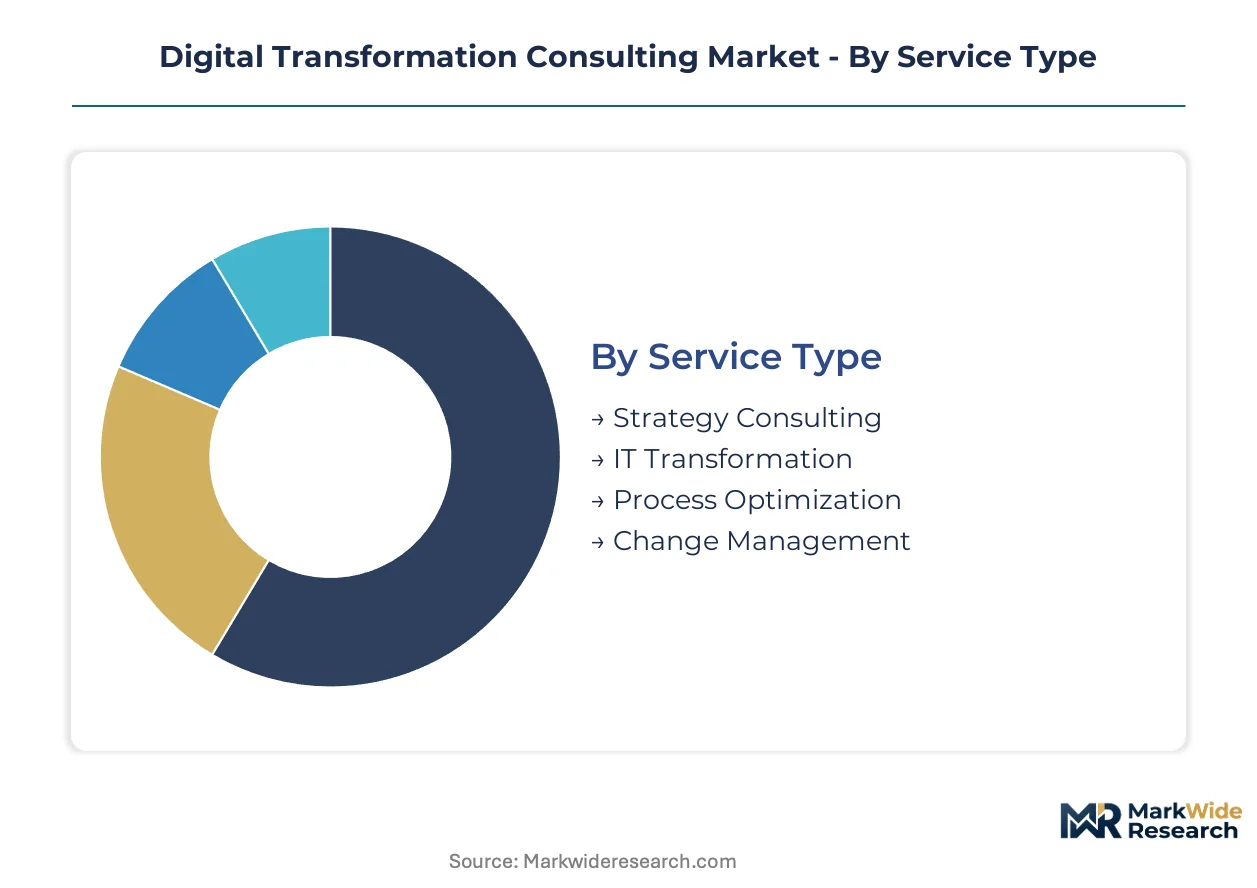
Segmentation in digital transformation consulting reveals distinct procurement rhythms and margin profiles. Service type and technology segments cycle at different velocities, while end user scale and industry vertical dictate contract structure and renewal patterns.
Service Type:
Cycle times vary dramatically across advisory and implementation work, with diagnostic phases compressing fastest while multi-year transformation partnerships extend delivery horizons.
- Strategy Consulting:Board-level engagements spanning technology roadmaps and capital allocation decisions. Large enterprises in financial services anchor demand as fiduciary pressure intensifies for AI governance frameworks.
- IT Transformation:Systems integration projects bridging legacy infrastructure with cloud-native architectures. Premium fees reflect scarce talent capable of hybrid environment orchestration, particularly among German manufacturers automating predictive maintenance platforms.
- Process Optimization:Workflow redesign services facing compressed pricing as automation tools commoditize deliverables. Mature category with margin pressure concentrated in retail and telecommunications procurement.
- Change Management:Workforce capability building and adoption support. Demand concentrates where technology deployment outpaces organizational readiness, creating reputation risk for implementation failures.
IT Transformation dominates installed base by contract value. Change Management is where expansion concentrates as adoption failures reshape procurement priorities.
End User:
Scale tiers separate procurement sophistication, with complexity thresholds determining whether buyers unbundle strategy from implementation or pursue integrated partnerships.
- Large Enterprises:Complex multi-year engagements with dedicated transformation offices. Healthcare providers in the United States demonstrate unbundling patterns, separating FDA pathway consulting from EHR deployment to technology specialists.
- SMEs:Modular service consumption through pre-built accelerators and phased diagnostic-to-implementation cycles. Cloud migration demand concentrates among mid-market financial services firms seeking compliance-integrated architecture.
- Government Agencies:Procurement governed by ISO 27001 certification requirements and algorithmic transparency mandates under EU AI Act specifications.
- Non-profits:Grant-constrained engagements prioritizing process optimization over capital-intensive IT transformation, with demand concentrated in donor accountability reporting automation.
Large Enterprises anchor revenue concentration through multi-year partnerships. SMEs represent the steepest expansion trajectory as cloud-native tooling democratizes access to enterprise-grade advisory.
Technology:
Margin pools separate infrastructure migration from intelligence layer deployment, with AI consulting commanding premium pricing against commoditized cloud lift-and-shift work.
- Cloud Computing:Dominant revenue pool encompassing legacy workload migration and security architecture. Healthcare providers accelerate adoption of patient management systems, creating sustained demand for HIPAA-compliant infrastructure design.
- Artificial Intelligence:Fastest-expanding margin pool as clients seek production deployment beyond pilot programs. EU AI Act compliance documentation and explainable AI architecture drive premium pricing in European procurement.
- Data Analytics:Governance-integrated implementation combining GDPR architecture with monetization pathway design. Demand concentrates among financial services institutions developing compliant data products.
- IoT:Industrial sensor integration and digital twin architecture. German manufacturing investments in predictive maintenance reshape procurement toward outcome-based partnerships.
Cloud Computing dominates current revenue pools by volume. Artificial Intelligence is where margin expansion concentrates as production deployment gaps widen.
Industry Vertical:
Regulatory intensity separates verticals, with compliance architecture requirements elevating consulting procurement specifications in supervised sectors.
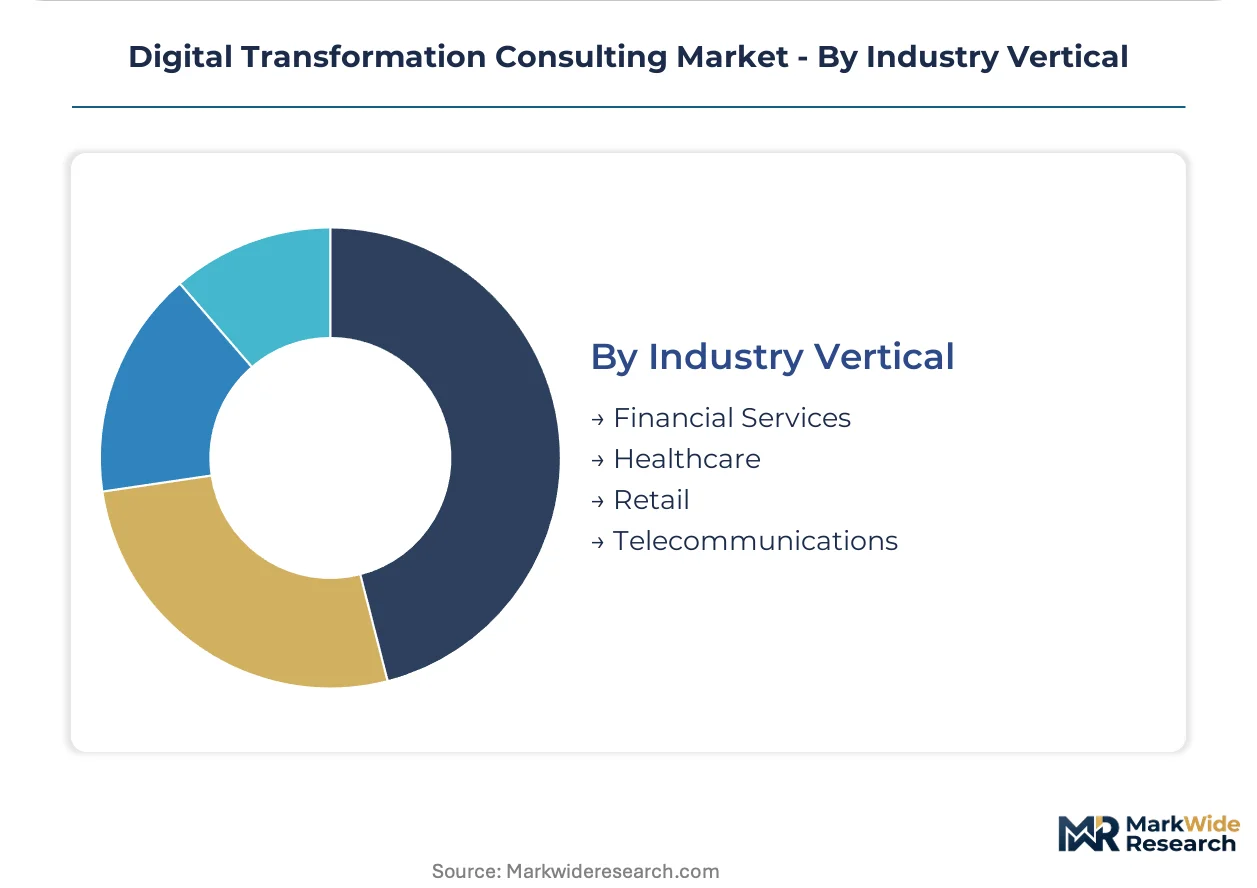
- Financial Services:Deep compliance expertise requirements spanning GDPR, EU AI Act, and SEC algorithmic trading oversight. Deloitte Digital sustains positioning through architecture specialization in this vertical.
- Healthcare:Dual regulatory pressure from FDA AI-enabled diagnostic scrutiny and HIPAA data governance. Procurement specifications embed transparency documentation as non-negotiable deliverables.
- Retail:Customer-facing workflow automation and supply chain digitization. Generative AI code generation collapses development timelines, forcing consultancies toward integration and governance revenue.
- Telecommunications:Infrastructure modernization and customer experience platform deployment. Process optimization pricing pressure concentrates in this vertical due to standardized tooling availability.
Financial Services dominates premium fee concentration. Healthcare is where compliance-integrated expansion accelerates fastest under tightening FDA and EMA pathway divergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers concentrate procurement authority in board-level transformation offices across four major economies. Healthcare providers and industrial manufacturers anchor demand patterns, with regulatory compliance requirements reshaping vendor selection criteria in supervised sectors.
United States
Healthcare providers dominate procurement volume as FDA scrutiny of AI-enabled diagnostic tools elevates demand for compliance-integrated implementation consulting. HIPAA governance requirements and SEC algorithmic trading oversight shape procurement specifications across financial services and healthcare verticals. The Boston-Cambridge corridor concentrates specialized advisory capacity for life sciences digital transformation.
Germany
Industrial automation investments in predictive maintenance and digital twin architecture are reshaping procurement toward multi-year transformation partnerships. The EU AI Act and GDPR jointly mandate algorithmic transparency documentation as non-negotiable deliverables. Manufacturing demand concentrates in Baden-Württemberg and Bavaria, where automotive and machinery producers anchor systems integration spending.
United Kingdom
Financial services institutions drive premium fee concentration through deep compliance expertise requirements spanning GDPR and emerging algorithmic governance frameworks. The Financial Conduct Authority's evolving oversight of AI in consumer-facing applications elevates procurement specifications for explainable architecture. London anchors advisory capacity, with Birmingham and Manchester emerging as implementation delivery clusters.
France
Enterprises front-load compliance architecture spend to preempt EU AI Act enforcement action, with CNIL guidance on automated decision-making shaping procurement timelines. Healthcare and public sector buyers concentrate demand for ISO 27001-certified implementation partners. The Paris-Saclay cluster hosts specialized capacity for high-risk algorithmic system conformity assessments.
India
Mid-market financial services firms accelerate cloud migration demand seeking compliance-integrated architecture at scale-adjusted fee structures. RBI guidelines on data localization and cybersecurity frameworks elevate certification requirements for serving multinational accounts. Bangalore and Hyderabad anchor delivery capacity for global consulting firms serving European and North American clients.
Digital Transformation Consulting Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered service categories, with full-service consultancies facing disintermediation as enterprise buyers unbundle strategy from implementation. The vendor base separates into three strategic archetypes: global full-service networks with pre-built industry accelerators, vertical specialists with deep regulatory expertise, and technology-native implementation firms. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into managed outcomes beyond advisory.
Within the full-service tier, Accenture and Deloitte Digital occupy positions anchored by pre-built industry cloud accelerators and vertical compliance architecture specialization respectively. McKinsey & Company exemplifies the strategy-centric archetype focused on board-level technology roadmap and capital allocation advisory. These three firms represent distinct competitive positioning vectors as procurement fragmentation accelerates.
| Leading Market Players |
|---|
| Accenture |
| Deloitte Digital |
| IBM Consulting |
| McKinsey & Company |
| Boston Consulting Group |
| Capgemini |
| PwC |
| Cognizant |
| Bain & Company |
| Others |
Supply Flow & Price Mechanics
Frankfurt-London data corridor transit costs directly shape tiered service pricing for European consultancies, concentrating margin advantage among firms with captive nearshore delivery centers while forcing price differentiation between compliance-heavy and commodity advisory tiers.
Pricing Analysis
Cost-plus contracts indexed to talent bench rates dominate IT Transformation engagements, with ISO 27001 certification and EU AI Act compliance documentation commanding substantial premiums over standard process optimization work. Three-tier pricing structure across premium, standard, and economy levels separates strategy boutiques from implementation specialists and offshore delivery firms. Cost compression in workflow automation services is intensifying because generative AI tools commoditize diagnostic deliverables. Mid-market financial services firms exhibit highest price sensitivity, while German automotive manufacturers demonstrate lowest sensitivity due to outcome-based contracting preferences.
Supply Chain Analysis
Tariff exposure between India and European Union jurisdictions dominates supply chain risk planning for multinational consulting networks. Talent sourcing concentrates in India, Germany, and United Kingdom, with delivery architecture drawing from Bangalore technical campuses, Munich industrial engineering pools, and London financial services expertise. Specialized inputs include cloud hyperscaler certifications, regulatory compliance credentials, and proprietary industry accelerators. Single-source vulnerability in explainable AI audit capacity constrains European delivery expansion. Distribution runs through direct enterprise sales teams, strategic partnership channels with technology vendors, and managed outcome contracts with recurring revenue structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive separation, as EU AI Act compliance documentation requirements and cross-border certification depth generate switching costs that resist client churn.
For Market Incumbents: Pre-empt boutique specialist encroachment by acquiring ISO 27001-certified regional firms in France and Germany before compliance mandates harden procurement specifications. Anchor defensive positioning through captive AI audit capacity building to address the structural shortage in explainable AI professionals threatening EU AI Act delivery timelines. For New Entrants and Emerging Players: Mid-market healthcare providers in United States seeking FDA pathway consulting separate from EHR implementation represent the most penetrable entry point for unbundled service positioning. Government agencies across European Union member states front-loading EU AI Act compliance spend offer concentrated demand for certified boutique entrants. Target initial penetration through CNIL-aligned automated decision-making governance offerings in France. For Investors and Strategic Acquirers: Specialist compliance architecture boutiques with embedded regulatory relationships and pre-built industry accelerators offer asymmetric return profiles in a five-to-ten-year consolidation window. Monitor enforcement action timelines under EU AI Act risk classification frameworks as the critical inflection signal for compliance service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | ISO 27001-certified boutiques in France and Germany arbitrage cross-border compliance requirements. |
| Strategic Partnership | Cloud hyperscaler alliances compress deployment timelines for HIPAA-compliant healthcare infrastructure. |
| Product Launch | Pre-built EU AI Act compliance accelerators differentiate advisory offerings in European procurement. |
| Platform Integration | Generative AI code generation tools collapse software development phases for financial services automation. |
| Geographic Expansion | Nearshore delivery centers in Poland and Portugal reduce Frankfurt-London corridor cost exposure. |
Methodological Framework
Desk research of regulatory filing databases, hyperscaler partnership announcements, and EU AI Act implementation guidance preceded structured interviews with healthcare CIOs, financial services compliance officers, German manufacturing transformation leads, and cloud architecture specialists. Primary fieldwork combined with secondary validation against SEC 10-K disclosures, ISO certification registries, and CNIL enforcement records. Bottom-up contract value analysis triangulated against top-down market sizing from technology segment revenue disclosures.
Assumptions held fixed include EU AI Act enforcement timelines and HIPAA governance requirements, while cloud adoption velocity and generative AI integration pace were varied across sensitivity scenarios. Segmentation modeling spanned service type, technology layer, end-user scale, and industry vertical with regional regulatory cluster differentiation. CAGRs derived from weighted average of historical contract value trajectories and forward procurement pipeline indicators. Forecast inputs incorporated talent supply constraints in systems integration and explainable AI audit capacity.
Practitioners should monitor EU AI Act conformity assessment body accreditation progress and FDA AI-enabled diagnostic guidance issuance for early signals of demand inflection. Forecasts embed assumptions regarding regulatory harmonization that may require revision upon jurisdictional divergence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market