
 Spain Digital Transformation Market | 2026-2036
Spain Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Digital Transformation Market Insights
The Spain digital transformation landscape is pivoting along a sharp divide between bespoke enterprise platforms and standardized SaaS offerings. Accenture PLC leverages its consulting depth to anchor complex multi-cloud migrations for Iberian banking clients. Indra competes through specialized defense and public-sector digitization contracts that sustain its domestic market position. Google LLC extends its data analytics stack to occupy the mid-market segment where price sensitivity meets scalability requirements.
Digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and IoT sensors into core business processes to automate workflows, enhance data-driven decision-making, and enable real-time operational visibility across distributed assets. Its primary commercial purpose centers on reducing operational latency while improving customer experience metrics through predictive analytics and connected infrastructure. Consulting and systems integration services currently dominate margin pools as enterprises confront legacy technical debt during cloud transitions. Hybrid cloud deployment is expanding fastest among Spanish manufacturers seeking to balance data sovereignty requirements with elastic compute capacity. AI technology adoption within healthcare verticals is concentrating investment as hospitals deploy diagnostic algorithms under national digital health strategies.
Spain's national cybersecurity strategy aligns with EU NIS2 Directive requirements, compelling critical infrastructure operators to upgrade monitoring architectures and incident response capabilities by mandated timelines. The Spanish Data Protection Agency enforces GDPR-compliant data governance frameworks that shape cloud provider selection criteria and cross-border data handling protocols. Banco de España's fintech sandbox regulations are accelerating blockchain experimentation among retail banking applications. Stakeholders must monitor how EU AI Act risk classifications will reshape algorithm deployment timelines and compliance budgets across Spanish enterprise software procurement cycles.
Market Dynamics
The EU Digital Operational Resilience Act compels Spanish financial institutions to modernize core infrastructure, redirecting technology budgets toward cloud-native architectures and automated compliance tooling.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators in Spain must upgrade cybersecurity monitoring and incident response capabilities, expanding demand for managed security services and SIEM platforms.
- Edge computing clusters:Barcelona and Madrid data center developments concentrate hybrid infrastructure investment, pulling fiber connectivity and colocation services into these metropolitan zones.
- Healthcare digitization:Spanish hospitals deploy diagnostic AI algorithms under national digital health strategies, creating procurement pipelines for medical imaging analytics and clinical decision support systems.
Market Restraints
- Technical debt burdens:Legacy mainframe systems in Iberian banking constrain migration velocity, forcing parallel-run architectures that double operational overhead during transition periods.
- GDPR compliance friction:The Spanish Data Protection Agency's cross-border data handling protocols complicate multi-cloud deployments, extending vendor selection timelines and legal review cycles.
- Semiconductor supply concentration:Dependency on East Asian foundries for AI accelerators and edge processors creates delivery uncertainty for Spanish infrastructure projects.
Strategic Opportunities
- Andalusia manufacturing corridor:Underpenetrated industrial automation in southern Spain offers white space for predictive maintenance platforms and connected factory deployments.
- EU AI Act risk classification:High-risk algorithm mandates create compliance service opportunities for Spanish consultancies and legal-technology hybrid providers.
- Blockchain experimentation:Banco de España's fintech sandbox regulations enable retail banking pilots for distributed ledger applications in payments and identity verification.
Industry Challenges
- Cloud architecture specialization:Shortage of certified Kubernetes and multi-cloud engineers constrains project delivery timelines for Spanish systems integrators.
- Interoperability complexity:Integration of IoT sensor networks with existing ERP systems requires custom middleware development, inflating implementation costs for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Digital Transformation Market |
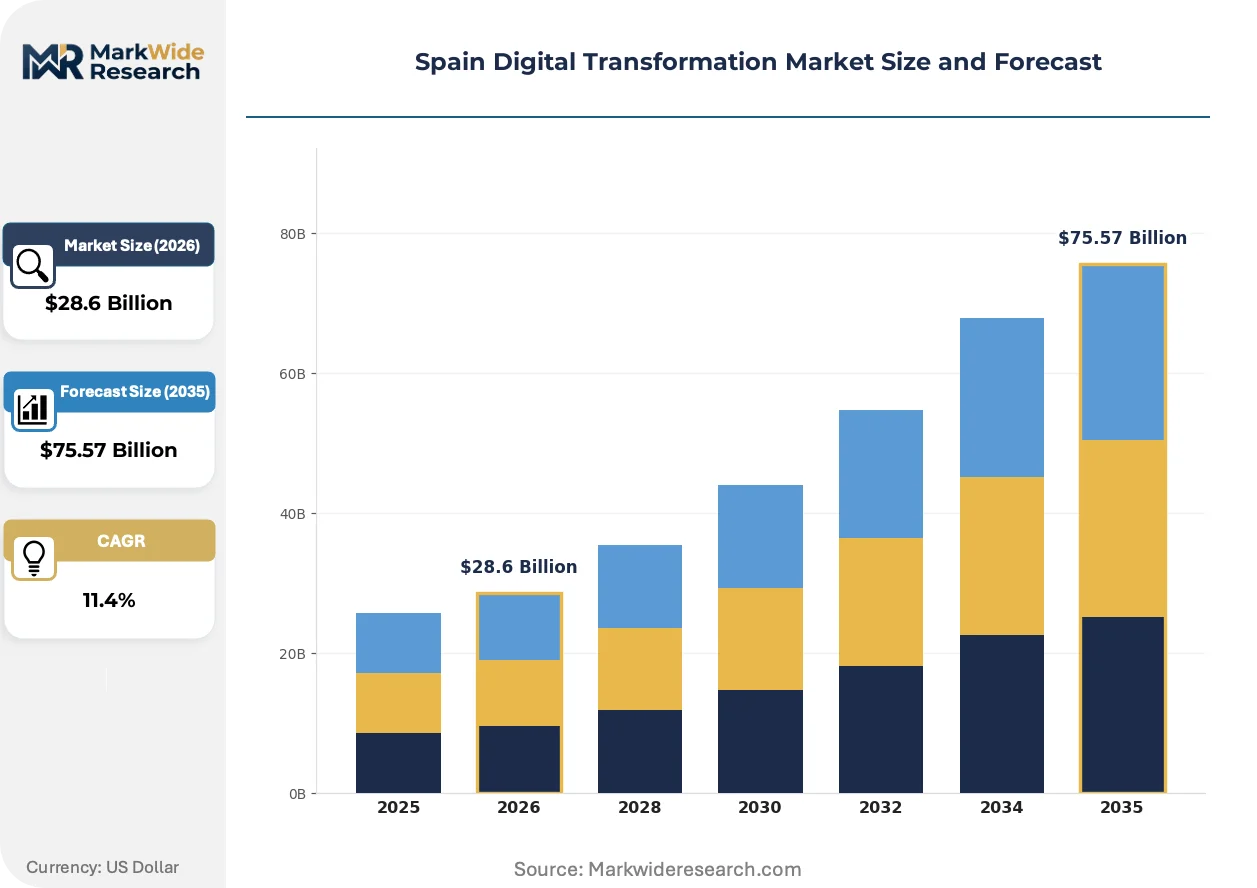
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Systems Integration, Managed Services, Support Services Industry Vertical: Healthcare, Banking, Retail, Manufacturing Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Google LLC, Indra, Accenture PLC, SAP SE, Capgemini, Microsoft Corporation, Telefónica Tech, Hewlett Packard Enterprise, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Digital Transformation Market Trends and Innovations
Generative AI tooling is compressing software development cycles across Spanish enterprises, while regulatory pressure on algorithmic accountability is reshaping vendor selection criteria.
Machine learning operations (MLOps) platforms are automating model deployment pipelines for Spanish financial services firms, reducing time-to-production for credit risk algorithms from months to weeks. Retail banks with established data engineering teams are adopting these toolchains fastest. This velocity shift is automating competitive differentiation in customer analytics capabilities.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk applications including biometric identification and credit scoring. Spanish enterprises must maintain algorithmic audit trails and impact assessments. Healthcare and financial services verticals are responding by embedding compliance checkpoints into DevSecOps workflows.
Spanish manufacturers are consolidating vendor relationships around integrated platform providers rather than point solutions for IoT and analytics. Industrial buyers now demand unified data lakes with pre-built connectors to SCADA and MES systems. This preference shift is most visible in Catalonia's automotive supplier base, where procurement teams prioritize single-contract accountability over best-of-breed component sourcing.
Spain Digital Transformation Market Segmentation
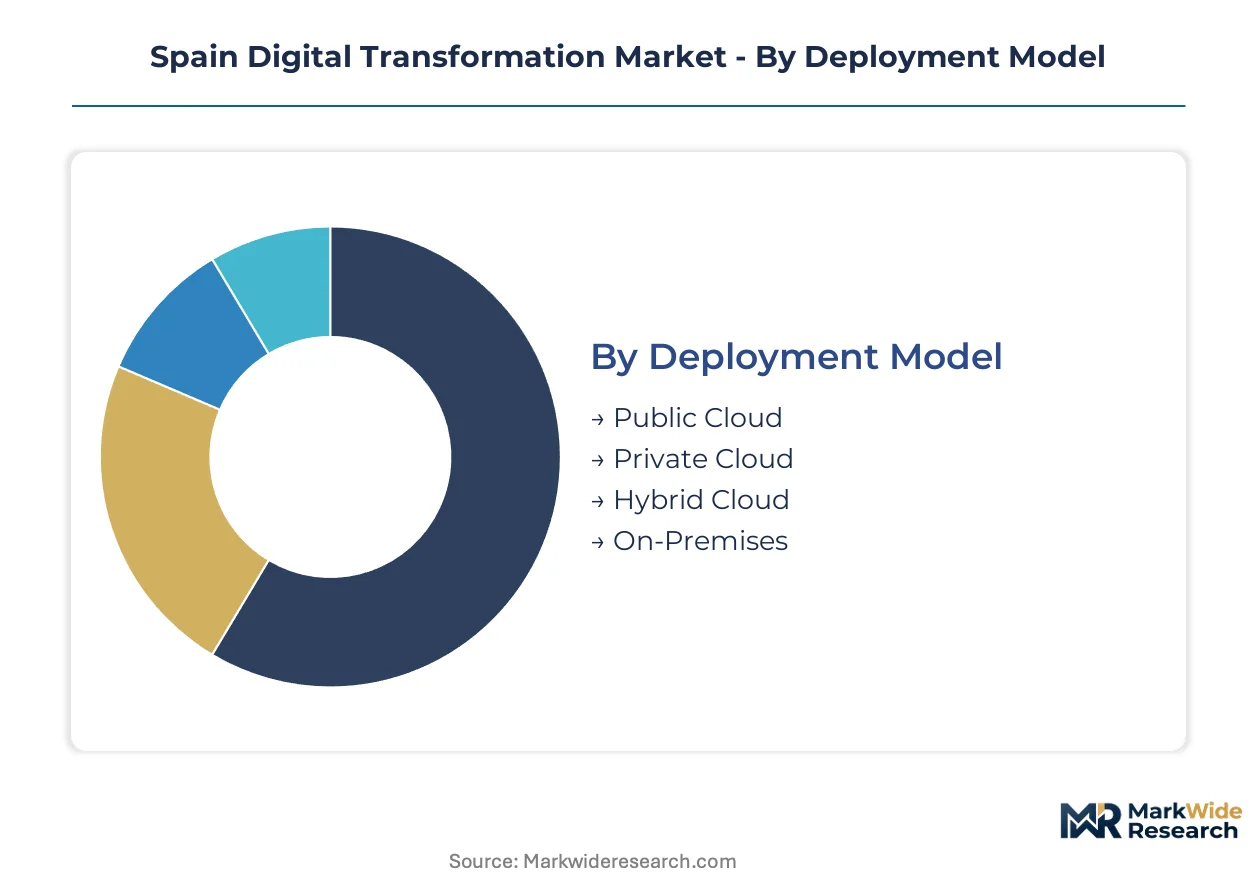
Deployment architecture, service delivery mode, industry application, and underlying technology stack each impose distinct procurement criteria on Spanish enterprise buyers. Procurement teams weight data sovereignty obligations against elasticity requirements when evaluating vendor proposals across these four segmentation dimensions.
Deployment Model:
Cost tier determines infrastructure selection for Spanish enterprises balancing capital efficiency against compliance overhead.
- Public Cloud:Shared infrastructure delivers elastic compute capacity through metered consumption models. Spanish mid-market retailers and fintech startups concentrate demand here, driven by zero upfront capital requirements and rapid provisioning timelines for seasonal workload spikes.
- Private Cloud:Dedicated single-tenant environments provide isolated resource pools with customized security policies. Iberian banking groups under Banco de España supervision prioritize this model for core banking workloads, compelled by GDPR data localization mandates and audit trail requirements.
- Hybrid Cloud:Orchestrated workload placement across on-premises and cloud environments enables tiered data classification. Catalan automotive suppliers and Madrid-based logistics operators deploy this architecture to keep sensitive ERP data on-site while bursting analytics workloads to public infrastructure.
- On-Premises:Legacy data center retention persists where latency constraints or regulatory grandfathering apply. Defense contractors and critical infrastructure operators in Spain maintain these deployments for air-gapped operational technology networks.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Type:
Application maturity shapes whether Spanish buyers seek advisory engagement or operational handoff.
- Consulting:Strategy and roadmap services address cloud migration planning, organizational change management, and digital operating model design. Spanish manufacturers in the Basque Country engage these services to align Industry 4.0 investments with EU funding eligibility criteria.
- Systems Integration:Technical implementation spans API development, legacy modernization, and multi-platform orchestration. Large Spanish banks procure these services for core system replacements under DORA-mandated resilience timelines.
- Managed Services:Ongoing operational responsibility for infrastructure, security operations, or application maintenance transfers to external providers. Regional healthcare consortiums in Andalusia adopt these arrangements to address internal IT skills gaps.
- Support Services:Break-fix, training, and vendor-specific technical assistance complete solution lifecycles. These services attach highest to on-premises deployments where Spanish enterprises retain full operational ownership.
Systems Integration commands the largest project values; Managed Services is climbing the fastest as operational outsourcing accelerates post-migration.
Industry Vertical:
Regulatory intensity and competitive pressure create divergent technology appetites across Spanish sectors.
- Healthcare:Electronic health record modernization, diagnostic imaging AI, and connected medical device integration dominate procurement. Spanish hospital networks under the national digital health strategy allocate capital to clinical decision support systems with embedded compliance for EU AI Act high-risk classifications.
- Banking:Core banking replacement, open API infrastructure, and real-time payment modernization absorb technology budgets. DORA implementation deadlines and Banco de España fintech sandbox participation drive concurrent investment in resilience tooling and experimental blockchain architectures.
- Retail:Omnichannel fulfillment platforms, customer data platforms, and supply chain visibility tools attract investment. Spanish fashion and grocery chains deploy these capabilities to match Amazon's logistics velocity in Iberian markets.
- Manufacturing:Predictive maintenance, digital twin simulation, and connected factory deployments target operational efficiency. Automotive suppliers in Catalonia and food processors in Valencia represent concentrated demand pockets for industrial IoT platforms.
Banking leads on scale; Healthcare leads on momentum.
Technology:
Technical readiness and data maturity filter which capabilities Spanish enterprises can absorb.
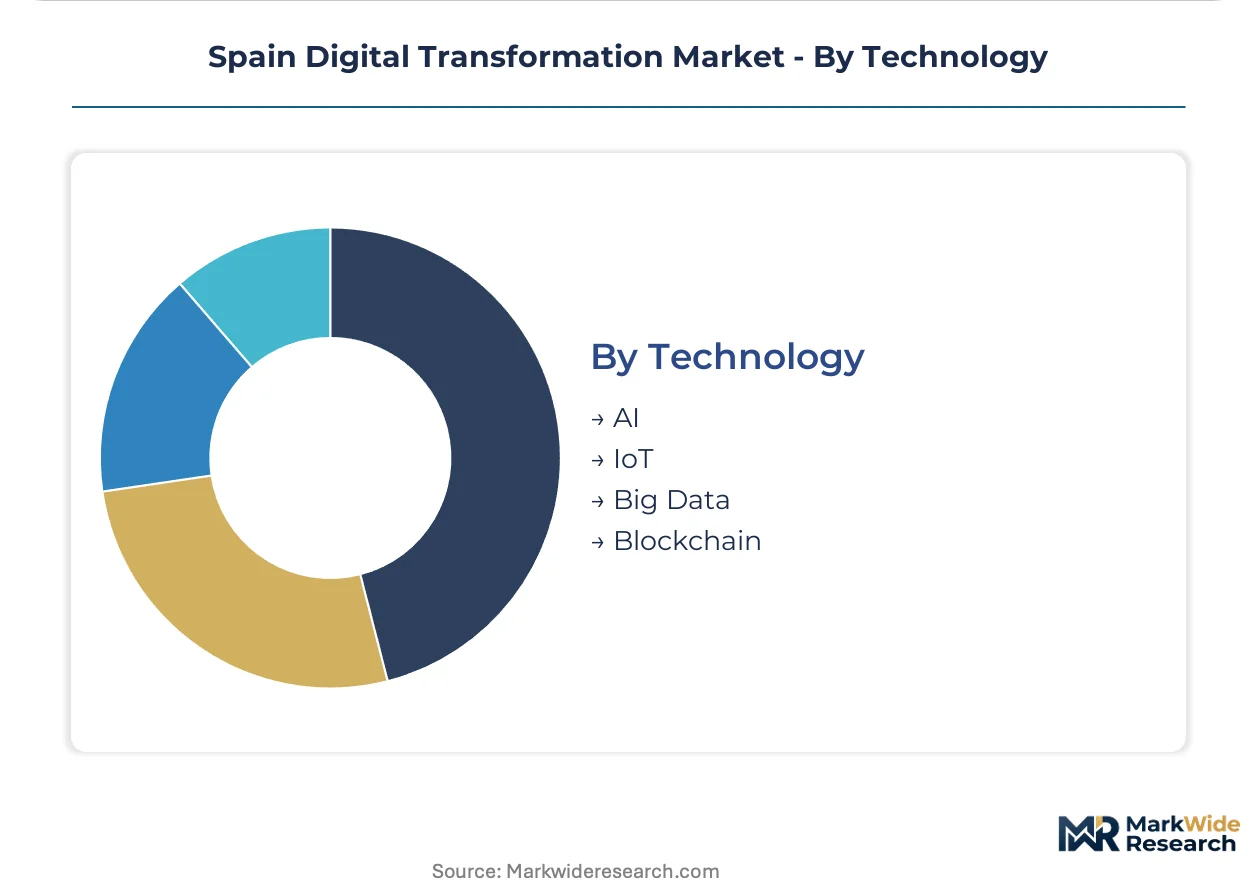
- AI:Machine learning model development, natural language processing, and computer vision applications automate decision workflows. Spanish financial services firms deploy credit risk algorithms while hospitals implement diagnostic imaging classification, both navigating EU AI Act documentation requirements.
- IoT:Sensor networks, edge gateways, and device management platforms connect physical assets to digital systems. Manufacturing corridors around Barcelona and Bilbao concentrate deployments for predictive maintenance and energy optimization use cases.
- Big Data:Data lake architecture, real-time streaming analytics, and business intelligence modernization enable centralized insight generation. Spanish retailers and telecommunications operators invest here to unify customer interaction data across channels.
- Blockchain:Distributed ledger pilots focus on supply chain provenance, digital identity, and wholesale payment settlement. Banco de España's regulatory sandbox enables controlled experimentation among retail banking consortia.
Big Data leads on scale; AI leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's digital transformation workforce concentrates in Madrid and Barcelona, where cloud architects and AI specialists anchor enterprise delivery capacity for Iberian banking and manufacturing clients.
Madrid
Financial services digitization and public-sector cloud migration dominate demand in Spain's capital. Banco de España's supervisory mandates for operational resilience compel regional headquarters of Santander and BBVA to modernize core infrastructure. The Madrid metropolitan zone hosts the densest concentration of hybrid cloud engineering talent, with Telefónica Tech and IBM maintaining delivery centers for DORA compliance projects.
Catalonia
Industrial IoT deployments and automotive supplier digitization drive technology investment across Barcelona and surrounding manufacturing corridors. The Generalitat de Catalunya's Industry 4.0 subsidy programs accelerate connected factory adoption among SMEs. SEAT's Martorell complex and associated tier-one suppliers anchor demand for predictive maintenance platforms and digital twin simulation tools.
Basque Country
Advanced manufacturing and energy sector transformation concentrate procurement around Bilbao and San Sebastián. Euskadi's regional innovation agency prioritizes AI adoption in machine tool and renewable energy equipment production. Mondragón Corporation's cooperative industrial groups deploy edge computing architectures for real-time quality control across distributed fabrication sites.
Andalusia
Underpenetrated industrial automation and agri-tech digitization create white space for platform vendors in Seville, Málaga, and Córdoba. Junta de Andalucía's digital agenda funds SME cloud migration through European Regional Development Fund allocations. The Málaga Tech Park attracts satellite delivery centers from multinational consultancies serving southern European markets.
Valencia
Ceramics, textiles, and food processing industries anchor manufacturing digitization demand in Spain's third-largest metropolitan area. Valencia's port logistics operators invest in supply chain visibility platforms to maintain competitiveness with Barcelona and Algeciras. Regional government programs for circular economy digitization target energy optimization in ceramics clusters around Castellón.
Spain Digital Transformation Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light advisory specialists for margin pools across Spain's digital transformation market. The vendor base stratifies into three tiers: global hyperscalers with localized delivery capacity, European systems integrators with Iberian banking expertise, and domestic specialists holding public-sector relationships. Consolidation pressure intensifies as mid-market consultancies face margin compression from platform-native service offerings. Dominant competitive moves include strategic partnerships between cloud providers and regional systems integrators, plus talent acquisition to address Kubernetes and MLOps engineering shortages.
Within the global technology tier, Google LLC and Microsoft Corporation anchor hyperscaler competition for Spanish enterprise workloads. Accenture PLC occupies the premium advisory segment alongside Capgemini, both leveraging pan-European delivery networks for complex multi-cloud migrations. Indra exemplifies domestic specialization, holding concentrated position in defense and public-sector digitization through long-standing institutional relationships. SAP SE and IBM Corporation represent the established enterprise software archetype, defending installed base through cloud extension offerings and industry-specific solution portfolios.
| Leading Market Players |
|---|
| Google LLC |
| Indra |
| Accenture PLC |
| SAP SE |
| Capgemini |
| Microsoft Corporation |
| Telefónica Tech |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
EU NIS2 Directive compliance mandates are forcing Spanish critical infrastructure operators to consolidate vendor relationships around integrated platform providers, compressing procurement timelines and intensifying price competition among systems integrators bidding for multi-year managed services contracts.
Pricing Analysis
Bundled platform offerings are displacing point-solution procurement across Spanish enterprise buyers. Three-tier pricing structure across premium consulting partnerships, standard systems integration, and economy managed services segments the market by service depth and risk transfer. Price differentiation rests on GDPR compliance certification tier and Kubernetes engineering density in delivery teams. Cost compression in the mid-market SaaS tier is intensifying because Google and Microsoft are subsidizing migration tooling to capture workload share. Spanish retail banking groups show least price sensitivity due to DORA-mandated resilience budgets, while Andalusian manufacturing SMEs face acute cost constraints.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure are compelling Spanish enterprises to qualify multiple hyperscaler partners simultaneously, extending procurement cycles but reducing lock-in risk. Hardware supply concentrates in Taiwan, South Korea, and China for AI accelerators and edge processors. Software licensing draws from Ireland, Luxembourg, and the United States for EU data residency compliance. Single-source vulnerability in East Asian semiconductor foundries threatens delivery timelines for Barcelona and Madrid edge computing deployments. Distribution runs through Telefónica Tech and IBM delivery centers for enterprise implementation, with direct hyperscaler relationships capturing mid-market share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's digital transformation market functions as a geographic-arbitrage play where EU regulatory stringency creates premium service opportunities unavailable in less regulated jurisdictions, with compliance-driven consulting margins exceeding North American benchmarks by a substantial spread.
For Market Incumbents: Hedge against hyperscaler margin compression by deepening captive Kubernetes and MLOps engineering capabilities in Madrid delivery centers. Accenture and Capgemini should anchor multi-cloud orchestration expertise as defensive moats against Google and Microsoft's platform-native service expansion. Vertical integration into regulatory compliance tooling addresses EU AI Act documentation requirements before boutique legal-technology hybrids capture this adjacency. For New Entrants and Emerging Players: EU AI Act risk classification mandates in Spain open a window for algorithmic audit and impact assessment specialists to capture compliance service revenue from healthcare and financial services verticals. Andalusia's underpenetrated manufacturing automation corridor offers the most penetrable geography for predictive maintenance platform vendors. A channel partnership strategy with regional systems integrators accelerates enterprise access without direct sales infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic Spanish consultancies holding Banco de España fintech sandbox relationships and Generalitat de Catalunya Industry 4.0 subsidy program access. Long-term viability favors acquisition targets with embedded public-sector contracting mechanisms and EU funding eligibility expertise. The signal to watch is consolidation velocity among mid-market Kubernetes specialists as hyperscaler platform services commoditize implementation layers. Deviation in EU AI Act enforcement timing would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Orchestration Partnership | Telefónica Tech's DORA compliance delivery capacity anchors banking modernization timelines. |
| MLOps Platform Integration | Spanish retail banks compress credit risk algorithm deployment from months to weeks. |
| Edge Computing Cluster Expansion | Barcelona and Madrid data center developments concentrate fiber and colocation investment. |
| Regulatory Compliance Tooling Acquisition | EU AI Act documentation requirements create legal-technology hybrid service opportunities. |
| Andalusian Manufacturing Corridor Entry | Junta de Andalucía ERDF allocations fund SME cloud migration and IoT adoption. |
Research Methodology
Coverage spans Iberian Peninsula markets with primary inputs from each major metropolitan technology cluster. The analysis combines structured interviews with Spanish bank CTOs, public-sector digital transformation leads, manufacturing plant engineers, and healthcare IT procurement officers with secondary validation against Banco de España regulatory filings, EU NIS2 implementation guidance, and hyperscaler capex disclosures. Bottom-up project pipeline analysis triangulates with top-down market sizing across deployment model, service type, industry vertical, and technology stack segmentation dimensions.
Rate-of-change decomposition separates baseline digitization momentum from regulatory acceleration effects across the projection horizon. The analytical framework models deployment architecture preferences, organization size tiers, vertical regulatory intensity, integration complexity levels, and regional adoption patterns to generate segment-specific growth trajectories. CAGR derivation incorporates DORA implementation deadlines, EU AI Act risk classification rollout, and national digital health strategy procurement pipelines as industry-specific forecast inputs.
Revisions become necessary when semiconductor supply chain disruptions, EU AI Act enforcement delays, or Banco de España supervisory mandate modifications materialize. Forecasts reflect assumptions regarding hyperscaler pricing discipline, Kubernetes engineering labor availability, and ERDF funding continuity. Deviation in any trigger condition would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
France Digital Transformation Market