
 Workplace Transformation Market | 2026-2036
Workplace Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Workplace Transformation Market Intelligence
A persistent shortage of cloud architecture and change-management talent is unwinding legacy outsourcing models and forcing enterprises toward integrated transformation partners. Accenture PLC leverages its global delivery network to embed workplace modernization into broader enterprise reinvention programs. Microsoft anchors the productivity layer through Teams and Azure Virtual Desktop, controlling the interface where most hybrid work occurs. IBM Corporation competes through Watson-enabled automation and consulting-led change programs that span infrastructure through culture.
Workplace transformation encompasses the redesign of physical, digital, and organizational environments to enable distributed collaboration, operational agility, and employee experience optimization through unified endpoint management, zero-trust security architectures, and real-time analytics dashboards. Its primary commercial purpose is to reduce real estate and IT operational costs while sustaining or improving workforce output across geographically dispersed teams. Cloud-based delivery models now dominate new engagements, with managed services capturing expanding margin pools as enterprises outsource ongoing platform optimization. AI-powered software within digital workspaces represents the fastest-growing product category, displacing point-solution collaboration tools that lack embedded intelligence or workflow automation.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape vendor product roadmaps and limit cross-border deployment options for automated workforce analytics. OSHA guidelines in the United States and Japan's METI telework standards additionally influence ergonomic and mental-health compliance obligations for hybrid arrangements. Stakeholders must monitor how rapidly evolving AI liability frameworks in multiple jurisdictions will redistribute risk between technology vendors and enterprise buyers.
Market Dynamics
Hybrid infrastructure mandates are compressing procurement cycles as financial services and technology firms demand unified endpoint management platforms that merge physical security, zero-trust networking, and AI-powered workspace analytics into single-vendor contracts.
Growth Catalysts
- EU AI Act compliance deadlines:Enterprises across Germany, France, and the Netherlands are accelerating automated workplace tool deployments to meet algorithmic transparency requirements before enforcement phases begin.
- Cloud-native collaboration stacks:Technology clusters in California and Texas are consolidating video conferencing, document management, and virtual desktop infrastructure onto unified platforms to reduce vendor fragmentation.
- Real estate cost optimization:Professional services firms are rightsizing physical footprints through hot-desking analytics and occupancy sensors that justify lease renegotiations in high-cost metropolitan markets.
Market Restraints
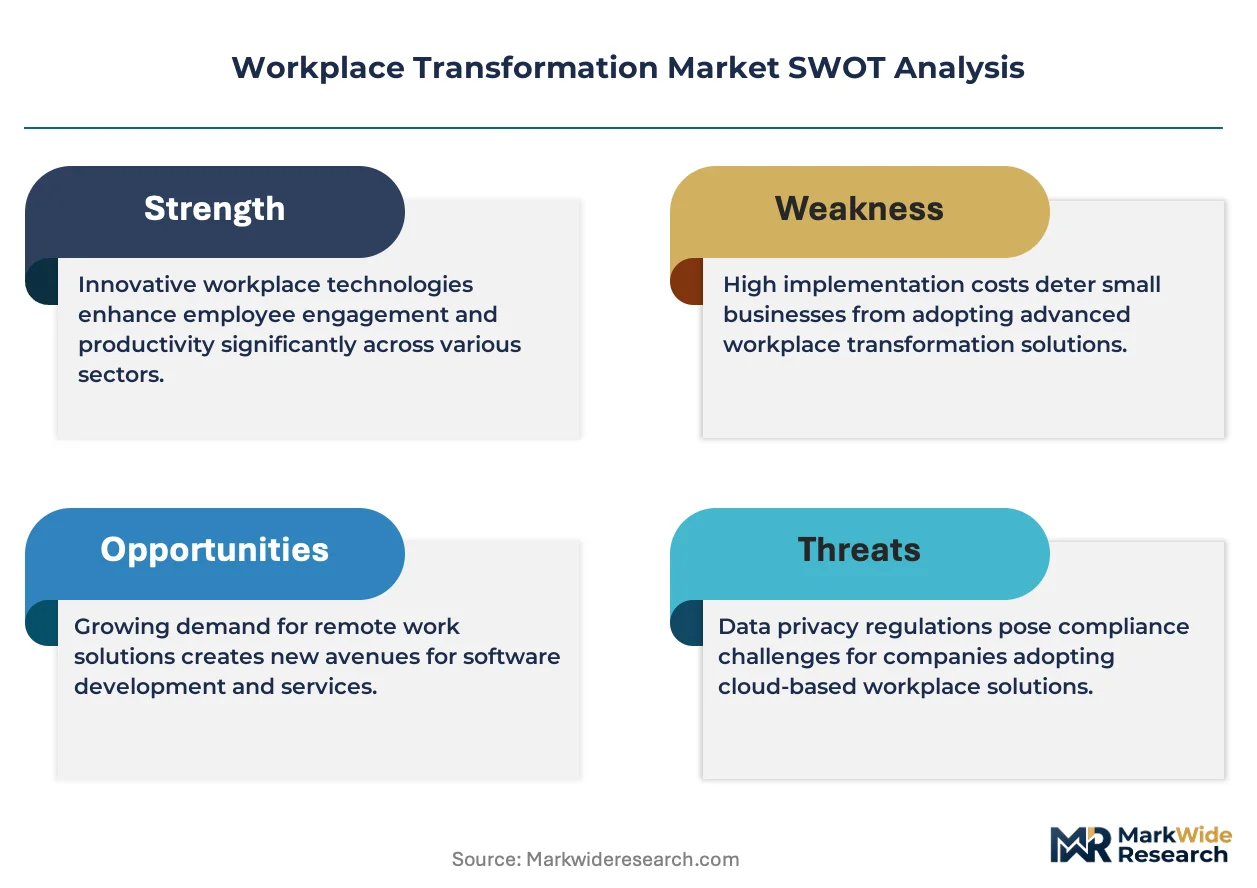
- Specialized talent scarcity:Cloud architecture and organizational change-management expertise concentrates in coastal United States labor markets, inflating implementation timelines and partner dependency.
- Cross-border data friction:GDPR residency requirements and EU AI Act algorithmic audit obligations complicate multi-national workspace analytics deployments for enterprises with distributed workforces.
- Legacy system entanglement:Decades-old on-premise identity management and VPN infrastructure resist cloud-native replacement, forcing expensive middleware layers that degrade user experience.
Strategic Opportunities
- Small and mid-market penetration:Professional services firms with 500-5,000 employees remain underserved by enterprise-focused vendors, creating whitespace for modular, consumption-priced workspace platforms.
- Convergence of physical and digital security:Integration of biometric access control, zero-trust network access, and endpoint detection represents an unclaimed product category for unified platform providers.
- OSHA ergonomic compliance expansion:Emerging guidelines for home office equipment and mental health monitoring create attach-rate opportunities for workspace-as-a-service providers bundling hardware and insurance.
Industry Challenges
- Multi-vendor integration complexity:Enterprises stitching together Microsoft Teams, disparate VPN solutions, and third-party analytics dashboards face authentication sprawl and support ticket escalation.
- Change management capacity gaps:Internal communications and training functions lack bandwidth to drive adoption of new collaboration tools across geographically dispersed, culturally heterogeneous teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workplace Transformation Market |
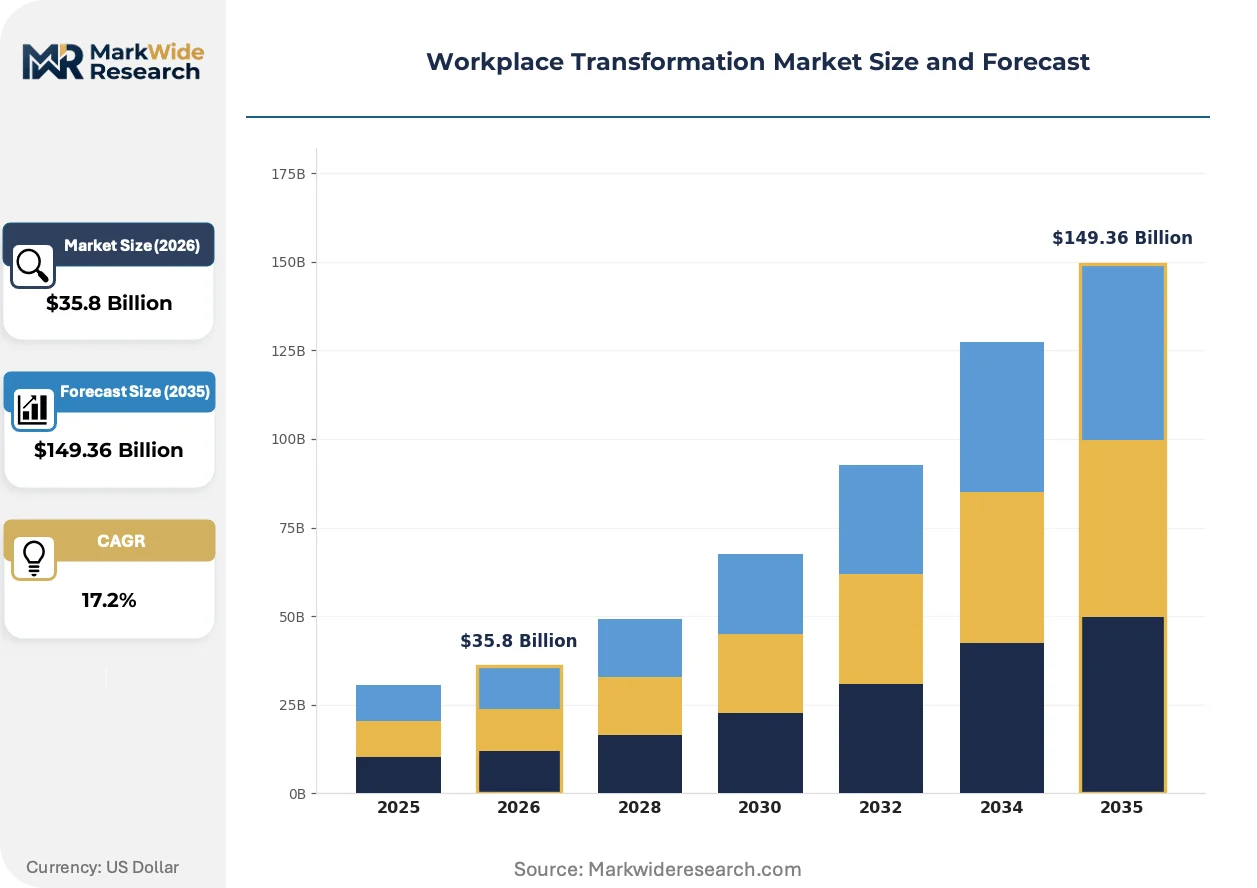
| Market Size in 2026 | $35.8 Billion |
| Market Size in 2035 | $149.36 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
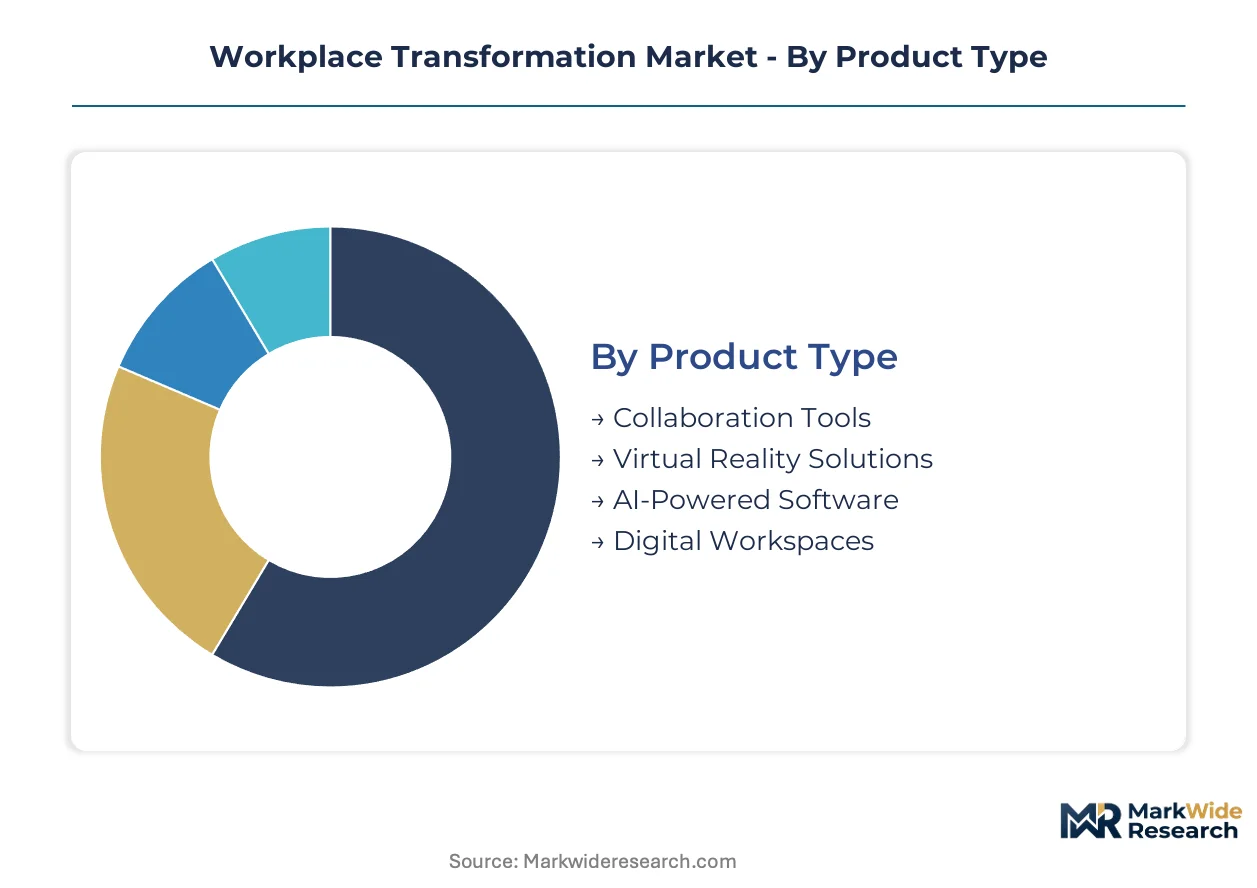
| Segmentation | Product Type: Collaboration Tools, Virtual Reality Solutions, AI-Powered Software, Digital Workspaces Delivery Model: On-Premise, Cloud-Based, Hybrid Solutions, Managed Services End User: Corporates, Small Businesses, Freelancers, Educational Institutions Technology: AI, IoT, Cloud Computing, Automation |
| Companies Covered | Accenture PLC, IBM Corporation, Cisco Systems, Inc., NTT Data Corporation, Hewlett Packard Enterprise Development LP, Capgemini, Cognizant Technology Solutions Corporation, HCL Technologies Ltd., Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workplace Transformation Market Strategic Shifts & Innovations
Intelligent automation is penetrating workspace management layers that previously relied on manual configuration, while regulatory pressure on algorithmic decision-making forces architectural redesign of productivity analytics.
AI-powered software agents embedded within digital workspaces are bifurcating the collaboration market between platforms with native workflow automation and point-solution tools requiring third-party integration. Financial services procurement teams in New York and London are prioritizing vendors offering predictive scheduling, automated meeting transcription with action-item extraction, and sentiment analysis of internal communications. This capability divide is compressing margins for standalone video conferencing providers while expanding addressable spend for integrated platform vendors.
The EU AI Act's risk-classification framework for automated workforce monitoring is reshaping product roadmaps for analytics vendors serving European enterprises. High-risk applications including emotion recognition and biometric inference now require conformity assessments and human oversight mechanisms that delay release cycles. Vendors are responding by stripping contested features from EU deployments while maintaining fuller functionality for United States customers, creating regulatory-driven product fragmentation.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based contracts that tie fees to measurable productivity or cost-reduction metrics rather than per-seat licensing. Systems integrators and managed service providers in the United States are displacing traditional software resellers by absorbing operational risk through guaranteed service-level agreements for platform uptime and user satisfaction scores. This preference shift concentrates procurement authority among chief financial officers and procurement functions rather than IT departments alone.
Workplace Transformation Market Segmentation
Workplace transformation procurement fractures across multiple decision axes, with CFOs prioritizing delivery model economics while CTOs weigh technology architecture. Understanding how these dimensions intersect reveals where vendors capture premium pricing versus commodity margin compression.
Product Type:
Margin pools concentrate in AI-embedded platforms that bundle workflow automation with collaboration infrastructure, displacing standalone tools.
- Collaboration Tools:Unified video conferencing, messaging, and document sharing platforms form the productivity backbone for hybrid teams. Demand clusters among professional services firms in California and Texas seeking to consolidate vendor relationships and reduce licensing fragmentation.
- AI-Powered Software:Predictive scheduling, automated transcription with action-item extraction, and sentiment analysis engines transform passive collaboration into intelligent workflow orchestration. Financial services procurement teams in New York and London prioritize these capabilities for compliance documentation and meeting efficiency.
- Virtual Reality Solutions:Immersive training environments and spatial collaboration rooms serve manufacturing and engineering use cases requiring 3D visualization.
- Digital Workspaces:Unified endpoint management platforms integrating virtual desktop infrastructure, application streaming, and zero-trust access control.
Collaboration Tools hold installed capacity. AI-Powered Software is rotating up the share rankings.
Delivery Model:
Cloud-native deployments now dominate new contract value, though regulatory complexity preserves hybrid architectures in regulated industries.
- Cloud-Based:Multi-tenant SaaS platforms with automatic updates and elastic scaling reduce capital expenditure and IT operational burden. Technology clusters in California and Texas lead adoption, driven by cloud-first mandates and availability of specialized architecture talent.
- Managed Services:Outcome-based contracts absorbing operational risk through guaranteed uptime and user satisfaction SLAs capture expanding margin pools. Enterprises outsource ongoing platform optimization to systems integrators displacing traditional software resellers.
- Hybrid Solutions:Split deployments maintaining sensitive workloads on-premise while leveraging cloud elasticity for general collaboration.
- On-Premise:Legacy data center installations persisting in highly regulated sectors with strict data residency requirements.
On-Premise retains compliance-driven pockets. Managed Services is climbing the fastest as procurement authority shifts to CFO functions.
End User:
Customer sophistication and procurement scale create tiered pricing architecture across organizational size bands.
- Corporates:Fortune 500 and equivalent enterprises with 10,000-plus employees demand bespoke integration, dedicated support, and custom development. These buyers consolidate vendor relationships and negotiate outcome-based contracts tied to productivity metrics.
- Small Businesses:Firms with 500-5,000 employees remain underserved by enterprise-focused vendors, creating whitespace for modular, consumption-priced platforms with rapid deployment.
- Educational Institutions:Universities and K-12 districts requiring FERPA-compliant collaboration with learning management system integration.
- Freelancers:Individual contractors and gig workers purchasing personal productivity subscriptions with limited enterprise feature requirements.
Corporates anchor contract value. Small Businesses is gaining share fastest as vendor attention shifts downmarket.
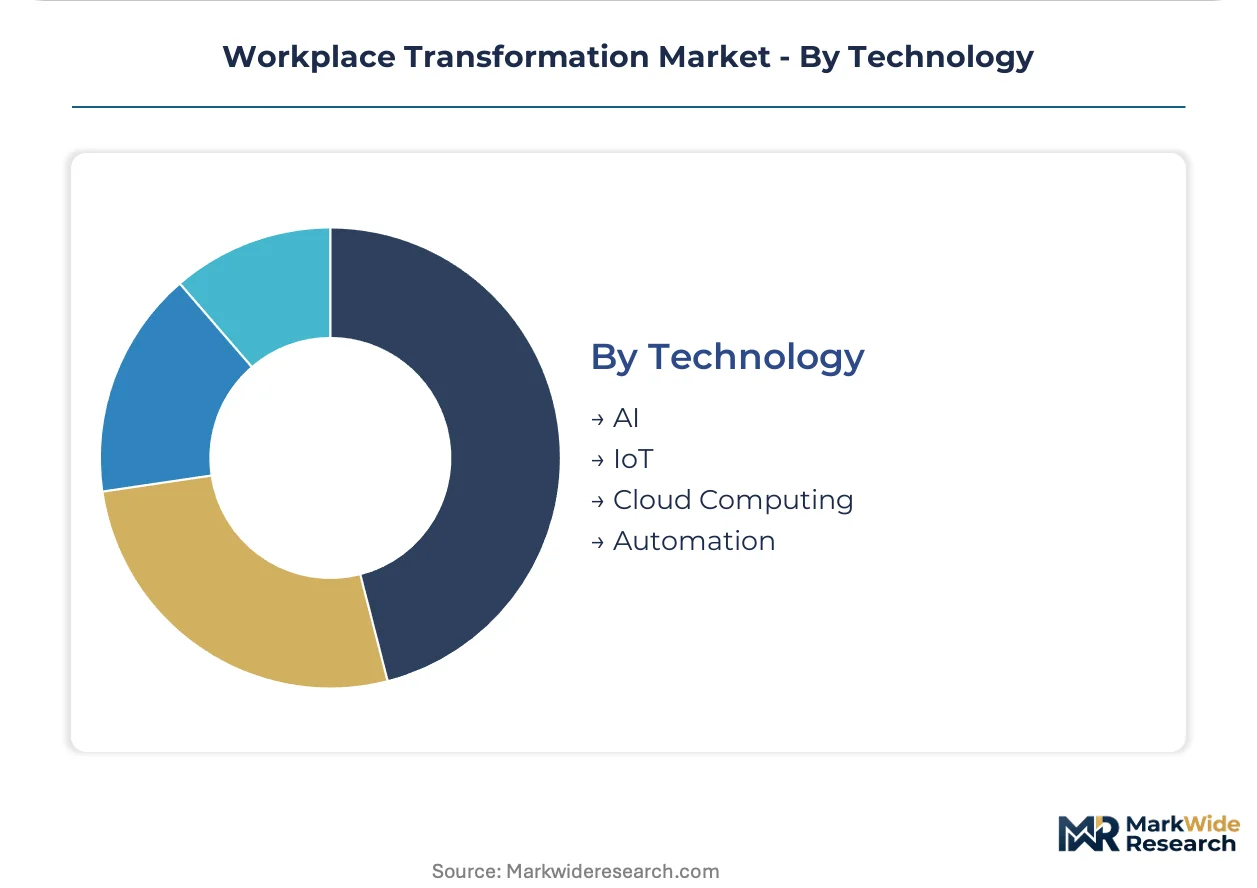
Technology:
Technology stack choices determine integration complexity and long-term vendor lock-in exposure for enterprise buyers.
- AI:Machine learning models powering predictive analytics, natural language processing, and automated decision support within workspace platforms. EU AI Act risk classifications for emotion recognition and biometric inference reshape European product roadmaps.
- Cloud Computing:Distributed infrastructure enabling elastic resource allocation, global availability zones, and consumption-based pricing models.
- IoT:Occupancy sensors, environmental monitors, and biometric access control bridging physical and digital workplace management.
- Automation:Robotic process automation and workflow engines eliminating manual configuration of user provisioning and policy enforcement.
Cloud Computing holds foundational deployment share. AI is rotating up the share rankings as embedded intelligence becomes table stakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA guidelines in the United States anchor the regulatory framework shaping hybrid workplace compliance obligations across major economies. The analysis examines demand concentration and policy drivers across five countries where workplace transformation spending concentrates.
United States
Technology clusters in California and Texas drive cloud-native collaboration stack consolidation, with financial services firms in New York accelerating unified endpoint management procurement. OSHA ergonomic guidelines for home office equipment create compliance-driven hardware attach opportunities. Professional services firms across these metropolitan markets are rightsizing physical footprints through occupancy analytics.
Germany
Industrial manufacturing headquarters in Munich and Stuttgart demand immersive training environments and spatial collaboration for engineering visualization. The EU AI Act's algorithmic transparency requirements compress deployment timelines for automated workforce analytics. Mittelstand firms with 500-5,000 employees remain underserved by enterprise-focused vendors, creating modular platform whitespace.
United Kingdom
Financial services procurement teams in London prioritize predictive scheduling and automated transcription with action-item extraction for compliance documentation. GDPR residency requirements complicate multi-national workspace analytics deployments for enterprises with distributed workforces. The City of London and Canary Wharf technology clusters anchor demand for zero-trust security architectures.
Japan
METI telework standards influence ergonomic and mental-health compliance obligations for hybrid arrangements across Tokyo and Osaka corporate headquarters. Manufacturing conglomerates in Nagoya and Fukuoka deploy IoT-enabled occupancy sensors to optimize facility utilization. Cloud architecture talent scarcity in these metropolitan markets inflates implementation timelines and partner dependency.
India
Bengaluru and Hyderabad technology campuses anchor global delivery network expansion for integrated transformation partners serving North American and European clients. The country's national IT regulator shapes data localization requirements affecting cross-border workspace analytics deployments. Mumbai and Delhi financial services firms are accelerating hybrid infrastructure mandates with compressed procurement cycles.
Workplace Transformation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with cloud-native platform vendors and systems integrators capturing diverging margin pools. The upper tier consolidates around vendors bundling collaboration infrastructure with AI-embedded workflow automation, while specialists concentrate in biometric access control and immersive training environments. Three strategic archetypes dominate: full-stack platform providers, consulting-led transformation partners, and managed service operators absorbing operational risk. Competitive dynamics center on M&A activity consolidating point-solution vendors and outcome-based contract structures transferring performance risk to service providers.
Within the integrated consulting tier, Accenture PLC exemplifies the global delivery network model embedding workplace modernization into broader enterprise reinvention programs. IBM Corporation occupies a position spanning Watson-enabled automation through culture-change consulting, while Microsoft anchors the productivity layer controlling the interface where most hybrid work occurs. These three entities represent distinct strategic postures: Accenture's consulting-led integration, IBM's automation-to-culture span, and Microsoft's interface dominance through Teams and Azure Virtual Desktop.
| Leading Market Players |
|---|
| Accenture PLC |
| IBM Corporation |
| Cisco Systems, Inc. |
| NTT Data Corporation |
| Hewlett Packard Enterprise Development LP |
| Capgemini |
| Cognizant Technology Solutions Corporation |
| HCL Technologies Ltd. |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Outcome-based contracts with guaranteed uptime SLAs lock in multi-year platform access for enterprises while anchoring price predictability against operational risk transfer. This structure concentrates procurement authority among CFO functions seeking to convert capital expenditure into operational expenditure across cloud-native workspace deployments.
Pricing Analysis
Per-seat subscription tiers dominate the Workplace Transformation Market, with three-tier pricing structure across premium, standard, and economy levels differentiating by AI-embedded automation depth and compliance certification grade. Price differentiation stems from GDPR and EU AI Act conformity assessments for European deployments versus streamlined United States configurations. Cost compression in the economy tier is intensifying because standalone video conferencing providers face margin erosion from integrated platform consolidation. Small businesses with 500-5,000 employees exhibit highest price sensitivity, while Fortune 500 corporates prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for biometric hardware and IoT sensor components destined for United States and European deployment sites. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore, with compute capacity expansion tethered to hyperscaler capex cycles and renewable energy availability. Raw material dependencies span semiconductor wafers, rare earth magnets for access control systems, and specialized optical components for immersive training hardware. Single-source vulnerability in Taiwan-based chip fabrication creates supply chain risk for endpoint management platforms. Distribution runs through systems integrators and managed service providers displacing traditional software resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services and platform optimization layers expand faster than core collaboration software licensing, creating service-attach opportunities that absorb operational risk through guaranteed SLAs.
For Market Incumbents: Compound platform stickiness by embedding AI-powered workflow automation deeper into existing Teams and Azure Virtual Desktop deployments before point-solution vendors can integrate. Acquire biometric access control specialists to unify physical-digital security convergence. Vertical integration into zero-trust networking hardware defends margin position against cloud-native challengers. Prioritize EU AI Act conformity assessment pre-certification to accelerate European sales cycles against compliance-lagged competitors. For New Entrants and Emerging Players: Lead with modular, consumption-priced platforms targeting Mittelstand firms in Germany and professional services clusters in Texas with 500-5,000 employee footprints currently underserved by enterprise-focused vendors. White-space opportunity concentrates in hot-desking analytics and occupancy sensor integration for lease renegotiation justification. Channel partnership with commercial real estate brokers provides embedded distribution into facilities management decision-makers. For Investors and Strategic Acquirers: Capital is best deployed toward managed service operators with outcome-based contract expertise and demonstrated SLA performance in financial services verticals. Long-term viability hinges on absorbing operational risk rather than reselling software licenses. Acquisition target archetype: systems integrators with certified change-management capabilities and existing Accenture or IBM partnership tiers. Watch for OSHA ergonomic guideline enforcement expansion as inflection indicator for hardware bundling attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating video conferencing, document management, and virtual desktop infrastructure reduces vendor fragmentation for California technology clusters. |
| Acquisition of Specialist Firm | Biometric access control and IoT sensor capabilities bridge physical-digital security convergence demanded by financial services procurement teams. |
| Strategic Partnership | Alliances with commercial real estate brokers embed workspace analytics into lease renegotiation workflows for professional services firms. |
| Product Launch | EU AI Act-compliant analytics platforms with stripped emotion recognition features capture European enterprise demand ahead of enforcement phases. |
| Geographic Expansion | Mumbai and Delhi financial services firms accelerate hybrid infrastructure procurement with compressed cycles requiring localized delivery networks. |
Research Approach
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration across primary fieldwork and secondary validation. Chief financial officers and chief human resource officers at Fortune 500 and mid-market enterprises contributed demand-side perspectives on outcome-based contracting preferences. Secondary sources encompassed SEC filings from systems integrators, hyperscaler capex disclosures, EU regulatory filings documenting AI Act implementation timelines, and OSHA guideline development records. Bottom-up deployment estimates triangulated against top-down enterprise IT spending benchmarks.
Consistency checks validated volume and value outputs against external benchmarks including IT services spending surveys and cloud infrastructure adoption indices across the analysis window. Segmentation modeling incorporated delivery model economics, organization size tier, vertical industry, integration complexity, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle assumptions. Forecast inputs included cloud architecture talent availability indices and real estate cost pressure metrics in high-cost metropolitan markets.
The analysis sits within stated boundaries; outcomes outside sustained hybrid work policy mandates or abrupt regulatory reversals would require recalibration. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and OSHA guideline expansion trajectories. Model sensitivity to cloud infrastructure cost inflation and specialized talent scarcity concentration in coastal United States labor markets warrants monitoring. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market