
 France Digital Transformation Market | 2026-2036
France Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Transformation Market Insights
Subscription-based software-defined services is consolidating control over enterprise IT procurement in France. Capgemini leverages its systems integration heritage to anchor multi-year transformation contracts with public sector clients. Microsoft Corporation competes through Azure cloud infrastructure bundled with productivity suites across French financial institutions. IBM Corporation differentiates via hybrid cloud and AI consulting aimed at legacy modernization in manufacturing.
France digital transformation encompasses the integration of cloud-native architectures, data analytics platforms, and automated workflows into enterprise operations, typically deployed through API-connected microservices with sub-100-millisecond latency requirements for real-time decisioning. Its primary purpose is to replace siloed legacy systems with interoperable digital infrastructure that reduces operational friction and enables predictive capabilities. Cloud Computing leads technology spending as enterprises migrate on-premise workloads, while AI captures margin pools through specialized consulting and model training services. Financial Services dominates vertical adoption due to regulatory pressure and fintech competition, though Manufacturing accelerates fastest through Industry 4.0 pilot programs.
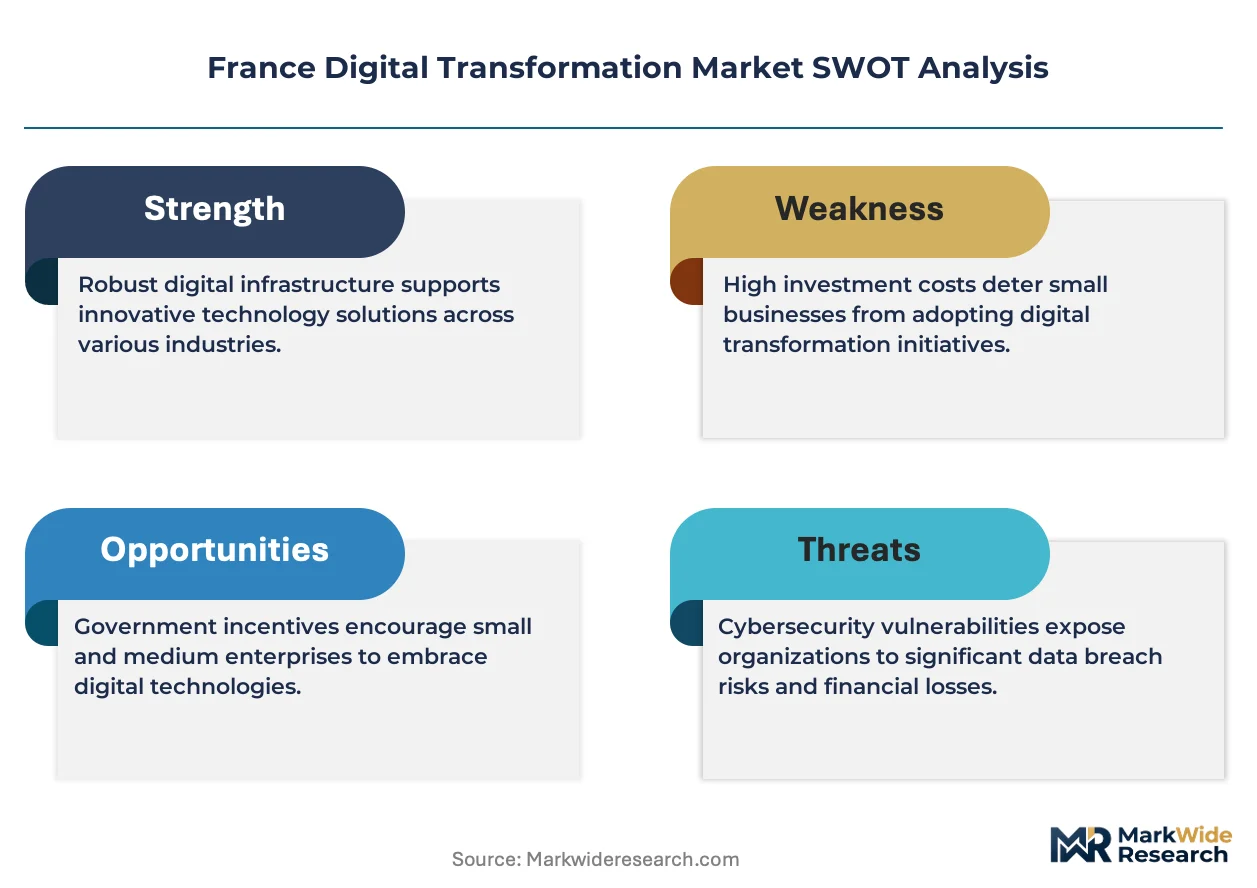
France's national regulator CNIL enforces GDPR-aligned data governance, while the EU AI Act imposes risk-tiered compliance obligations on automated decision systems deployed across French enterprises. ANSM mandates digital traceability standards in healthcare, directly shaping procurement requirements for hospital IT modernization. Stakeholders must monitor how EU Green Deal reporting rules through CSRD will force sustainability data infrastructure into transformation roadmaps.
Market Dynamics
CNIL enforcement of GDPR-aligned data governance and the EU AI Act's risk-tiered obligations are forcing French enterprises to rebuild core infrastructure around compliance-by-design architectures rather than retrofitting controls onto legacy stacks.
Growth Catalysts
- EU AI Act mandates:Automated decision systems in French financial services and healthcare must meet conformity requirements, accelerating procurement of audit-ready AI infrastructure and model documentation platforms.
- Cloud migration imperatives:Enterprises across Ile-de-France are replacing on-premise data centers with Paris-Saclay hosted services to reduce latency below 100 milliseconds for real-time analytics workloads.
- Industry 4.0 pilots:Manufacturing clusters in Auvergne-Rhône-Alpes are deploying IoT-enabled predictive maintenance systems, creating demand for edge computing and digital twin platforms.
Market Restraints
- Specialized talent scarcity:French enterprises face acute shortages of MLOps engineers and cloud security architects, inflating project timelines and consulting dependency.
- Legacy system entrenchment:COBOL and mainframe-dependent institutions in banking and insurance confront prohibitive migration costs and operational risk from decades-old codebases.
- Cross-border data friction:GDPR territoriality rules complicate multi-cloud strategies requiring data residency guarantees for workloads spanning French and EU jurisdictions.
Strategic Opportunities
- CSRD sustainability reporting:The EU Green Deal's Corporate Sustainability Reporting Directive mandates granular emissions tracking, opening demand for ESG data infrastructure and carbon accounting software in French enterprises.
- Healthcare digitization gaps:ANSM traceability requirements for pharmaceutical supply chains remain underimplemented in regional hospital networks outside Paris, creating whitespace for compliance-focused vendors.
- Edge-AI convergence:Manufacturing facilities in Hauts-de-France are piloting federated learning architectures that process sensor data locally while training models centrally, enabling new service models.
Industry Challenges
- Interoperability complexity:API standardization across French public sector agencies remains fragmented, forcing systems integrators to build bespoke connectors for each ministry deployment.
- Cybersecurity certification delays:ANSSI qualification timelines for critical infrastructure operators extend 12-18 months, bottlenecking deployment of sensitive cloud workloads in energy and transport.
- Organizational change resistance:Unionized workforces in traditional industries obstruct workflow automation initiatives, requiring parallel investment in reskilling programs and labor negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Transformation Market |
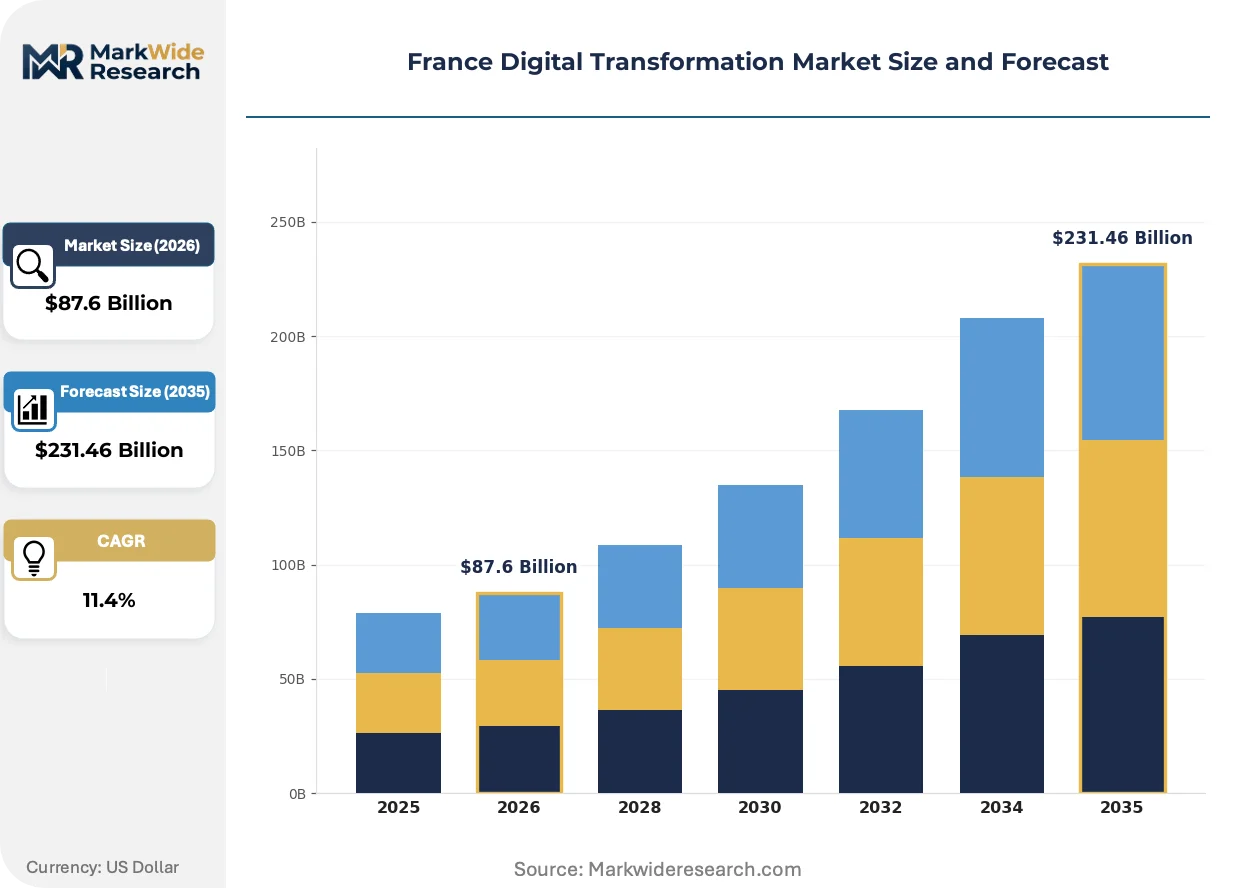
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Healthcare, Retail, Manufacturing, Financial Services Technology: Cloud Computing, AI, IoT, Blockchain Application: Customer Experience, Operational Efficiency, Data Analytics, Cybersecurity End User: Small Enterprises, Large Corporations, Government Agencies, Nonprofits |
| Companies Covered | Accenture PLC, Google LLC, IBM Corporation, Microsoft Corporation, Capgemini, Atos, Orange Business Services, Sopra Steria, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Transformation Market Trends and Innovations
Generative AI capabilities are compressing software development cycles while regulatory pressure hardens infrastructure requirements. French enterprises now confront simultaneous demands for acceleration and control.
API-first microservices architectures are consolidating control over enterprise application development in France. Financial institutions in Paris-La Défense are rebuilding core banking platforms around containerized services with automated failover. This consolidation is collapsing traditional three-tier application stacks into unified platform-as-a-service offerings.
The EU AI Act's risk classification system imposes documentation and human oversight obligations on high-risk automated systems deployed in French credit scoring and recruitment. Healthcare providers must maintain algorithmic impact assessments for diagnostic AI. Manufacturing quality-control systems face lighter transparency requirements but must still register with national competent authorities.
Subscription consumption models are displacing perpetual licensing across French enterprise software procurement. Public sector buyers now mandate outcome-based pricing tied to service availability metrics rather than seat counts. Regional hospital consortia in Provence-Alpes-Côte d'Azur are consolidating vendor relationships around multi-year platform subscriptions with built-in upgrade paths.
France Digital Transformation Market Segmentation
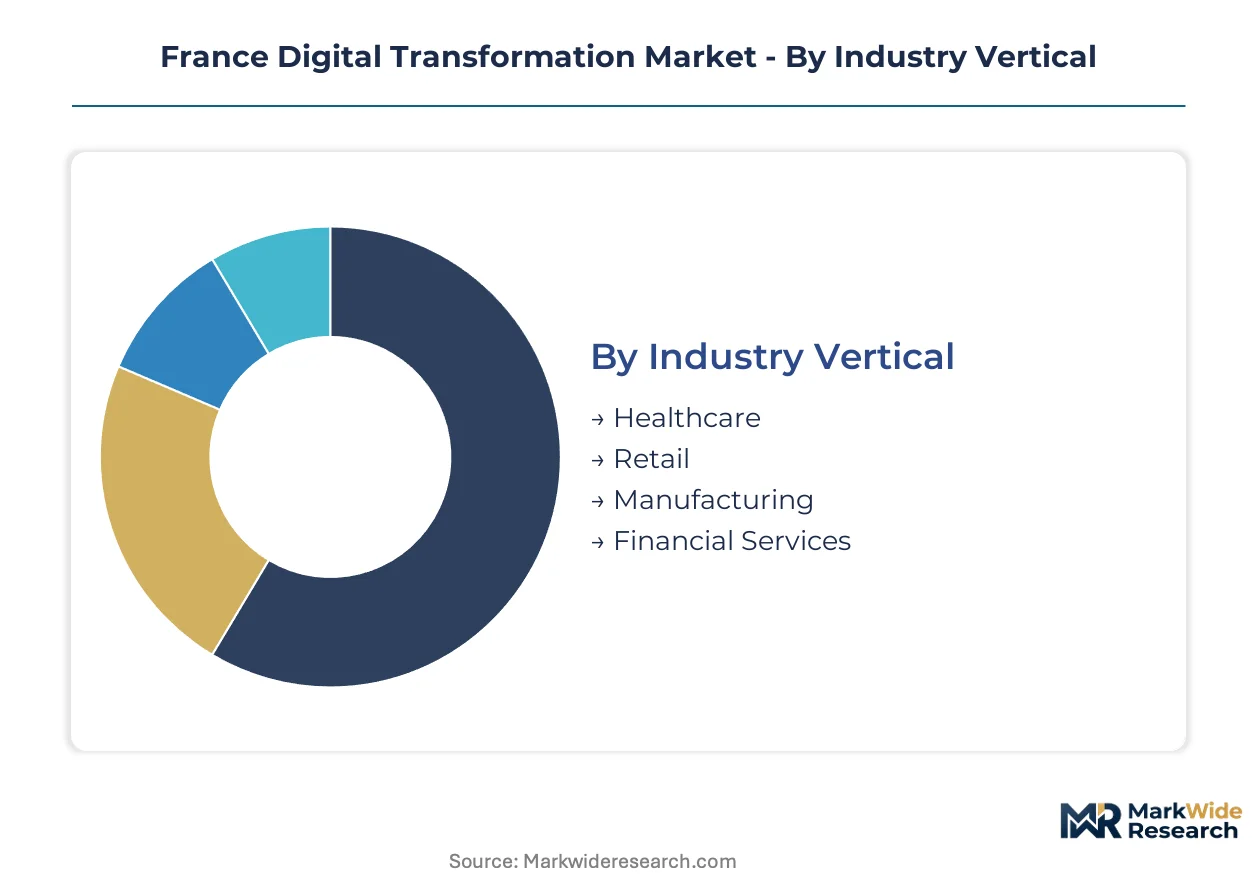
Enterprise buyers in France prioritize technology stacks that reconcile operational acceleration with CNIL-mandated data sovereignty. Segmentation reveals where procurement budgets concentrate and which compliance architectures command premium pricing.
Industry Vertical:
Regulatory intensity and competitive pressure determine technology investment priority across French sectors.
- Healthcare:ANSM traceability mandates require interoperable electronic health records and pharmaceutical supply chain tracking systems. Hospital networks in Ile-de-France accelerate procurement of audit-ready infrastructure to meet patient data portability requirements.
- Financial Services:EU AI Act conformity obligations and fintech disruption drive core banking modernization. Paris-La Défense institutions replace legacy payment rails with real-time settlement architectures.
- Manufacturing:Industry 4.0 pilot programs in Auvergne-Rhône-Alpes deploy predictive maintenance and digital twin platforms.
- Retail:Omnichannel fulfillment investments concentrate in logistics-heavy operations serving the Greater Paris region.
Volume sits with Financial Services; growth tilts toward Manufacturing.
Technology:
Infrastructure maturity and margin capture potential differentiate technology procurement tiers.
- Cloud Computing:Workload migration to Paris-Saclay hyperscale facilities dominates enterprise IT roadmaps. Latency requirements below 100 milliseconds for real-time analytics reshape data center placement decisions.
- AI:Model training services and automated decision systems attract specialized consulting spend. High-risk use cases in credit scoring and recruitment trigger EU AI Act documentation obligations.
- IoT:Sensor networks in Hauts-de-France manufacturing enable edge processing architectures.
- Blockchain:Supply chain provenance applications remain niche outside pharmaceutical traceability pilots.
Cloud Computing commands current procurement volume; AI consulting represents the steepest expansion trajectory.
Application:
Outcome measurability determines subscription pricing acceptance across French enterprise buyers.
- Operational Efficiency:Workflow automation and robotic process implementation target cost reduction in unionized industrial settings. Change management complexity extends deployment timelines.
- Data Analytics:Real-time decisioning platforms require sub-100-millisecond infrastructure investments. Paris-Saclay proximity becomes a procurement criterion.
- Customer Experience:Personalization engines face GDPR consent architecture constraints.
- Cybersecurity:ANSSI qualification delays bottleneck critical infrastructure deployments in energy and transport.
Operational Efficiency absorbs the largest share; Data Analytics climbs fastest as latency-sensitive workloads proliferate.
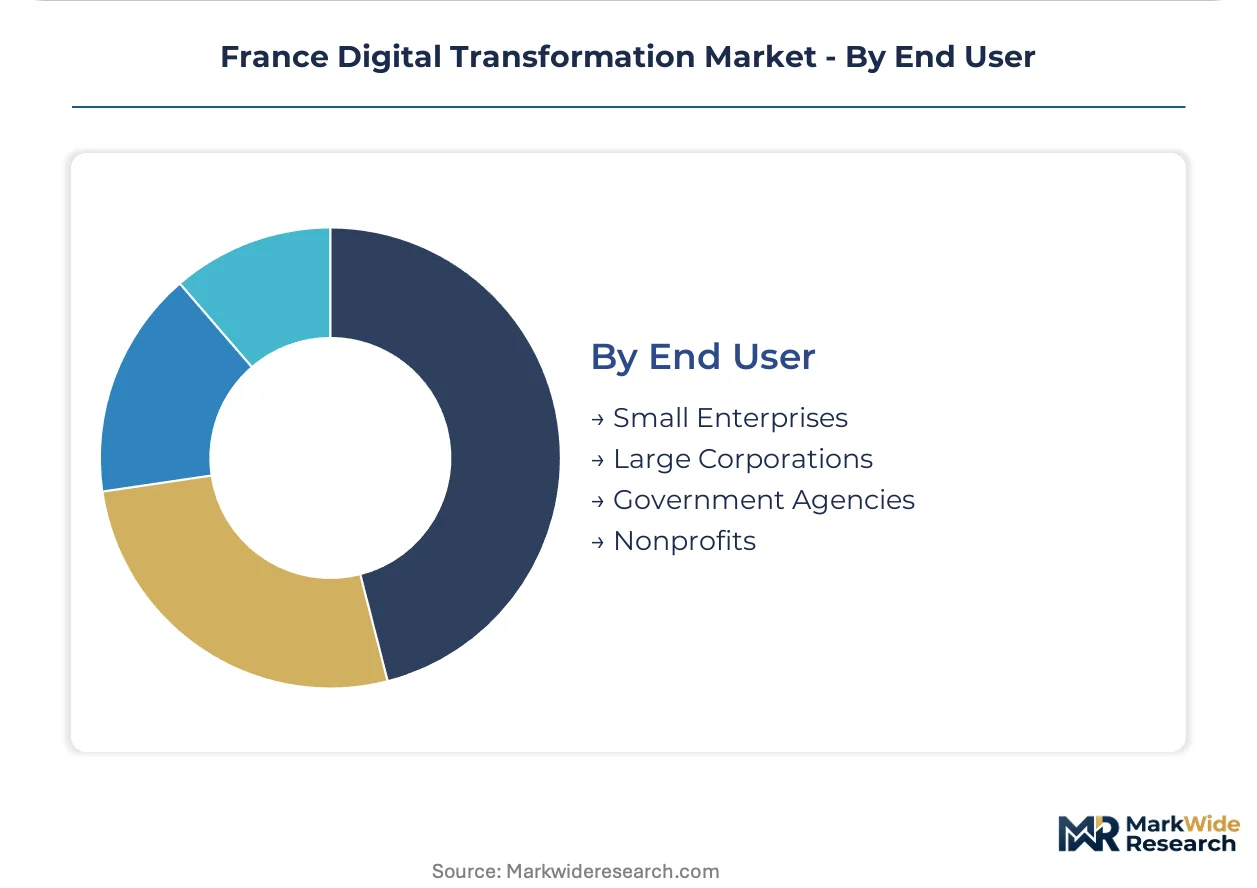
End User:
Budget scale and compliance exposure shape vendor engagement models.
- Government Agencies:Multi-year transformation contracts favor systems integrators with public sector heritage. API standardization fragmentation across ministries forces bespoke connector development.
- Large Corporations:Hybrid cloud and legacy modernization projects concentrate procurement authority with CIO offices.
- Small Enterprises:SaaS consumption models reduce upfront capital requirements.
- Nonprofits:Grant-dependent funding cycles constrain multi-year platform commitments.
Government Agencies anchor contract value; Large Corporations drive technology diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates digital transformation supply within Paris-Saclay hyperscale facilities while regional demand disperses across manufacturing clusters and hospital networks. Île-de-France hosts the infrastructure gravity; peripheral regions drive application-specific procurement.
Île-de-France
Financial institutions in Paris-La Défense and public sector agencies anchor enterprise software procurement at scale. CNIL enforces GDPR-aligned data governance with particular intensity in this jurisdiction. Paris-Saclay technology clusters concentrate cloud computing demand as enterprises migrate workloads for sub-100-millisecond latency compliance.
Auvergne-Rhône-Alpes
Manufacturing conglomerates deploy Industry 4.0 pilot programs spanning predictive maintenance and digital twin platforms. The EU AI Act's risk-tiered obligations shape automated quality-control system procurement. Lyon-based industrial automation specialists coordinate IoT sensor networks across automotive and precision engineering facilities.
Provence-Alpes-Côte d'Azur
Regional hospital consortia consolidate vendor relationships around multi-year platform subscriptions with built-in upgrade paths. ANSM mandates digital traceability standards that directly shape procurement requirements. Marseille logistics hubs drive omnichannel fulfillment investments in retail-heavy operations.
Hauts-de-France
Manufacturing facilities pilot federated learning architectures that process sensor data locally while training models centrally. The EU Green Deal's CSRD reporting rules force sustainability data infrastructure into transformation roadmaps. Lille metropolitan area anchors edge-AI convergence pilots for automotive suppliers.
Nouvelle-Aquitaine
Aerospace and defense contractors maintain legacy system entrenchment that complicates cloud migration timelines. ANSSI qualification requirements for critical infrastructure operators extend deployment cycles. Bordeaux technology parks attract mid-market SaaS vendors targeting grant-dependent nonprofit funding cycles.
France Digital Transformation Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light consulting specialists for control over French enterprise procurement. Systems integrators with public sector heritage anchor multi-year transformation contracts against cloud hyperscalers bundling compute with productivity suites. Three archetypes dominate: heritage consultancies leveraging ministerial relationships, global technology vendors pushing platform consolidation, and regional specialists targeting sector-specific compliance gaps. Competitive moves concentrate on strategic partnerships with Paris-Saclay facility operators and portfolio diversification into AI governance tooling.
Within the heritage consultancy tier, Capgemini and Atos occupy positions shaped by decades of French public sector engagement. Sopra Steria represents the mid-scale systems integration archetype targeting regional hospital networks. Among global technology vendors, Microsoft Corporation and IBM Corporation exemplify contrasting cloud strategies—Azure-centric platform bundling versus hybrid infrastructure specialization. Accenture PLC anchors the strategy-heavy consulting segment with transformation program authority. These five entities collectively illustrate how vendor selection in France privileges compliance documentation capabilities and ministerial relationship depth over pure technology performance metrics.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC |
| IBM Corporation |
| Microsoft Corporation |
| Capgemini |
| Atos |
| Orange Business Services |
| Sopra Steria |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among Paris-Saclay hyperscale facility operators anchors supply positioning and pricing power for French enterprise cloud infrastructure, with three dominant providers controlling latency-critical capacity that underpins subscription pricing tiers across Ile-de-France financial services procurement.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects hyperscaler bundling strategies that compress standalone software margins. Three-tier pricing structure across enterprise, professional, and standard levels separates CNIL-certified sovereign cloud deployments from standard EU-hosted alternatives. Pricing pressure stems from outcome-based contracting mandates in French public sector RFPs. Government agencies exhibit highest price sensitivity due to multi-year budget cycles, while banking CIOs prioritize latency guarantees over unit cost.
Supply Chain Analysis
MLOps engineer scarcity in French metropolitan technology corridors constrains delivery capacity for AI implementation projects. Hardware supply concentrates in Taiwan, South Korea, and USA for GPU accelerators and advanced networking equipment. Specialized silicon and high-bandwidth memory components feed from concentrated Asian foundry capacity. Single-source vulnerability around NVIDIA data center GPUs creates procurement queue risk. Distribution runs through systems integrator-led channel structures with direct hyperscaler relationships for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France digital transformation operates as a supply-constrained market where MLOps talent scarcity props pricing for implementation services and extends project timelines across all buyer tiers.
For Market Incumbents: To counter fintech-native challengers eroding core banking modernization contracts, Capgemini and Atos should deepen ministerial relationship moats through ANSSI-cleared security certifications while building captive AI training capacity in Lyon and Toulouse technology parks to reduce consulting dependency.
For New Entrants and Emerging Players: Digital-channel route through regional hospital procurement consortia offers the most penetrable entry vector, with ANSM traceability compliance gaps in Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine creating whitespace for subscription-based pharmaceutical supply chain platforms with built-in audit documentation.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global hyperscalers seeking EU sovereign cloud credentials. Long-term viability hinges on compliance tooling differentiation rather than infrastructure ownership. Watch CNIL enforcement intensity against non-EU data transfers as the inflection signal for sovereign cloud valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Investment | Qualification timelines bottleneck critical infrastructure deployments in energy and transport sectors. |
| EU AI Act Compliance Tooling | Documentation platforms capture margin pools from high-risk automated decision system mandates. |
| Paris-Saclay Facility Partnership | Sub-100-millisecond latency guarantees anchor financial services procurement decisions. |
| Regional Hospital Consortium Consolidation | Multi-year platform subscriptions with upgrade paths lock out competing vendors. |
| Edge-AI Federated Learning Pilots | Manufacturing facilities in Hauts-de-France enable new service models for automotive suppliers. |
Research Methodology
Regulatory filings, hyperscaler capex disclosures, and French public procurement databases formed the secondary backbone, supplemented by primary interviews with CTOs at Ile-de-France financial institutions, IT procurement officers in regional hospital networks, platform engineers at Paris-Saclay facility operators, and integration specialists serving manufacturing clients. Bottom-up project pipeline analysis triangulated against top-down technology spending surveys.
Historical trendline analysis across technology adoption curves informed projection frameworks, with segmentation modeling across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from weighted average of technology-specific penetration trajectories. Forecast inputs incorporated EU AI Act implementation timelines and CNIL enforcement patterns.
The model holds under stable regulatory enforcement; deviation in ANSSI qualification delays or GDPR territoriality rulings would shift deployment timelines. Forecasts reflect documented assumptions about cloud migration velocity and AI adoption thresholds. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Workspace Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Latin America Digital Transformation Market