
 Telco Transformation Market | 2026-2036
Telco Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Telco Transformation Market Analytics
Enterprise manufacturing is pivoting toward private 5G and network slicing, pulling carrier capex away from residential broadband. Deutsche Telekom AG anchors European network virtualization through its Open RAN labs in Berlin and Bonn. SK Telecom Co., Ltd. leads AI-driven operations with its proprietary network automation platform deployed across Korean industrial zones. Bharti Airtel Group extends its cloud infrastructure footprint through distributed edge nodes serving African enterprise corridors.
Telco transformation encompasses the architectural overhaul of legacy circuit-switched infrastructure into software-defined, cloud-native platforms operating at sub-10 millisecond latency thresholds for mission-critical applications. The primary purpose centers on enabling programmable network slices with guaranteed service-level agreements for differentiated enterprise verticals. Cloud infrastructure and AI-driven operations capture expanding margin pools as carriers shift from connectivity resale to platform-as-a-service models. Edge computing within the technology dimension exhibits the steepest adoption curve, driven by autonomous systems and real-time analytics requirements in logistics and healthcare.
FCC spectrum auctions in the United States, EU Digital Networks Act provisions on open interfaces, and India's TRAI recommendations on infrastructure sharing collectively reshape competitive access and interoperability mandates. These frameworks force incumbents to unbundle proprietary stacks while creating entry points for specialized software vendors. Stakeholders must monitor whether regulatory pressure on open RAN interoperability outpaces vendor readiness for multi-supplier integration at production scale.
Market Dynamics
Enterprise demand for deterministic network performance is forcing carriers to dismantle monolithic infrastructure in favor of disaggregated, software-defined stacks. The shift from connectivity resale to platform-as-a-service models compresses legacy revenue streams while opening margin pools in edge orchestration and AI-driven automation.
Growth Catalysts
- EU Digital Networks Act:Mandates on open network interfaces accelerate vendor diversification and reduce incumbent lock-in across European carrier procurement.
- Industrial automation:Manufacturing facilities in Germany, South Korea, and the United States deploy private 5G slices for robotic coordination and predictive maintenance workflows.
- Edge computing infrastructure:Distributed micro-data centers enable sub-10 millisecond latency for autonomous logistics and real-time healthcare diagnostics.
Market Restraints
- Semiconductor supply concentration:Advanced networking silicon fabrication concentrates in Taiwan, creating geopolitical exposure for baseband and radio component sourcing.
- Multi-vendor integration complexity:Open RAN interoperability gaps between radio units, distributed units, and centralized units delay production deployments.
- Legacy debt burden:Circuit-switched voice infrastructure and proprietary OSS/BSS systems require sustained operational expenditure during parallel cloud-native migration.
Strategic Opportunities
- India's production-linked incentive scheme:Domestic telecom equipment manufacturing subsidies attract global vendors to establish local assembly and R&D facilities.
- Network-as-a-service models:API-driven programmable slices allow carriers to monetize guaranteed latency tiers for financial trading and cloud gaming applications.
- AI-operations convergence:Machine learning for predictive fault detection and energy optimization integrates with existing network automation platforms.
Industry Challenges
- Cloud-native engineering scarcity:Container orchestration, Kubernetes networking, and microservices architecture skills outpace carrier workforce development pipelines.
- Certification timeline compression:Multi-vendor Open RAN deployments require extended interoperability testing against 3GPP and O-RAN Alliance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telco Transformation Market |
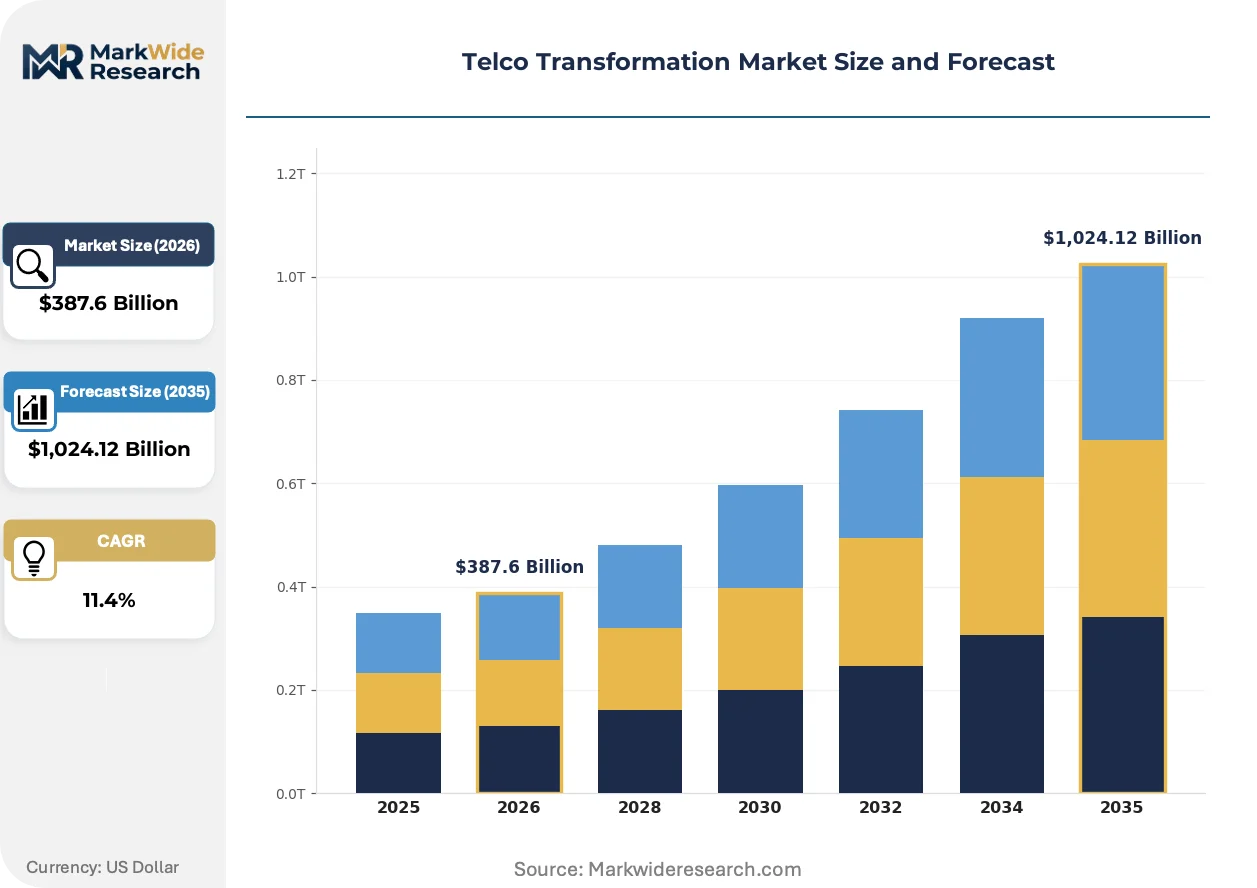
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 5G Expansion, Network Slicing, Cloud Infrastructure, AI-Driven Operations Technology: Virtualization, SD-WAN, IoT Connectivity, Edge Computing Customer Type: Enterprises, Government, Residential Users, Wholesale Providers Deployment Model: On-Premises, Public Cloud, Hybrid Cloud, Managed Services |
| Companies Covered | AT&T Group, Deutsche Telekom AG, Vodafone Group Plc, Bharti Airtel Group, MTN Group, America Movil Group, SK Telecom Co., Ltd., NTT Docomo, Inc., Telefónica, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telco Transformation Market Evolving Landscape
Disaggregation of the radio access network is rewriting competitive boundaries between hardware specialists and software vendors. Three concurrent developments dominate carrier technology roadmaps and supplier selection criteria.
Open RAN specifications and cloud-native baseband software is rewriting how carriers architect their mobile access layers. Tier-1 operators in Japan, Germany, and the United States now mandate virtualized radio access in new spectrum deployments. This compression of proprietary hardware margins forces incumbent infrastructure vendors to pivot toward software licensing and managed services.
REACH chemical restrictions and the EU AI Act impose new compliance layers on network equipment supply chains and automated decision systems. Equipment vendors must now document substance composition for radio hardware and algorithmic transparency for traffic management AI. European carriers are responding by embedding sustainability and explainability requirements directly into procurement tenders.
Enterprise buyers now contract for guaranteed service outcomes rather than raw bandwidth commitments. Manufacturing and logistics clusters in the United States, South Korea, and Germany negotiate latency-bound SLAs for specific industrial applications. This unbundling of connectivity from performance assurance shifts risk onto carriers and rewards those with edge computing density and real-time analytics capabilities.
Telco Transformation Market Segmentation
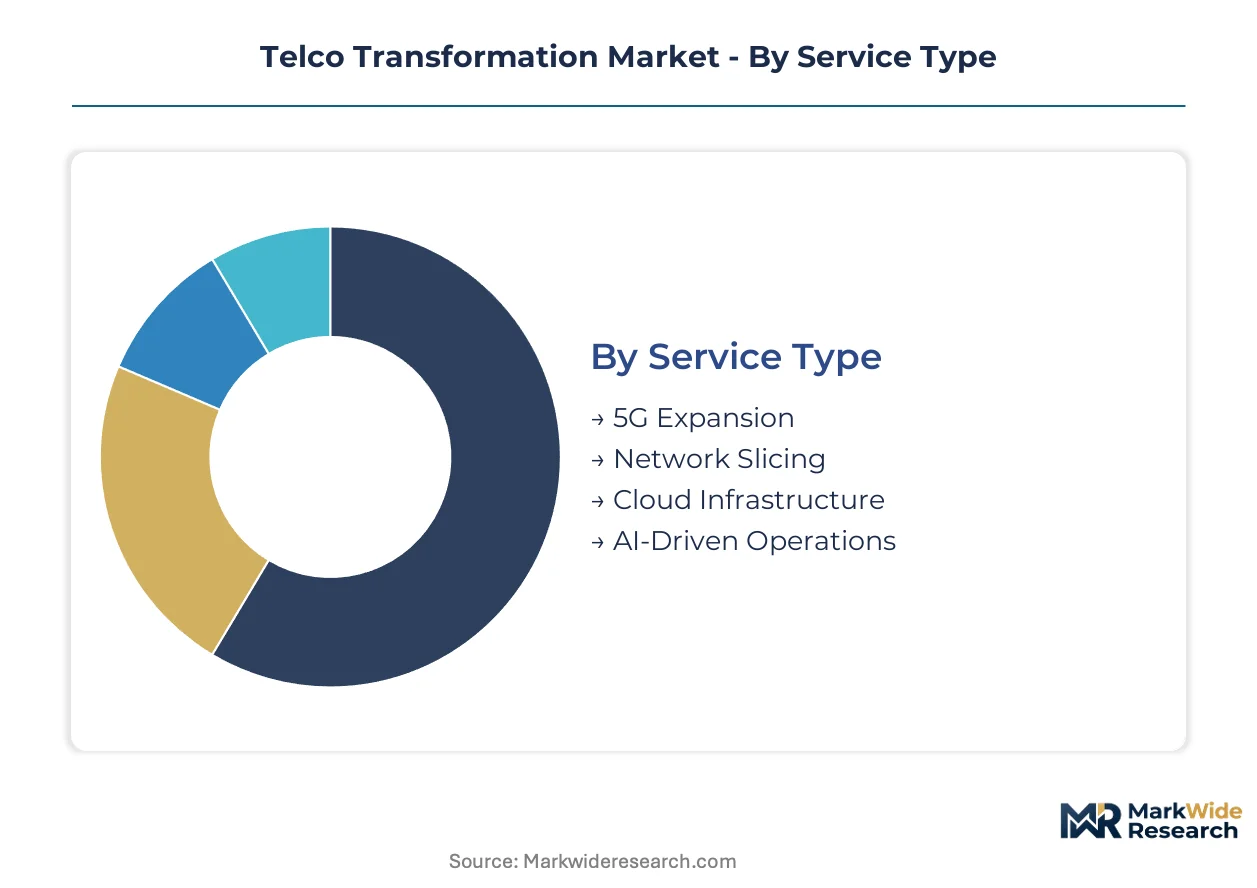
Segmentation in telco transformation reveals where capital deployment concentrates and how carriers rebalance infrastructure spending across competing priorities. Each dimension exposes different margin structures, from high-touch managed services to commoditized connectivity resale.
Service Type:
Capital intensity varies sharply across service categories, with physical infrastructure builds demanding multiyear investment horizons while software layers monetize faster.
- 5G Expansion:Macro and small-cell deployments absorb spectrum acquisition costs, civil works, and radio hardware. Manufacturing corridors in Germany and South Korea contract for dedicated campus networks with guaranteed latency thresholds.
- Network Slicing:Virtualized partition creation enables guaranteed service-level agreements for differentiated verticals. Financial trading venues in Singapore and autonomous logistics hubs in the United States purchase deterministic performance tiers rather than raw bandwidth.
- Cloud Infrastructure:Distributed compute pools support containerized network functions and subscriber data management.
- AI-Driven Operations:Predictive fault detection and energy optimization algorithms reduce operational expenditure.
5G Expansion absorbs the bulk of installed capacity; Network Slicing is expanding most quickly.
Technology:
Technology selection determines vendor lock-in exposure and the pace at which carriers can disaggregate proprietary hardware stacks.
- Virtualization:Cloud-native baseband software replaces purpose-built appliances, compressing hardware margins and accelerating feature deployment cycles. European carriers under EU Digital Networks Act mandates now require open interfaces in procurement tenders.
- Edge Computing:Micro-data centers positioned within 10 milliseconds of end-users enable real-time healthcare diagnostics and industrial robotic coordination. German automotive clusters and Korean smart factory zones drive dense edge node deployment.
- SD-WAN:Software-defined overlay networks simplify enterprise branch connectivity management.
- IoT Connectivity:Massive machine-type communications modules serve agricultural sensors and utility metering infrastructure.
Virtualization dominates current carrier procurement volumes; Edge Computing shows the steepest adoption trajectory.
Customer Type:
Customer mix shapes pricing power, with enterprise buyers accepting outcome-based contracts while residential segments resist rate increases.
- Enterprises:Manufacturing, logistics, and financial services buyers negotiate latency-bound service-level agreements with penalty clauses. Private 5G deployments for robotic coordination in Stuttgart and predictive maintenance in Detroit command premium pricing.
- Government:Critical infrastructure protection and emergency communications networks require sovereign data residency and certified supply chains.
- Residential Users:Price-sensitive broadband subscribers drive volume but compress margins.
- Wholesale Providers:Mobile virtual network operators and regional carriers purchase bulk capacity for resale.
Enterprises generate the highest revenue per connection; Government contracts deliver the longest tenure.
Deployment Model:
Deployment architecture determines operational control boundaries and the distribution of cybersecurity responsibility between carrier and customer.
- Managed Services:End-to-end outsourcing of network operations, security monitoring, and performance optimization transfers operational risk to vendors. Mid-market enterprises in France and Canada lacking internal cloud-native engineering expertise favor this model.
- Hybrid Cloud:Split workloads between on-premises infrastructure and public cloud platforms balance latency requirements with scalability. Healthcare providers in Sydney and logistics operators in Dubai deploy sensitive data processing locally while bursting analytics to cloud.
- On-Premises:Fully captive infrastructure serves defense and classified government applications.
- Public Cloud:Multi-tenant network function virtualization reduces capital expenditure for smaller carriers.
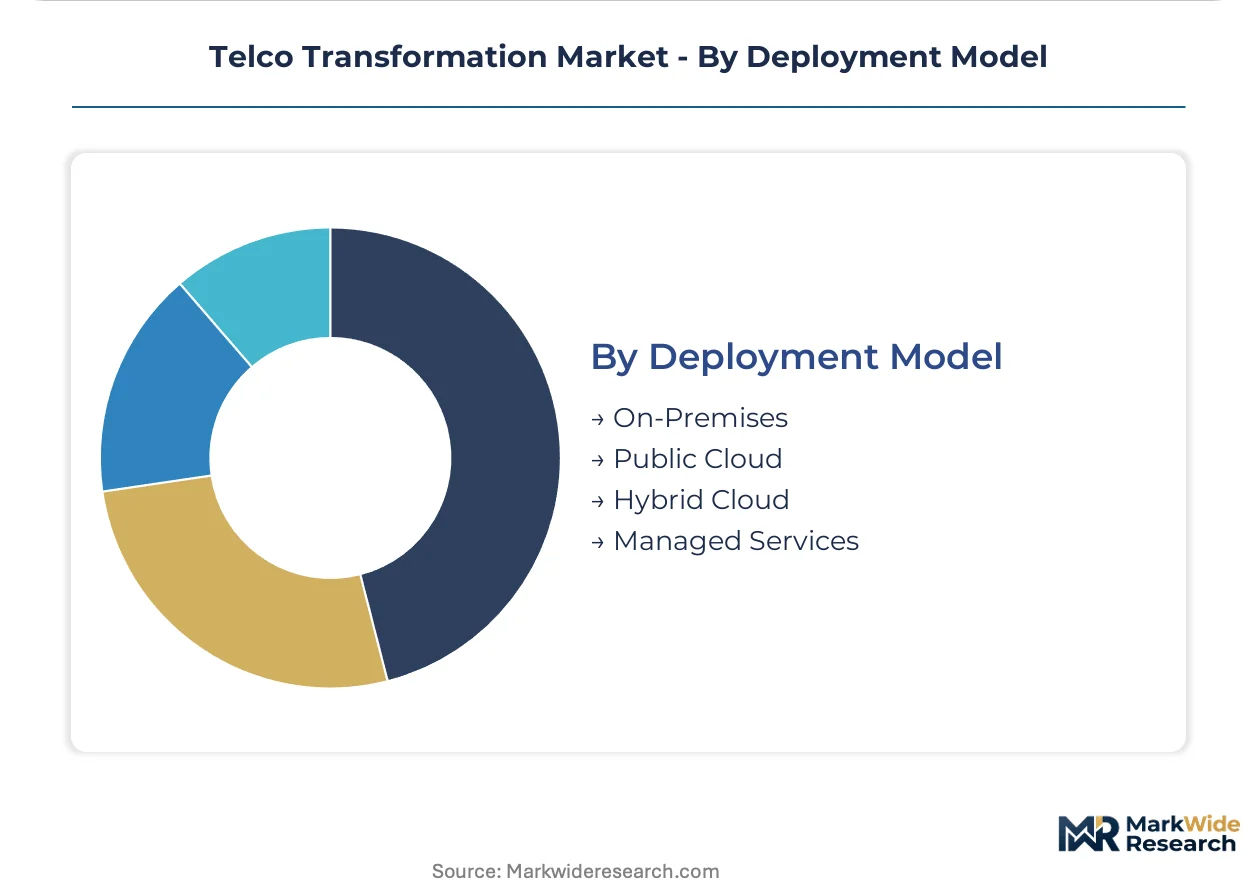
Managed Services captures the largest contract value; Hybrid Cloud is climbing the fastest as enterprises straddle legacy and cloud-native systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Germany are concentrating telco transformation investment through production-linked incentives and open RAN research facilities. These zones attract vendor assembly operations and carrier innovation labs alike. Government programs in South Korea and the United States complement this pattern with dedicated spectrum for industrial automation.
United States
FCC spectrum auctions for mid-band 5G are directing carrier capex toward private network deployments for manufacturing and logistics. The Inflation Reduction Act provisions on domestic semiconductor fabrication reduce exposure to Taiwan-based baseband silicon sourcing. Detroit automotive clusters and Houston energy corridors now contract for guaranteed latency SLAs through dedicated network slices.
Germany
Industrial automation demand from automotive and machinery sectors is accelerating Open RAN procurement under EU Digital Networks Act mandates. REACH chemical restrictions and the EU AI Act impose compliance layers on radio hardware supply chains and traffic management algorithms. Stuttgart manufacturing zones and Munich industrial corridors deploy private 5G for robotic coordination and predictive maintenance workflows.
India
Reliance Jio's aggressive fiber rollout and government production-linked incentives are accelerating domestic vendor ecosystem formation. TRAI recommendations on infrastructure sharing reshape competitive access rules while reducing barriers for new entrants. Bangalore technology corridors and Gujarat special economic zones attract global equipment manufacturers establishing local assembly and R&D facilities.
South Korea
AI-driven network operations are scaling through proprietary automation platforms deployed across industrial zones. The national regulator advances spectrum policies supporting mission-critical communications for smart factories. Busan port logistics clusters and Seoul metropolitan manufacturing belts demand sub-10 millisecond latency for autonomous systems and real-time analytics.
Japan
NTT Docomo's network virtualization programs anchor regional cloud-native infrastructure development. METI industrial policy promotes Open RAN interoperability standards to reduce vendor lock-in in procurement tenders. Nagoya automotive production zones and Osaka industrial corridors integrate edge computing nodes for robotics and quality control applications.
Telco Transformation Market Competitive Landscape
Top-tier vendors anchor carrier-grade infrastructure supply, while mid-tier specialists capture Open RAN software and edge orchestration niches. The competitive structure fragments across three strategic archetypes: integrated national carriers with captive network engineering, specialized virtualization software vendors, and regional equipment assemblers serving price-sensitive markets. Dominant competitive moves include strategic partnerships for multi-vendor interoperability certification and geographic expansion through local production incentives.
Within the integrated carrier tier, Deutsche Telekom AG and SK Telecom Co., Ltd. exemplify operators that have internalized cloud-native engineering capabilities and AI-driven automation platforms. Bharti Airtel Group occupies a position bridging infrastructure ownership with distributed edge node deployment across emerging market corridors. These three entities represent distinct geographic anchors—European open-interface mandates, East Asian industrial automation density, and South Asian production-linked incentive zones—each shaping procurement patterns that cascade through their supplier ecosystems.
| Leading Market Players |
|---|
| AT&T Group |
| Deutsche Telekom AG |
| Vodafone Group Plc |
| Bharti Airtel Group |
| MTN Group |
| America Movil Group |
| SK Telecom Co., Ltd. |
| NTT Docomo, Inc. |
| Telefónica, S.A. |
| Others |
Value Network & Pricing Analysis
Enterprise manufacturing buyers in Germany, South Korea, and the United States negotiate latency-bound service-level agreements with penalty clauses, anchoring a performance-tiered pricing model where guaranteed sub-10 millisecond thresholds command substantial premiums over best-effort connectivity resale.
Pricing Analysis
Short lead-time premiums for certified Open RAN hardware and cloud-native baseband software separate urgent deployment timelines from standard procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against O-RAN Alliance specifications and geographic delivery cost from Taiwan-based silicon foundries. Price differentiation intensifies as carrier procurement teams consolidate vendor panels under EU Digital Networks Act mandates. Residential broadband subscribers exhibit highest price sensitivity, while financial trading venues in Singapore and autonomous logistics operators accept outcome-based premiums.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced networking silicon fabrication, creating geopolitical exposure for baseband and radio component sourcing. Taiwan, South Korea, and the United States anchor semiconductor supply for radio units, distributed units, and centralized units. Raw material dependencies span gallium nitride substrates, high-frequency RF filters, and specialized thermal management alloys. Tariff exposure on Chinese-assembled radio hardware feeds into procurement cost compression. Distribution runs through carrier-direct procurement teams, systems integrators, and emerging domestic assemblers in India's production-linked incentive zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
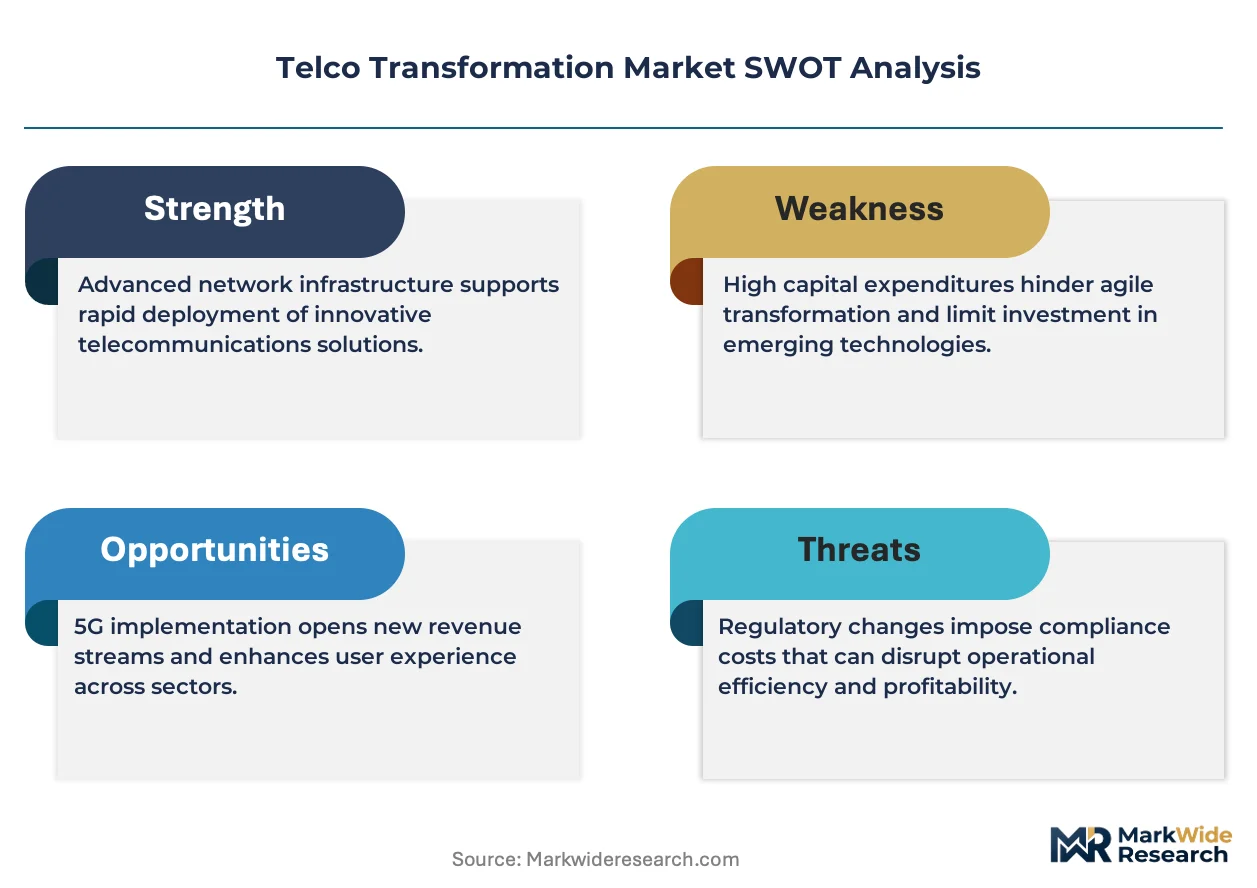
This market consolidates around carriers with captive cloud-native engineering capabilities, as multi-vendor integration complexity and legacy debt burdens force weaker players toward managed service exits or asset divestitures.
For Market Incumbents: To counter Open RAN interoperability gaps delaying production deployments, Deutsche Telekom and SK Telecom should deepen backward integration into proprietary automation platforms and expand Berlin-Bonn lab certification capacity for multi-supplier integration. Capacity addition in India's special economic zones captures production-linked incentive subsidies while reducing exposure to Taiwan silicon concentration. For New Entrants and Emerging Players: The mid-tier price-point gap between premium carrier-managed slices and economy wholesale connectivity creates entry space for specialized edge orchestration vendors targeting French and Canadian mid-market enterprises lacking internal Kubernetes networking expertise. White-space concentration sits in API-driven network-as-a-service models for cloud gaming and financial trading applications. Go-to-market execution should anchor on interoperability certification against O-RAN Alliance specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional equipment assemblers with captive domestic manufacturing in India's PLI zones and established carrier relationships. Long-term viability across the analysis window rests on software licensing transition velocity away from proprietary hardware margins. The signal to watch is carrier procurement mandate timing for open interface requirements under EU Digital Networks Act enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | Multi-vendor integration testing against O-RAN Alliance specifications accelerates production deployment timelines for European carriers. |
| Edge Node Density Expansion | Micro-data center positioning within 10 milliseconds of German automotive clusters enables latency-guaranteed service tier monetization. |
| Domestic Manufacturing Localization | India's production-linked incentive scheme attracts global vendors to Bangalore and Gujarat assembly facilities. |
| AI-Operations Platform Development | Proprietary network automation deployment across Korean industrial zones compresses operational expenditure for mission-critical slices. |
| API-Driven Network-as-a-Service Launch | Programmable slice monetization for financial trading venues in Singapore shifts carrier revenue from connectivity resale to platform services. |
Research Methodology
Regulatory filings from the FCC, EU Digital Networks Act implementation documents, and TRAI recommendation papers formed the secondary backbone, supplemented by customs data on telecom equipment trade flows and carrier capex disclosure statements. Primary interviews with carrier network engineering directors, Open RAN procurement leads, systems integration specialists, and edge computing infrastructure vendors combined with secondary validation. Bottom-up and top-down triangulation cross-checked vendor shipment data against carrier deployment announcements.
Bottom-up modeling aggregated individual carrier procurement patterns and vendor contract values across service type, technology, and deployment model dimensions. Top-down validation referenced aggregate spectrum auction proceeds and infrastructure investment disclosures from national regulators. Segmentation dimensions modeled encompassed service type, technology selection, customer archetype, and deployment architecture. CAGRs were derived from fitted growth curves against historical deployment trajectories, with Open RAN adoption rates and private 5G slice penetration serving as industry-specific forecast inputs.
Inputs from carrier procurement databases and vendor certification registries were available through the study window; gaps in multi-vendor production deployment timelines introduce uncertainty bands around Open RAN market penetration assumptions. Forecasts reflect documented carrier technology roadmaps and regulatory enforcement schedules. Semiconductor supply concentration, geopolitical trade policy shifts, and cloud-native engineering scarcity represent specific risk factors that could revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Innovation Management Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market