
 Mexico Digital Transformation Market | 2026-2036
Mexico Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital Transformation Market Insights
Buyer concentration among Mexico's largest enterprises is recalibrating as mid-market manufacturers and regional banks fragment into discrete digital procurement clusters. Microsoft Corporation leverages its Azure cloud infrastructure to anchor public-sector modernization contracts across federal agencies. IBM Corporation sustains mainframe-to-cloud migration services for legacy-dependent financial institutions. Google LLC competes through AI and data analytics platforms tailored to Spanish-language enterprise search and consumer intelligence needs.
Mexico digital transformation encompasses the integration of cloud computing, artificial intelligence, internet-of-things sensors, and blockchain protocols into enterprise operational technology stacks, typically deployed via hybrid architectures spanning on-premise legacy systems and multi-tenant cloud environments to automate decision workflows and real-time data exchange. Cloud computing dominates current enterprise spending as the foundational layer enabling subsequent AI and IoT deployments, while blockchain remains nascent with concentrated pilot activity in supply chain traceability for agribusiness and automotive exporters. Managed services capture expanding margin pools as Mexican enterprises prioritize operational expenditure models over capital-intensive in-house digital infrastructure buildouts.
Federal telecommunications regulator IFT governs spectrum allocation and data center interconnection standards that shape cloud service provider market access, while Mexico's national data protection authority INAI enforces cross-border data transfer restrictions compelling localization strategies. The Secretariat of Economy's digital economy initiatives and NOM cybersecurity standards further condition enterprise procurement requirements for certified vendors. Stakeholders must monitor pending amendments to Mexico's Federal Law on Protection of Personal Data as these will determine compliance costs for AI training datasets and biometric authentication deployments.
Market Dynamics
Federal mandates from the Secretariat of Economy and INAI's cross-border data localization rules are forcing Mexican enterprises to rebuild operational technology stacks around domestic cloud infrastructure and certified cybersecurity architectures.
Growth Catalysts
- NOM Cybersecurity Standards:Mandatory certification requirements for critical infrastructure operators are accelerating replacement cycles for legacy operational technology systems across energy and financial sectors.
- Bajío Manufacturing Corridor:Industrial IoT deployments in Guanajuato and Querétaro automotive plants are creating concentrated demand for edge computing and predictive maintenance platforms.
- Cloud-First Federal Procurement:Public-sector modernization directives are redirecting government IT budgets toward multi-tenant infrastructure and software-as-a-service delivery models.
Market Restraints
- Specialized Talent Scarcity:Mexico produces insufficient certified cloud architects and AI/ML engineers to match deployment timelines, extending implementation cycles by 40-60 percent.
- Legacy Mainframe Dependency:Core banking systems at major financial institutions remain bound to on-premise infrastructure, constraining hybrid cloud migration velocity.
- Input Cost Volatility:Data center construction faces fluctuating prices for GPU clusters and specialized cooling equipment, compressing margins for infrastructure providers.
Strategic Opportunities
- Yucatán Peninsula Digital Hub:Underdeveloped fiber connectivity and submarine cable landing points in Mérida offer greenfield cloud region expansion outside saturated Mexico City markets.
- Agribusiness Blockchain Traceability:Export compliance requirements for US and EU markets are driving pilot programs linking IoT sensors to distributed ledger systems for avocado and berry supply chains.
- AI-Enabled Regulatory Compliance:Convergence of natural language processing and robotic process automation is automating INAI-mandated data subject access request workflows for mid-market enterprises.
Industry Challenges
- Interoperability Friction:Integration complexity between decades-old ERP systems and modern API-first cloud platforms consumes 30-40 percent of project budgets.
- Certification Timeline Compression:INAI's evolving biometric authentication guidelines create uncertainty for facial recognition deployments in financial services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital Transformation Market |
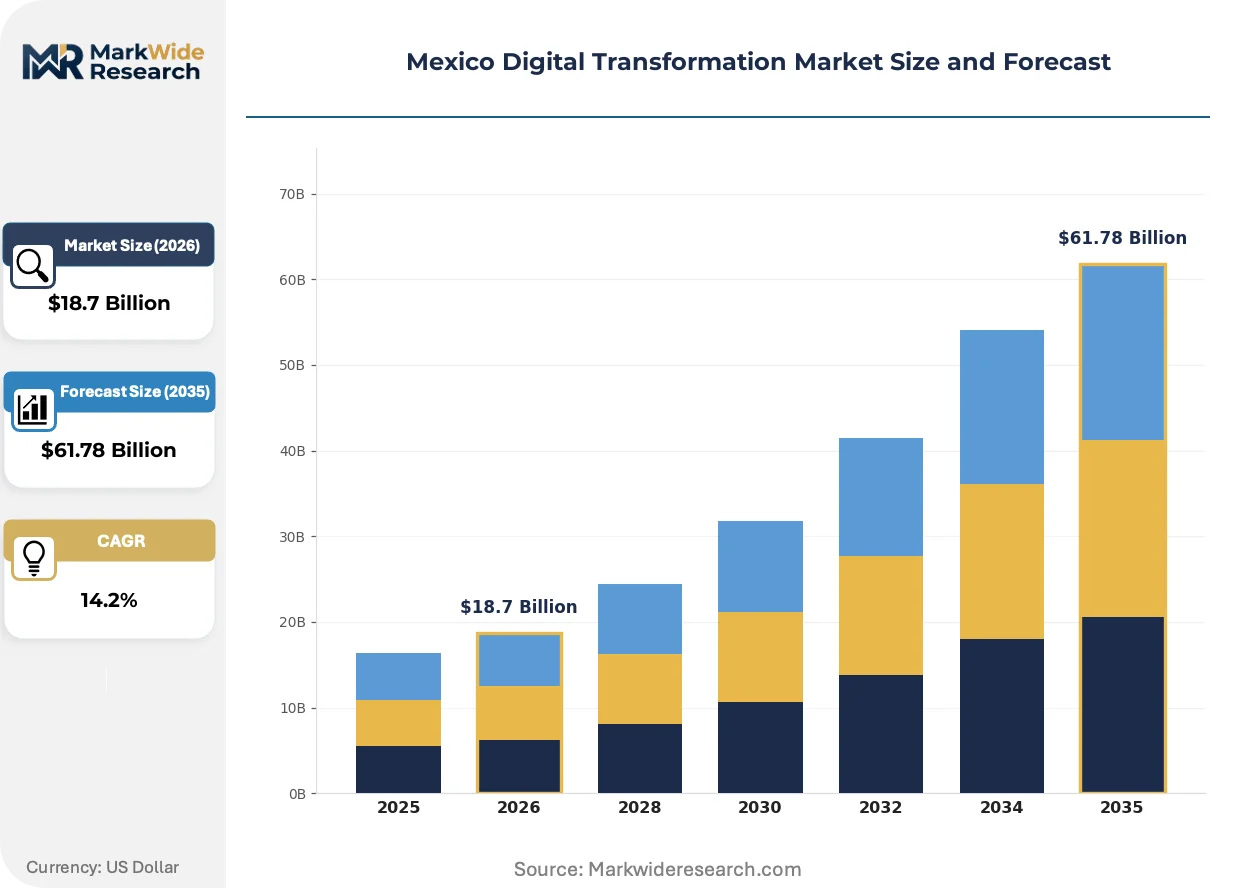
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, IoT, Blockchain Service Type: Consulting, Integration Services, Managed Services, Implementation End User: Retail, Healthcare, Manufacturing, Financial Services Application: Supply Chain Management, Customer Relationship Management, Data Analytics, Human Resource Management |
| Companies Covered | Google LLC (Alphabet Inc.), IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Oracle Corporation, Accenture PLC, Adobe Inc, SAP SE, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital Transformation Market Trends and Innovations
Edge computing architectures and sovereign cloud deployments are restructuring how Mexican enterprises balance latency requirements against data residency obligations. Three developments are reconfiguring competitive positioning.
Industrial edge computing is converging with 5G private networks to enable real-time quality control in automotive assembly plants. Tier-one manufacturers in Guanajuato are deploying millimeter-wave sensors connected to on-premise inference engines. This convergence is compressing defect detection cycles from hours to milliseconds while keeping sensitive production data within facility perimeters.
IFT's revised spectrum allocation framework for 6 GHz band access is expanding unlicensed capacity for enterprise wireless backhaul. Industrial facilities are reallocating capital from wired infrastructure toward flexible mesh networks. Manufacturing clusters in Querétaro and Puebla are most affected, with plant engineers redesigning shop floor layouts around untethered sensor mobility.
Mid-market manufacturers are unbundling digital transformation projects from single-vendor systems integrators. Discrete procurement of specialized AI, IoT, and cybersecurity modules is displacing comprehensive outsourcing arrangements. This pattern is most visible in Mexico City's food processing and packaging verticals, where procurement teams now directly contract niche SaaS providers for specific operational workflows.
Mexico Digital Transformation Market Segmentation
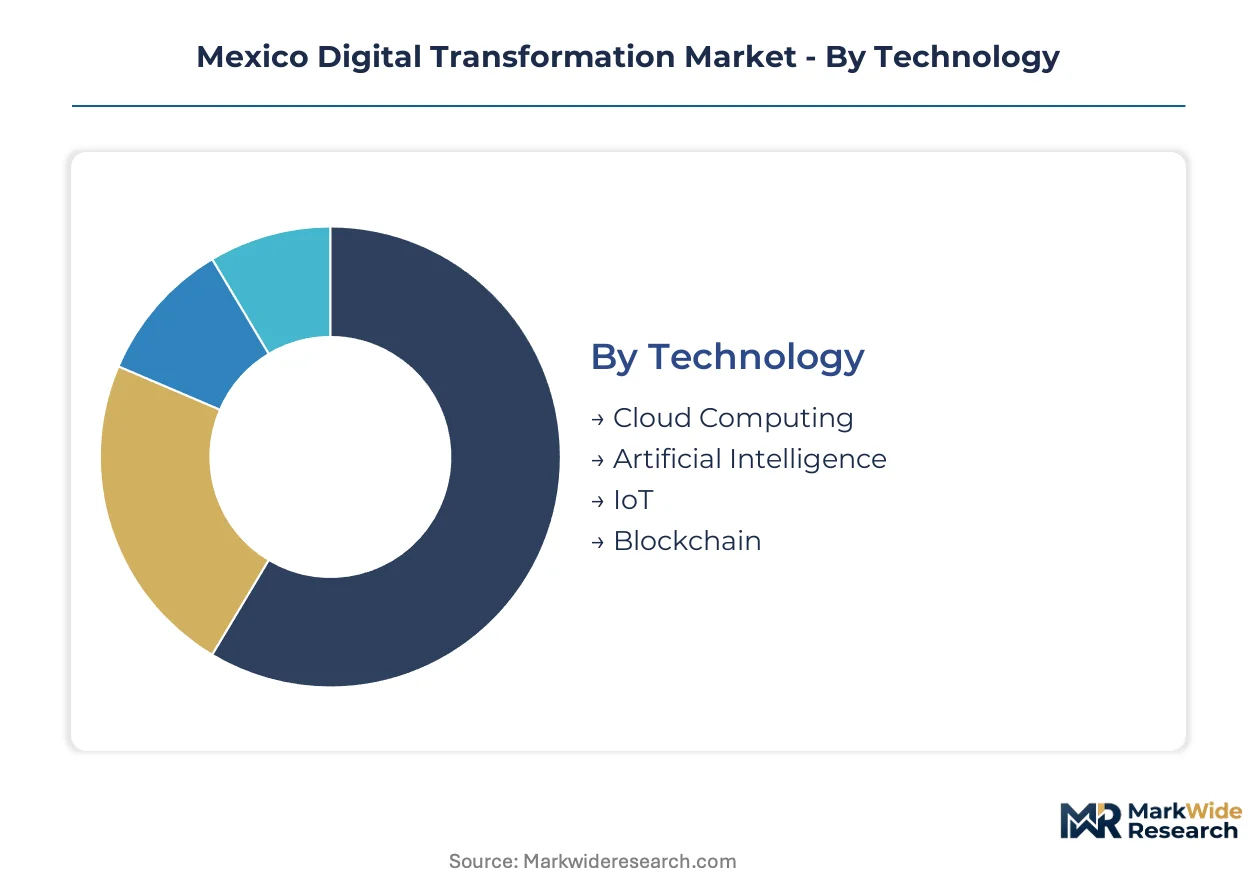
Mexican enterprises fragment their digital procurement across technology layers, service delivery models, and operational use cases. Understanding these divisions reveals where capital concentrates and where vendor competition intensifies.
Technology:
Capital intensity varies sharply across this dimension, with infrastructure-heavy deployments demanding multi-year amortization against lighter software-only implementations.
- Cloud Computing:Multi-tenant infrastructure and hybrid orchestration platforms form the foundational layer for subsequent AI and IoT deployments. Mexican financial institutions and federal agencies concentrate spending here as INAI data localization rules force domestic data center expansion.
- Artificial Intelligence:Machine learning operations platforms and natural language processing engines automate decision workflows in Spanish-language enterprise environments. Demand clusters among Mexico City-based banks and insurers seeking to modernize customer service and risk scoring.
- IoT:Industrial sensor networks and edge inference hardware connect operational technology systems to enterprise data lakes.
- Blockchain:Distributed ledger protocols enable supply chain traceability for agribusiness and automotive exporters facing US and EU compliance requirements.
Most installed capacity flows through Cloud Computing. Expansion is steepest in Artificial Intelligence.
Service Type:
Procurement patterns reveal enterprise preferences for operational expenditure models over capital-intensive in-house builds.
- Managed Services:Long-term operational contracts covering infrastructure monitoring, security operations, and platform maintenance. Mid-market manufacturers in the Bajío corridor favor this model to bypass certified talent scarcity in cloud architecture.
- Integration Services:API middleware deployment and legacy system connectivity projects bridge decades-old ERP installations with modern cloud platforms. These engagements consume disproportionate budget share due to interoperability friction in Mexican financial institutions.
- Consulting:Strategy advisory and digital roadmap development for enterprises navigating federal digitalization mandates.
- Implementation:Project-based deployment of specific technology modules with defined acceptance criteria and knowledge transfer obligations.
Revenue concentration sits with Managed Services. Integration Services claims the fastest margin expansion.
End User:
Vertical-specific compliance requirements and operational technology maturity shape demand heterogeneity across Mexican industries.
- Financial Services:Core banking modernization, biometric authentication systems, and regulatory reporting automation. INAI cross-border data rules and NOM cybersecurity standards force continuous infrastructure refresh cycles at major institutions.
- Manufacturing:Industrial IoT deployments, predictive maintenance platforms, and smart factory architectures. Automotive plants in Guanajuato and Querétaro drive concentrated demand for edge computing and private 5G networks.
- Healthcare:Electronic health record interoperability and telemedicine infrastructure expansion.
- Retail:Omnichannel commerce platforms and customer data platforms for loyalty optimization.
Financial Services anchors current spending. Manufacturing demonstrates the steepest expansion trajectory.
Application:
Use-case prioritization reflects where Mexican enterprises expect measurable operational returns against compliance-driven investments.
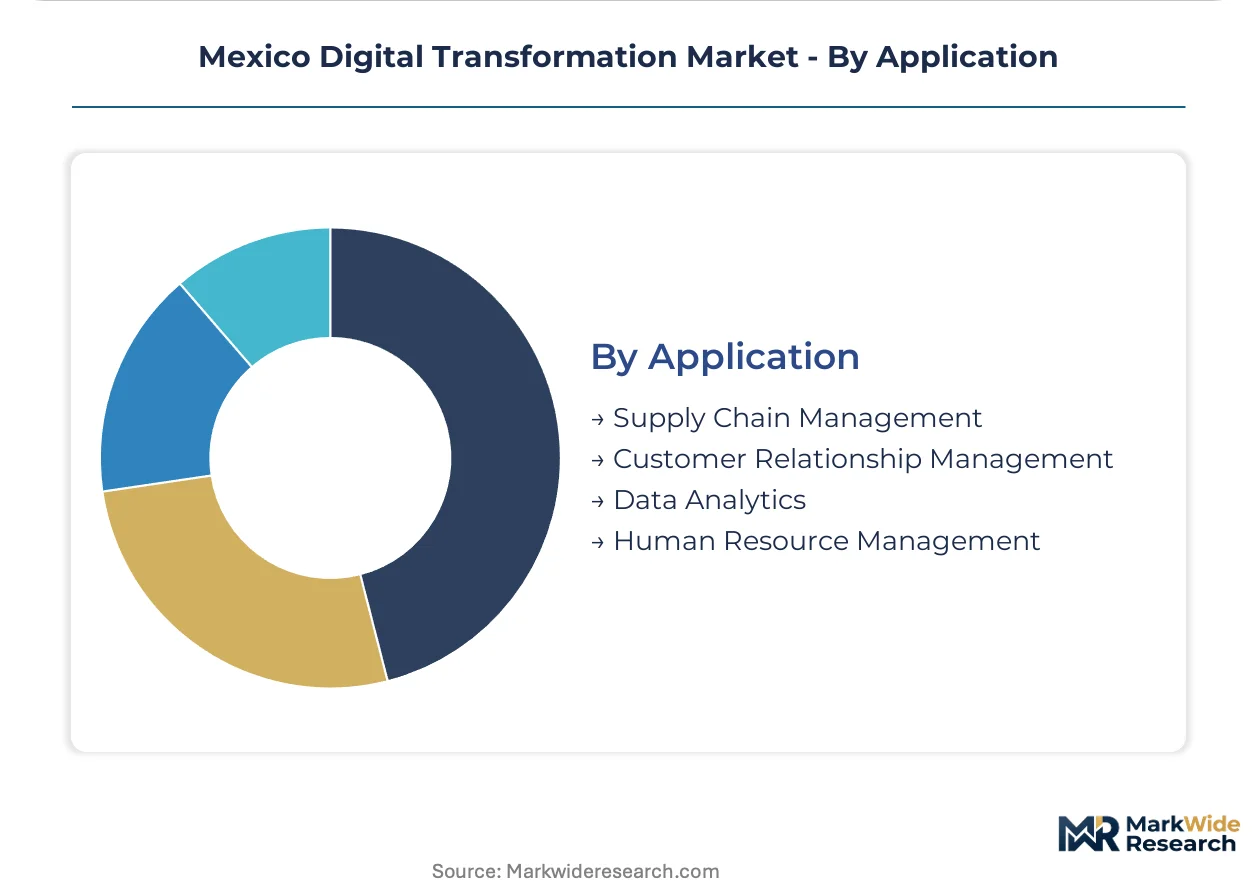
- Data Analytics:Business intelligence platforms, real-time dashboards, and predictive modeling environments processing operational and customer data. Manufacturing clusters and financial institutions both prioritize this capability for competitive differentiation.
- Supply Chain Management:End-to-end visibility platforms linking procurement, logistics, and distribution with IoT sensor feeds. Agribusiness exporters in Michoacán and Jalisco deploy these systems to satisfy US and EU traceability mandates.
- Customer Relationship Management:Sales force automation and service desk platforms with Spanish-language natural language processing.
- Human Resource Management:Workforce planning, payroll automation, and talent acquisition platforms adapted to Mexican labor law requirements.
Data Analytics captures the largest share of enterprise budgets. Supply Chain Management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada accelerates federal cloud procurement faster than Mexico, yet both nations confront similar data sovereignty mandates from their respective national regulators. Mexico's digital transformation concentrates in three distinct economic corridors, each shaped by local industrial composition and federal compliance requirements.
Mexico City Metro
Financial services modernization and federal agency cloud migration dominate enterprise spending in the capital region. INAI's cross-border data localization rules compel domestic data center expansion among banks and insurers. Polanco and Santa Fe business districts host concentrated procurement of AI-enabled customer service platforms and regulatory compliance automation.
Bajío Region
Automotive manufacturing clusters in Guanajuato and Querétaro drive industrial IoT and edge computing deployment for real-time quality control. The Secretariat of Economy's smart factory incentives accelerate private 5G network installations. Silao and Apaseo el Grande assembly plants represent the densest concentration of predictive maintenance platform adoption in Mexican manufacturing.
Nuevo León
Monterrey-based conglomerates integrate cloud infrastructure across steel, cement, and beverage operations with emphasis on operational technology cybersecurity. State-level digital competitiveness programs complement federal NOM standards for critical infrastructure protection. San Pedro Garza García technology corridors attract managed services providers serving mid-market manufacturers.
Jalisco
Guadalajara's software development ecosystem feeds enterprise demand for Spanish-language AI and data analytics platforms. State government digital service mandates expand municipal cloud procurement beyond traditional federal channels. Zapopan technology parks concentrate boutique SaaS vendors serving regional agribusiness and food processing exporters.
Northern Border States
Maquiladora operations in Baja California and Chihuahua deploy supply chain traceability systems to satisfy US customs compliance requirements. Nearshoring manufacturing expansion strains existing telecommunications infrastructure, accelerating fiber and edge data center investment. Tijuana and Ciudad Juárez logistics hubs pilot blockchain-linked IoT sensors for cross-border shipment verification.
Mexico Digital Transformation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's digital transformation procurement landscape. The vendor base stratifies into three tiers: hyperscale cloud platforms anchoring infrastructure contracts, systems integrators bridging legacy-to-cloud migrations, and vertical SaaS providers targeting specific operational workflows. Consolidation pressure intensifies as mid-market manufacturers fragment procurement across discrete technology modules rather than comprehensive outsourcing arrangements. M&A activity concentrates on cybersecurity and AI talent acquisition, while strategic partnerships between global platforms and regional managed services providers expand geographic coverage.
Within the hyperscale infrastructure tier, Microsoft Corporation and Google LLC occupy positions as primary cloud platform anchors for federal and financial sector modernization. IBM Corporation exemplifies the legacy-to-cloud migration specialist archetype, sustaining mainframe transition services for established financial institutions. These three entities represent distinct competitive approaches: platform-native ecosystem expansion, AI-first data analytics positioning, and hybrid infrastructure orchestration respectively.
| Leading Market Players |
|---|
| Google LLC (Alphabet Inc.) |
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Oracle Corporation |
| Accenture PLC |
| Adobe Inc |
| SAP SE |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
INAI's biometric authentication guidelines gate qualified supply for facial recognition deployments while simultaneously creating premium-tier pricing access for vendors holding early compliance certifications. Mexican financial institutions face compressed procurement timelines as these mandates force simultaneous infrastructure refresh cycles.
Pricing Analysis
Capacity additions in Querétaro and Guanajuato data center zones are reshaping price floors for edge computing deployments. Three-tier pricing structure across premium, standard, and economy levels dominates cloud infrastructure procurement, with certification tier and after-sales service bundling as primary differentiation drivers. Cost compression in standard-tier managed services is intensifying because hyperscale providers are absorbing margin pressure to secure federal agency contracts. Mid-market manufacturers demonstrate highest price sensitivity, while federal agencies prioritize compliance certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Mexico City and Monterrey anchor hub-and-spoke patterns for enterprise hardware deployment. Supply concentrates in USA, Taiwan, and China for GPU clusters, edge inference hardware, and specialized cooling systems. Raw material dependencies span semiconductor wafers, lithium-ion battery cells, and precision optical sensors. Single-source vulnerability in NVIDIA GPU allocation creates procurement risk for AI training infrastructure providers. Distribution runs through certified systems integrators holding NOM cybersecurity credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's digital transformation market functions as a regulatory compounder, with INAI's evolving cross-border data localization mandates continuously refreshing enterprise procurement cycles. Federal digitalization directives from the Secretariat of Economy sustain demand velocity regardless of macroeconomic headwinds.
For Market Incumbents: Acquire certified cloud architecture talent pools to offset Mexico's specialized engineer scarcity. Consolidate position through backward integration into domestic data center development, bypassing construction cost volatility. Defend against emerging pure-play AI vendors by embedding regulatory compliance automation into managed service contracts. For New Entrants and Emerging Players: Begin with Yucatán Peninsula cloud region development, where fiber infrastructure gaps create greenfield expansion opportunities outside saturated Mexico City markets. Target mid-market food processing verticals in Jalisco for Spanish-language AI workflow automation. Pursue direct SaaS procurement channels as manufacturers unbundle from single-vendor integrators. For Investors and Strategic Acquirers: Roll-up economics work for regional managed services providers because mid-market procurement fragmentation creates multiple small-scale acquisition targets with sticky federal compliance revenue. Five-to-ten year viability hinges on sustained regulatory complexity expanding addressable spend per enterprise. Watch IFT spectrum allocation rulings for 6 GHz band access as inflection indicator for private 5G network deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Early INAI biometric compliance captures locked-in federal agency procurement pipelines. |
| Geographic Expansion | Mérida cloud region development exploits submarine cable landing point advantages. |
| Strategic Partnership | Hyperscaler alliances with regional integrators extend NOM-certified service coverage. |
| Product Launch | Spanish-language NLP engines address underserved financial services customer service automation. |
| Acquisition of Specialist Firm | AI/ML engineering boutiques fill certified talent gaps constraining implementation timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, IFT spectrum allocation records, and INAI regulatory bulletins. Bottom-up enterprise spending estimates triangulated against top-down federal budget allocation data.
Segment-weighting across technology layers, service delivery models, and end-use verticals shaped the analytical framework. Deployment model, organization size, integration complexity, and regional adoption patterns structured the segmentation grid. CAGRs derived from curve-fitting historical procurement trajectories against regulatory mandate implementation schedules. Cloud infrastructure spending velocity and AI/ML engineer supply constraints served as industry-specific forecast inputs throughout the projection horizon.
Several conditions sit outside the modeled scope, including potential amendments to Mexico's Federal Law on Protection of Personal Data, currency volatility effects on cross-border cloud service pricing, and geopolitical disruptions to semiconductor supply chains. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
France Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Innovation Management Market
Digital Transformation
Telco Transformation Market
Digital Transformation
SQL Server Transformation Market