
 South Korea Digital Transformation Market | 2026-2036
South Korea Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Digital Transformation Market Insights
Healthcare and financial services demand is rebalancing the South Korea digital transformation landscape as these verticals outpace traditional manufacturing IT spending. Samsung Electronics leverages its semiconductor and display captive demand to anchor domestic cloud infrastructure deployment. SAP SE competes through localized ERP suites tailored to Korean conglomerate governance structures. NAVER Cloud Corp. dominates the sovereign cloud segment, extending its KakaoTalk ecosystem integration into enterprise collaboration tools.
Digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and IoT sensors into enterprise operational technology, typically requiring API-first architectures and real-time data pipeline orchestration to replace legacy mainframe dependencies. Cloud computing and AI command the largest technology investment pools, though blockchain applications in supply chain traceability are expanding fastest from a smaller base. Within applications, customer experience platforms capture premium margins in retail and financial services, while cybersecurity spending matures as a compliance-driven baseline rather than a discretionary upgrade.
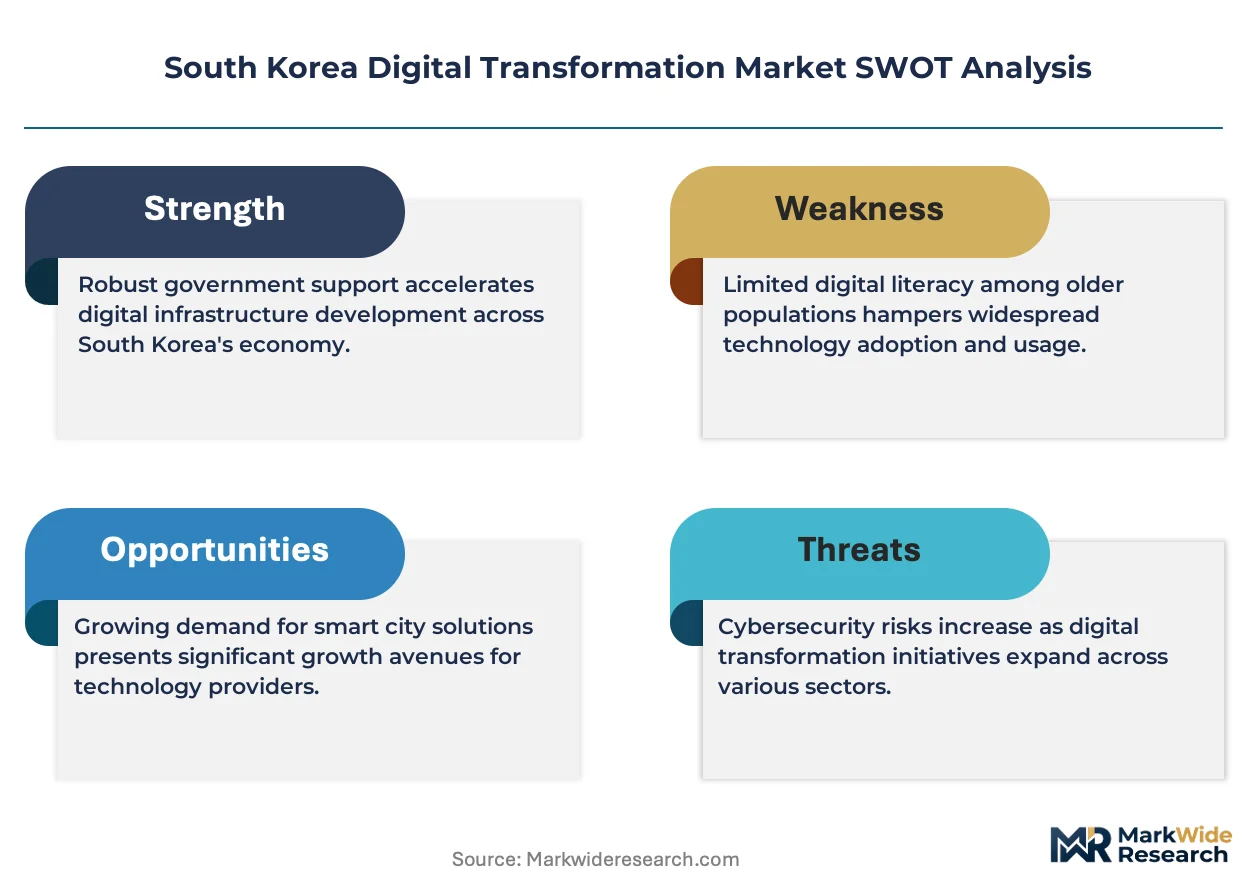
MFDS data governance rules, KISA cybersecurity certification frameworks, and the Personal Information Protection Act collectively shape product standards and vendor qualification requirements for domestic market access. The Digital New Deal policy office under the Ministry of Science and ICT channels procurement preferences toward domestic cloud providers meeting sovereign data residency mandates. Stakeholders must monitor whether upcoming amendments to the Network Act force operational technology segmentation between foreign hyperscalers and nationally certified infrastructure operators.
Market Dynamics
The South Korea Digital Transformation Market is being fundamentally restructured by the government's Digital New Deal framework, which channels public procurement toward domestic cloud providers meeting sovereign data residency mandates. This policy mechanism is compressing foreign hyperscaler access while accelerating domestic infrastructure deployment.
Growth Catalysts
- Digital New Deal procurement preferences:The Ministry of Science and ICT directs government contracts toward nationally certified infrastructure operators, creating guaranteed demand pools for domestic vendors.
- 5G network convergence:Manufacturing enterprises in Seoul's Pangyo technopolis cluster are deploying private 5G networks to enable real-time predictive maintenance platforms.
- Chaebol captive demand:Conglomerate-affiliated digital subsidiaries generate internal demand for cloud-based ERP systems, reducing customer acquisition costs for domestic software providers.
Market Restraints
- Foreign hyperscaler lock-in:Early cloud adopters in financial services face switching costs when migrating from foreign platforms to MFDS-compliant domestic alternatives.
- Semiconductor input concentration:Domestic AI infrastructure deployment depends on Samsung Electronics' captive supply of advanced memory chips, creating single-source vulnerability.
- KISA certification timelines:The cybersecurity certification framework imposes 12-18 month approval cycles that delay product launches for software vendors.
Strategic Opportunities
- Busan-Ulsan industrial corridor:Shipbuilding and petrochemical clusters outside Seoul remain underpenetrated for IoT-enabled operational technology platforms.
- Healthcare AI diagnostics:MFDS regulatory sandboxes are accelerating approval pathways for AI-assisted medical imaging applications in tertiary hospitals.
- Edge-to-cloud orchestration:The convergence of factory-floor edge computing with sovereign cloud infrastructure creates new integration service categories.
Industry Challenges
- Legacy mainframe integration:Financial institutions face complex API orchestration requirements when connecting 1980s-era core banking systems to modern cloud architectures.
- AI ethics compliance:The Personal Information Protection Act's algorithmic decision-making disclosure rules require retraining of machine learning models and documentation overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Digital Transformation Market |
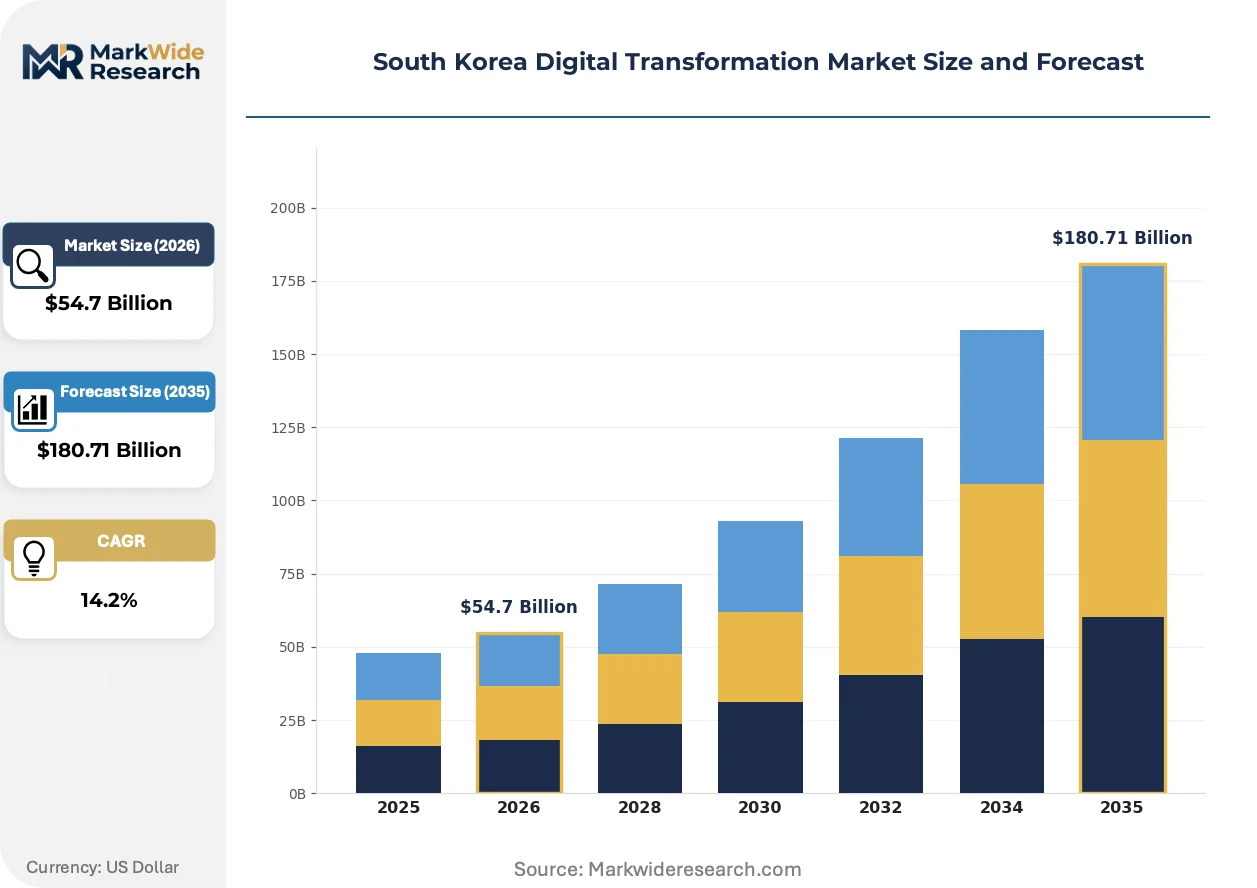
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $180.71 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Cloud Computing, IoT, Blockchain Application: Supply Chain Management, Customer Experience, Data Analytics, Cybersecurity End User: Retail, Manufacturing, Healthcare, Financial Services Deployment: On-premise, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Microsoft Corporation, SAP SE, Samsung Electronics, Salesforce.com Inc., Cisco Systems Inc., NAVER Cloud Corp., Oracle Corporation, Amazon Web Services Inc., IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Digital Transformation Market Trends and Innovations
Edge AI deployment is accelerating across South Korean manufacturing floors, compressing latency requirements for quality control and safety monitoring. This architectural shift is forcing cloud providers to reposition their infrastructure stacks toward distributed computing models.
Digital twin technology is converging with private 5G networks to enable real-time factory simulation. Hyundai Motor Group and SK Innovation are deploying these integrated systems at their Ulsan and Seosan facilities. The technology is converging with sovereign cloud data residency requirements, creating demand for domestically hosted simulation platforms that keep operational data within national borders.
The Network Act amendments under National Assembly review are tightening operational technology segmentation between foreign hyperscalers and certified domestic operators. Industrial consequences include mandatory data localization for critical infrastructure sectors. Energy and transportation verticals are most affected, with KEPCO and Korail accelerating migration to NAVER Cloud and KT Cloud platforms to preempt compliance deadlines.
Enterprise software procurement is consolidating around outcome-based pricing models that tie vendor compensation to measurable productivity gains. System integrators are displacing traditional license resellers in Seoul's Gangnam district. This shift is most visible in retail and logistics, where CJ Logistics and Lotte Shopping have restructured vendor contracts around warehouse automation throughput metrics.
South Korea Digital Transformation Market Segmentation
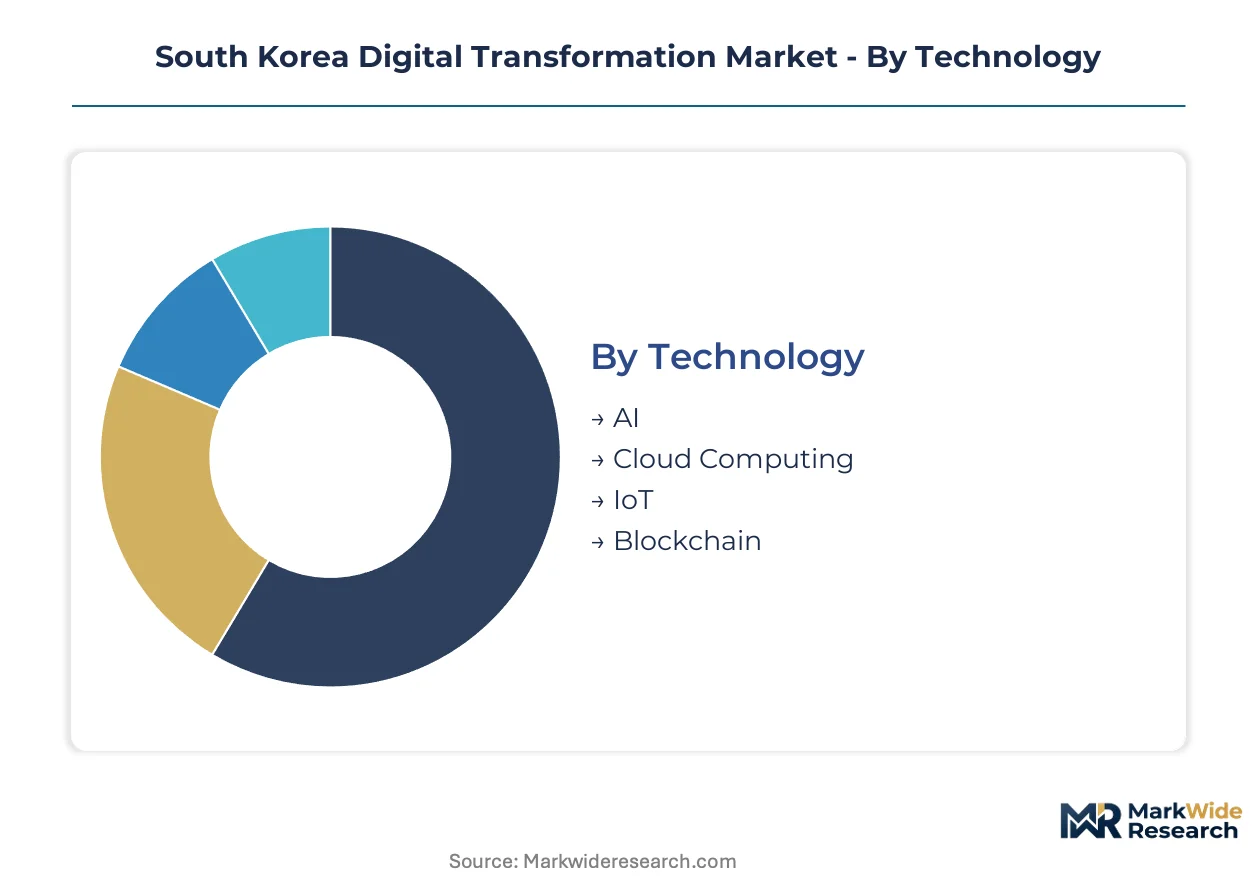
Segmentation reveals how Digital New Deal procurement preferences and sovereign data mandates are concentrating vendor capabilities around specific technology stacks and deployment models. Understanding these divisions exposes where domestic infrastructure investments are flowing and where foreign hyperscalers face exclusion.
Technology:
Supply concentration in semiconductor memory and domestic cloud infrastructure is tilting investment toward AI and cloud computing platforms that leverage Samsung Electronics' captive chip output.
- AI:Machine learning infrastructure demands advanced GPU clusters and high-bandwidth memory substrates. Seoul's Pangyo technopolis hosts the densest concentration of training facilities, driven by chaebol-affiliated digital subsidiaries building sovereign large language models.
- Cloud Computing:Virtualized compute and storage resources delivered through API-first architectures. Government contracts under the Digital New Deal framework are channeling demand toward NAVER Cloud and KT Cloud platforms meeting MFDS data residency requirements.
- IoT:Sensor networks and edge device orchestration for factory-floor automation. Manufacturing enterprises in Ulsan and Busan industrial corridors are deploying private 5G-integrated IoT stacks for predictive maintenance.
- Blockchain:Distributed ledger systems for supply chain traceability and trade finance documentation. Financial services pilot programs at Kookmin Bank and Shinhan Bank are testing won-denominated settlement rails.
Cloud Computing absorbs the bulk of installed capacity; Blockchain is expanding most quickly from its smaller base in supply chain traceability applications.
Application:
Cost tier differentiation separates compliance-mandated cybersecurity spending from discretionary customer experience investments that tie vendor compensation to measurable productivity outcomes.
- Supply Chain Management:End-to-end visibility platforms integrating warehouse automation, logistics tracking, and supplier collaboration portals. CJ Logistics and Lotte Global Logistics are restructuring contracts around throughput metrics rather than license fees.
- Customer Experience:Omnichannel engagement platforms, personalization engines, and real-time recommendation systems. Retail and financial services in Seoul's Gangnam district capture premium margins for these deployments.
- Data Analytics:Business intelligence dashboards, predictive modeling tools, and real-time pipeline orchestration. Manufacturing quality control applications dominate demand in Hyundai Motor Group's Ulsan facilities.
- Cybersecurity:Threat detection, identity management, and encryption services mandated by KISA certification frameworks. Compliance-driven procurement treats this as baseline infrastructure rather than discretionary upgrade.
Cybersecurity commands the largest absolute spending pool due to regulatory mandates; Customer Experience platforms are climbing the fastest as retail and banking competition intensifies.
End User:
Volume concentration in manufacturing is giving way to healthcare and financial services as these verticals outpace traditional industrial IT spending.
- Manufacturing:Operational technology integration spanning ERP, predictive maintenance, and digital twin simulation. Hyundai Motor Group and SK Innovation anchor demand at Ulsan and Seosan facilities.
- Financial Services:Core banking modernization, algorithmic trading infrastructure, and regulatory compliance automation. Early cloud adopters face switching costs when migrating to MFDS-compliant domestic alternatives.
- Healthcare:Electronic medical records, AI-assisted diagnostics, and telemedicine platforms. MFDS regulatory sandboxes are accelerating approval pathways for medical imaging applications in tertiary hospitals.
- Retail:Inventory optimization, warehouse automation, and omnichannel fulfillment systems. E-commerce competition between Coupang and traditional chaebol retailers is driving automation investment.
Manufacturing retains the largest installed base; Healthcare is gaining share fastest as MFDS sandboxes compress regulatory timelines for AI diagnostics.
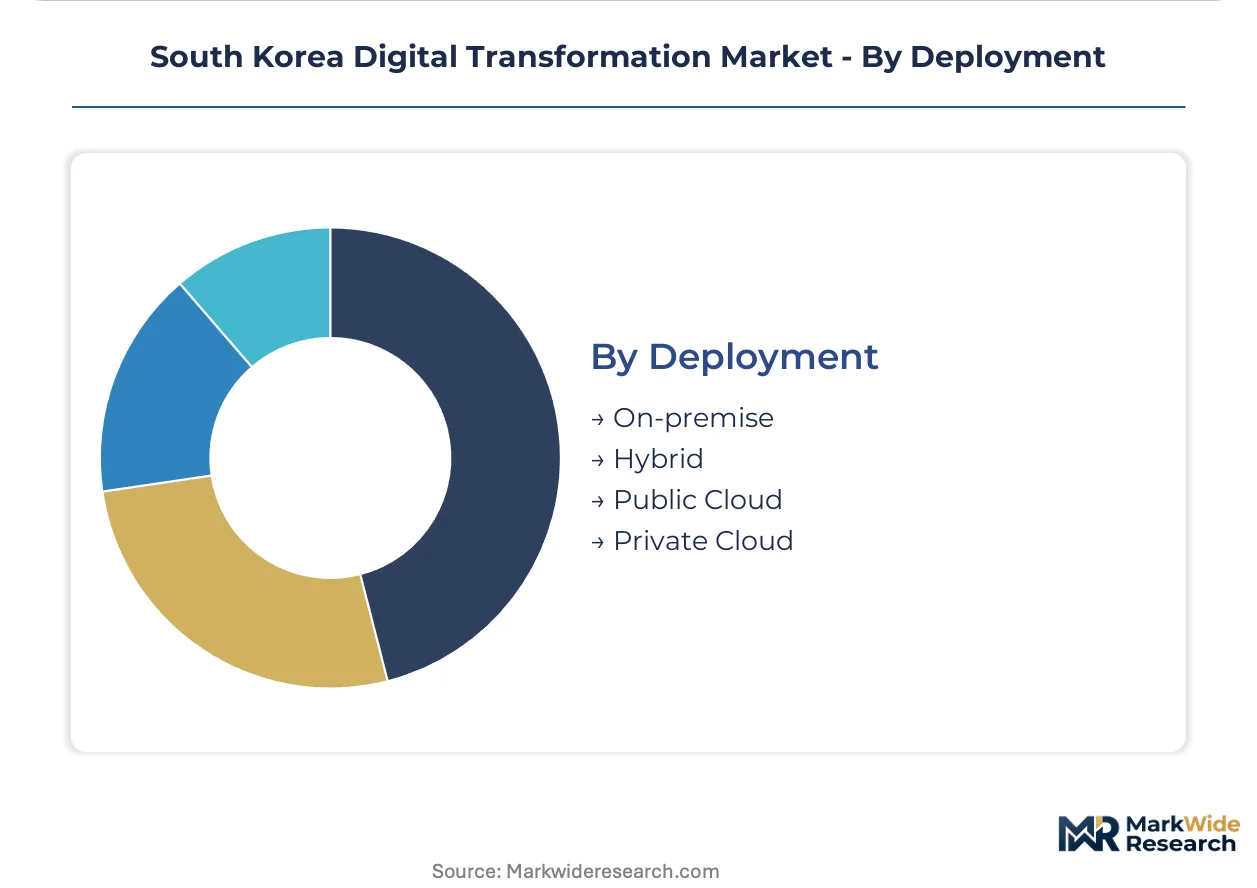
Deployment:
Margin structures favor hybrid architectures that blend on-premise legacy integration with sovereign cloud scalability, avoiding the cost premiums of full private cloud isolation.
- Hybrid:Workload distribution across on-premise infrastructure and domestic cloud platforms. This architecture dominates in financial services seeking to connect 1980s-era mainframes to modern API gateways.
- Private Cloud:Dedicated infrastructure meeting sovereign data residency mandates for critical sectors. KEPCO and Korail are accelerating migration to NAVER Cloud and KT Cloud platforms ahead of Network Act compliance deadlines.
- Public Cloud:Shared multi-tenant resources from certified domestic providers. Early foreign hyperscaler adopters face procurement exclusion as Digital New Deal preferences tighten.
- On-premise:Legacy data center retention for latency-sensitive operational technology. Factory-floor edge computing in Busan-Ulsan corridors maintains localized processing for safety-critical systems.
Hybrid deployments absorb the majority of new enterprise commitments; Private Cloud is expanding most rapidly in energy and transportation verticals facing Network Act segmentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area's Pangyo Techno Valley tax-incentive zone concentrates the bulk of domestic cloud infrastructure investment. Digital New Deal procurement preferences channel government contracts toward certified operators within this corridor. Sub-regional specialization patterns reveal how sovereign data mandates reshape vendor geography.
Seoul Capital Area
Enterprise software procurement concentrates in Gangnam's financial district and Pangyo's R&D cluster. MFDS data governance rules force healthcare AI vendors to maintain domestic hosting facilities. Samsung Electronics anchors cloud infrastructure deployment through captive semiconductor demand in Suwon and Hwaseong.
Busan-Ulsan
Shipbuilding and petrochemical operational technology demand lags Seoul's cloud adoption curve. The Ministry of Trade, Industry and Energy directs smart factory subsidies toward Hyundai Heavy Industries and SK Innovation facilities. Private 5G-integrated IoT stacks are penetrating Ulsan's industrial zones for predictive maintenance.
Daegu-Gyeongbuk
Textile and machinery manufacturers in this southeastern corridor face legacy system modernization pressure. KISA cybersecurity certification timelines delay software launches for regional vendors. Daegu's Daegu Digital Innovation Park hosts SME-focused cloud migration programs under provincial economic development mandates.
Daejeon-Sejong
Public sector digital transformation demand concentrates in this administrative capital region. The Ministry of Science and ICT headquarters directs Digital New Deal procurement toward nationally certified infrastructure operators. KAIST and ETRI research spinoffs populate Sejong's government complex with AI solution providers.
Gwangju-Honam
Underpenetrated industrial base offers expansion opportunity for edge-to-cloud orchestration services. The AI-centered complex in Gwangju receives national budget allocation for semiconductor-adjacent software development. Regional banks and agricultural cooperatives drive modest but accelerating core system modernization demand.
South Korea Digital Transformation Market Competitive Landscape
Top-tier vendors anchor sovereign cloud infrastructure, while mid-tier specialists occupy vertical-specific niches. The vendor base stratifies between chaebol-affiliated digital subsidiaries, foreign hyperscalers facing procurement exclusion, and domestic cloud operators capturing Digital New Deal contracts. Three archetypes dominate: semiconductor-captive infrastructure providers, regulatory-compliant domestic platforms, and legacy ERP integrators serving conglomerate governance structures. Competitive moves center on KISA certification acquisition and hybrid architecture partnerships bridging on-premise legacy with sovereign cloud scalability.
Within the domestic platform tier, NAVER Cloud Corp. and KT Cloud exemplify operators capturing energy and transportation verticals ahead of Network Act compliance deadlines. SAP SE occupies a position among foreign ERP specialists adapting localized suites to Korean conglomerate requirements. Samsung Electronics anchors the semiconductor-captive archetype through vertical integration into memory chip supply for domestic AI training clusters.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Samsung Electronics |
| Salesforce.com Inc. |
| Cisco Systems Inc. |
| NAVER Cloud Corp. |
| Oracle Corporation |
| Amazon Web Services Inc. |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between KISA-certified domestic cloud operators and uncertified alternatives manifests in both pricing premiums and supply chain access. MFDS data residency compliance functions as a tiered gate, with certified vendors commanding subscription premiums while foreign hyperscalers face procurement exclusion from Digital New Deal contracts.
Pricing Analysis
Lead-time-driven pricing compression favors domestic operators with shorter KISA certification cycles over foreign platforms facing 12-18 month approval delays. Subscription-based SaaS tiers dominate, with price differentiation resting on certification level and sovereign data residency guarantees. Pricing pressure stems from chaebol captive demand internalizing cloud services through affiliated subsidiaries. Financial services buyers exhibit highest price sensitivity due to legacy migration switching costs, while public sector procurement shows lowest sensitivity given compliance mandates.
Supply Chain Analysis
KISA certification gating restricts component sourcing to nationally approved hardware vendors and domestic memory suppliers. Supply concentrates in South Korea, Taiwan, and USA for advanced GPU clusters and high-bandwidth memory substrates. Raw material dependencies center on Samsung Electronics' captive DRAM and NAND output, NVIDIA AI accelerators, and domestic foundry capacity. Single-source vulnerability from semiconductor input concentration poses structural risk. Distribution runs through system integrators in Seoul's Gangnam district displacing traditional license resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea Digital Transformation Market operates as a cost-of-compliance story where KISA cybersecurity certification creates a barrier-to-entry moat rewarding early investment in national standards.
For Market Incumbents: Deepen hybrid architecture partnerships bridging on-premise legacy systems with sovereign cloud scalability to defend against foreign hyperscaler re-entry attempts. Fortify KISA certification maintenance capabilities and expand Pangyo technopolis R&D presence to anchor talent pools. For New Entrants and Emerging Players: Capture Busan-Ulsan industrial corridor white space in shipbuilding and petrochemical operational technology where cloud penetration lags Seoul. Target healthcare AI diagnostics through MFDS regulatory sandbox pathways, deploying edge-to-cloud orchestration as the primary go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with KISA-certified domestic platform operators given Network Act amendment catalysts accelerating public sector migration. Long-term viability favors operators with backward integration into semiconductor memory supply and established government procurement relationships. Watch KEPCO and Korail compliance deadline acceleration as inflection signal for infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| KISA Certification Acquisition | Unlocks Digital New Deal procurement contracts and sovereign cloud eligibility for domestic operators. |
| Hybrid Architecture Partnership | Bridges financial services legacy mainframes to NAVER Cloud and KT Cloud API gateways. |
| Edge-to-Cloud Integration Service | Captures factory-floor predictive maintenance demand from Hyundai Motor Group Ulsan facilities. |
| Healthcare AI Regulatory Sandbox Entry | Accelerates MFDS approval pathways for tertiary hospital diagnostic imaging deployments. |
| Private 5G Network Convergence | Enables real-time digital twin simulation for SK Innovation Seosan petrochemical operations. |
Research Methodology
Independent corroboration across primary interviews with cloud platform engineers, IT procurement officers at chaebol affiliates, KISA certification consultants, and system integration specialists underwrites the qualitative findings. Secondary validation draws from Ministry of Science and ICT policy disclosures, Digital New Deal procurement databases, hyperscaler capex filings, and MFDS regulatory sandbox announcements. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across technology, application, end-user, and deployment dimensions.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation models capture technology type, vertical industry, organization scale, deployment architecture, and regional cluster adoption patterns. CAGRs derive from historical trajectory analysis adjusted for policy inflection points and infrastructure buildout curves. Forecast inputs incorporate 5G network deployment timelines, KISA certification pipeline visibility, and chaebol captive demand internalization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Network Act amendment scope and semiconductor supply continuity. Model outputs reflect assumptions around regulatory enforcement consistency and sovereign cloud migration pace. A model refresh is warranted upon material change in Digital New Deal budget allocation or MFDS data governance rule expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
Mexico Digital Transformation Market