
 Poland Digital Transformation Market | 2026-2036
Poland Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Digital Transformation Market Insights
ISO 27001 certification cycles is collapsing from twenty-four months to under twelve for Polish system integrators, tightening vendor qualification. Accenture PLC leverages its Krakow delivery center to anchor complex SAP migrations for Central European industrials. Comarch specializes in regulated banking infrastructure, sustaining long-term contracts with Polish cooperative banks. Asseco dominates public-sector digitization, controlling tenders from the National Revenue Administration and municipal governments.
Poland Digital Transformation encompasses the integration of cloud-native architectures, AI-driven process automation, and industrial IoT sensor networks into enterprise operations, typically delivered through API-connected platforms with sub-100 millisecond latency requirements for real-time manufacturing control. Its primary purpose is replacing legacy on-premises ERP silos with horizontally scalable systems that synchronize supply chain, customer-facing, and regulatory reporting functions. Cloud Computing leads technology spending as Polish enterprises exit owned data centers, while Artificial Intelligence captures margin pools in predictive maintenance and credit risk scoring. Manufacturing verticals drive fastest growth in Operational Efficiency applications, whereas Financial Services concentrates spend in Cybersecurity amid PSD2 and DORA compliance deadlines.
BIS interoperability standards and EU AI Act risk classifications shape which vendors qualify for Polish public procurement, while GDPR enforcement by the national data protection authority tightens cross-border data governance requirements for hybrid cloud deployments. Polish enterprises must monitor how CSRD sustainability reporting mandates will force ERP upgrades, and decide whether to build in-house AI compliance teams or outsource to certified managed services providers before regulatory deadlines harden.
Market Dynamics
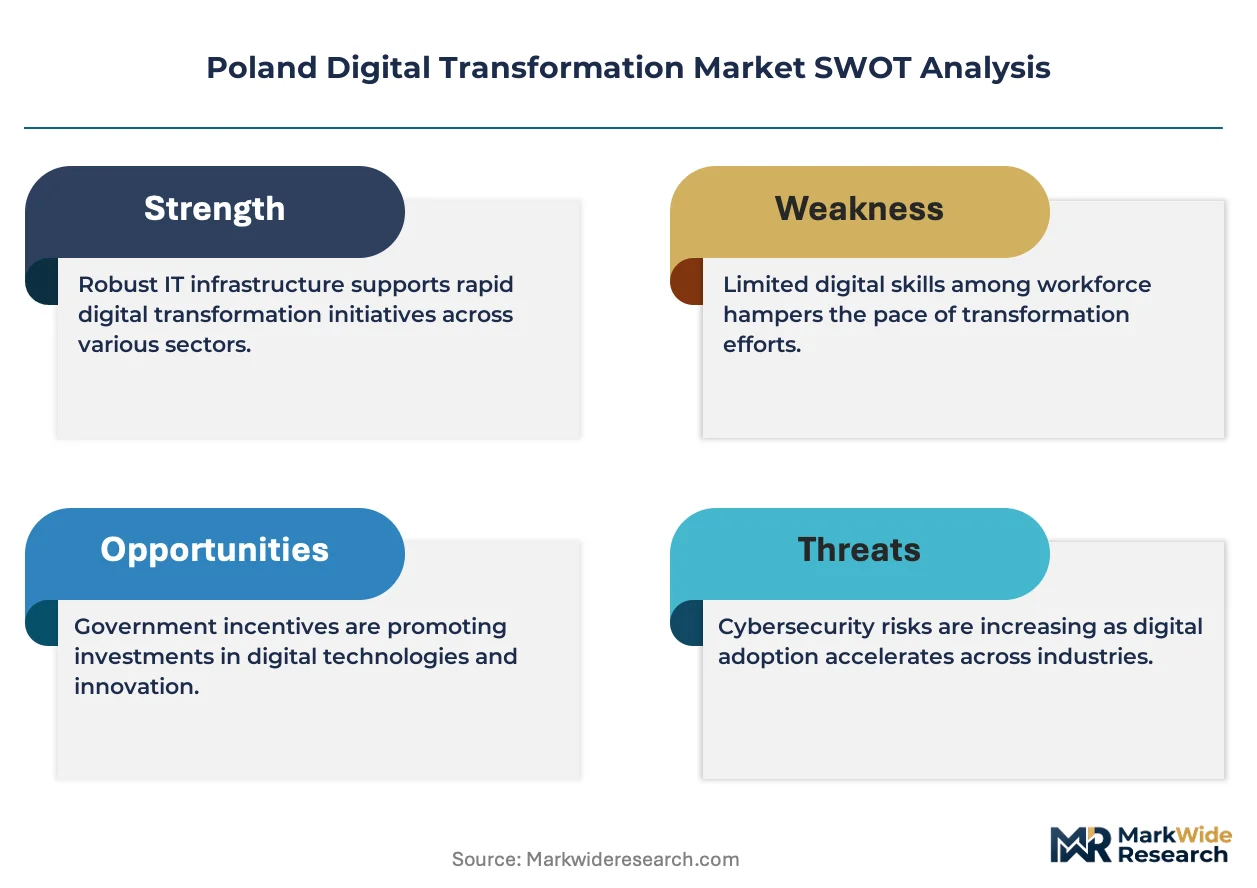
Polish enterprises face compressed ISO 27001 certification timelines that are collapsing vendor qualification windows, forcing system integrators to accelerate security audits while EU AI Act risk classifications reshape procurement eligibility for automated decision systems.
Growth Catalysts
- EU AI Act implementation:Risk-based classification mandates for high-risk AI systems are creating compliance-driven demand for certified automation platforms across Polish banking and manufacturing sectors.
- Cloud exit acceleration:Polish enterprises are abandoning owned data centers for horizontally scalable infrastructure, with Warsaw's enterprise software corridor and Krakow's cloud services hub capturing concentrated migration spend.
- Industrial IoT sensor networks:Manufacturing verticals are deploying sub-100 millisecond latency control systems to synchronize real-time production lines with supply chain visibility platforms.
Market Restraints
- GDPR cross-border friction:Poland's national data protection authority enforces strict data governance requirements that complicate hybrid cloud architectures spanning EU and non-EU jurisdictions.
- Legacy ERP silo entrenchment:Deep integration of on-premises SAP and Oracle systems creates technical debt that slows API-connected platform adoption in established industrials.
- Specialized talent scarcity:Shortages of certified AI compliance officers and cloud-native architects constrain execution velocity for complex transformation programs.
Strategic Opportunities
- CSRD sustainability reporting mandates:Upcoming disclosure requirements will force ERP upgrades across Polish listed companies, creating captive demand for integrated ESG data platforms.
- Operational Efficiency application expansion:Predictive maintenance and quality control AI are penetrating mid-market manufacturers previously priced out of enterprise automation suites.
- PSD2 and DORA compliance services:Financial services institutions require cybersecurity infrastructure overhauls, opening managed services contracts for specialized Polish integrators.
Industry Challenges
- Compressed certification cycles:ISO 27001 audits collapsing from twenty-four months to under twelve strain documentation and evidence-collection capabilities for Polish system integrators.
- Hybrid integration complexity:API-connected platforms must synchronize with legacy regulatory reporting functions without disrupting National Revenue Administration submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Digital Transformation Market |
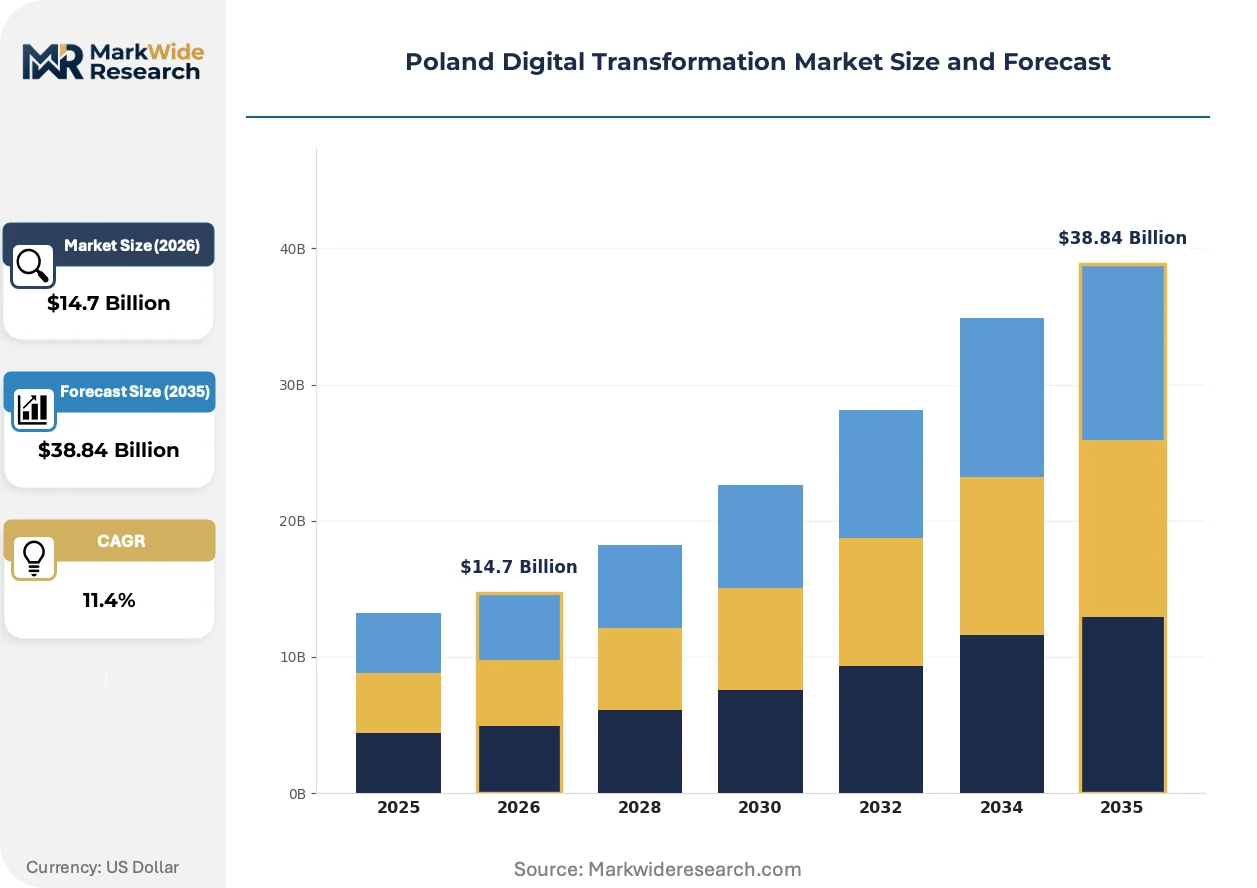
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, IoT, Big Data Industry Vertical: Retail, Healthcare, Manufacturing, Financial Services Application: Customer Experience, Operational Efficiency, Business Analytics, Cybersecurity Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Managed Services |
| Companies Covered | Accenture PLC, Google LLC (Alphabet Inc.), Siemens AG, IBM Corporation, Microsoft Corporation, Asseco, Comarch, SAP SE, Cisco Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Digital Transformation Market Trends and Innovations
Edge computing architectures are displacing centralized cloud processing for factory-floor control, while regulatory pressure from Brussels accelerates compliance technology investment. Buyer behavior is pivoting toward outcome-guaranteed service contracts that transfer operational risk to vendors.
Containerized microservices running on edge nodes are displacing monolithic ERP modules for real-time manufacturing control. Polish automotive and electronics manufacturers are deploying these architectures fastest, prioritizing sub-100 millisecond sensor response over cloud latency. This shift is displacing traditional system integrator revenue models built around centralized infrastructure migration.
The EU AI Act risk classification framework is mandating conformity assessments for high-risk automated decision systems before public procurement eligibility. Polish banking infrastructure vendors must now document algorithmic transparency and human oversight mechanisms to qualify for cooperative bank tenders. Financial services and public sector segments are restructuring procurement specifications to embed these requirements.
Polish enterprises are unbundling transformation programs into discrete outcome-based engagements with penalty clauses for missed KPIs. Industrial buyers in Silesia and Greater Poland voivodeships now require guaranteed operational efficiency gains before releasing full payment, displacing time-and-materials contracts. This procurement evolution concentrates vendor selection on demonstrable reference implementations rather than architectural proposals.
Poland Digital Transformation Market Segmentation
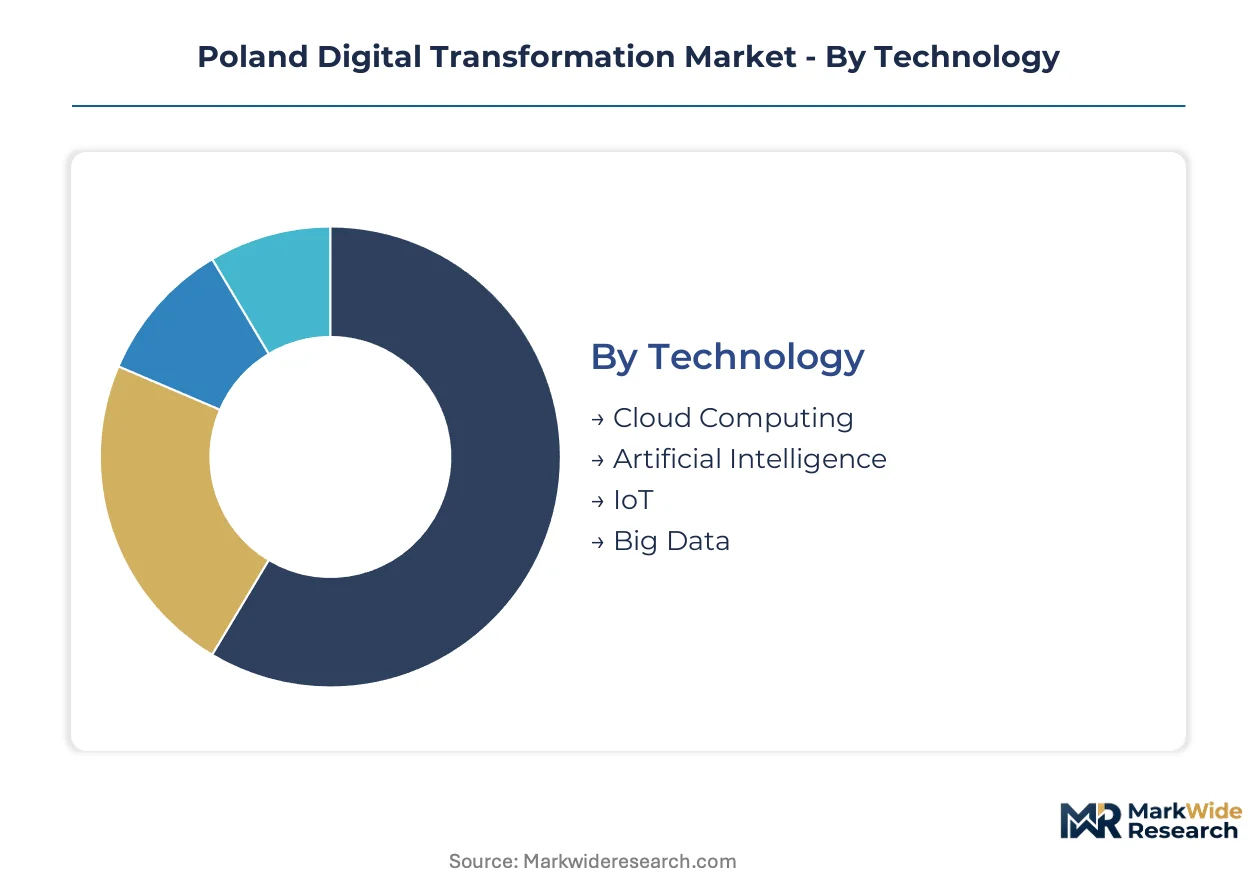
Poland's digital transformation market fragments across four intersecting dimensions that determine vendor qualification paths and procurement specifications. Technology choices dictate infrastructure migration complexity, while industry verticals shape compliance requirements under EU AI Act and DORA mandates. Application priorities and deployment models further stratify buyer budgets between Warsaw's enterprise corridor and Krakow's cloud hub.
Technology:
Margin pools concentrate in AI-driven automation and industrial IoT integration, where specialized compliance documentation commands pricing premiums over commoditized infrastructure.
- Cloud Computing:Horizontally scalable infrastructure replacing owned data centers dominates Warsaw enterprise spend. Polish manufacturers in Silesia voivodeship prioritize hybrid architectures that synchronize with National Revenue Administration reporting timelines.
- Artificial Intelligence:Predictive maintenance algorithms and credit risk scoring engines capture premium margins. Banking sector demand concentrates in Krakow's financial services cluster, where EU AI Act conformity assessments mandate documented human oversight mechanisms.
- IoT:Factory-floor sensor networks with sub-100 millisecond latency requirements.
- Big Data:ESG data lakes for upcoming CSRD sustainability reporting mandates.
Cloud Computing holds installed capacity. Artificial Intelligence is rotating up the share rankings.
Industry Vertical:
Application complexity and regulatory exposure create tiered pricing structures across verticals, with financial services and manufacturing commanding premium implementation fees.
- Manufacturing:Smart factory deployments in automotive and electronics sectors drive fastest expansion. Silesia and Greater Poland voivodeships require outcome-guaranteed contracts with operational efficiency KPIs before full payment release.
- Financial Services:PSD2 and DORA compliance deadlines force cybersecurity infrastructure overhauls. Cooperative banks sustain long-term contracts with specialized Polish integrators for regulated core banking systems.
- Retail:Omnichannel customer data platforms unifying online and store operations.
- Healthcare:Electronic health record interoperability under national digitization programs.
Manufacturing captures volume leadership. Financial Services is climbing the fastest in margin contribution.
Application:
Buyer procurement patterns pivot toward discrete outcome-based engagements, with penalty clauses displacing time-and-materials contracts across all application areas.
- Operational Efficiency:Real-time production line synchronization and quality control AI penetrate mid-market manufacturers. Containerized microservices on edge nodes displace monolithic ERP modules for factory-floor control.
- Cybersecurity:Zero-trust architectures and identity management systems concentrate spend in banking and public sectors. ISO 27001 certification cycles collapsing to under twelve months strain vendor qualification.
- Customer Experience:Unified commerce platforms and personalization engines.
- Business Analytics:Regulatory reporting automation and ESG disclosure dashboards.
Operational Efficiency leads deployment velocity. Cybersecurity is gaining share fastest amid compliance deadlines.
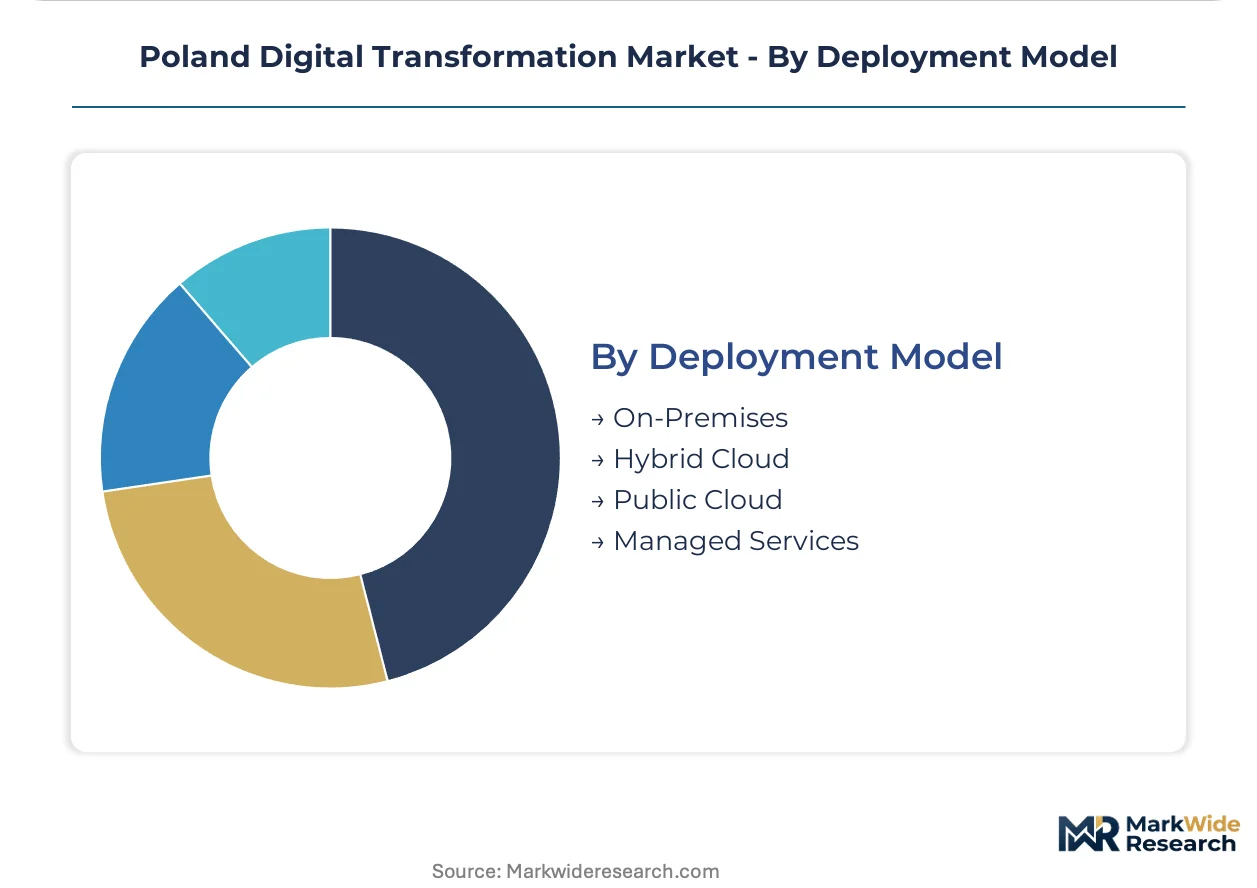
Deployment Model:
Latency requirements and data residency rules fragment deployment choices between edge-heavy manufacturing and centralized public cloud for administrative functions.
- Hybrid Cloud:Dominant architecture balancing real-time manufacturing control with centralized ERP synchronization. GDPR cross-border friction complicates architectures spanning EU and non-EU jurisdictions.
- Managed Services:Growing preference for risk-transfer contracts where vendors guarantee uptime and compliance outcomes. Polish system integrators face compressed documentation cycles under accelerated ISO 27001 audits.
- Public Cloud:Horizontal scaling for customer-facing applications and development environments.
- On-Premises:Residual legacy ERP silos in established industrials with deep technical debt.
Hybrid Cloud anchors current infrastructure. Managed Services is rotating up the share rankings as procurement shifts to outcome-based models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion funds and national digitization programs are channeling infrastructure investment toward Central European technology corridors. Warsaw and Krakow anchor Poland's transformation ecosystem, while provincial manufacturing clusters accelerate edge computing adoption.
Masovian Voivodeship
Warsaw's enterprise software corridor concentrates cloud migration demand from financial services and public sector buyers. The National Revenue Administration's digitization mandates force ERP synchronization upgrades across tax-compliant enterprises. Służewiec Przemysłowy district hosts hyperscaler regional headquarters serving Central European clients.
Lesser Poland Voivodeship
Krakow's cloud services hub attracts managed services contracts from banking and insurance verticals. EU AI Act conformity assessments reshape procurement specifications for automated credit scoring systems. The city's technology park clusters specialize in SAP migration and cybersecurity implementation for cooperative banks.
Silesian Voivodeship
Automotive and electronics manufacturers deploy sub-100 millisecond latency control systems for smart factory floors. Compressed ISO 27001 certification cycles strain vendor qualification for system integrators serving industrial clients. Katowice-Gliwice corridor leads Operational Efficiency application deployment with outcome-guaranteed contracts.
Greater Poland Voivodeship
Mid-market manufacturers adopt predictive maintenance AI previously priced out of enterprise automation suites. Poznań's logistics technology cluster synchronizes supply chain visibility platforms with real-time production lines. Regional industrial parks require guaranteed efficiency KPIs before releasing full contract payments.
Lower Silesian Voivodeship
Wrocław's shared services centers drive demand for hybrid cloud architectures balancing GDPR data residency with cross-border operations. The voivodeship's electronics manufacturing base deploys containerized microservices on edge nodes for quality control automation. Wrocław Technology Park anchors R&D partnerships between industrial buyers and compliance technology vendors.
Poland Digital Transformation Market Competitive Landscape
Player mix skews toward global technology consultancies with regional delivery centers, tier-one enterprise software vendors, and specialized Polish system integrators with public sector relationships. Market structure concentrates around three strategic archetypes: hyperscale platform providers anchoring infrastructure migration, global consultancies delivering complex ERP transformations, and domestic specialists capturing regulated verticals through compliance expertise. Competitive dynamics center on accelerated certification timelines and outcome-based contract structures with penalty clauses.
Among global consultancies with Polish delivery infrastructure, Accenture PLC exemplifies the complex SAP migration archetype for Central European industrials. Domestic specialists Asseco and Comarch occupy positions tied to public sector and regulated banking procurement respectively. Asseco anchors public-sector digitization through National Revenue Administration relationships, while Comarch exemplifies long-term contract sustainability with cooperative banking infrastructure. These three companies represent the tiered competitive structure spanning global scale, regional delivery capability, and vertical specialization.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC (Alphabet Inc.) |
| Siemens AG |
| IBM Corporation |
| Microsoft Corporation |
| Asseco |
| Comarch |
| SAP SE |
| Cisco Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native infrastructure substitution for legacy on-premises ERP systems simultaneously concentrates vendor pricing power in Warsaw's enterprise corridor and Krakow's cloud hub while compressing deployment margins for system integrators facing accelerated ISO 27001 certification cycles.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with EU AI Act conformity assessments and ISO 27001 documentation quality commanding substantial premiums over uncertified automation platforms. Project-based pricing with outcome-guaranteed contracts dominates procurement, displacing time-and-materials structures as Silesian manufacturers demand efficiency KPIs before payment release. Pricing pressure stems from compressed vendor qualification windows that force integrators to absorb audit acceleration costs. Mid-market manufacturers exhibit highest price sensitivity, while National Revenue Administration tenders show lowest sensitivity due to regulatory entrenchment requirements.
Supply Chain Analysis
Inventory cycles for specialized AI compliance talent and cloud-native architects now stretch twelve to eighteen months, constraining execution velocity for complex transformation programs. Supply concentrates in Ireland and Germany for hyperscaler infrastructure, with Poland's domestic system integrators anchoring regulated vertical delivery. The ecosystem draws from EU-certified hardware vendors, open-source container orchestration platforms, and specialized banking software modules. Single-source vulnerability around SAP and Oracle legacy integration expertise poses structural risk. Distribution runs through direct enterprise sales teams and certified managed services partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where EU AI Act procurement eligibility and National Revenue Administration relationships create durable defensive moats against unqualified competitors.
For Market Incumbents: Compound certification advantages by accelerating ISO 27001 audit automation and embedding EU AI Act conformity documentation into standard service delivery. Threat from compressed certification cycles demands preemptive investment in compliance technology platforms. Vertical integration into edge computing hardware assembly secures sub-100 millisecond latency guarantees for manufacturing clients.
For New Entrants and Emerging Players: Anchor in mid-market Operational Efficiency applications where outcome-based contracts and predictive maintenance AI remain underpenetrated. Greater Poland voivodeship logistics technology clusters offer most penetrable geography given guaranteed KPI procurement structures. Go-to-market angle should emphasize rapid CSRD sustainability reporting platform deployment ahead of ERP upgrade cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized Polish system integrators with cooperative banking infrastructure contracts and public sector digitization relationships. Long-term viability hinges on regulatory entrenchment depth rather than technology differentiation alone. Signal to watch is acceleration of EU AI Act high-risk system procurement specifications across municipal government tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Conformity assessment investment unlocks high-risk automated decision system procurement eligibility across Polish banking tenders. |
| Edge Computing Infrastructure Deployment | Sub-100 millisecond latency architectures displace centralized cloud processing for Silesian automotive manufacturing control systems. |
| Outcome-Based Contract Structuring | Operational efficiency KPI guarantees align vendor incentives with Greater Poland industrial buyer payment release conditions. |
| CSRD Sustainability Platform Integration | ESG data lake deployment captures captive ERP upgrade demand from Polish listed companies ahead of disclosure mandates. |
| ISO 27001 Audit Acceleration | Compressed certification cycle automation preserves vendor qualification status under twelve-month documentation timelines. |
Research Methodology
Operator-level perspectives from digital transformation program directors, IT procurement officers at Polish cooperative banks, system integrator delivery leads, National Revenue Administration technology managers, and manufacturing plant engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed technology vendors, hyperscaler regional capex disclosures, EU AI Act implementation guidance documents, and Polish public procurement registry data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across technology, vertical, application, and deployment model dimensions.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and cloud migration acceleration scenarios. The analytical framework modeled spending trajectories across Cloud Computing, Artificial Intelligence, IoT, and Big Data technologies; Manufacturing, Financial Services, Retail, and Healthcare verticals; Operational Efficiency, Cybersecurity, Customer Experience, and Business Analytics applications; and Hybrid Cloud, Managed Services, Public Cloud, and On-Premises deployment models. CAGRs derived from regression analysis of historical technology adoption curves adjusted for EU regulatory compliance deadlines and Polish national digitization program funding allocations.
Decision-makers should treat outputs as directional under assumptions of sustained EU cohesion fund availability and stable GDPR enforcement intensity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Thailand Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Nigeria Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Germany Digital Transformation Market