
 Qatar Digital Transformation Market | 2026-2036
Qatar Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Digital Transformation Market Insights
Buyer concentration among Qatari government entities and national oil and gas enterprises is consolidating around integrated digital platforms rather than point solutions. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor enterprise-grade deployments across state-backed infrastructure projects. IBM Corporation competes through Watson-based AI and quantum computing research partnerships with Qatar Foundation. Ooredoo Qatari Public Shareholding Company controls domestic connectivity layers and extends data center capacity to capture hybrid cloud demand from regulated industries.
Digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, Internet of Things sensors, and advanced analytics into organizational workflows to automate decision-making and optimize resource allocation. Cloud Computing deployments form the foundational infrastructure layer, with hybrid configurations dominating among financial institutions subject to Qatar Central Bank data residency rules. AI adoption concentrates in predictive maintenance for energy assets and personalized service delivery in BFSI verticals, while IoT expansion tracks Lusail smart city infrastructure and Qatar Rail operational systems. Public Cloud segments lead volume growth among SMEs accessing scalable compute, whereas Private Cloud and On-Premises retain preference within defense-linked and hydrocarbon processing environments where operational technology isolation remains mandatory.
The Communications Regulatory Authority enforces data localization and cybersecurity certification requirements that shape vendor qualification criteria for public sector contracts. Qatar National Vision 2030 and associated smart city frameworks mandate open data standards and interoperability protocols that influence procurement specifications across municipal and transport authorities. Stakeholders must monitor evolving sovereign AI governance requirements and assess whether current partnership structures satisfy emerging domestic content obligations for critical infrastructure digitization.
Market Dynamics
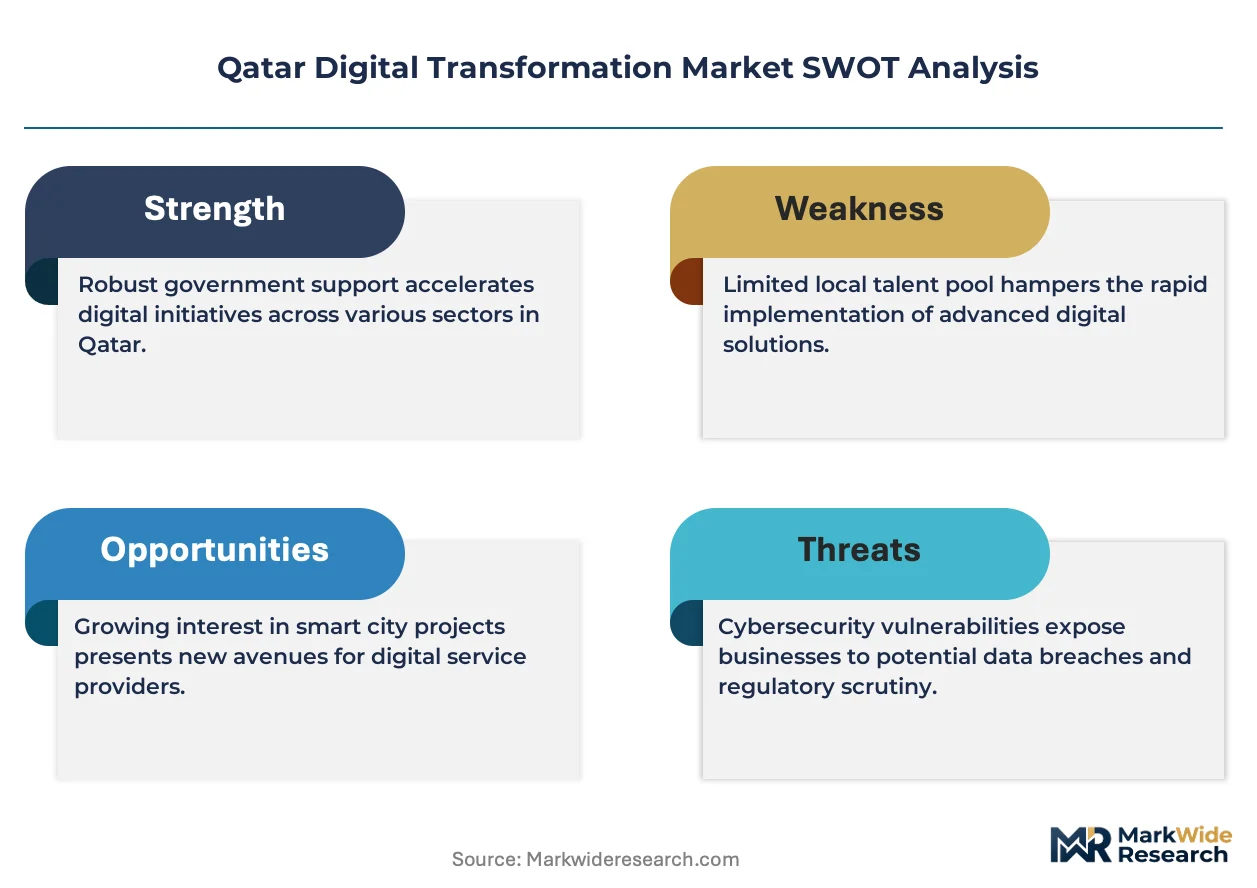
Sovereign data mandates from the Communications Regulatory Authority are compressing vendor qualification timelines and forcing procurement consolidation around compliant domestic infrastructure. This regulatory pressure is restructuring competitive positioning across Qatar's enterprise technology landscape.
Growth Catalysts
- Qatar National Vision 2030:Smart city frameworks mandate interoperability protocols across municipal and transport authorities, creating standardized procurement pipelines for integrated platform vendors.
- Energy sector automation:Predictive maintenance deployments for hydrocarbon processing assets are pulling AI and IoT sensor networks into operational technology environments.
- Lusail infrastructure buildout:The new city's integrated command centers require unified cloud, connectivity, and analytics stacks that favor single-source platform contracts.
Market Restraints
- Data localization compliance costs:Sovereign cloud certification requirements impose redundant infrastructure investments that inflate total cost of ownership for foreign platform providers.
- Skilled workforce scarcity:Domestic talent pools for quantum computing and advanced AI engineering remain shallow, constraining deployment velocity for complex transformation programs.
- Operational technology isolation:Defense-linked and hydrocarbon processing environments mandate air-gapped systems that fragment cloud adoption and prevent unified management planes.
Strategic Opportunities
- Hybrid cloud orchestration:Financial institutions navigating Qatar Central Bank data residency rules present demand for seamless workload portability between on-premises and sovereign cloud environments.
- AI governance services:Emerging domestic content obligations for critical infrastructure create whitespace for compliance consulting and algorithmic audit capabilities.
- Edge-to-core integration:Qatar Rail operational systems and Lusail sensor networks require distributed computing architectures that converge 5G connectivity with localized inference engines.
Industry Challenges
- Legacy system interoperability:Decades-old hydrocarbon SCADA infrastructure resists API-based integration, forcing costly middleware development for unified data lakes.
- Certification timeline compression:Cybersecurity certification queues at the Communications Regulatory Authority extend vendor onboarding cycles, delaying project kickoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Digital Transformation Market |
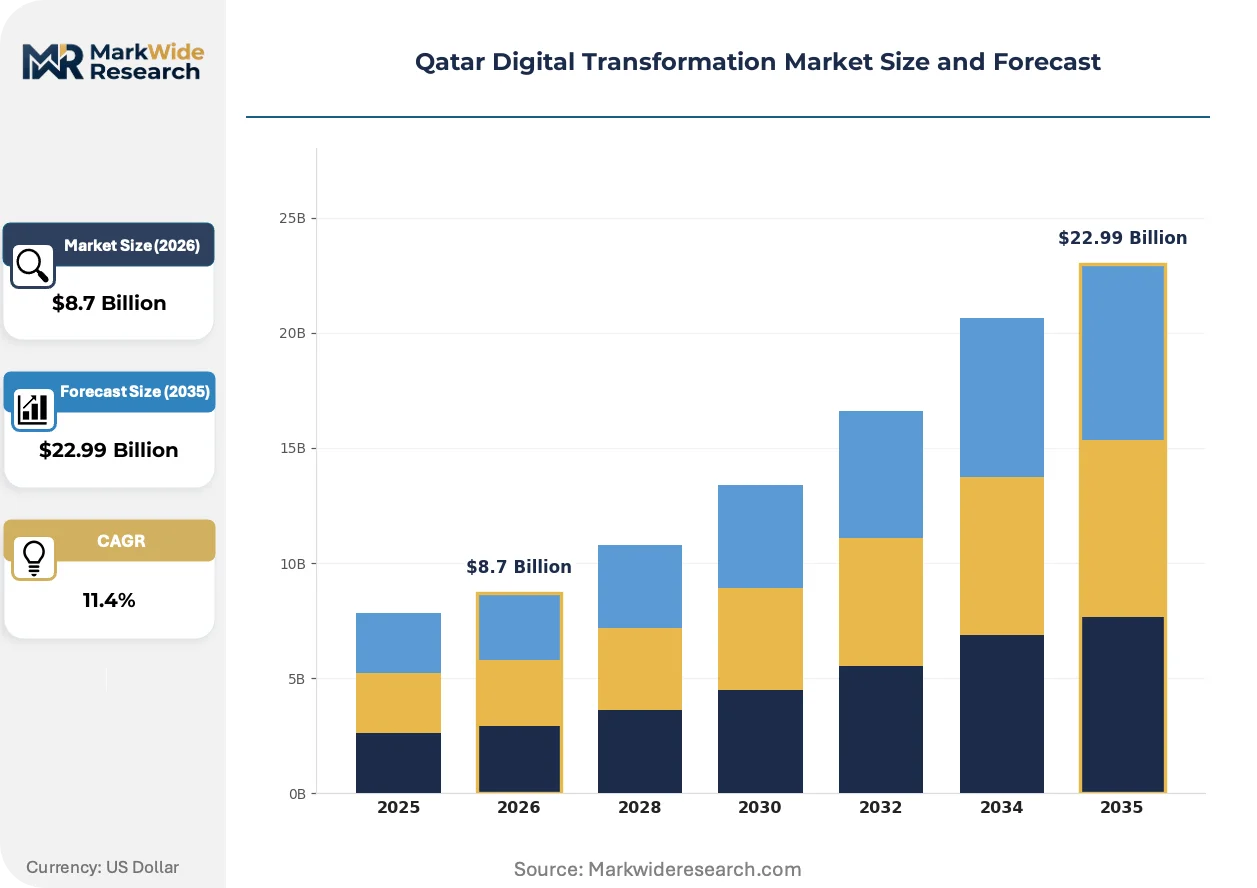
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Big Data, AI, IoT Industry Vertical: Healthcare, BFSI, Retail, Education Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | Microsoft Corporation, IBM Corporation, Ooredoo Qatari Public Shareholding Company, Qatar Computer Services, Wipro Limited, Accenture plc, Cisco Systems, Inc., Amazon Web Services, Inc., Meeza, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Digital Transformation Market Trends and Innovations
Platform consolidation is displacing point-solution procurement across Qatar's regulated industries. Vendors are repositioning around integrated cloud-AI-connectivity stacks that satisfy sovereign compliance requirements in single contracting vehicles.
Hybrid cloud architectures are integrating containerized workloads with sovereign data residency controls. Qatar Central Bank-regulated banks are migrating core banking systems to these configurations at measured pace. This convergence is compressing vendor selection criteria toward platforms offering unified governance dashboards across on-premises and cloud-native estates.
The Communications Regulatory Authority's data localization enforcement is tightening certification requirements for public sector cloud contracts. Foreign providers must demonstrate domestic infrastructure ownership and operational control. Energy sector procurement teams are responding by pre-qualifying only vendors with established Qatar-based data center presence.
Enterprise buying patterns are rotating from perpetual licenses toward consumption-based platform subscriptions. Ministry and state-owned enterprise IT departments favor operational expenditure models that align technology costs with project milestones. This shift is most visible in Doha-based government clusters where multi-year transformation programs require budget flexibility.
Qatar Digital Transformation Market Segmentation
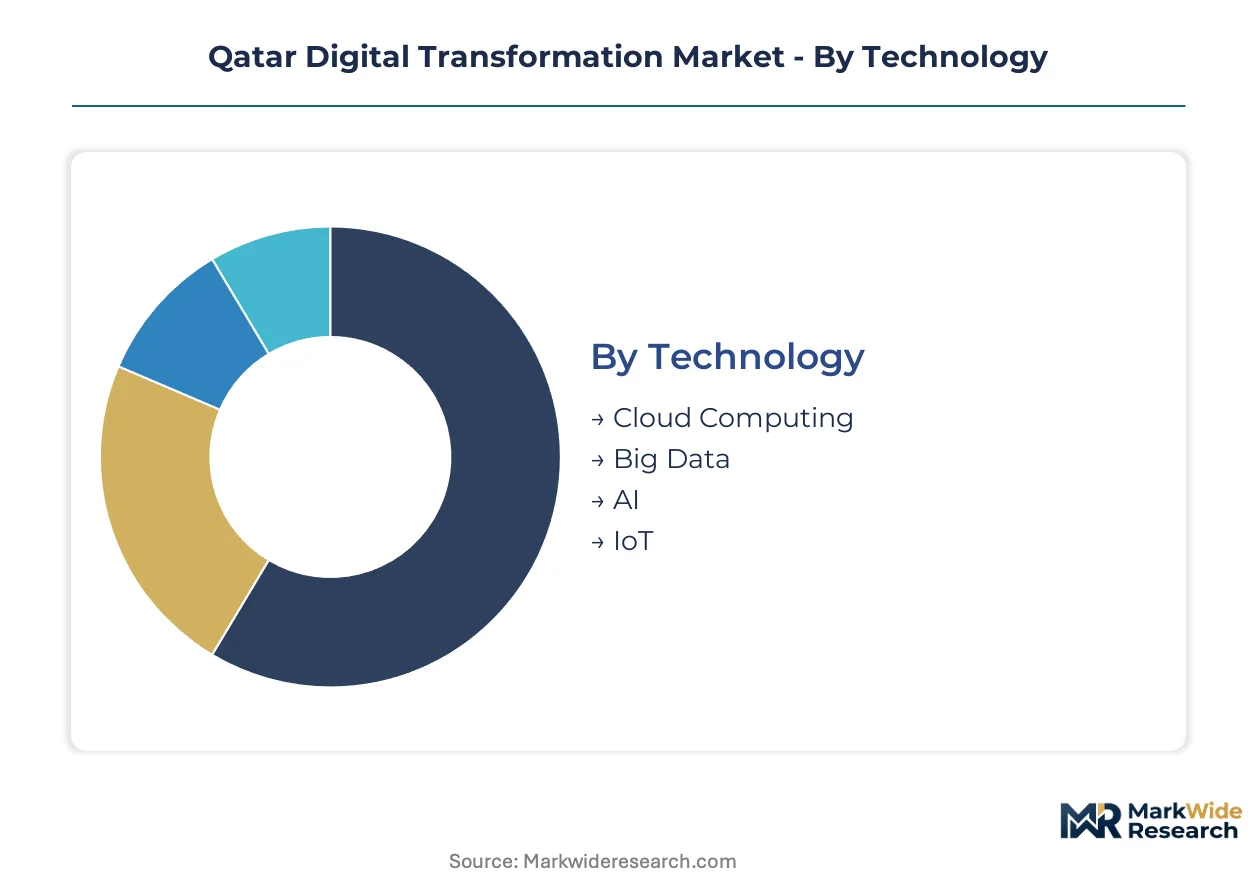
Qatar's digital transformation procurement patterns diverge sharply across technology layers and deployment models. Communications Regulatory Authority certification requirements create asymmetric compliance burdens that reshape vendor economics and customer selection criteria.
Technology:
Cloud Computing and AI deployments face the most intensive Communications Regulatory Authority sovereign data certification requirements, while Big Data and IoT sensor networks navigate lighter cybersecurity queues.
- Cloud Computing:Hybrid configurations dominate among Qatar Central Bank-regulated financial institutions requiring data residency controls. Sovereign cloud certification from the Communications Regulatory Authority compresses vendor qualification timelines to 8-14 months.
- AI:Predictive maintenance algorithms for Qatar Energy hydrocarbon assets and personalized BFSI service delivery concentrate demand. Domestic talent scarcity for advanced AI engineering constrains deployment velocity for complex transformation programs.
- Big Data:Unified data lakes for Lusail smart city command centers and Qatar Rail operational analytics.
- IoT:Sensor networks across Lusail infrastructure and Qatar Energy processing facilities.
Cloud Computing sits at the top of the volume ranking, with AI climbing the fastest.
Industry Vertical:
Cost tier stratification separates hydrocarbon-linked verticals with unlimited capital budgets from education and retail segments operating under constrained procurement ceilings.
- BFSI:Qatar Central Bank data residency rules mandate hybrid cloud architectures with sovereign data controls. Core banking migrations proceed at measured pace due to operational risk sensitivity.
- Healthcare:Hamad Medical Corporation and private hospital networks deploy AI diagnostic imaging and electronic health record platforms. Patient data localization requirements add certification complexity.
- Retail:Doha-based luxury retail clusters and e-commerce platforms adopting cloud-native customer analytics.
- Education:Qatar Foundation universities and Ministry of Education institutions piloting digital learning infrastructure.
BFSI commands the highest per-project expenditure, with Healthcare expanding most quickly on patient data modernization mandates.
Deployment Model:
Application criticality determines model selection — air-gapped operational technology environments in hydrocarbon processing exclude public cloud options entirely.
- Hybrid Cloud:Containerized workloads with unified governance dashboards span on-premises and sovereign cloud estates. Qatar Central Bank-regulated banks favor this configuration for core system portability.
- Private Cloud:Single-tenant infrastructure satisfies defense-linked and Qatar Energy processing requirements where operational technology isolation remains mandatory.
- Public Cloud:SMEs in Doha enterprise clusters access scalable compute without capital infrastructure investment.
- On-Premises:Legacy SCADA integration and air-gapped security environments persist in critical infrastructure.
Hybrid Cloud dominates new project initiations, with Private Cloud retaining preference in regulated hydrocarbon and defense sectors.
End User:
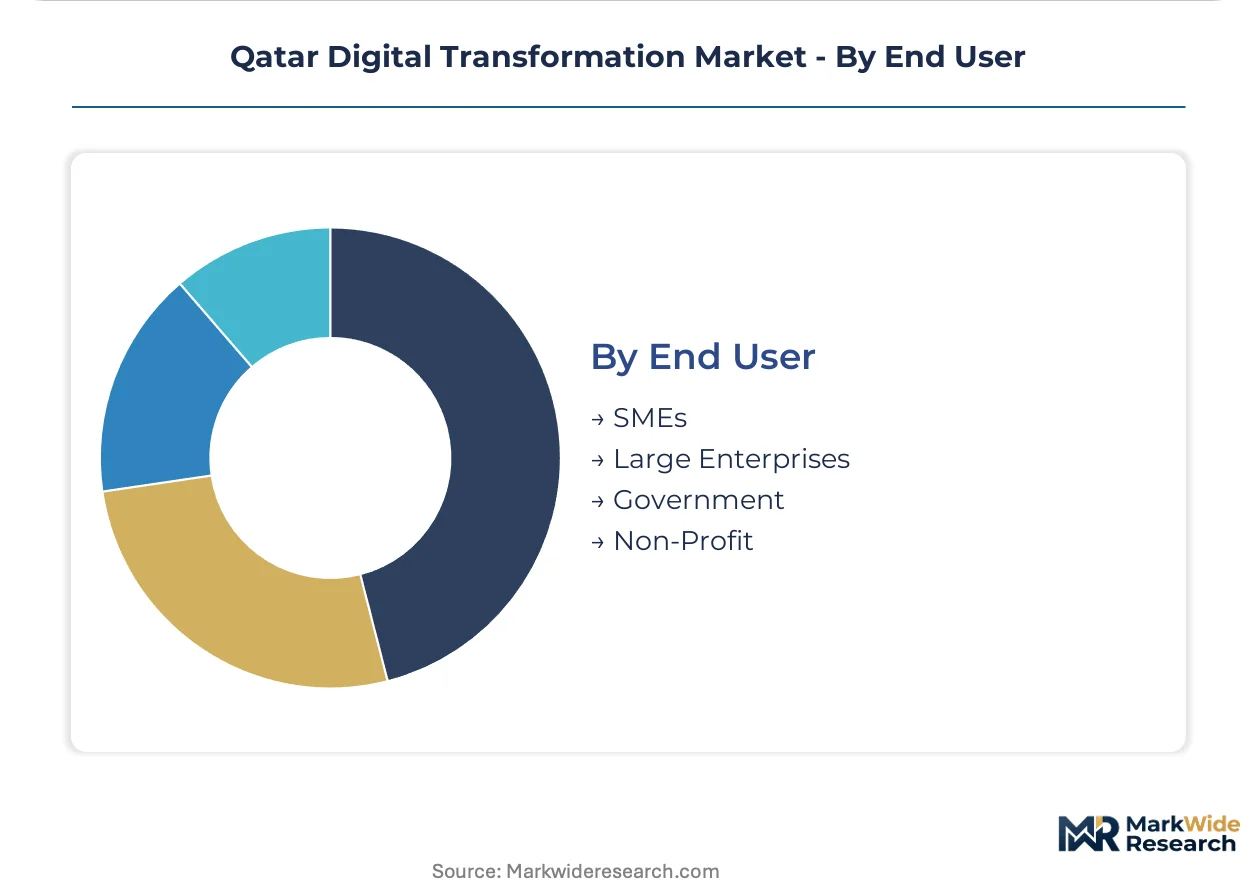
Customer type shapes procurement modality — government entities consolidate around multi-year platform contracts while SMEs favor consumption-based subscriptions.
- Government:Ministry IT departments and state-owned enterprises mandate sovereign cloud certification and domestic infrastructure ownership. Multi-year transformation programs require operational expenditure flexibility.
- Large Enterprises:Qatar Energy and Qatar Airways anchor demand for integrated cloud-AI-connectivity stacks with single-source contracting.
- SMEs:Doha-based professional services and trading firms adopt public cloud scalability without certification burden.
- Non-Profit:Qatar Foundation research initiatives and cultural institutions accessing grant-funded digital infrastructure.
Government accounts represent the largest contract value concentration, with Large Enterprises driving platform standardization across supplier ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's digital transformation market concentrates skilled cloud architects and AI engineers in Doha-based enterprise clusters and Lusail smart city development zones. The Communications Regulatory Authority shapes procurement patterns through sovereign data certification requirements that filter vendor participation. Lusail's integrated command centers and Qatar Energy's hydrocarbon processing facilities anchor demand for compliant infrastructure.
Doha Metropolitan Cluster
Financial institutions and government ministries drive hybrid cloud adoption under Qatar Central Bank data residency mandates. The Communications Regulatory Authority enforces cybersecurity certification that compresses vendor qualification timelines to 8-14 months. West Bay and Lusail development corridors host concentrated Microsoft Azure and IBM Watson deployments for state-backed transformation programs.
Al Wakrah Industrial Zone
Qatar Energy processing facilities and petrochemical operations demand air-gapped operational technology environments resistant to public cloud integration. The Qatar National Vision 2030 framework mandates smart infrastructure protocols across municipal utilities. Ras Laffan industrial complexes anchor private cloud and on-premises deployments where SCADA system isolation remains mandatory.
Education City and Qatar Foundation District
Research universities and healthcare networks pilot AI diagnostic imaging and quantum computing partnerships. Qatar Foundation's technology licensing requirements shape vendor selection for grant-funded digital infrastructure. Hamad Medical Corporation electronic health record modernization concentrates patient data localization investments in this corridor.
Lusail Smart City Development
Integrated command centers and IoT sensor networks across the new city require unified cloud-connectivity-analytics stacks. The Communications Regulatory Authority's open data standards mandate interoperability protocols for municipal and transport authorities. Lusail Marina and Entertainment City districts host edge-to-core computing architectures converging 5G with localized inference engines.
Hamad International Airport Logistics Corridor
Qatar Airways and aviation-linked enterprises anchor demand for real-time operational analytics and predictive maintenance platforms. Customs and border automation systems require sovereign cloud certification for passenger data processing. The corridor's free zone status attracts hybrid cloud providers serving regional headquarters operations.
Qatar Digital Transformation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Qatar's regulated procurement landscape. Platform consolidation favors vendors offering integrated cloud-AI-connectivity stacks that satisfy sovereign compliance in single contracting vehicles. Three archetypes dominate: global hyperscalers with sovereign cloud architectures, regional telecom operators with domestic data center assets, and systems integrators with public sector certification expertise. Competitive moves center on strategic partnerships with Qatar Foundation research initiatives and capacity expansion into Communications Regulatory Authority-certified domestic infrastructure.
Within the global hyperscaler tier, Microsoft Corporation and IBM Corporation exemplify platform-centric positioning through Azure sovereign cloud deployments and Watson-based AI research partnerships. Ooredoo Qatari Public Shareholding Company occupies a distinct position as the domestic connectivity layer provider extending data center capacity to capture hybrid cloud demand from regulated industries. These three anchors represent divergent strategic postures: foreign platform scale, domestic infrastructure control, and integrated service delivery.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Ooredoo Qatari Public Shareholding Company |
| Qatar Computer Services |
| Wipro Limited |
| Accenture plc |
| Cisco Systems, Inc. |
| Amazon Web Services, Inc. |
| Meeza |
| Others |
Pricing and Supply Chain Analysis
Qatari government entities and national oil and gas enterprises concentrate procurement around multi-year platform contracts, locking in subscription-based pricing models that bundle cloud, AI, and connectivity layers. This buyer concentration compresses vendor margins while favoring integrated service providers capable of satisfying Communications Regulatory Authority certification requirements.
Pricing Analysis
Bundled platform subscriptions dominate over unbundled point solutions, with vendors packaging sovereign cloud, AI analytics, and managed services into single contracting vehicles. Price differentiation rests on certification tier—Communications Regulatory Authority sovereign cloud qualification commands premium positioning—and customization depth for operational technology integration. Pricing pressure intensifies as foreign hyperscalers absorb redundant domestic infrastructure investments to meet data localization mandates. SMEs in Doha enterprise clusters exhibit highest price sensitivity, whereas Qatar Energy and defense-linked entities prioritize compliance assurance over cost optimization.
Supply Chain Analysis
Qatar National Vision 2030 domestic content obligations are reshaping vendor sourcing patterns, requiring foreign platform providers to establish local data center ownership and operational control. Hardware supply concentrates in Taiwan, South Korea, and the United States for server infrastructure and specialized AI accelerators. Software licensing draws from Ireland, Singapore, and the United States for enterprise application stacks. Single-source vulnerability persists in sovereign cloud certification pathways, where Communications Regulatory Authority approval queues create vendor onboarding bottlenecks. Distribution runs through Doha-based systems integrators and Ooredoo's domestic connectivity infrastructure to reach regulated end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's digital transformation market functions as a geographic-arbitrage opportunity where vendors with established Middle East sovereign cloud operations capture premium positioning unavailable to providers lacking regional certification infrastructure.
For Market Incumbents: Anticipate margin compression from emerging domestic systems integrators acquiring Communications Regulatory Authority certification capabilities. Prioritize capacity expansion into Qatar-based data center assets to satisfy evolving domestic content obligations for critical infrastructure contracts. Deepen partnership structures with Qatar Foundation research initiatives to anchor quantum computing and AI governance service lines. For New Entrants and Emerging Players: The premium-to-economy pricing gap in hybrid cloud orchestration services opens white-space for mid-tier providers offering seamless workload portability between on-premises and sovereign cloud environments. Target SME clusters in Doha professional services verticals where certification burden remains lighter. Pursue channel partnerships with established domestic connectivity providers to bypass direct certification queues. For Investors and Strategic Acquirers: Regional telecom operators with sovereign cloud assets are the most active acquirer in this space, consolidating domestic infrastructure control through targeted platform acquisitions. Long-term viability hinges on exposure to Qatar National Vision 2030 execution continuity and Lusail smart city deployment milestones. Monitor Communications Regulatory Authority certification timeline compression as the critical inflection signal for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Communications Regulatory Authority approval unlocks public sector procurement pipelines and multi-year platform contracts. |
| Hybrid Cloud Integration | Qatar Central Bank-regulated banks require seamless workload portability between on-premises and cloud-native estates. |
| AI Governance Services | Domestic content obligations for critical infrastructure create demand for compliance consulting and algorithmic audit capabilities. |
| Edge-to-Core Architecture | Lusail smart city sensor networks and Qatar Rail systems converge 5G connectivity with localized inference engines. |
| Quantum Computing Partnership | Qatar Foundation research collaborations anchor differentiated positioning in advanced AI and computational services. |
Research Methodology
Coverage spans Qatar's Doha metropolitan cluster, Lusail smart city development zone, and Al Wakrah industrial corridor, with primary inputs from each. The analysis combines structured interviews with government IT procurement officers, platform engineers at hyperscaler regional headquarters, systems integration specialists, and regulatory affairs leads at Communications Regulatory Authority-certified vendors. Secondary validation draws from Qatar Central Bank circulars on data residency, Communications Regulatory Authority certification databases, Qatar National Vision 2030 framework documents, and sovereign cloud provider capex disclosures. Bottom-up project pipeline analysis triangulates against top-down market sizing across technology layers and deployment models.
Granularity-level modeling spans four dimensions: technology layer (cloud computing, AI, big data, IoT), deployment model (hybrid cloud, private cloud, public cloud, on-premises), industry vertical (BFSI, energy, healthcare, government), and end-user category (government, large enterprise, SME). CAGRs derive from regression analysis against Qatar National Vision 2030 capital allocation trajectories and Lusail infrastructure buildout schedules. Forecast inputs include Communications Regulatory Authority certification queue projections, Qatar Energy operational technology modernization timelines, and Qatar Central Bank core banking migration pacing.
Caveats apply where Communications Regulatory Authority sovereign data mandate enforcement intensity, Qatar National Vision 2030 budget reallocation, or hydrocarbon sector capital expenditure volatility could materially shift the outlook. Forecasts reflect assumptions regarding certification timeline normalization and domestic talent pool development velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Italy Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market